Key Takeaways
- Walmart shares rose 2.1% after it committed about $6 billion over several years to expand Symbotic automation across 25 U.S. regional distribution centers.
- The bet targets cost to serve as global e-commerce grew 23% last quarter and advertising grew 38%.
- At 40x forward earnings, with third-quarter operating income guided up just 2% to 4%, the stock leaves little room for a stumble.
- Walmart reports third-quarter results on November 19, and investors will watch e-commerce profitability and any update on capex plans.
More robots. That’s Walmart’s answer to rising fulfillment costs.
Walmart (WMT) shares rose 2.1% to $121 on Thursday after the retailer committed about $6 billion over several years to expand its automation deal with Symbotic (SYM). The two companies have worked together since 2017.
The stock has now returned about 19% over the past year. It still sits roughly 10% below its 52-week high of $135.
The timing is interesting. Rival Amazon (AMZN) is spending far more on a different kind of buildout, and its cash flow is paying for it.
More robots in more buildings
The expanded deal covers 25 U.S. regional distribution centers. Here’s what Walmart is buying:
- About $6 billion in commitments over several years
- Symbotic’s BreakPack each-picking and SymMicro micro-fulfillment systems
- $125 million for racking research
Symbotic was already deploying across all 42 of Walmart’s regional distribution centers as of early 2025. It also bought Walmart’s robotics unit that year, adding automation for store pickup and delivery.
More than 60% of Walmart stores already get shipments from automated distribution centers. About half of e-commerce fulfillment center volume was automated in fiscal 2026.
Capital spending has been rising alongside that push…

Spread over several years, $6 billion is a modest slice of Walmart’s annual capital budget. The payoff Walmart wants is faster replenishment and a lower cost to serve.
Cheaper fulfillment funds the growth
Online is where that cost matters most. Global e-commerce sales grew 23% last quarter and now make up 24% of net sales. Store-fulfilled delivery grew 40%, and marketplace sales rose more than 50%.
The higher-margin businesses are growing even faster. Advertising rose 38%, while membership and other income grew 17%.
Second-quarter revenue climbed 5.9% to $187.9 billion, and adjusted EPS of $0.81 beat the $0.74 estimate. Walmart then raised its fiscal 2027 outlook to 4% to 5% sales growth and adjusted EPS of $2.80 to $2.87.
Compare the cash each retailer keeps after capex…
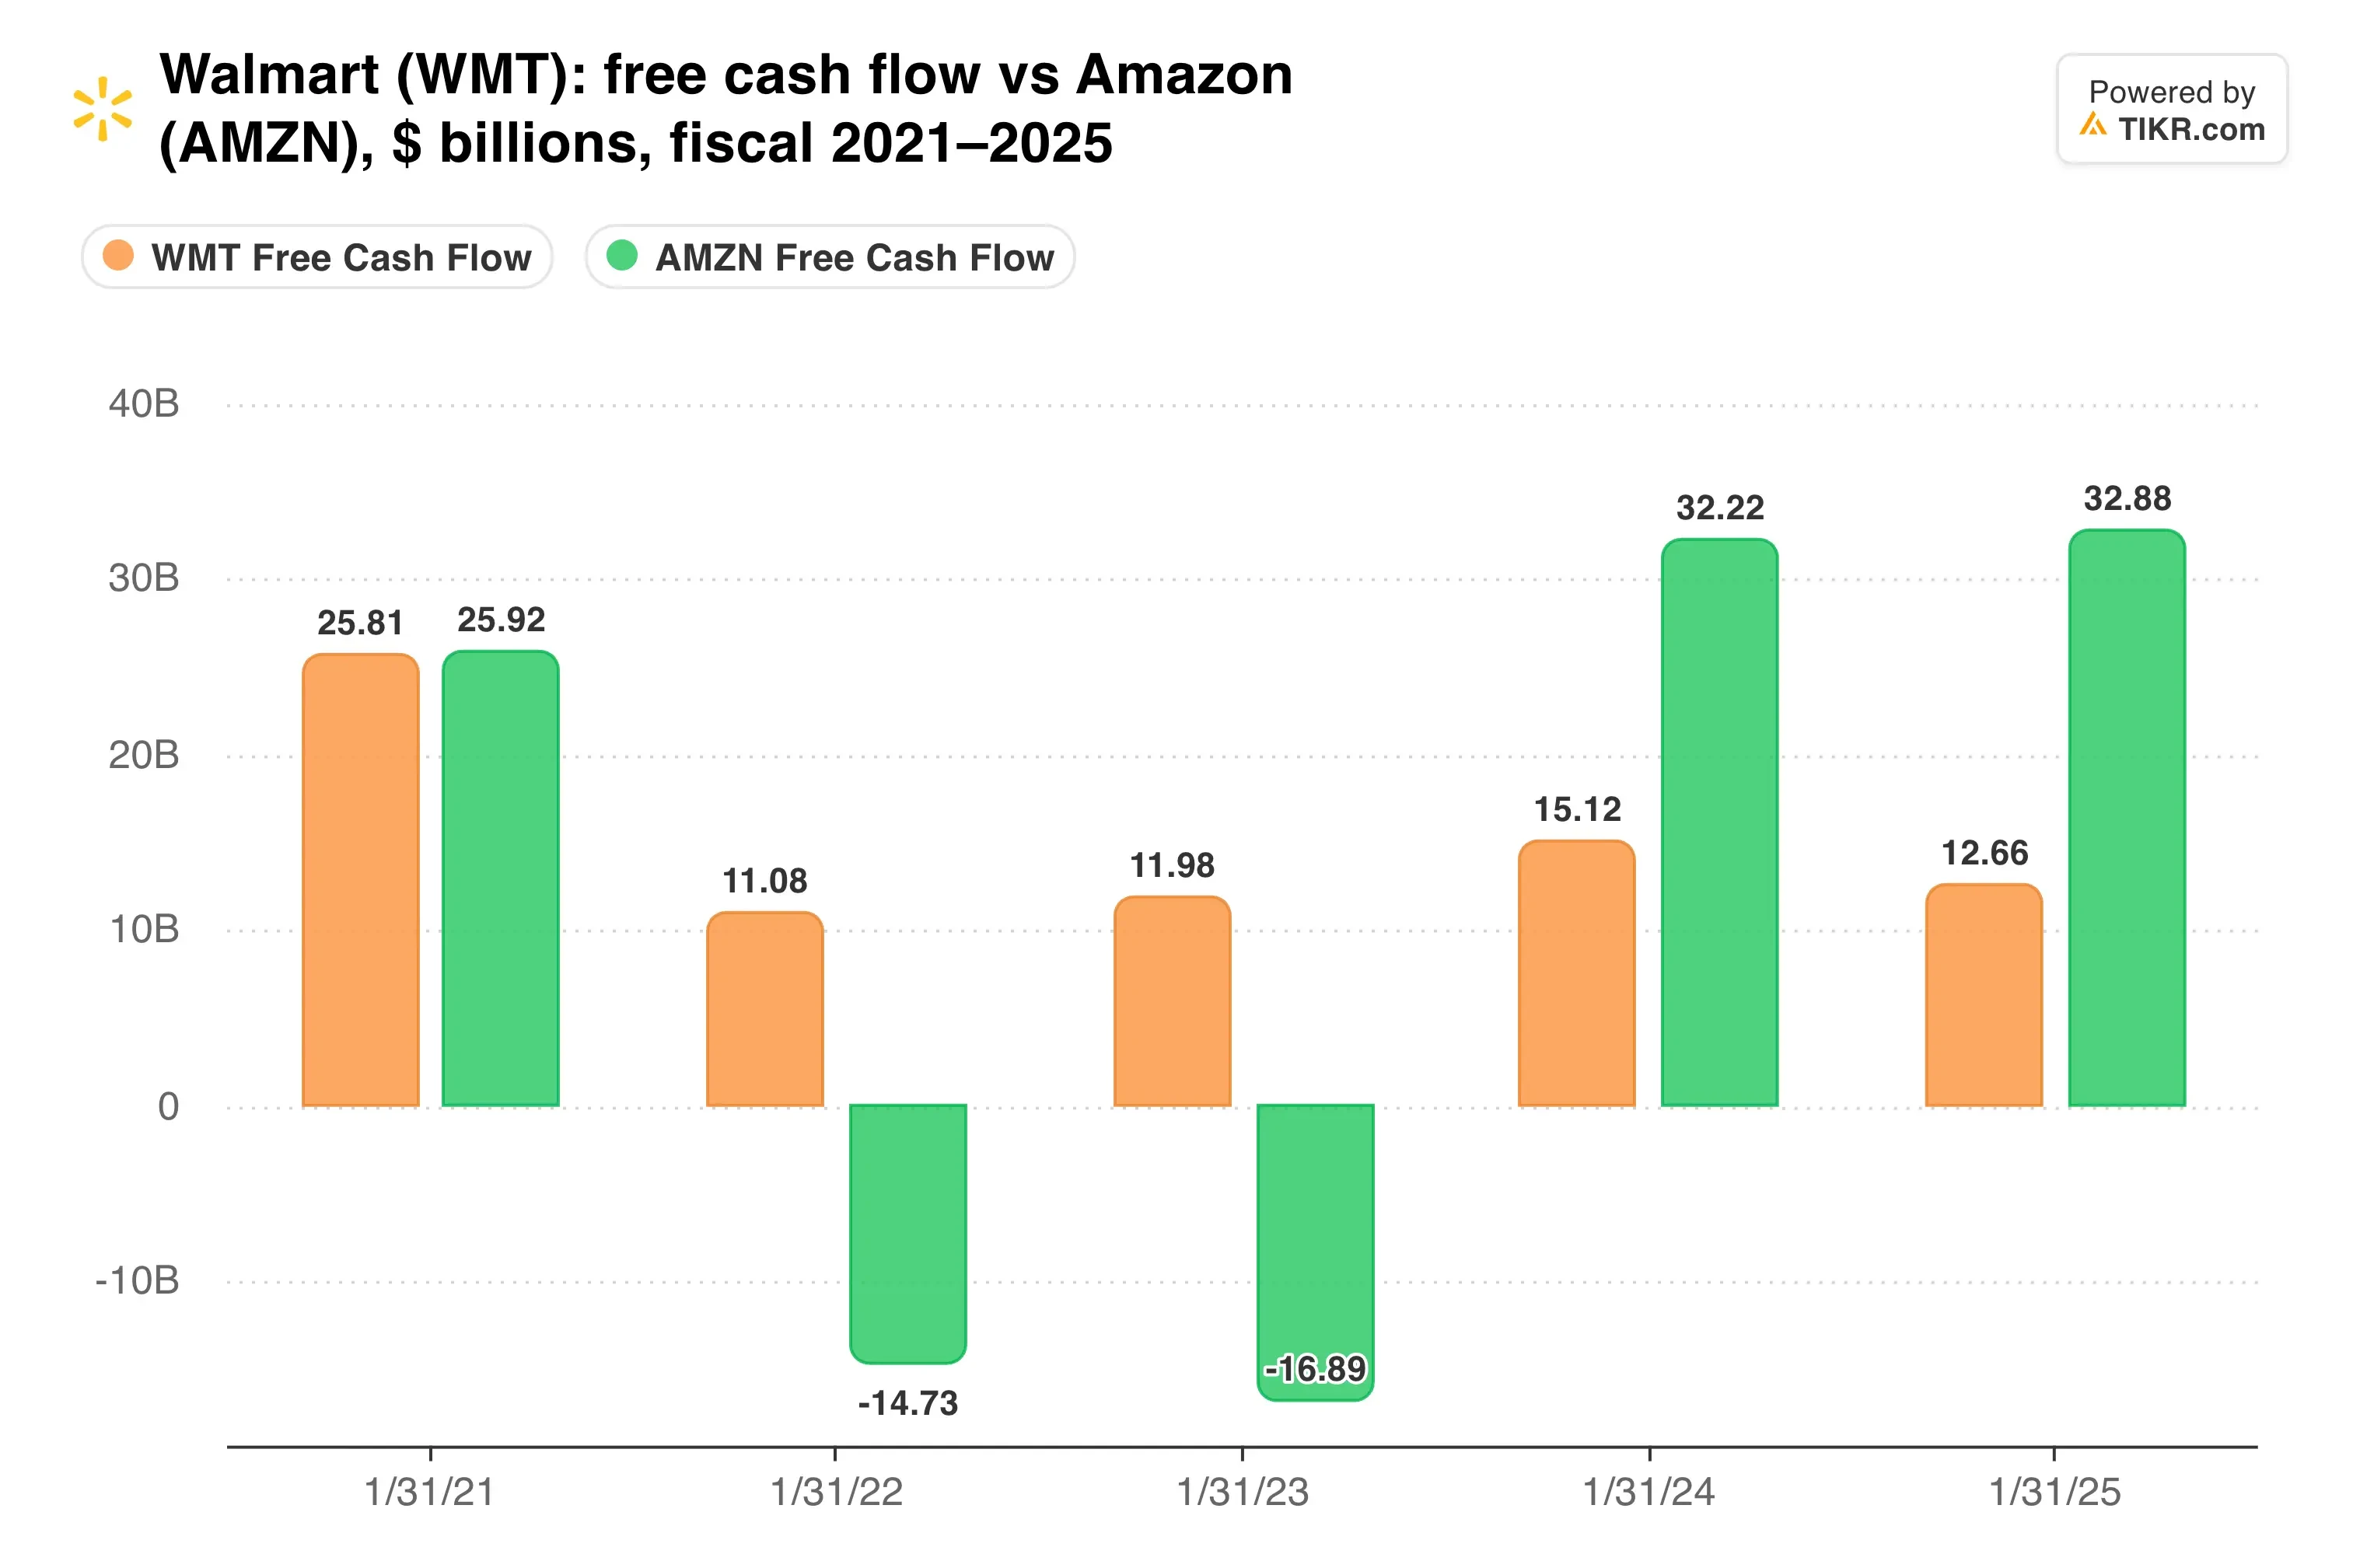
Amazon expects about $220 billion of capex this year, and its trailing free cash flow had already swung to an outflow of $7.6 billion by June. Walmart is funding its automation while keeping free cash flow positive.
TIKR tracks 44 analysts on Walmart. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Walmart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Walmart’s Analyst Ratings
The multiple leaves no slack
Here’s the uncomfortable part. Walmart trades at 40x forward earnings, and the average price target of $127 sits just 5% above Thursday’s close.
The near-term guide is modest. Walmart expects third-quarter adjusted operating income to grow only 2% to 4%, with adjusted EPS of $0.62 to $0.64. Its 28.8% second-quarter operating income jump also included a 750 basis point boost from tariff refunds.
Here’s how that premium has built up:

The stock now trades at a far richer multiple than it did five years ago.
Other pressures are building. Walmart de México reported tighter margins this week as costs outpaced sales growth, and the FTC demanded data from Walmart on personalized pricing.
My take: Automation is Walmart’s best tool for protecting margins as e-commerce grows, and this deal extends a partnership that already works. But at 40x earnings, the stock is priced for flawless execution. I’d hold it and wait for a better price before adding.
The next checkpoint is November 19, when Walmart reports third-quarter results. Watch e-commerce profitability and whether management updates its capex plans.
So what is Walmart stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Walmart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!