


Cleveland-Cliffs (CLF) shares are up about 18% this afternoon (trading at about $14) after the steelmaker posted its strongest quarter in three years and said 2027 adjusted EBITDA should top $4 billion.
That outlook is the real news. It sits about 57% above what Wall Street expects for 2027, and the stock still trades at a discount to its peers.
What Cleveland-Cliffs Reported
- Adjusted EBITDA of $612 million, above the $575 million it guided to in July and up from $143 million a year earlier.
- Adjusted EPS of $0.28 against a $0.24 consensus (revenue of $5.6 billion missed estimates).
- Q4 adjusted EBITDA guidance of about $715 million.
- A “major debt reduction” planned for Q4, funded by free cash flow and property sales.
The $4 Billion Gap
Analysts expect about $2.55 billion of EBITDA in 2027. Management says contracts it has already signed and prevailing index-price forecasts support more than $4 billion of adjusted EBITDA, more than double this year’s $1.64 billion consensus.

If the contracts and the price forecasts both hold, the Street’s 2027 numbers are at least $1.45 billion too low.
Still the Cheap One
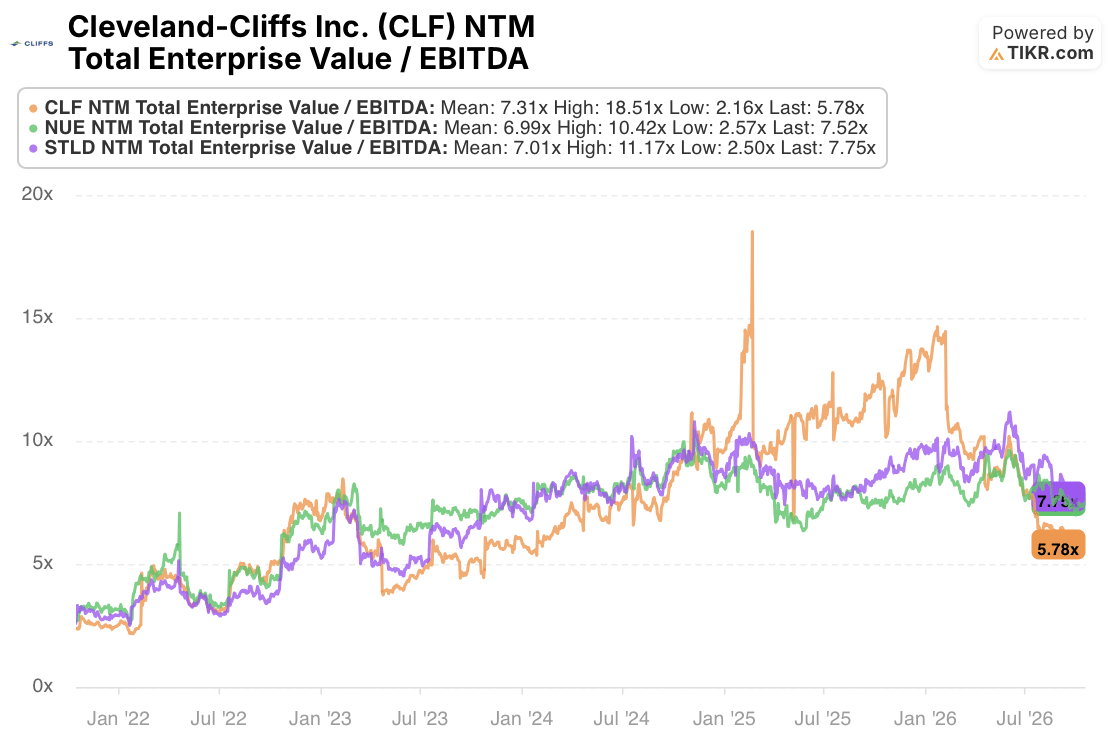
Cliffs trades at 5.78x forward EV/EBITDA, below its five-year average of 7.31x. Nucor (NUE) sits at 7.52x and Steel Dynamics (STLD) at 7.75x, and both rose only 1% to 2% in Monday morning trading. On management’s $4 billion, Cliffs’ enterprise value of roughly $15.7 billion works out to under 4x.
What Cliffs Still Has to Prove

The mean analyst target was $12.50 going into Monday, now about 13% below the share price. Ratings lean cautious: 2 buys, 10 holds and 1 underperform.
There’s a reason. Q3 operating cash flow was $224 million, only 37% of adjusted EBITDA, and long-term debt has climbed to $7.65 billion this year. The cheap multiple rests on management being right about 2027. Q4 free cash flow is the number to watch: the planned debt cut also leans on property sales, so a smaller debt balance alone won’t prove this EBITDA is turning into cash.
Want to see how the gap between Cliffs and its peers moves from here? Pull up the same forward EV/EBITDA comparison and the Street’s 2027 estimates for any steelmaker on TIKR, free. Learn more here.
So what is Cleveland-Cliffs stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CLF stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Cleveland-Cliffs Inc. for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


