


Key Takeaways
- Cleveland-Cliffs shares surged after Q3 adjusted EBITDA reached $612 million, beating management’s $575 million guidance.
- Management expects 2027 adjusted EBITDA to exceed $4 billion, more than double its approximately $1.7 billion implied for 2026.
- TIKR estimates show roughly $3 billion in 2027 EBITDA, illustrating the size of management’s ambitions, although the measures differ.
- Elevated debt and steel-price volatility remain major risks, making fourth-quarter cash generation a crucial test.
What Happened?
Cleveland-Cliffs (NYSE: CLF) shares rallied on October 19 after the steelmaker reported its strongest quarterly performance in three years and outlined an ambitious profitability outlook.
According to the company’s Q3 earnings release, adjusted EBITDA reached $612 million, exceeding its $575 million guidance and more than doubling Q2’s $286 million.
Adjusted EPS reached $0.28, while average selling prices rose to $1,177 per net ton from $1,032 a year earlier.
CEO Lourenco Goncalves called it the company’s “strongest quarter in three years.”
Management also guided for approximately $715 million in fourth-quarter adjusted EBITDA, indicating further expected profitability improvements.
Can Cleveland-Cliffs Deliver $4 Billion in 2027 EBITDA?
Management expects adjusted EBITDA to exceed $4 billion in 2027, supported by newly signed customer contracts and prevailing steel-price forecasts.
Adding $993 million in adjusted EBITDA generated during the first nine months of 2026 to its $715 million Q4 guidance implies approximately $1.7 billion for the year.
The 2027 outlook therefore represents more than twice the implied 2026 level.
According to TIKR estimates, Cleveland-Cliffs is projected to generate approximately $3 billion in EBITDA in 2027, with EBITDA margins expected to reach around 13%.

TIKR’s EBITDA estimates are not necessarily calculated the same way as management’s adjusted EBITDA outlook, so the figures should not be treated as directly equivalent.
Earlier this month, Wells Fargo upgraded CLF to Overweight, with a $2.65 billion 2027 EBITDA forecast.
For industry context, Steel Dynamics reported $921 million in adjusted EBITDA during Q2 2026, though its results cover a different reporting quarter.
Why Debt Reduction Matters for CLF Stock
Cleveland-Cliffs’ balance sheet remains a significant risk.
According to TIKR data, Cleveland-Cliffs’ net debt-to-EBITDA ratio increased from approximately 1.6x in 2023 to nearly 81x in 2025, primarily reflecting exceptionally weak EBITDA. This historical measure may differ from the adjusted leverage calculation underlying management’s target of below 2.5x by mid-2027.
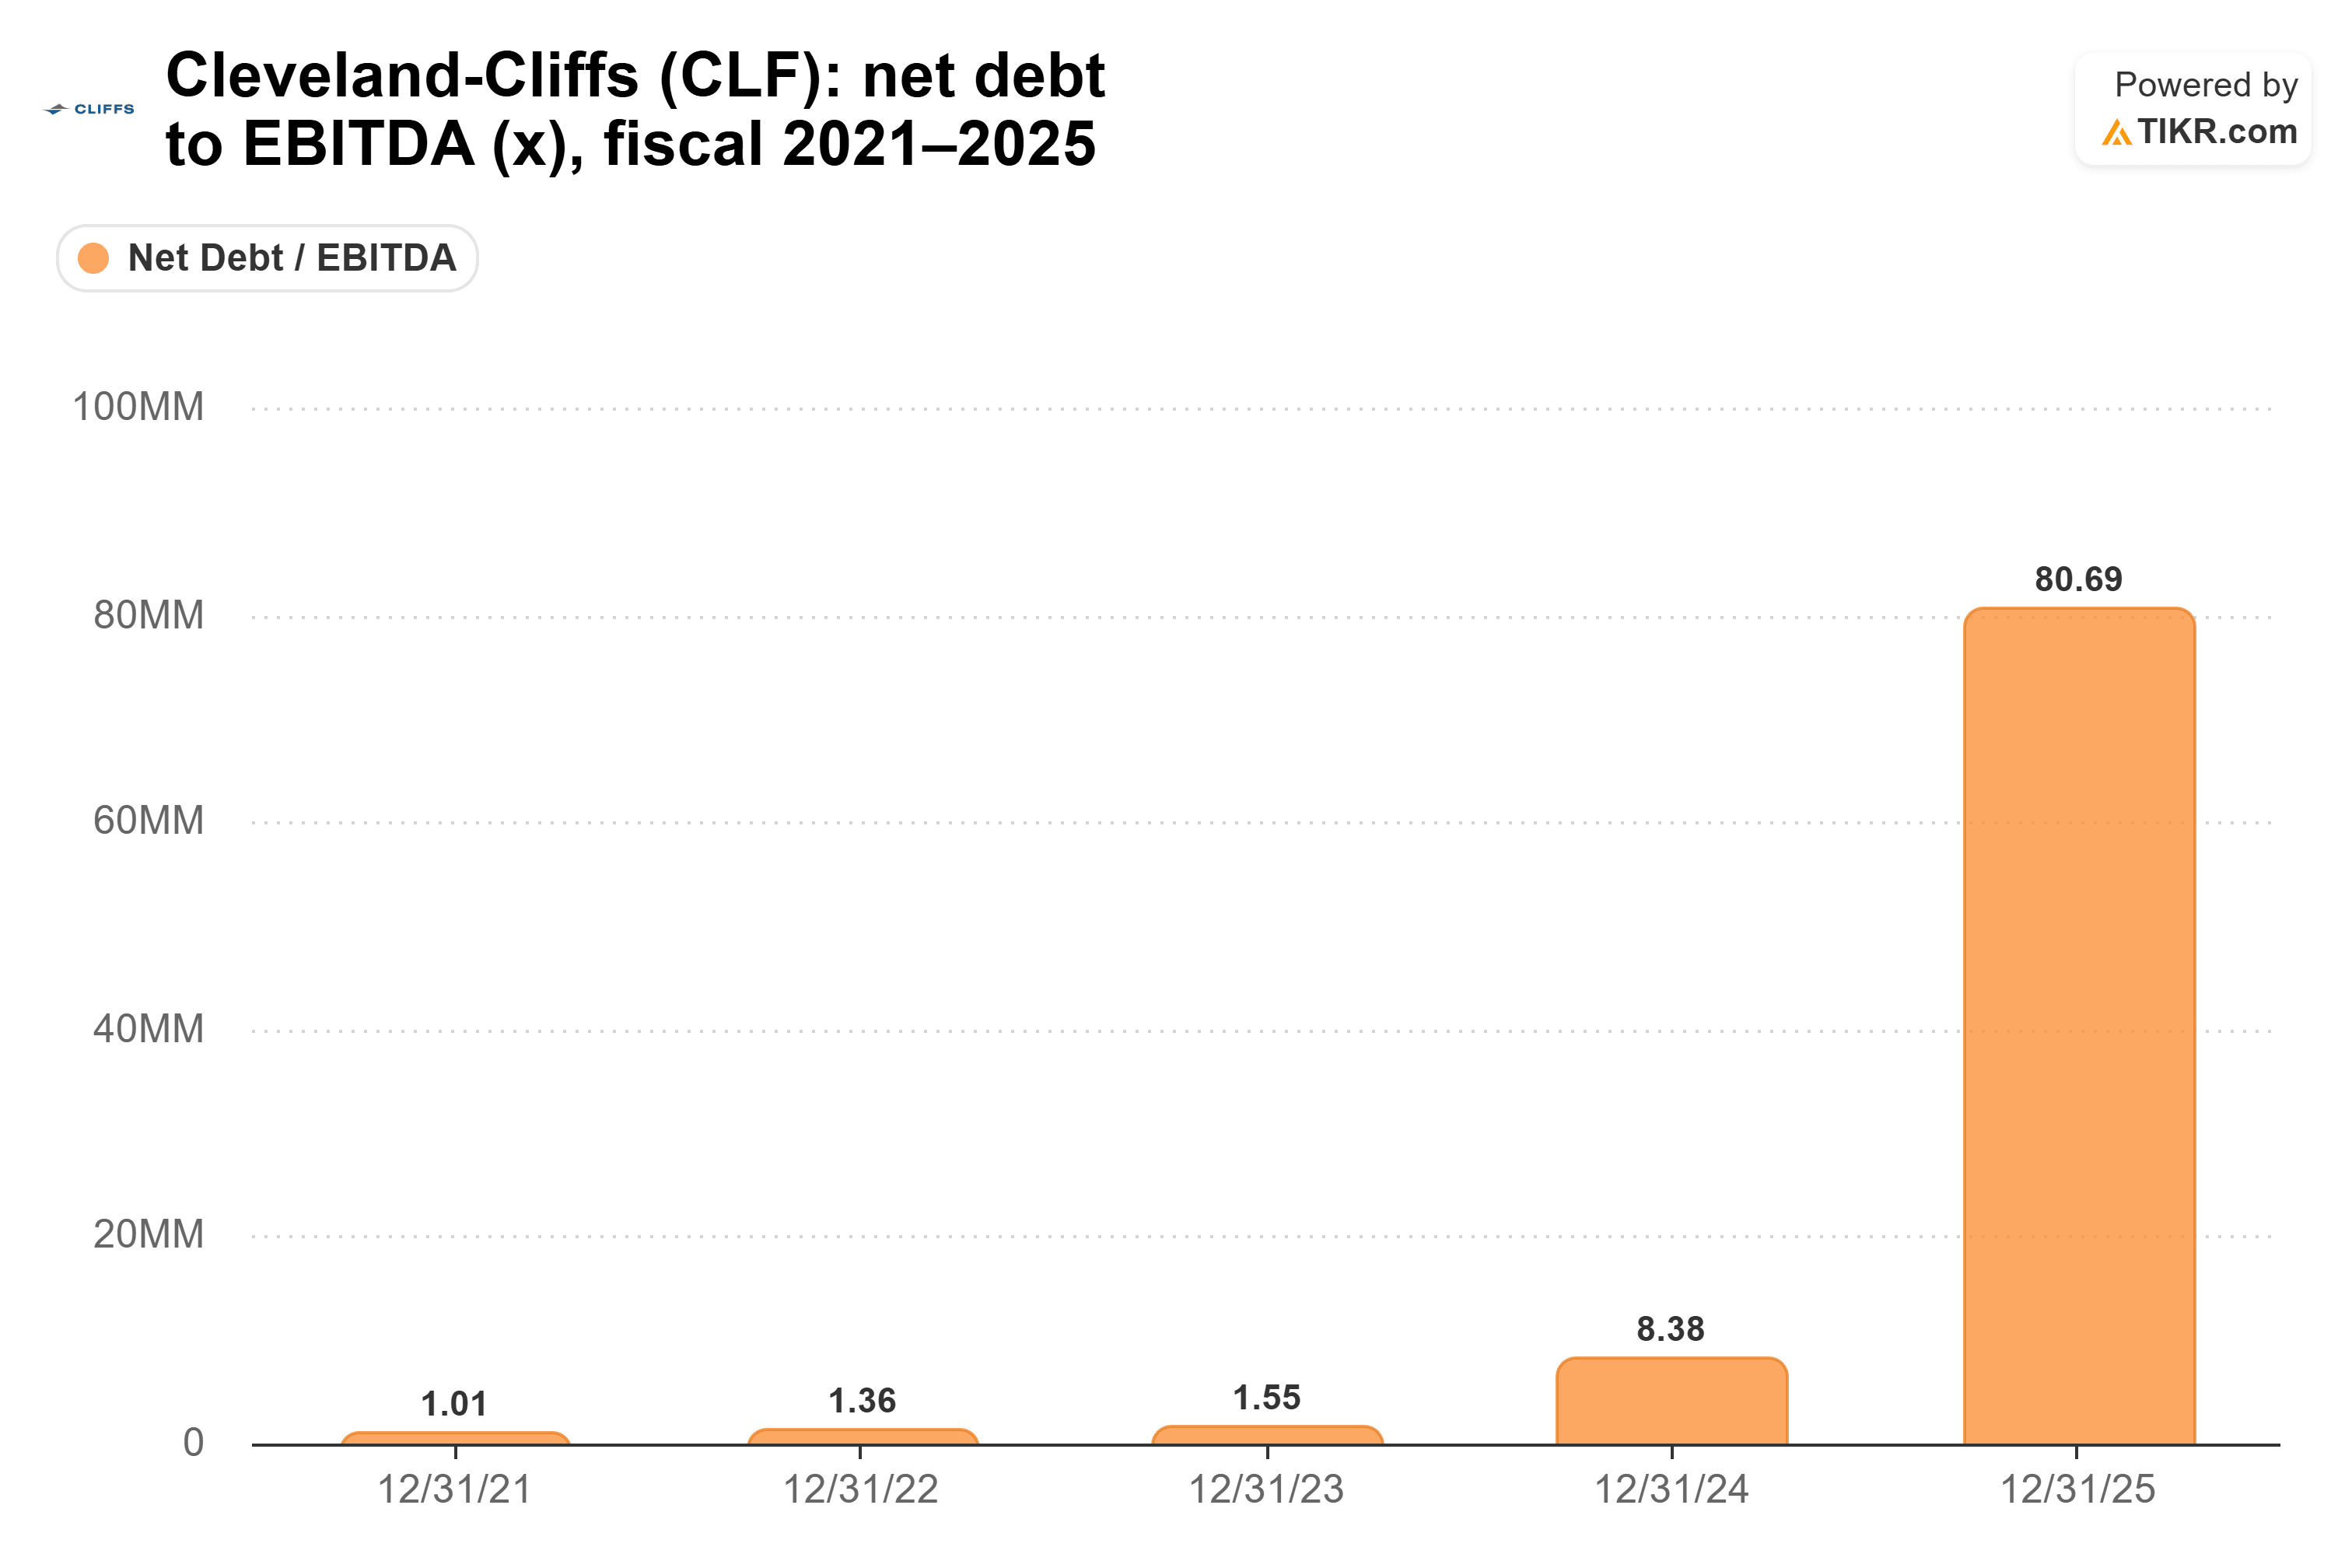
Management expects a major debt reduction in Q4 and targets leverage below 2.5x by mid-2027.
With approximately $7.6 billion in net debt at September’s end, stronger cash generation will be critical. The company also plans to indefinitely idle Stelco’s galvanizing lines amid Canadian market oversupply.
What Does CLF Stock’s Valuation Tell Investors?
Cleveland-Cliffs traded at approximately 9.2x forward earnings at the October 16 close, before its earnings-driven rally.
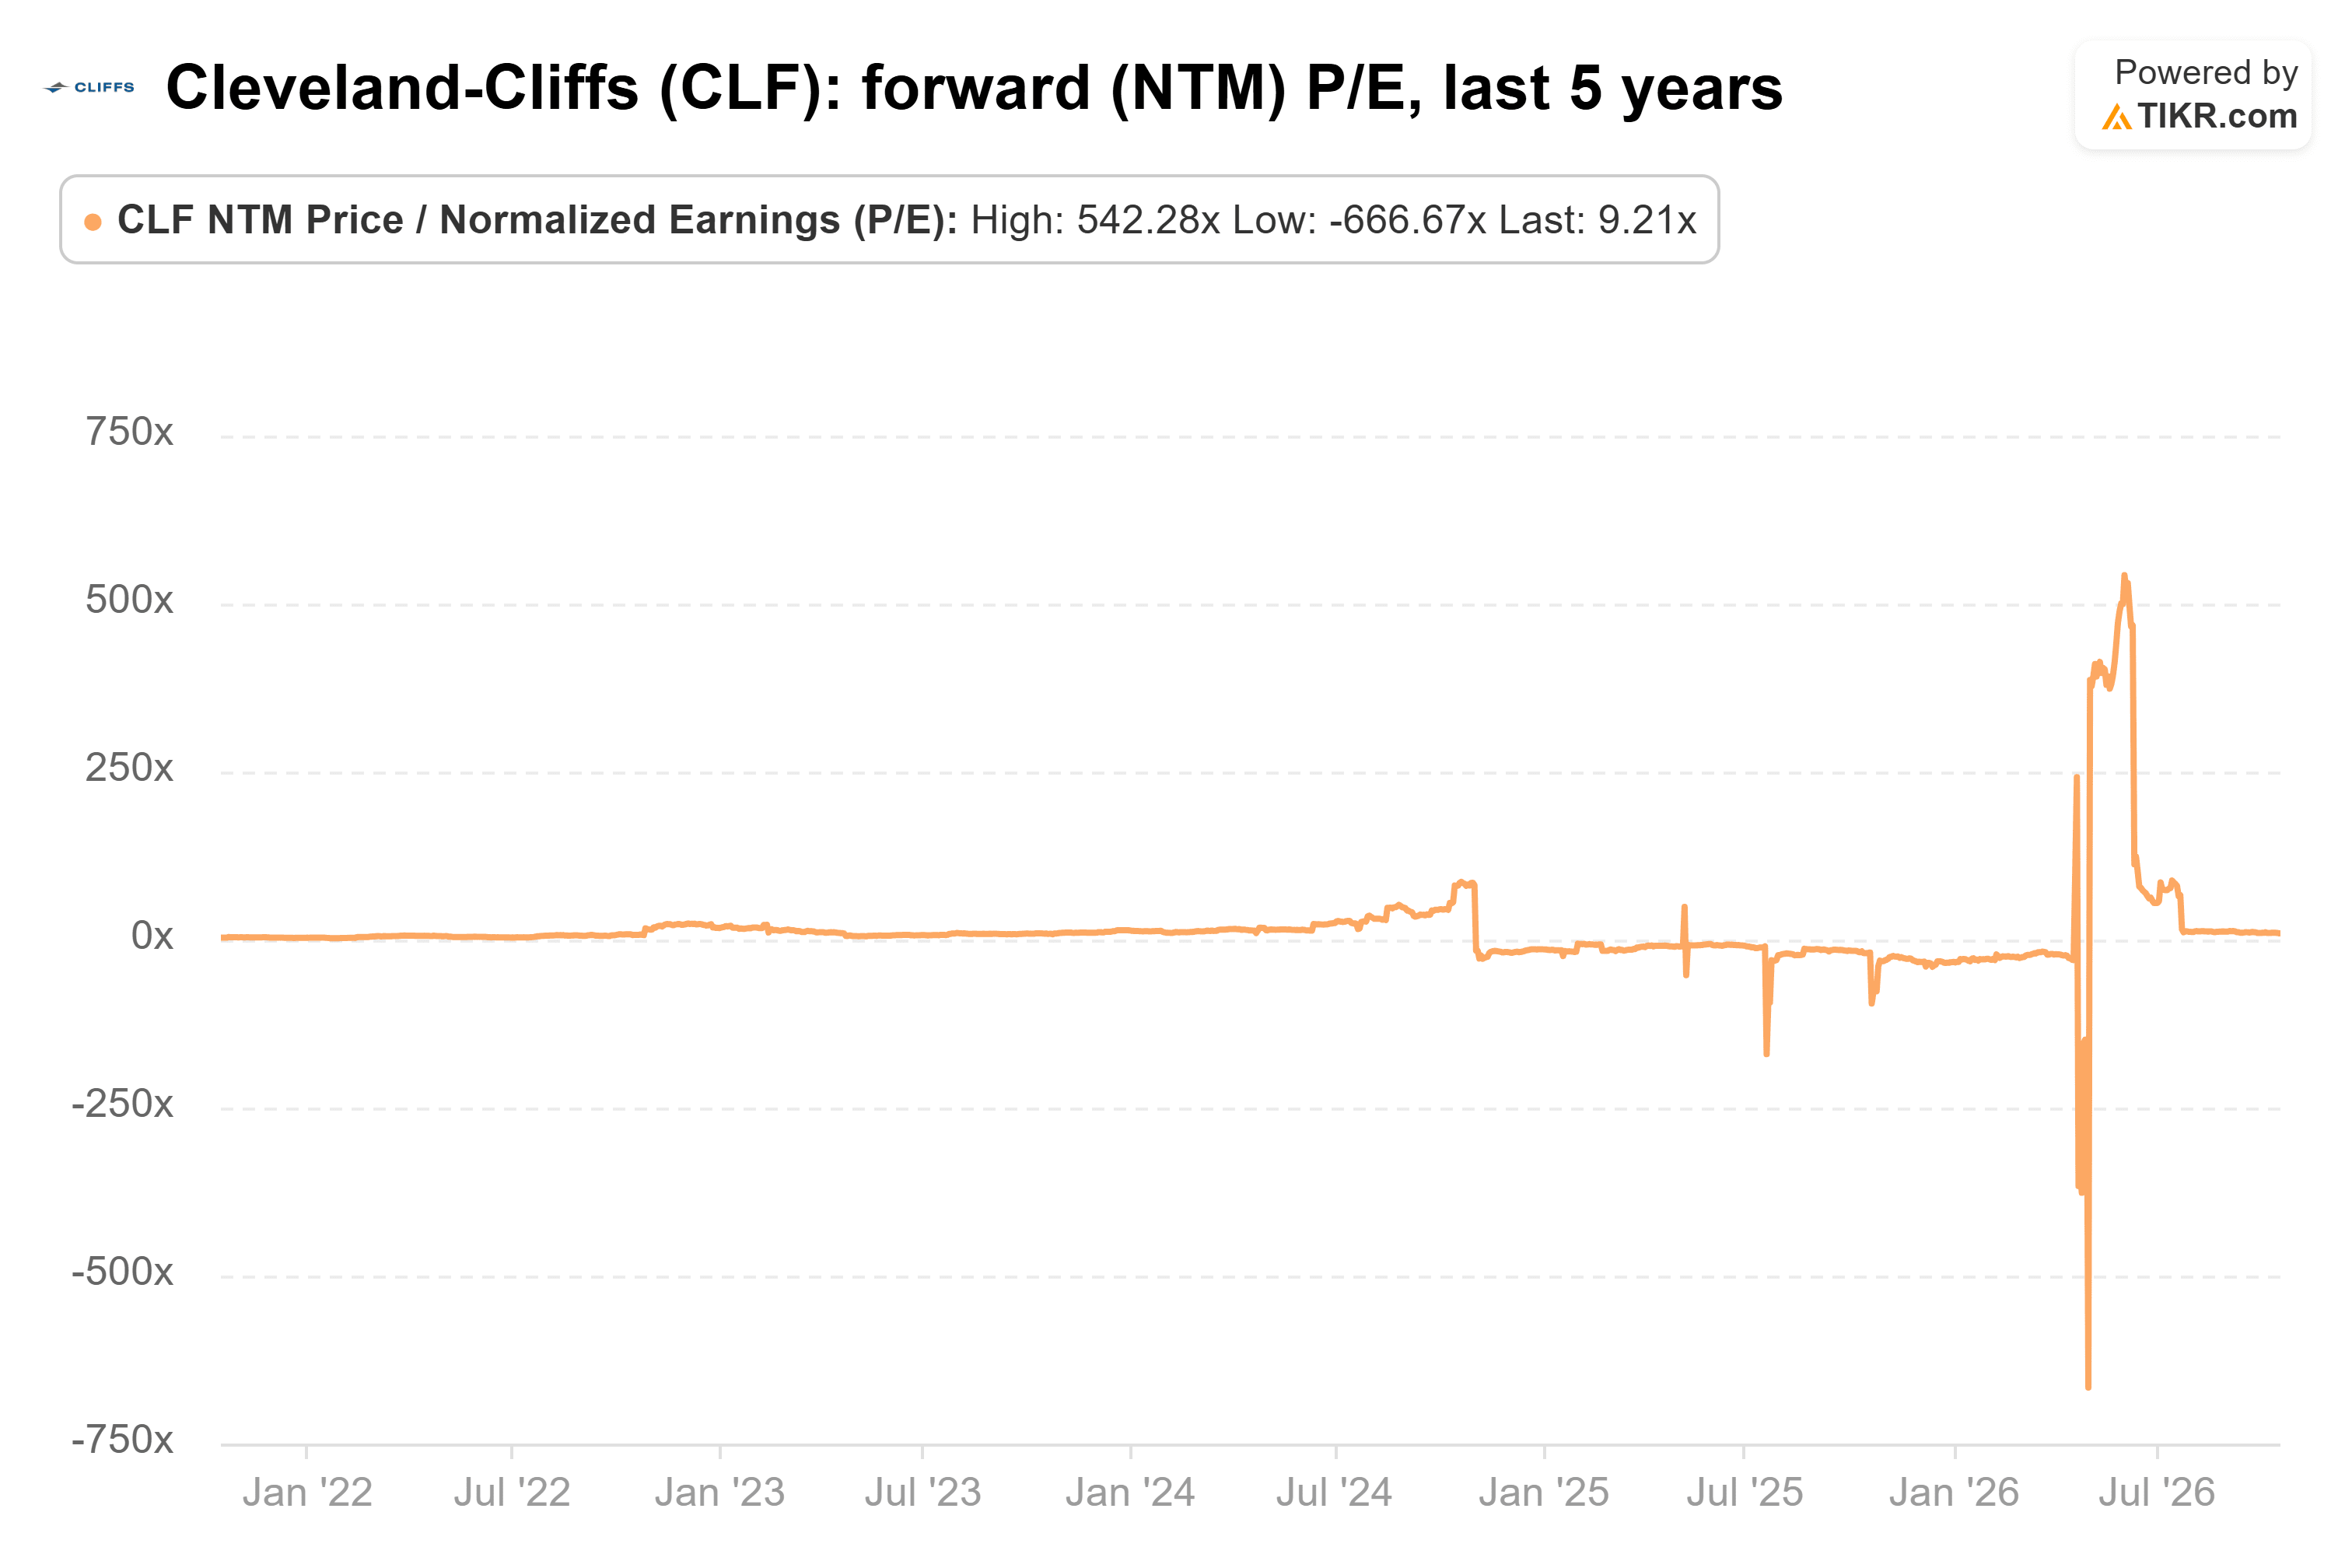
However, the chart shows extreme positive and negative valuation multiples when earnings expectations approach or fall below zero, making its historical average an unreliable benchmark for determining fair value.
Cleveland-Cliffs’ rally appears justified by stronger quarterly earnings and improving guidance, but its $4 billion 2027 adjusted EBITDA outlook does not automatically make the stock undervalued.
Management’s ambitious 2027 outlook depends on favorable steel prices, customer contracts, and continued operational improvement.
CLF looks more compelling as an earnings-recovery opportunity than as a clearly undervalued stock. Investors should watch whether fourth-quarter adjusted EBITDA approaches $715 million and whether management delivers meaningful debt reduction.
If both targets are achieved, the bullish case would strengthen. However, weaker steel prices or disappointing debt reduction could make it difficult for the stock to sustain its rally.
So what is Cleveland-Cliffs stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cleveland-Cliffs could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Cleveland-Cliffs for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


