Key Takeaways
- AT&T plans to keep its dividend at $1.11 a share a year while it speeds up buybacks to about $10 billion in 2026.
- Altria yields 6.5% to AT&T’s 4.6%, and its dividend per share grew 4% a year from fiscal 2020 to fiscal 2025.
- AT&T’s dividend took 45% of its free cash flow over the twelve months to June 2026, against 78% at Altria.
- Altria carries less than half AT&T’s leverage, and AT&T expects its leverage to rise after its EchoStar deal closes.
If you own AT&T (T) for the dividend, don’t wait on a raise. With its second-quarter results on July 22, AT&T said it plans to keep its dividend at $1.11 a share a year while it speeds up share repurchases to about $10 billion in 2026.
Altria Group (MO), which reported on July 30, has kept raising instead. Its dividend per share grew 4.1% a year from fiscal 2020 to fiscal 2025, and it yields 6.5% to AT&T’s 4.6%.
So which is the better dividend stock?
| Metric | AT&T (T) | Altria Group (MO) |
|---|---|---|
| Dividend yield | 4.6% | 6.5% |
| Current annual dividend | $1.11 | $4.44 |
| Dividend growth, fiscal 2020–2025 | -11.8% a year | 4.1% a year |
| Cash dividend payout ratio (TTM to June 30, 2026) | 45% | 78% |
| Net debt/EBITDA (LTM) | 2.91x | 1.41x |
| Interest coverage (LTM) | 3.86x | 13.27x |
| Forward P/E (NTM) | 10.1x | 11.9x |
AT&T has room to spare, and it’s buying back stock
AT&T’s Advanced Connectivity service revenue, from fiber and wireless, rose 5.1% from a year earlier to $23.5 billion in the second quarter of 2026.
That growth leaves the dividend well-covered, at 45% of free cash flow over the twelve months to June 30, 2026. Dividends paid fell from $15.1 billion in fiscal 2021 to $8.14 billion in fiscal 2023, and free cash flow has run more than twice that every year since.

So where does the spare cash go? On the second-quarter call, management put it plainly: “Together, our planned share repurchases and expected dividend payments will total approximately $18 billion this year, which is essentially 100% of our outlook for free cash flow.”
Debt is the main risk. TIKR puts AT&T’s net debt at 2.91x EBITDA over the last twelve months. The company expects its own leverage measure to rise after its EchoStar deal closes, then return to its 2.5x target range within about three years.
Altria spends most of its cash on the dividend
Where AT&T keeps a wide cushion, Altria runs much closer to the line. Its domestic cigarette shipment volumes are falling, while on! PLUS nicotine pouches, expanded to 120,000 stores, are doing the growing. Even so, adjusted diluted EPS rose 4.9% to $2.80 in the first half of 2026 from a year earlier, and Altria guides to $5.61 to $5.72 for 2026.
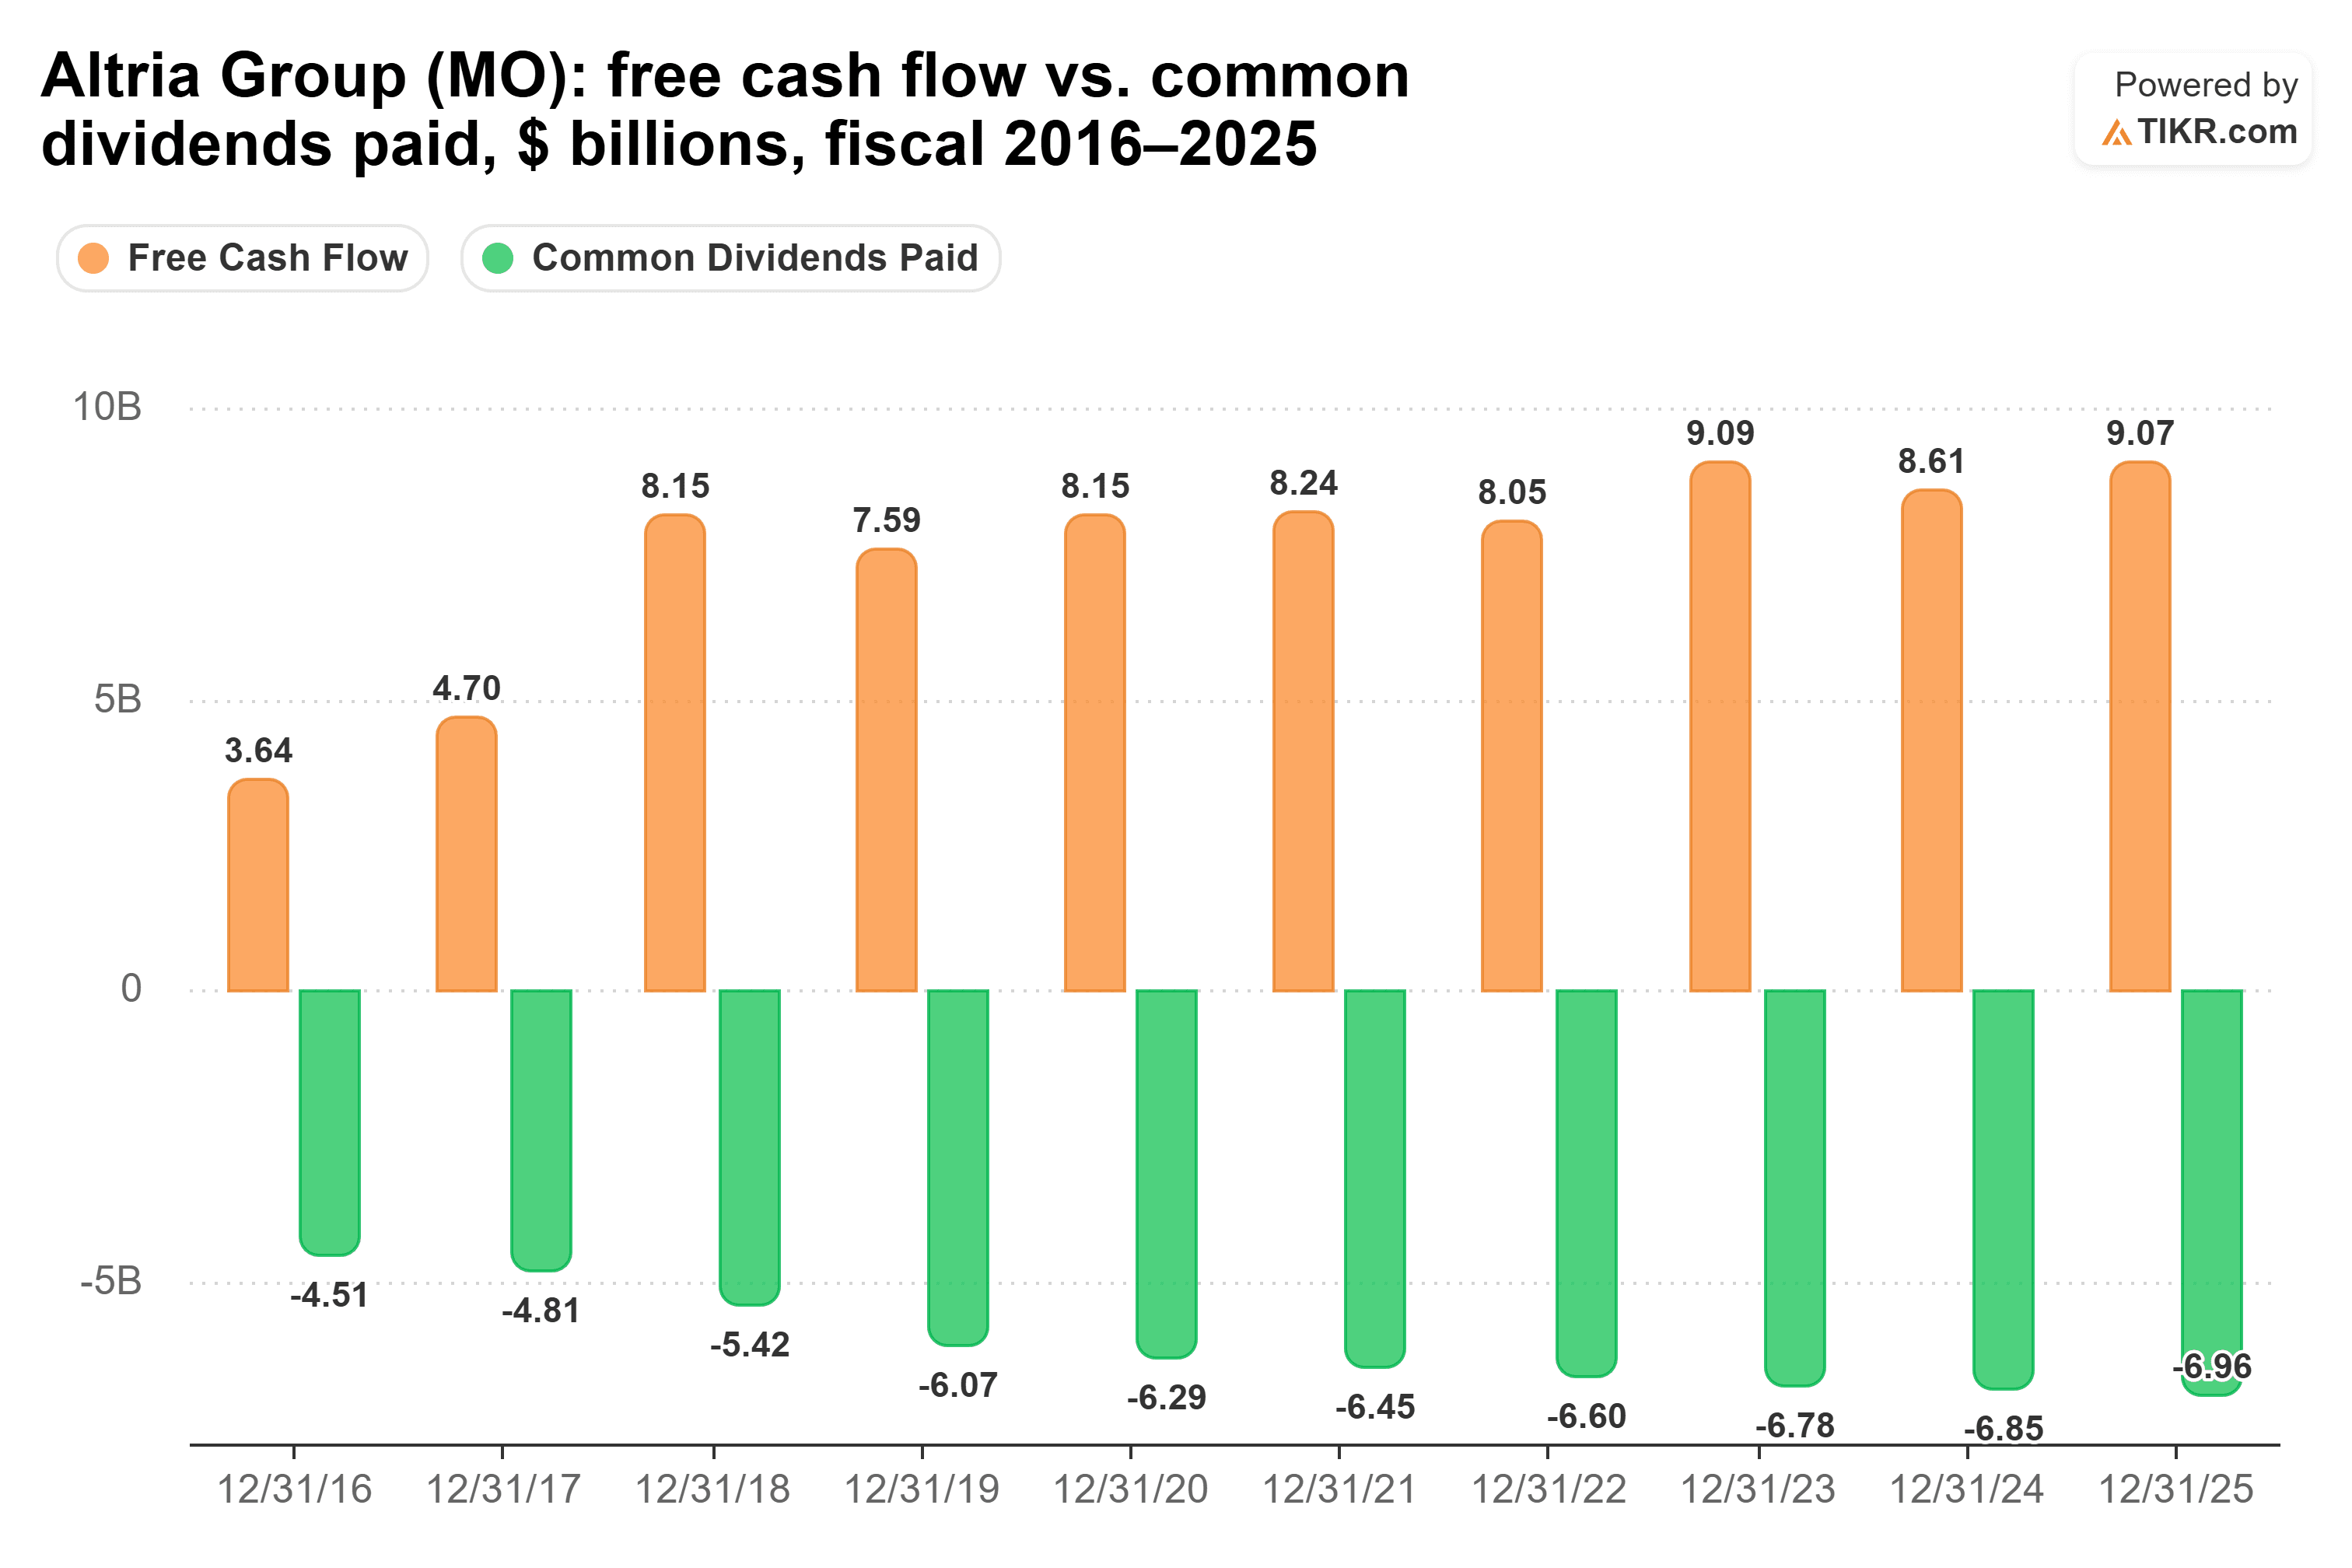
Its dividend took 78% of free cash flow over the twelve months to June 30, 2026. That’s high, but steady: the ratio stayed between 74.6% and 82.0% every fiscal year from 2021 to 2025. Free cash flow climbed from $3.64 billion in fiscal 2016 to $9.07 billion in fiscal 2025, and it has topped dividends paid every year since fiscal 2018.
Management puts the dividend first, as it said on the second-quarter call: “Historically, after we have the dividend, we have about $1 billion excess in cash, and we look at capital-efficient ways to deploy that capital.”
The core business is the risk: a 78% payout leaves less cushion if cigarette earnings slip.
So which dividend wins?
For me, Altria is the better dividend stock: it pays you more today and keeps raising the check.
Take each dividend at its pace now. Altria’s rose 4.0% in fiscal 2025, and AT&T’s didn’t rise. At those rates, $10,000 invested today pays about $925 in year 10 from Altria, against about $460 from AT&T. (AT&T’s 5-year rate of -11.8% a year comes from its dividend cut, so it says little about the dividend now.)
Altria’s 78% payout is the tighter one. But it has held in a narrow band for five fiscal years, and Altria carries less than half AT&T’s leverage.
This isn’t to say AT&T’s dividend is in trouble. Its fiber and wireless revenue is growing, and the dividend takes less than half its free cash flow. It’s just that, by its own plan, the spare cash goes to buybacks. Altria’s check is bigger, growing, and backed by a stronger balance sheet.
Of course, Altria’s raises rest on its earnings holding up as cigarette volumes fall. Its full-year results against that $5.61 to $5.72 guidance are the number to watch.
So what is Altria stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Altria could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!