[IMAGE CREDIT: Engin Akyurt from Pexels via Canva]
Key Takeaways
- Cintas shares fell 5% today and UniFirst shares fell 10% after a report that the FTC plans to sue to block Cintas’s $5.5 billion purchase of UniFirst.
- If the deal dies, Cintas loses about $375 million of planned cost savings, but its own business doesn’t depend on them.
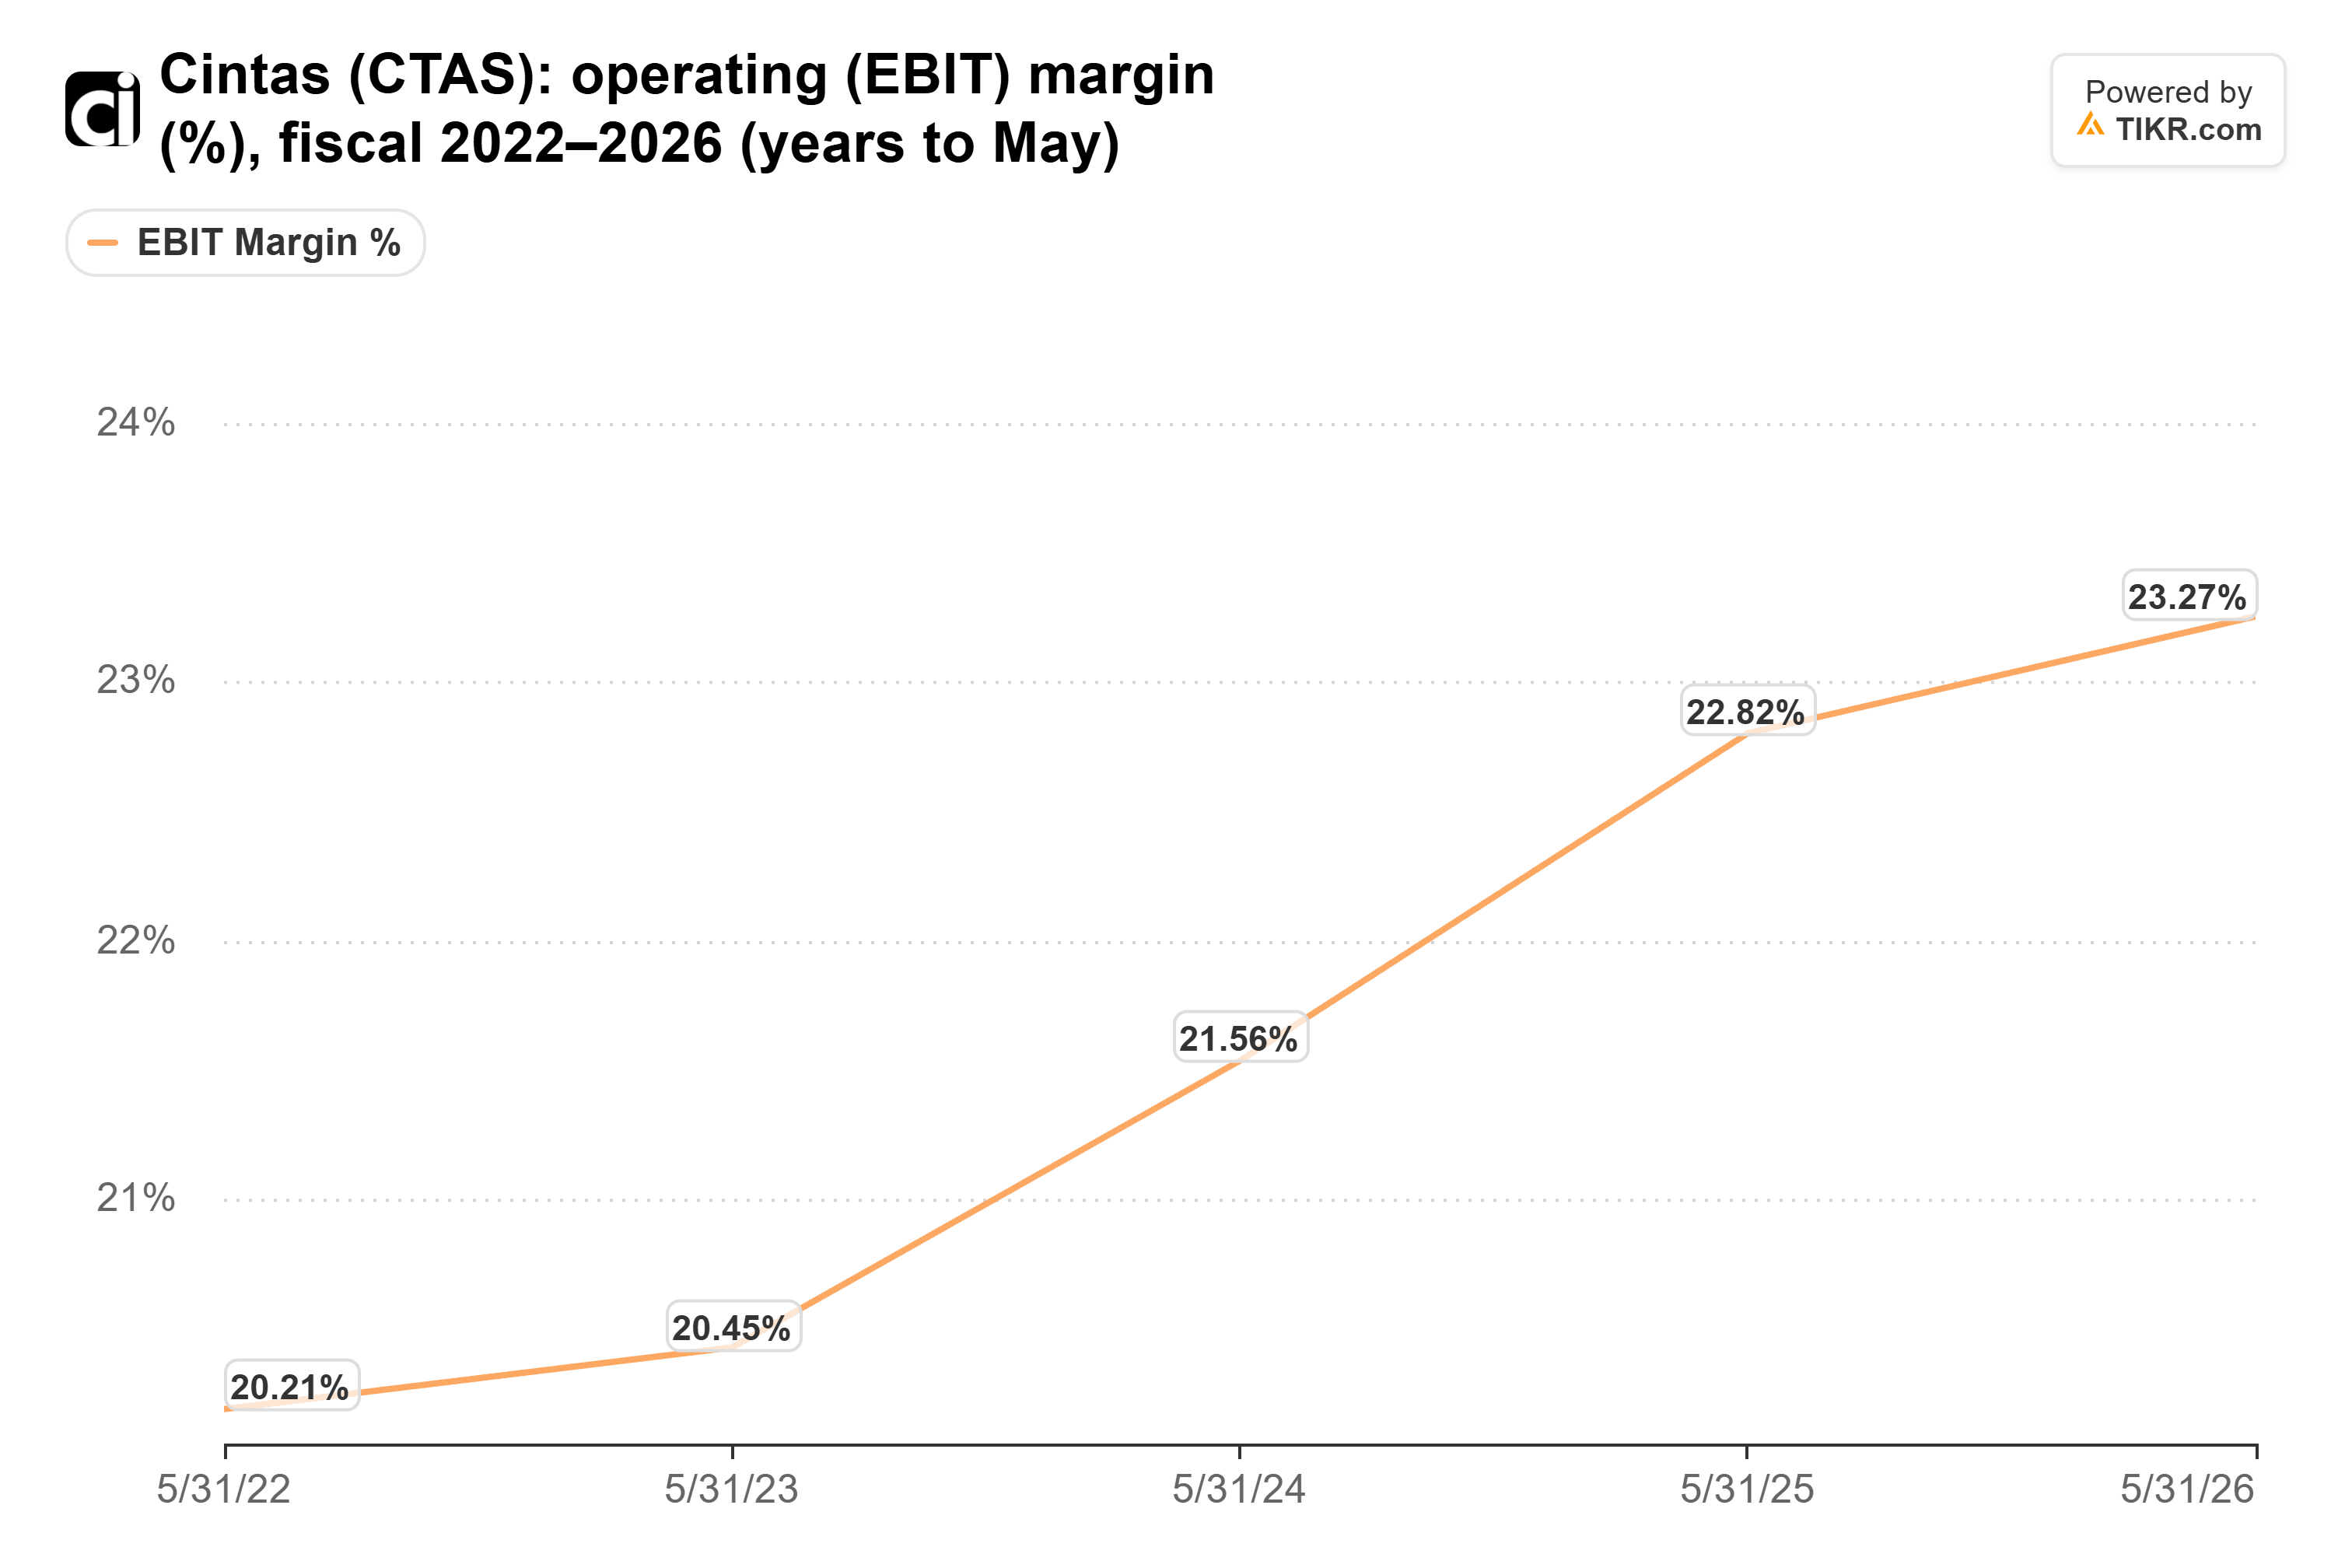
- Analysts expect Cintas’s normalized EPS to grow about 12% a year through fiscal 2028, and its operating margin has risen every year since fiscal 2022.
- The FTC hasn’t voted yet, so its decision is the next thing to watch.
Cintas (CTAS) stock fell 5% today after a report that the Federal Trade Commission plans to sue to block its $5.5 billion purchase of its uniform-rental rival UniFirst (UNF). UniFirst shares fell 10%.
What exactly happened
Semafor’s Rohan Goswami reported this morning that the FTC has told Cintas it will sue, citing people familiar with the matter. FTC staff have reportedly raised concerns about the two companies’ combined market share.
But nothing is final yet. The FTC hasn’t voted, and an FTC spokesperson said: “Any decision will not be communicated through the press.”
Here are the deal’s terms, announced on March 11:
- $310 per UniFirst share, half in cash and half in Cintas stock
- About $375 million of operating cost synergies, by Cintas’s estimate
- Approved by more than 99% of the votes cast at UniFirst’s June 11 special meeting
UniFirst was a cost story
Most of the deal’s appeal was the savings. UniFirst runs the same business, so Cintas could merge UniFirst’s routes, plants and supply chains with its own and serve more customers with the same trucks.
Cintas already does this well. Its operating margin has gone up every year, from 20.2% in fiscal 2022 to 23.3% in fiscal 2026 (the year ended May 2026).
UniFirst would have given Cintas many more routes and plants to do the same with. So losing $375 million of planned savings would be a real blow to Cintas’s upside.
TIKR tracks 20 analysts on Cintas. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cintas, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cintas’ Analyst Ratings
Cintas can grow without it
Still, Cintas’s own earnings keep growing. Analysts expect normalized EPS to rise from $4.94 in fiscal 2026 to $6.16 in fiscal 2028, about 12% a year.

And today’s drop brings the valuation back to normal. Cintas closed Monday at 40x forward earnings, and at today’s price it’s closer to 38x.

That’s right at its five-year average, and well below the 52x it reached in November 2024.
The FTC still has to vote
If the FTC does sue, Cintas can fight it in court, offer to sell parts of the business to win approval, or walk away. A long court fight would take up management’s time and leave the stock waiting on a judge.
My take: Losing UniFirst would mean giving up a lot of savings, but Cintas’s own business is still widening its margins and growing earnings by double digits a year. With the stock at its usual multiple, today’s drop makes Cintas more interesting, and UniFirst becomes extra upside if the deal survives.
Of course, a lawsuit would push that upside a long way out, so the FTC’s vote is the thing to watch.
So what is Cintas stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cintas could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!