Key Takeaways
- Cantor Fitzgerald cut its SK hynix price target to $250 from $300 on Oct. 26 and kept its Overweight rating. The new target is 75% above Monday’s close.
- SK hynix is 28% below its September high after China’s CXMT claimed a denser DRAM design and worries about AI spending came back.
- The $250 target works out to about 7.4x next-twelve-months earnings, against about 4.2x today, and analysts have cut their 2027 earnings estimate by about 13% since July.
- Cantor’s target looks like the best case until SK hynix’s Oct. 28 third-quarter report shows 2027 prices holding up.
Cantor Fitzgerald’s C.J. Muse, who began covering the US-listed shares of SK hynix (SKHY) in August with a $300 target, cut it to $250 on Monday, Oct. 26, and kept his Overweight rating. Even after the cut, $250 sits 75% above Monday’s close, with the stock 28% below its Sept. 9 closing high.
The timing stands out. SK hynix reports third-quarter results on Wednesday, Oct. 28, and plans to announce its next round of shareholder returns alongside them.
China, Then the AI Jitters
In mid-October, China’s CXMT claimed a denser DRAM design and said a standard server memory module built on it is due by the end of 2026. Elon Musk then put a date on the worry in an Oct. 16 post on X: if China ramps low-power memory as fast as it has ramped other products, “then 2028 will be a different story.” (He added that “HBM is a tougher hill to climb, however.”)
Then worries about the AI buildout came back. CNBC reported on Oct. 23 that concerns over the AI trade dragged the Nasdaq down that week, with neoclouds among the hardest hit and credit risks mounting.
Cantor Cuts, and Stays Bullish
Muse started coverage on Aug. 4 with a $300 target, more than double the prior close of $142.72. At $250, he now sits almost exactly on the Street’s $247 mean target. One of August’s most bullish voices has moved close to the consensus mean.
He still has the company’s own outlook on his side. On its July 29 call, SK hynix said “it appears difficult for the supply-demand balance to improve meaningfully in the near term,” meaning memory stays scarce. It also said it had signed long-term agreements with around 10 customers, usually running about five years and backed by deposits.
TIKR Tracks 16 Analysts on SK hynix. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SK hynix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SK hynix’s Analyst Ratings
Does $250 Add Up?
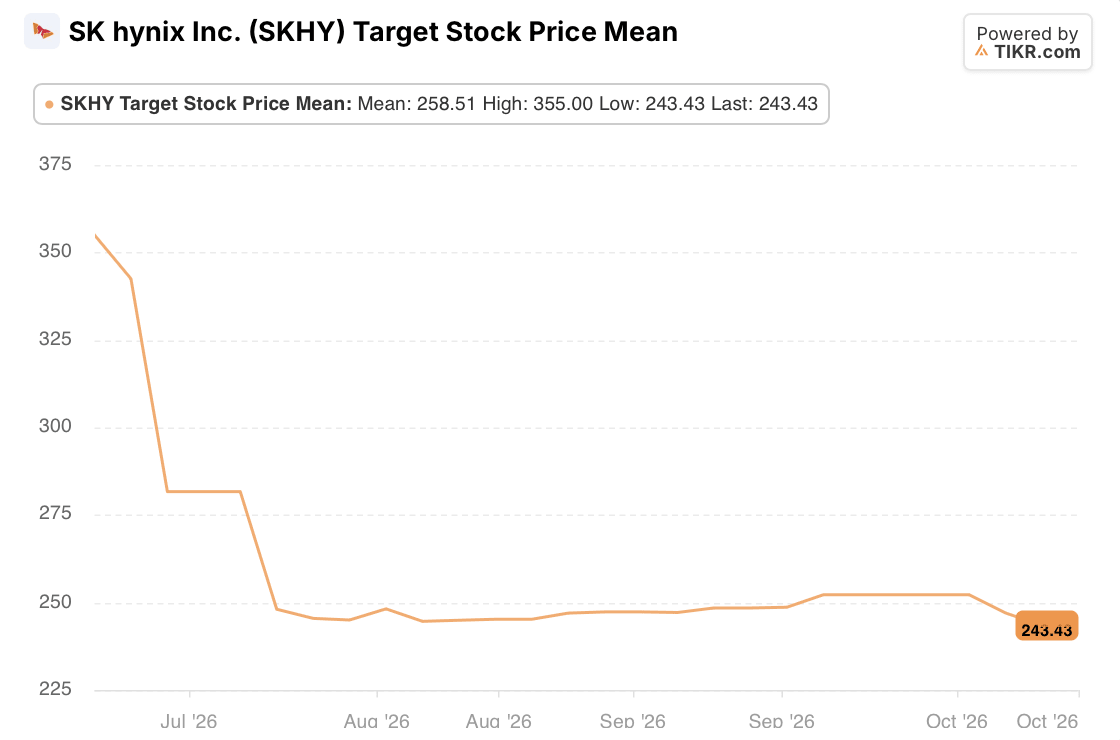
Targets run from $152 to $320 around that $247 mean. The mean has barely moved since August, when it was about $245, so Cantor’s cut reads as one bull coming back to the crowd, not the crowd turning.

The earnings estimates point in two directions. Analysts expect $27.11 a share for 2026, up from $24.65 three months ago, but their 2027 estimate is $35.02, down from $40.47.

In July, analysts had 2027 earnings 64% above 2026. Now the gap is 29%.
On those estimates, the stock trades at about 4.2x next-twelve-months earnings. Cantor’s $250 works out to about 7.4x, so the target needs investors to pay a much richer multiple for earnings that analysts are still cutting.
Memory Has Been Here Before
A memory maker at record margins rarely gets a high multiple, because investors have seen what comes next. SK hynix earned a 76% operating margin in the second quarter of 2026. After its 2018 peak, operating profit fell 87% in 2019, and it posted an operating loss of 7.7 trillion won in 2023.
That history is why a multiple of about 4x doesn’t look cheap to me. The market prices SK hynix as if these are close to peak earnings, and $250 asks investors to pay more for 2027 profits that analysts have cut by about 13% since July. Until the cycle shows it can run longer than the last two, I’d treat Cantor’s target as the best case.
What SK hynix Has to Prove on Wednesday
What management says about 2027 HBM pricing is what to watch. In July, it said those negotiations were still under way, and how they land will weigh heavily on whether the 2027 estimate keeps sliding. SK hynix will also announce new shareholder returns with the results, on top of the 40 trillion won buyback it finished on Oct. 23. Bigger returns would support the stock, but they don’t change what the business earns. For Cantor’s 7.4x to look reasonable, the 2027 estimate has to stop falling first.
So what is SK hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!