Key Takeaways
- Booking Holdings (BKNG) stock jumped 14% in the past week, most of it after a Q3 report that beat the company’s own guidance.
- Its forward P/E was 13.8x before the report, against a five-year average of 20.5x, and the jump closed only part of that gap.
- Today’s analyst targets, from $170 to $301, work out to about 14x to 24x fiscal 2027 earnings estimates.
- AI agents steering travelers to hotels’ own websites are the main risk, but the price already assumes a lot goes wrong.
Booking Holdings stock is up 14% in the past week after its Q3 numbers topped its own guidance.
It was down 28% for the year at Tuesday’s close and is down 20% now. Five analysts weighed in recently, with targets from $170 to $301.
Booking beat its own forecast
Booking said on its Q3 call that room nights, gross bookings, adjusted revenue and adjusted EBITDA all beat the high end of its guidance:
- Gross bookings: $54.5 billion, up 10%
- Room nights: up 7%, from 5% growth in Q2
- Adjusted EPS: $4.66
Going in, analysts expected normalized EPS to climb from $9.12 in fiscal 2025 to $12.37 in fiscal 2027, a 36% gain in two years:
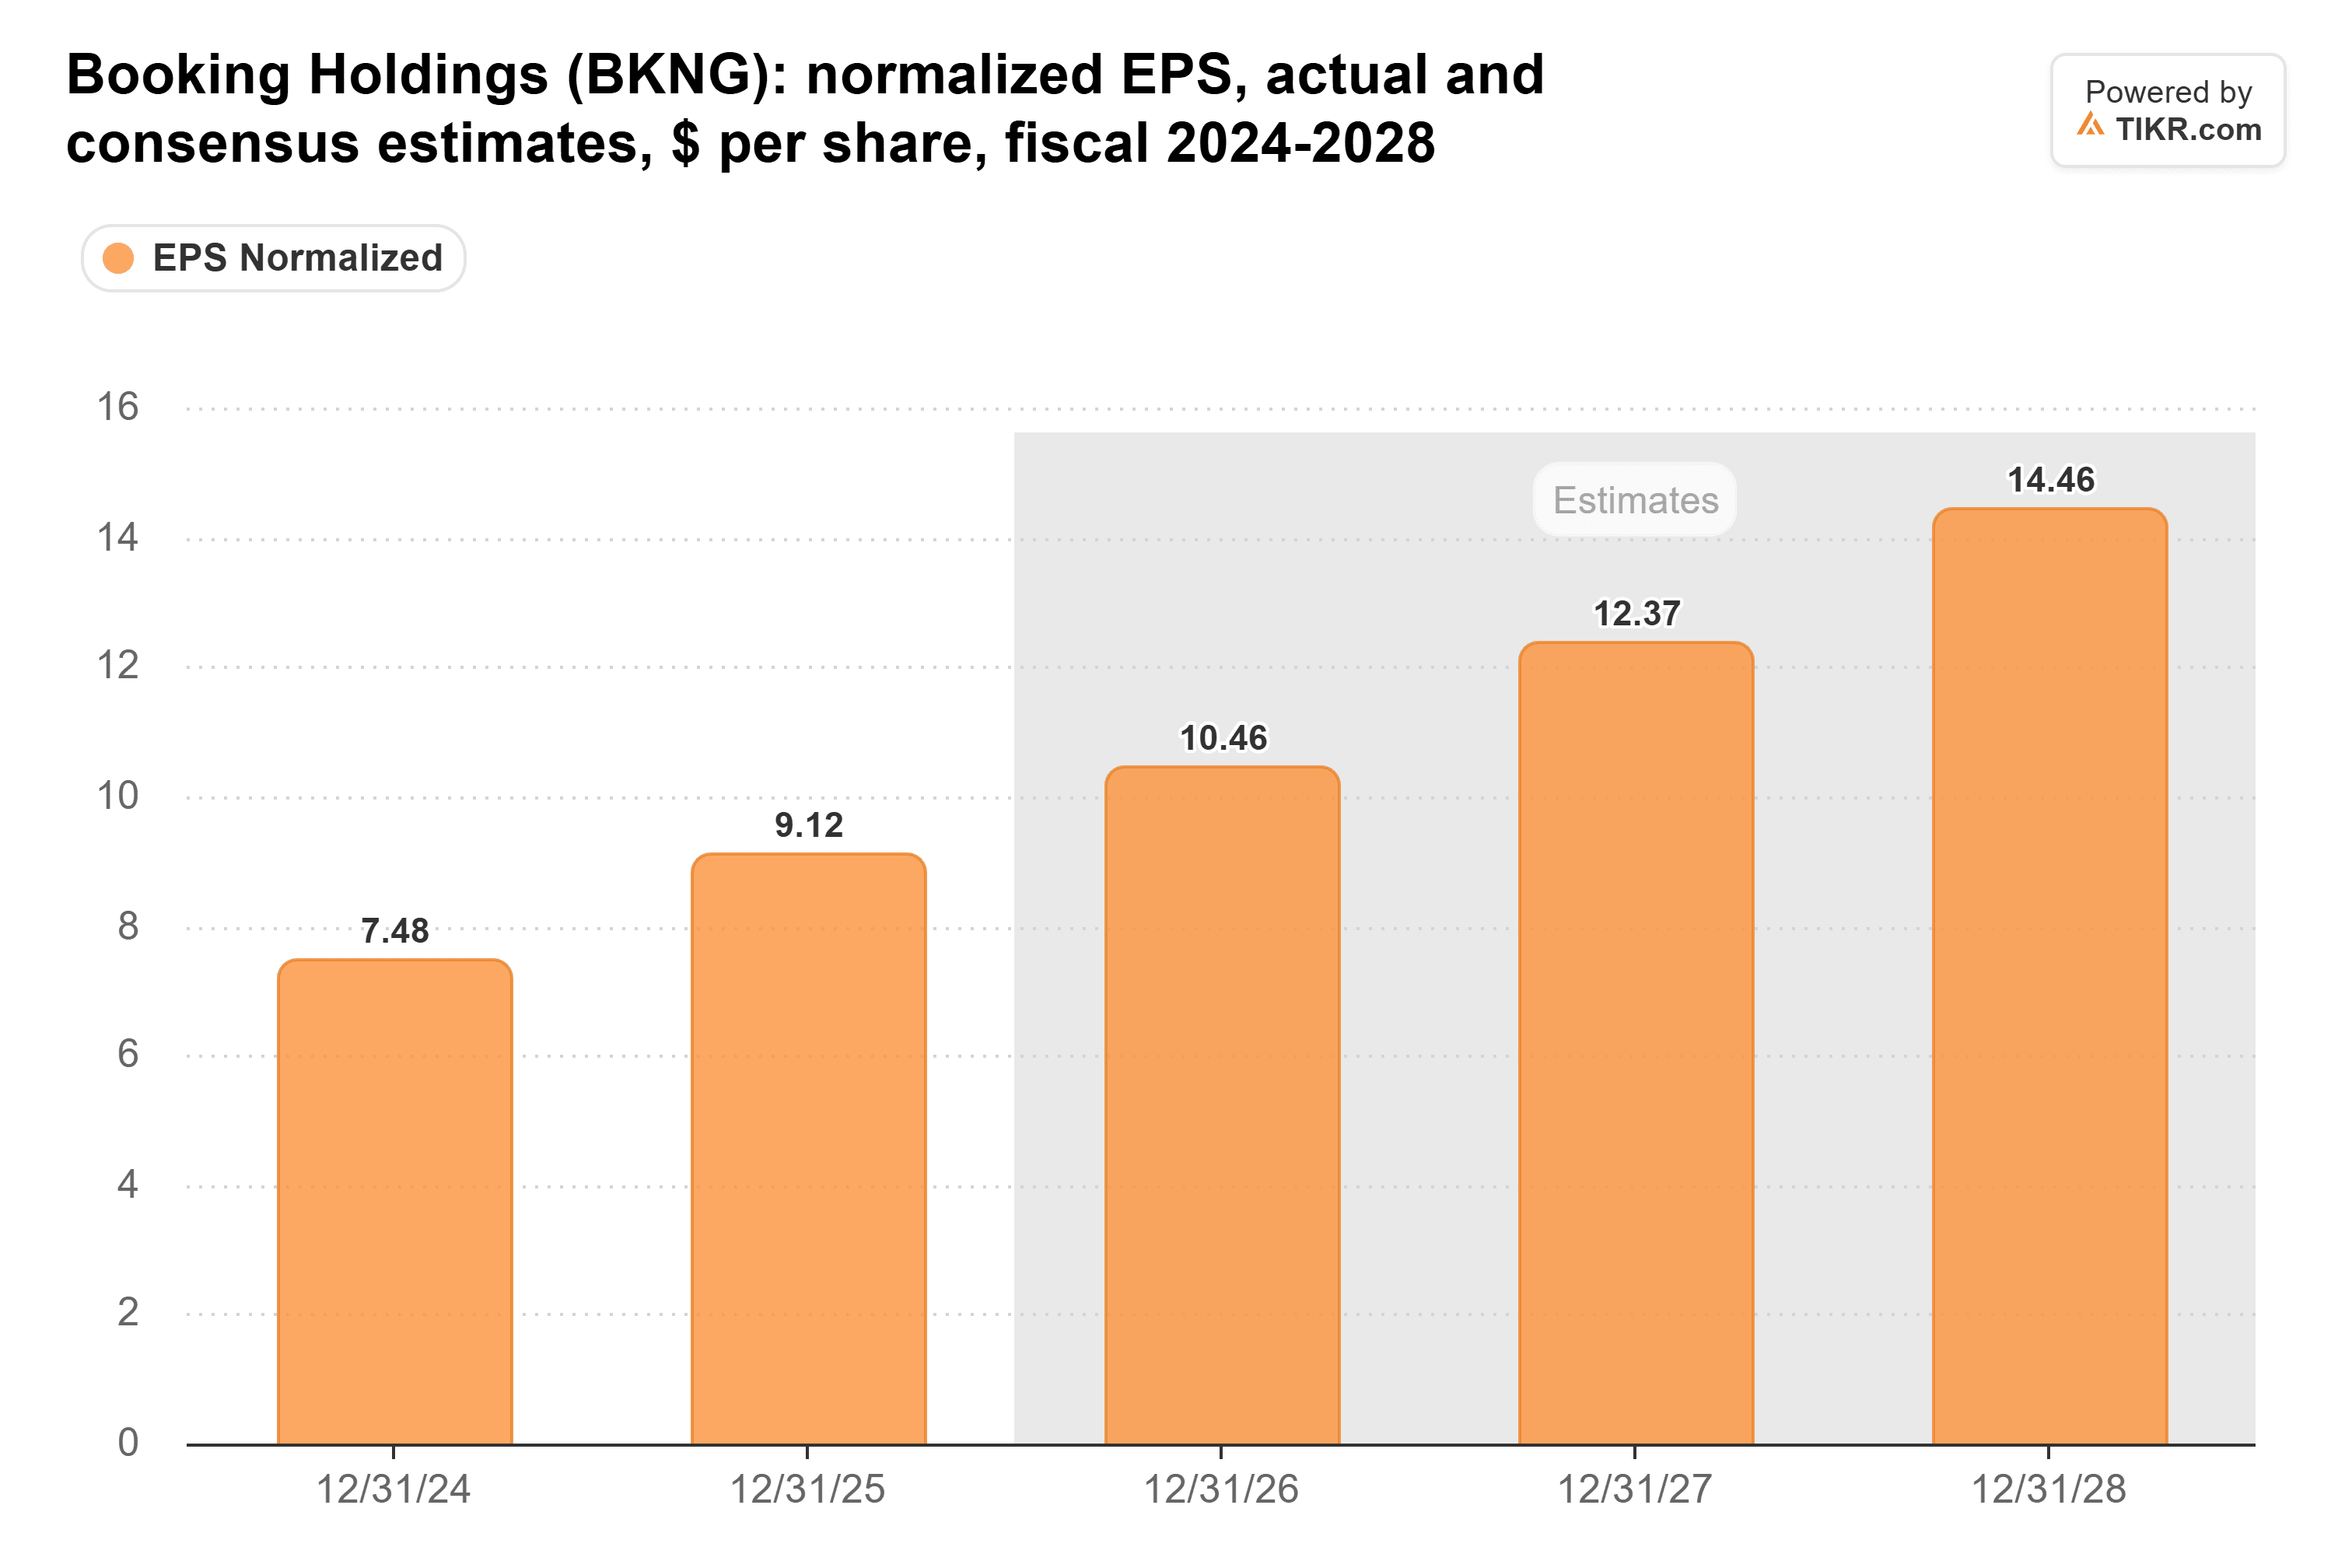
And nothing in this quarter gives analysts a reason to cut those numbers.
TIKR tracks 37 analysts on Booking Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Booking Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Booking Holdings’ Analyst Ratings
Most of the discount is still there
Booking’s forward P/E was 13.8x on Nov. 4, near its five-year low and far below its 20.5x average:
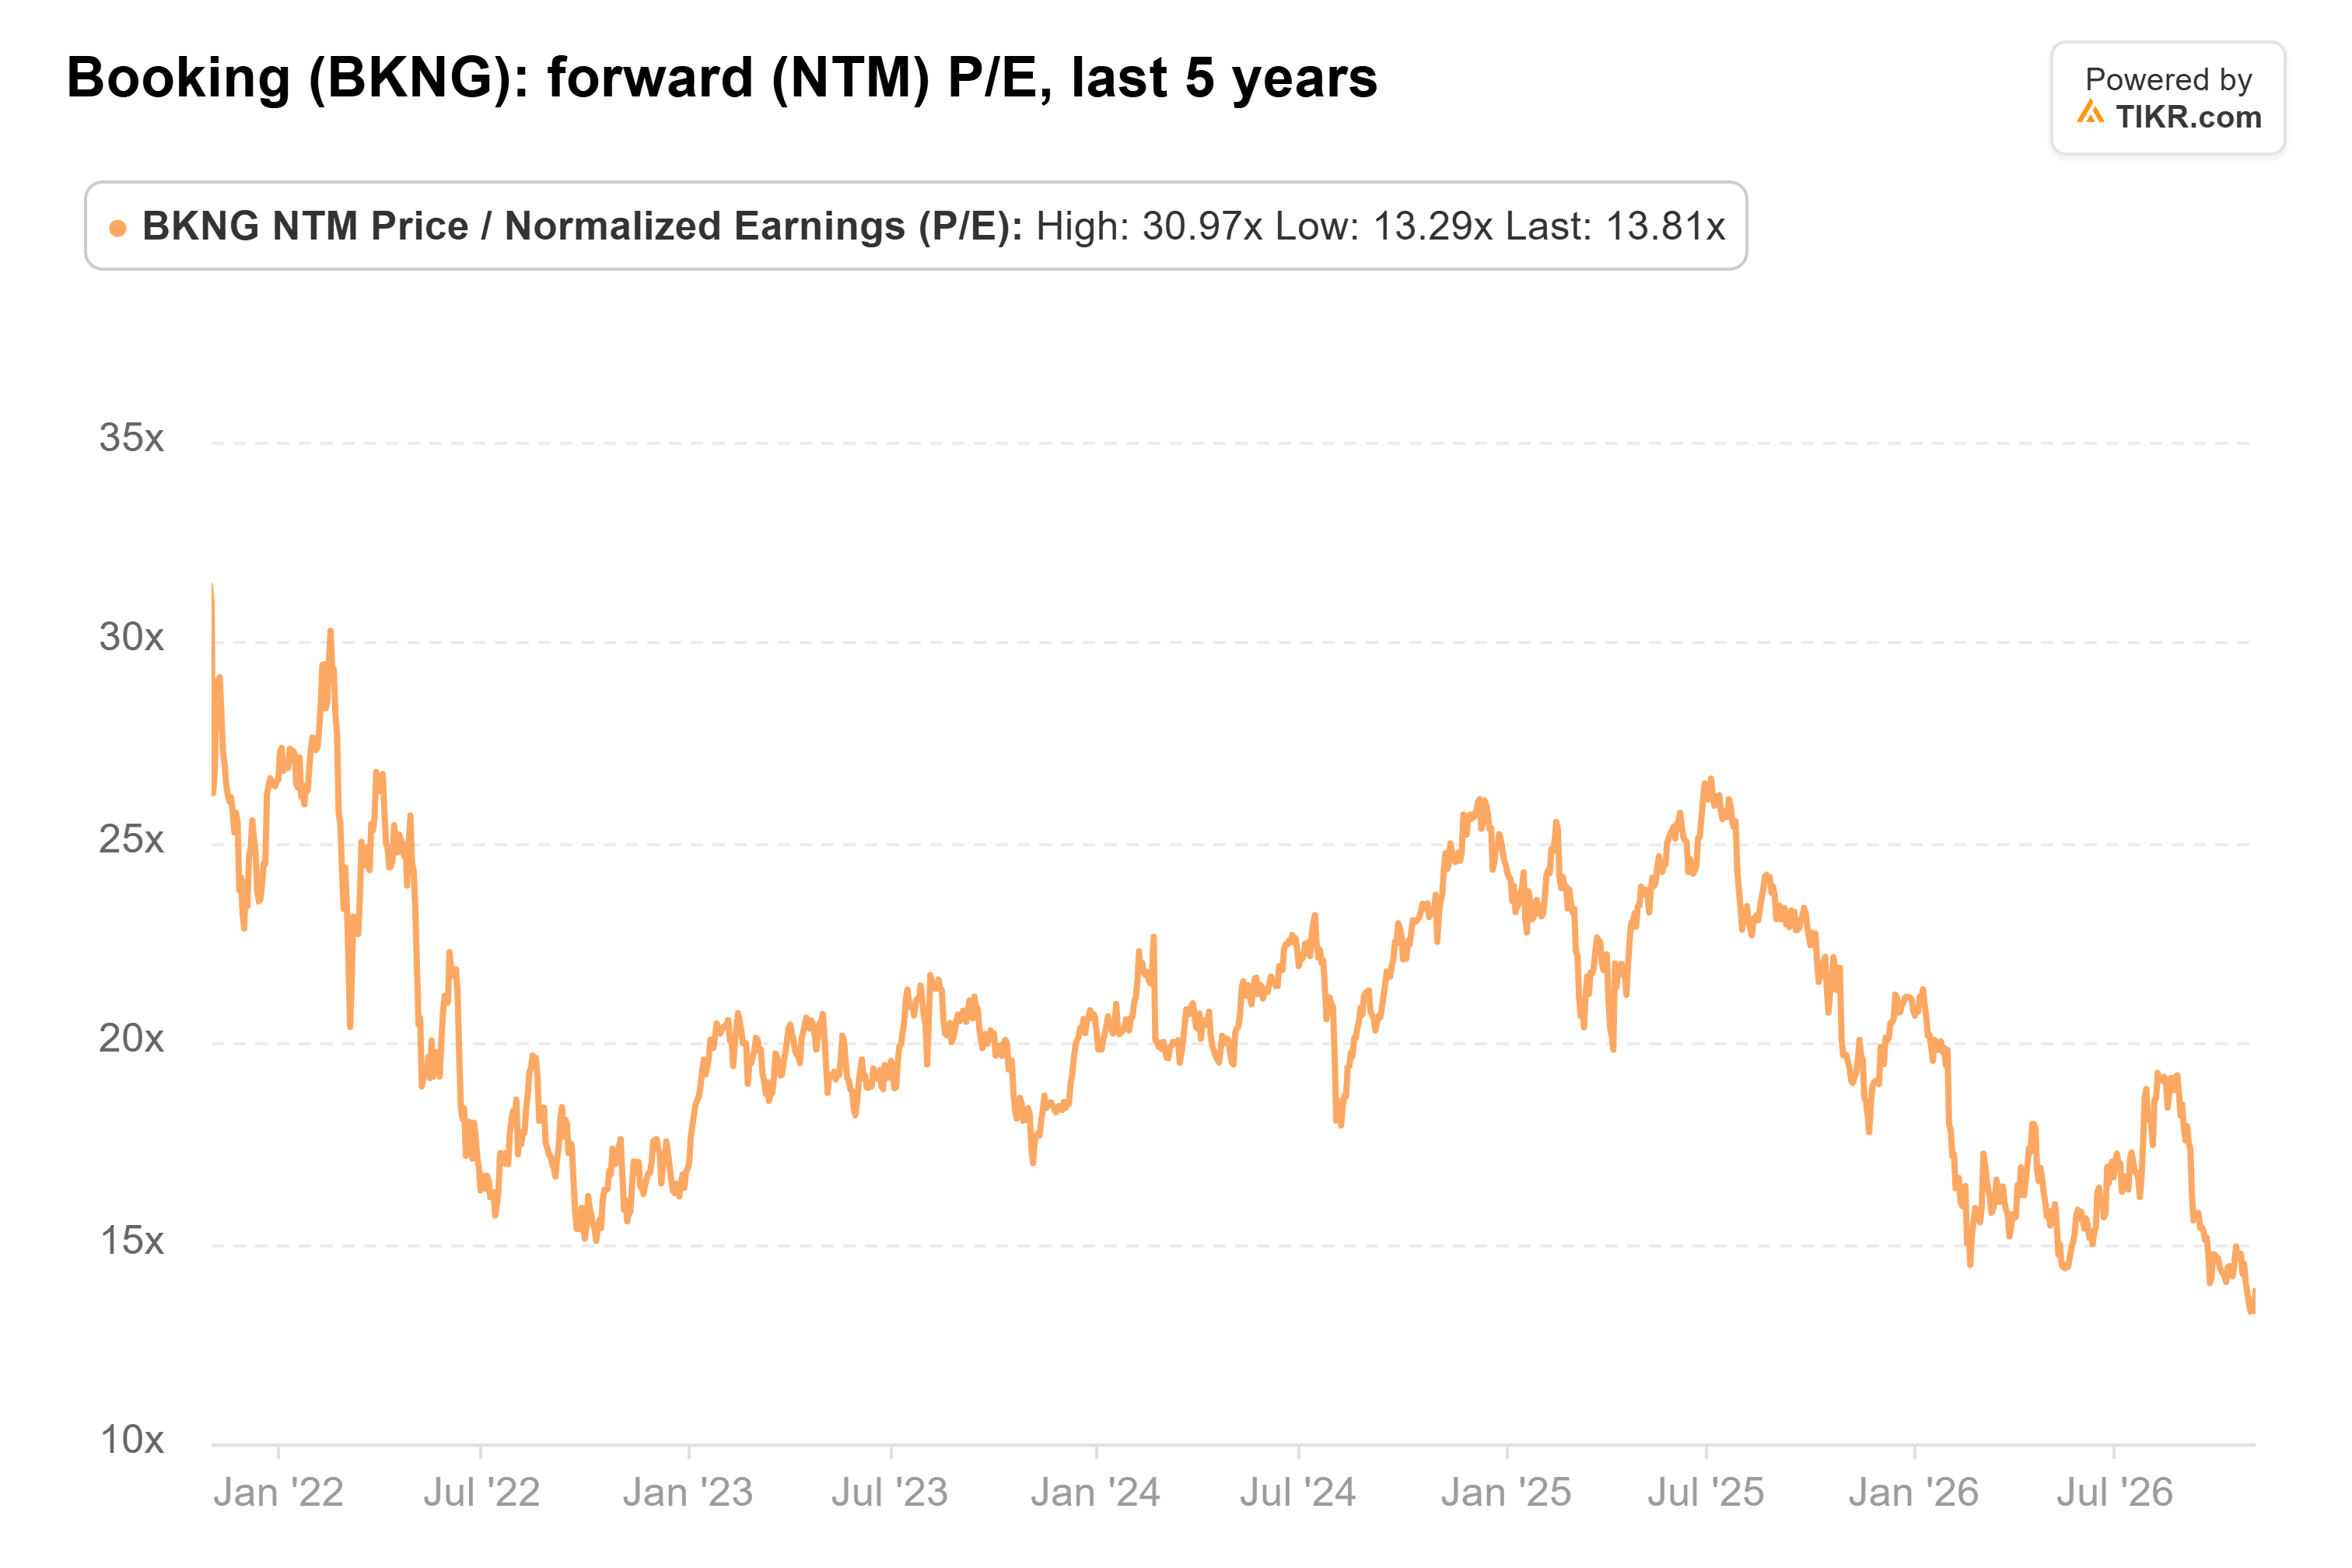
At today’s price, it’s closer to 15x.
So at its average multiple, today’s price would pay for about a quarter less in earnings than analysts expect over the next twelve months.
That’s less than the $9.12 a share Booking earned in fiscal 2025. (In fairness, that average leans on late 2021, when the multiple hit 31x on pandemic-hit earnings.)
Today’s calls split along the same line. Against the $12.37 fiscal 2027 estimate, each target implies:
- Cantor Fitzgerald, Hold, $150 (cut from $170): about 12x, below the five-year low
- Bernstein, Hold, $188: about 15x, roughly today’s multiple
- RBC Capital, Buy, $205: about 17x
- TD Cowen, Buy, $250: about 20x, near the average
- B. Riley Securities, initiated coverage at Buy, $265: about 21x
Hotels have a new way around Booking
The bear case is AI.
On Morgan Stanley’s Thoughts on the Market podcast on Monday, Morgan Stanley’s Stephen Grambling said hotels typically pay online travel agencies commissions of 10%-30%, against about 5% when guests book direct.
In Morgan Stanley’s test, search engines sent travelers to official hotel websites 13% of the time, and AI searches sent them there 97% of the time.
“As AI agents increasingly help travelers find hotels, compare options, and potentially book on their behalf, we could see a major pivot in brand preference and booking channel,” Grambling said.
Then again, when the AI agent was told a traveler belonged to an online travel agency’s loyalty program, the results moved entirely to that platform.
And so far, Booking’s free cash flow keeps climbing, from $6.19 billion in fiscal 2022 to $9.09 billion in fiscal 2025:

Room to run if the estimates hold
At about 14x, the price assumes one of two things: Booking’s earnings fall well short of the roughly 15% a year analysts model through fiscal 2028, or AI agents cut what it can charge for good.
That’s too gloomy for a company that just beat its own guidance and keeps growing its cash. I wouldn’t count on a return to the full 20.5x average, but RBC’s $205 looks reasonable to me.
Of course, Morgan Stanley’s test is one early snapshot of how AI agents book hotels. The next real check is Booking’s Q4 report early next year, and whatever it says about 2027.
So what is Booking Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Booking Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Booking Holdings for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!