


Key Takeaways
- Booking Holdings stock is down 27% this year, and UBS, Baird, Bank of America and RBC Capital all kept Buy ratings ahead of its third-quarter report, though most of them trimmed their targets.
- Analysts’ estimates point to a lower valuation as the cause of the drop: going into the report, consensus had normalized EPS climbing from $9.12 in fiscal 2025 to $14.46 in fiscal 2028.
- Booking’s third quarter beat its own guidance, with room nights up 7% against a forecast of 3%-5%, though demand softened in October and fourth-quarter guidance calls for room nights up just 1% to 3%.
- The stock trades near its lowest forward P/E in five years, and AI booking agents and Airbnb’s growth are the risks to watch.
Booking Holdings (BKNG) is down 27% this year through its Nov. 3 close, and analysts spent the weeks before its third-quarter report cutting their price targets.
They didn’t cut their ratings, though. Four of the five recent calls covered here still say Buy. Then Booking’s Nov. 3 report gave them a decent case, even as shares slipped about 1.5% in after-hours trading, according to Reuters.
Smaller targets, same Buy ratings
Here are the calls, newest first:
- UBS reiterated its Buy on Nov. 3, hours before the report, and cut its target to $265 from $274.
- Baird kept its Outperform rating, its version of a Buy, on Oct. 27 and cut its target to $223 from $230.
- Bank of America reiterated its Buy on Oct. 26 and trimmed its target to $232 from $234.
- RBC Capital kept its Buy and a $220 target on Oct. 20.
- Wells Fargo kept its Equal Weight rating on Oct. 7 and cut its target to $190 from $220.
Apart from Wells Fargo’s, those are small cuts. Even Wells Fargo’s $190 is 22% above Booking’s $155.67 close on Nov. 3, and UBS’s target is 70% above it. Not every firm is that upbeat: Goldman Sachs and Cantor Fitzgerald, both at Hold-equivalent ratings, cut their targets in October to $180 and $170.
TIKR tracks 37 analysts on Booking Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Booking Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Booking Holdings’ Analyst Ratings
The quarter beat the plan
Booking reported after the close on Nov. 3, and the quarter came in ahead of what management guided to in August. Room nights grew 7%, against guidance of 3% to 5%. Adjusted EBITDA rose 9%, against 4% to 6%, adjusted EPS jumped 17%, and gross bookings grew by double digits.
Revenue is messier. Booking now leads with an adjusted revenue figure, which grew 9% (about 10% in constant currency), while reported revenue slipped 1%. The gap is a $900 million revenue reduction, plus a $100 million accrued loss, tied to a Federal Trade Commission matter that Reuters reported involves Priceline. Booking left both out of its adjusted figures, and Reuters reported that the company warned it could face further fines.
The weaker news was in the outlook. Booking said travel demand cooled toward the end of the quarter as international trips slowed, though domestic travel held up. October was rougher still, with disrupted travel to and from the Middle East, higher airfares tied to the conflict, and unrest in some European cities. Booking’s guidance assumes all of that lasts through year-end. For the fourth quarter, it guided room nights up just 1% to 3% and adjusted EBITDA about flat, though it kept its full-year outlook.
Earnings estimates have held up
So did the drop come from a weaker earnings outlook? Going into the report, 33 analysts expected normalized EPS of $10.46 this year, and consensus had it reaching $14.46 by fiscal 2028, up from $9.12 in fiscal 2025.

A 17% jump in third-quarter adjusted EPS, along with Booking’s full-year call for low- to mid-teens adjusted EPS growth, gives analysts little reason for deep cuts, even with a softer fourth quarter.
The multiple has held up much worse. Booking’s forward P/E has fallen to 14x, close to its five-year low of 13x and well below its 21x average.
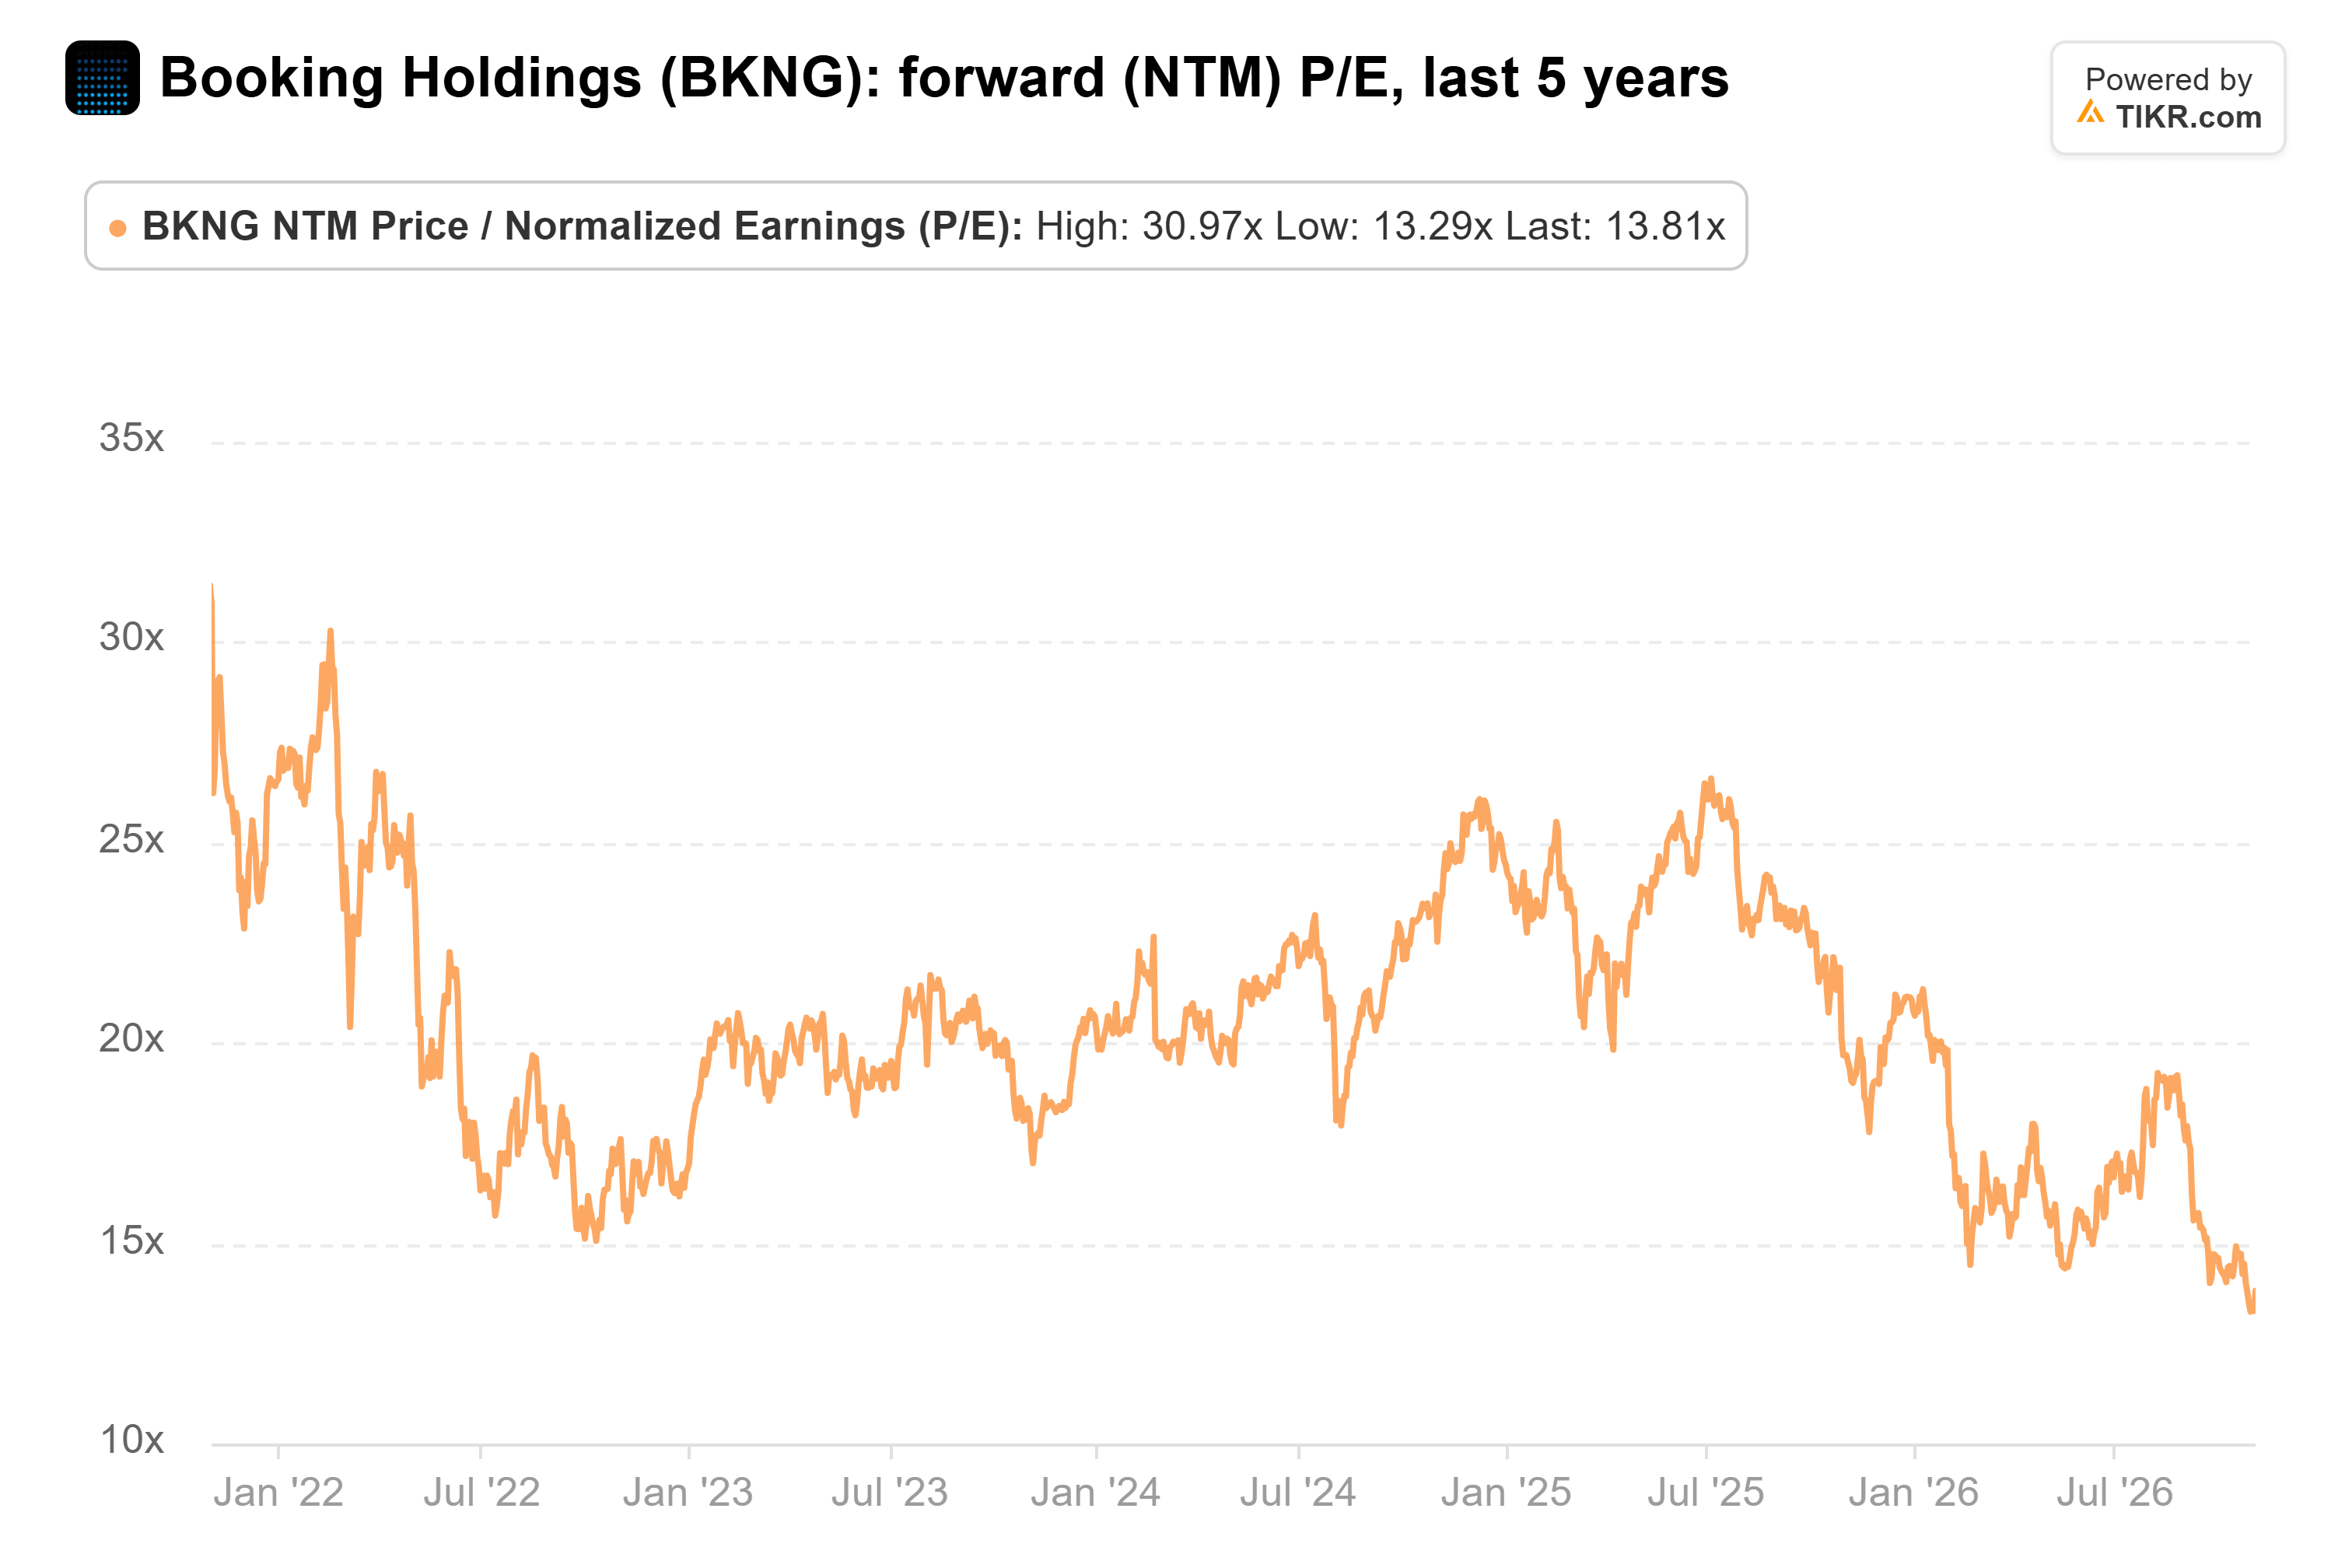
Most of the targets only need that multiple to get back to normal. Baird’s $223, RBC’s $220 and Bank of America’s $232 come to 20x-21x the earnings analysts expect over the next 12 months, right around the five-year average. UBS’s $265 needs 24x.
Hotels would love to skip the middleman
Of course, a multiple can fall for good reason. The market may be pricing in a slower future that the estimates don’t show yet.
AI is the first worry. On Morgan Stanley’s Thoughts on the Market podcast, lodging and leisure analyst Stephen Grambling said branded hotels typically pay online travel agencies commissions of 10% to 20%, and independents 20% to 30%. When guests book directly, it costs hotels closer to 5%. In his words: “As AI agents increasingly help travelers find hotels, compare options, and potentially book on their behalf we could see a major pivot in brand preference and booking channel.”
In Morgan Stanley’s test across eight US destinations, traditional search engines sent travelers to official hotel websites 13% of the time. AI searches sent them there 97% of the time.
That’s a lot of traffic that could go around Booking. But the same test found that when the traveler belonged to an online travel agency’s loyalty program, the AI’s results moved entirely to that platform. So far, AI isn’t steering much business anyway. On Booking’s Nov. 3 call, CFO Ewout Steenbergen said traffic from large language models had picked up in recent weeks but was “still significantly below 1%” of room nights. And over the past four quarters, the share of Booking’s room nights booked directly stayed in the mid-fifties percent range, about where it was a year earlier.
Airbnb is the second worry, in vacation rentals. On the We Study Billionaires podcast, hosts Kyle Grieve and Shawn O’Malley set Booking’s 4% second-quarter growth in alternative accommodations against Airbnb’s 10% growth in nights booked, noting that “it does appear that Airbnb is still taking market share from them.” Booking’s third quarter showed alternative accommodation room nights at Booking.com up 7%, and Airbnb reports its own quarter on Nov. 5.
Even so, analysts weren’t building in a growth collapse. Going into the report, consensus had revenue rising every year, from $26.9 billion in fiscal 2025 to $34.7 billion in fiscal 2028.

That’s about 9% a year, slower than the 11% and 13% of fiscal 2024 and 2025, but nothing like a business in decline.
The Buy calls have it right
The case for the Buy ratings is simple. If the estimates hold, Booking can reward shareholders on earnings growth alone, and any recovery in the multiple is a bonus.
Still, October’s softness is real. The next test is whether analysts cut their estimates after this report, and then fourth-quarter results in February. If those estimates start falling, the multiple won’t be Booking’s only problem.
So what is Booking Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Booking Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Booking Holdings for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


