Key Takeaways
- Bloom Energy stock is up 90.6% over the past year, yet it closed at $193.30 on October 23 after falling 11.24% the day after third-quarter revenue jumped 138.1% to $1.24 billion.
- The stock now trades at 40.21x forward normalized earnings, against a 76.15x average.
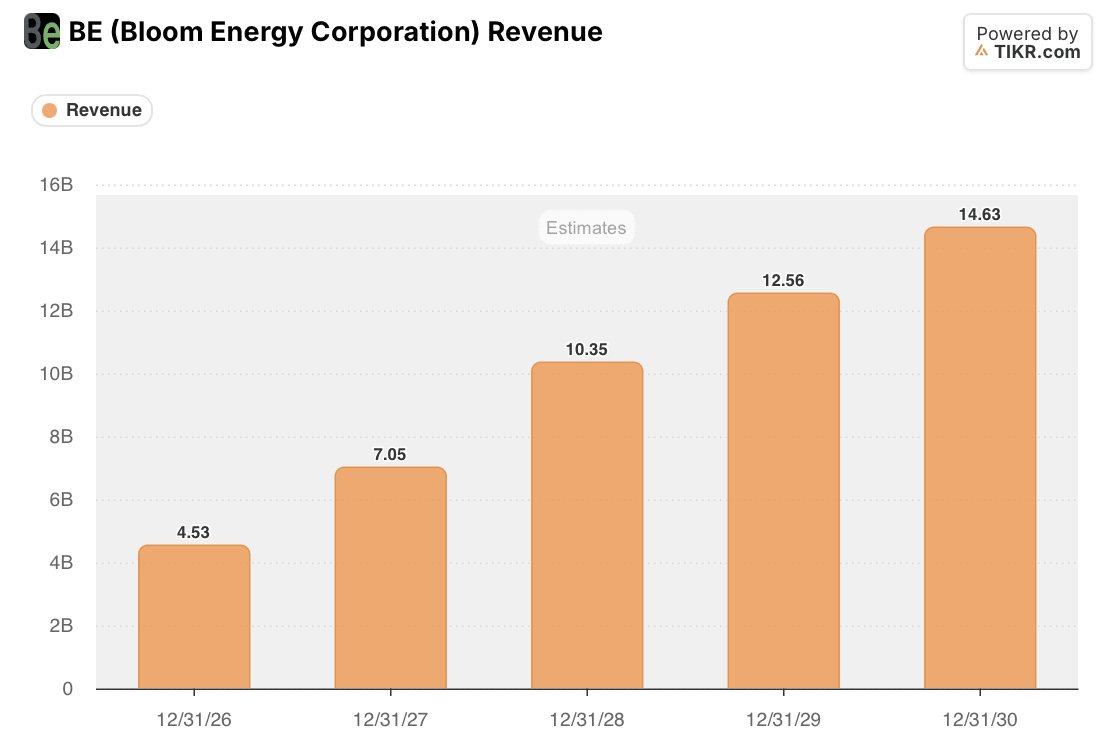
- Analysts expect revenue of $4.53 billion in 2026, rising to $14.63 billion by 2030.
- Bloom raised its 2026 revenue outlook for the third time, to $4.4 billion to $4.6 billion, but held off on a backlog figure until early next year.
Bloom Energy (BE) stock is up 90.6% over the past year, closing at $193.30 on October 23. Bloom posted record third-quarter revenue and raised its 2026 outlook for the third time on October 22, and Bloom Energy stock fell 11.24% the next session to a two-month low.
By my math, the stock lost 19.0% across October 22 and 23, sliding from a $238.53 close. That’s a lot of ground to give back in two days. Yet the drop leaves Bloom on its lowest earnings multiple in more than a year, while analysts still see revenue more than tripling by 2030.
How Bloom Energy Stock Climbed From the $70s to $351
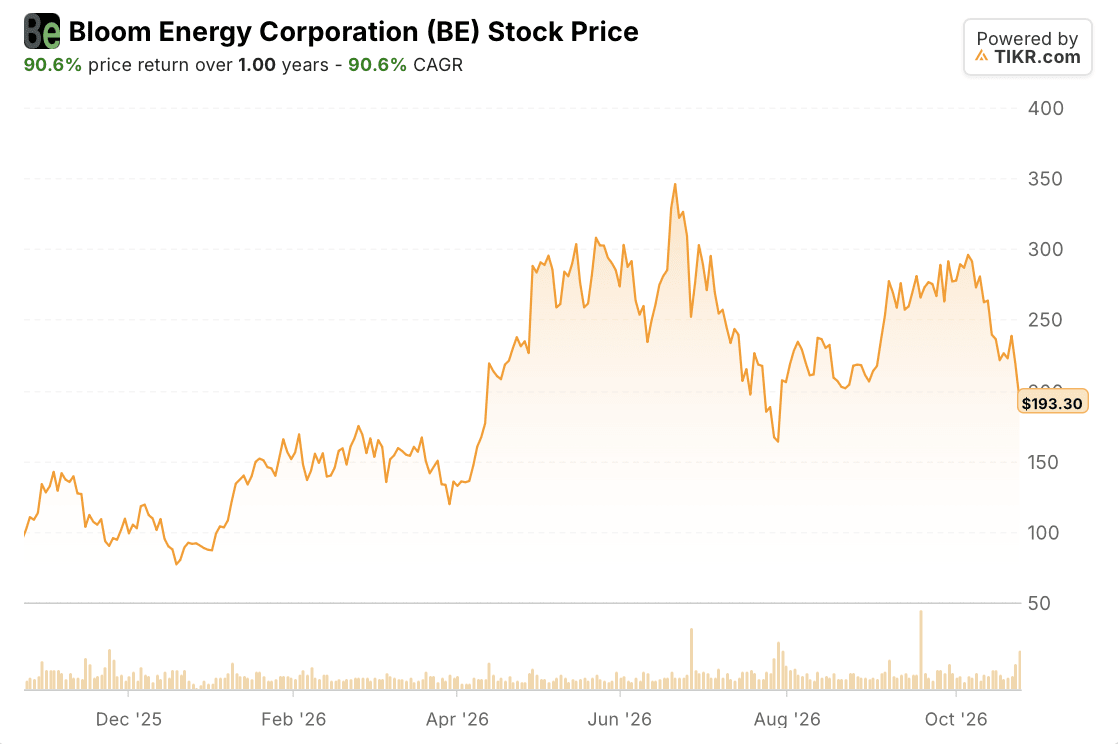
BE slid through late 2025, bottomed in the upper $70s in December, and worked back to the $170s by March. Bloom Energy stock jumped to a new 52-week high in mid-April after Oracle (ORCL) expanded their partnership to deploy up to 2.8 gigawatts of Bloom fuel cells, with an initial 1.2 GW already contracted. Two weeks later, Bloom reported first-quarter revenue of $751.1 million, up 130.4%.
The run peaked in early summer. The stock closed at a record $328.91 on June 18 after a 15.41% one-day jump, and later touched $351.28 intraday.
A Short Report, a $1 Billion Quarter and the S&P 500
The reversal started on July 8, when short seller Hunterbrook Media published a report alleging Bloom relies on Chinese scandium despite saying otherwise. (Scandium is a rare-earth metal that stabilizes the ceramic electrolyte in Bloom’s fuel cells.) Shares fell 5.7% to $254.29 that day. Bloom called the allegations false and misleading in a filing, and proposed securities class actions followed.
The slide ran into the July 28 report. Shares were down 11% intraday that session, then Bloom posted its first $1 billion quarter: revenue of $1.065 billion, up 165.5%, with 2026 guidance raised to $3.9 billion to $4.2 billion. The trough still came on July 29, more than 52% below the peak.
S&P Dow Jones Indices said on September 4 that Bloom would join the S&P 500, and Bloom Energy stock closed at $276.53 on September 22, the day after it entered the index. On October 14, American Electric Power (AEP) said it plans to invest approximately $4 billion in a 702-megawatt Bloom fuel cell plant in Wyoming to supply Google, owned by Alphabet (GOOGL), under a 20-year contract.
TIKR Tracks 32 Analysts on Bloom Energy. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
Bloom Energy Stock Fell 11% After a Beat-and-Raise
The selling started before the numbers. BE closed at $217.77 on October 22, down 8.7% on the day by my math, before the after-hours report.
The quarter itself cleared the bar. Revenue rose 138.1% to $1,235.8 million, above the $1.06 billion analysts expected, according to LSEG data cited by Reuters, and non-GAAP EPS of $0.94 topped the $0.68 estimate. Bloom lifted its 2026 range to $4.4 billion to $4.6 billion in revenue and $3.10 to $3.40 in non-GAAP EPS.
“We started our 2026 Q1 earnings call expecting a year-on-year revenue growth of 60%,” founder and CEO K.R. Sridhar said on the Q3 2026 earnings call. “Today, we are upward revising that guidance and projecting over 120% year-on-year revenue growth at the midpoint.” Bloom puts the new midpoint at approximately 122%.
Two things in the report pulled the other way. Operations used $27 million of cash as inventory, contract assets and receivables grew, and free cash flow was a $181 million outflow after $153 million of capital spending. CFO Simon Edwards said the quarter was not the start of a trend, pointing to positive operating cash flow year to date. Sridhar also declined to size backlog growth, saying the number comes with guidance early next year.
On October 23, Bloom Energy stock fell 11.24% to $193.30. Roth Capital said the valuation already reflected high expectations for orders and capacity growth, and that limited transparency kept it cautious, according to Reuters. Every target change Reuters logged that day still sat above the close, from a cut to $242 to a raise to $335.
Bloom Energy Stock Now Trades at 40x Earnings
A lower price and a raised earnings outlook have squeezed the multiple hard. BE trades at 40.21x forward normalized earnings, against a 76.15x average since late 2023 and a 199.35x peak, its lowest reading since the first half of 2025.
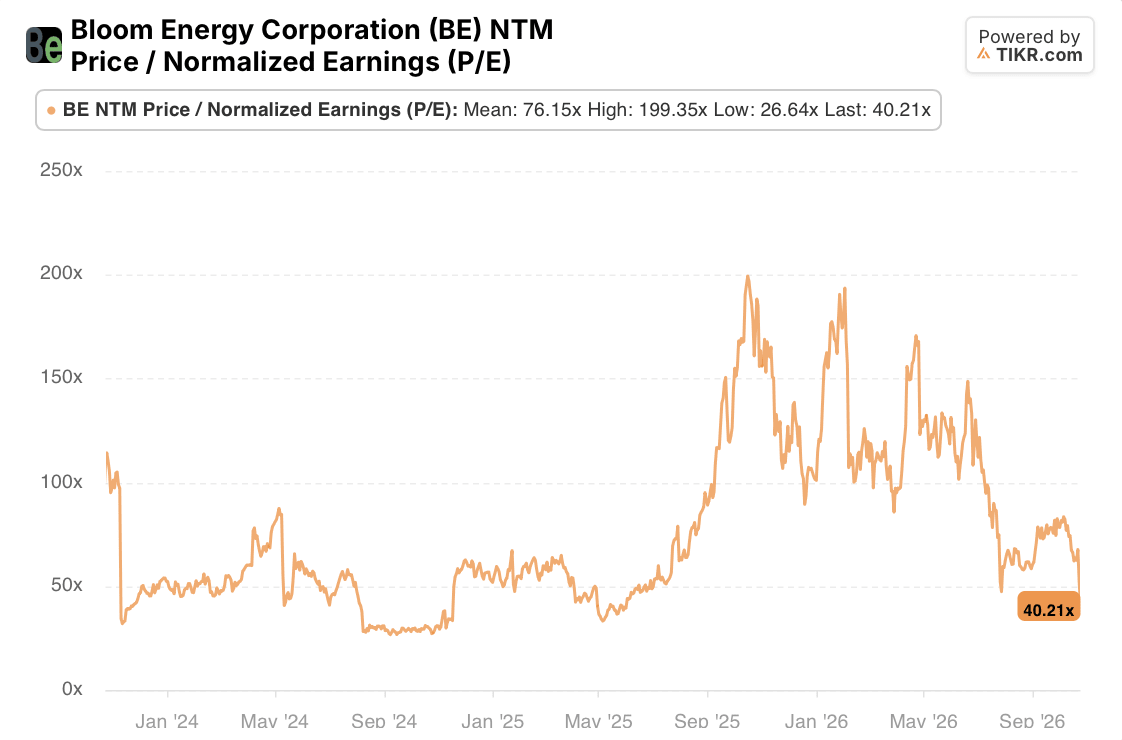
That 40.21x on $193.30 implies $4.81 of normalized EPS over the next 12 months, well above the $3.10 to $3.40 Bloom guides for 2026. So 40.21x only holds if 2027 earnings keep climbing.
What the Street Expects From Bloom Energy Through 2030
Analysts expect $4.53 billion of revenue in 2026, just above the $4.5 billion midpoint of Bloom’s new range, and $7.05 billion in 2027, a 55.6% jump. Growth then cools to 46.8% in 2028, 21.4% in 2029 and 16.5% in 2030, when revenue reaches $14.63 billion, 3.2 times the 2026 figure. Next to that path, 40.21x reads less like a growth premium and more like a discount for doubt.
Two Ways to Read Bloom Energy Stock at $193.30
The bull read starts with the margin. Bloom turned 138.1% revenue growth into a 23.1% operating margin, raised guidance three times in one year, and still has analysts modeling 55.6% revenue growth in 2027. If next year lands near $7.05 billion, today’s multiple asks very little of it.
The bear read starts with cash and disclosure. A $181 million free cash outflow in a record quarter, no backlog figure until early 2027, and a stock that fell more than 52% peak to trough this summer all argue that 40.21x still isn’t cheap for a business whose deliveries hinge on customer site timing.
Nothing in the report pointed to weaker demand: guidance went up, margins went up, and the critique Reuters carried was about valuation and visibility. That tilts the read toward the bull side for me. The early-2027 guidance, with Bloom’s first backlog number, is where that view holds or breaks.
So What Is Bloom Energy Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what BE stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Bloom Energy Corporation for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!