Key Takeaways
- PepsiCo cut its fiscal 2026 core EPS growth outlook to 2.5% to 3.5% on Oct. 8, while Altria raised its 2026 adjusted EPS guidance on Oct. 29.
- Altria yields 5.8% against PepsiCo’s 4.3%, but PepsiCo has raised its dividend faster, 7% a year from fiscal 2020 to fiscal 2025 against 4% for Altria.
- Free cash flow covers both dividends over the latest twelve months, 75% for PepsiCo and 78% for Altria, though PepsiCo’s dividends used nearly all its free cash flow in fiscal 2024 and 2025.
- Watch whether PepsiCo’s cost cuts protect its margins, and whether Altria’s nicotine pouches can make up for falling cigarette volumes.
PepsiCo (PEP) cut its 2026 earnings outlook on Oct. 8, as rising input costs and a weaker product mix squeezed its margins. Three weeks later, Altria Group (MO) raised its own guidance.
Both pay the kind of dividend income investors build a portfolio around: 4.3% for PepsiCo and 5.8% for Altria. So which is the better dividend stock?
| Metric | PepsiCo (PEP) | Altria Group (MO) |
|---|---|---|
| Dividend yield | 4.3% | 5.8% |
| Annual dividend | $5.92 | $4.44 |
| Dividend growth, fiscal 2020-2025 | 6.9% a year | 4.1% a year |
| Cash dividend payout ratio (TTM) | 75% | 78% |
| Net debt/EBITDA | 2.0x | 1.7x |
| Interest coverage | 14.9x | 10.9x |
Source: TIKR and StockAnalysis, Nov. 5, 2026. TTM is the twelve months to Sept. 16, 2026 for PepsiCo and to Sept. 30, 2026 for Altria.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
PepsiCo’s coverage is back from the edge
PepsiCo is still growing its sales. Net revenue rose 5.6% in the 12 weeks ended Sept. 5, 2026, against the same quarter a year before, and organic revenue rose 3.1%. North American soft drinks are the weak spot: “we’re not satisfied with the performance in the U.S.,” CEO Ramon Laguarta said on the third-quarter call.
The Oct. 8 cut took fiscal 2026 core EPS growth down to 2.5% to 3.5%, from the low end of 5% to 7%. Laguarta said in the results release that “Additional structural cost reduction actions are being identified and will be implemented in the coming months.”
The dividend grew 6.9% a year, from $4.02 a share in fiscal 2020 to $5.62 in fiscal 2025. Dividends paid rose every year from $4.23 billion in fiscal 2016 to $7.64 billion in fiscal 2025, while free cash flow stayed between $5.42 billion and $7.92 billion, so the dividend caught up with it:
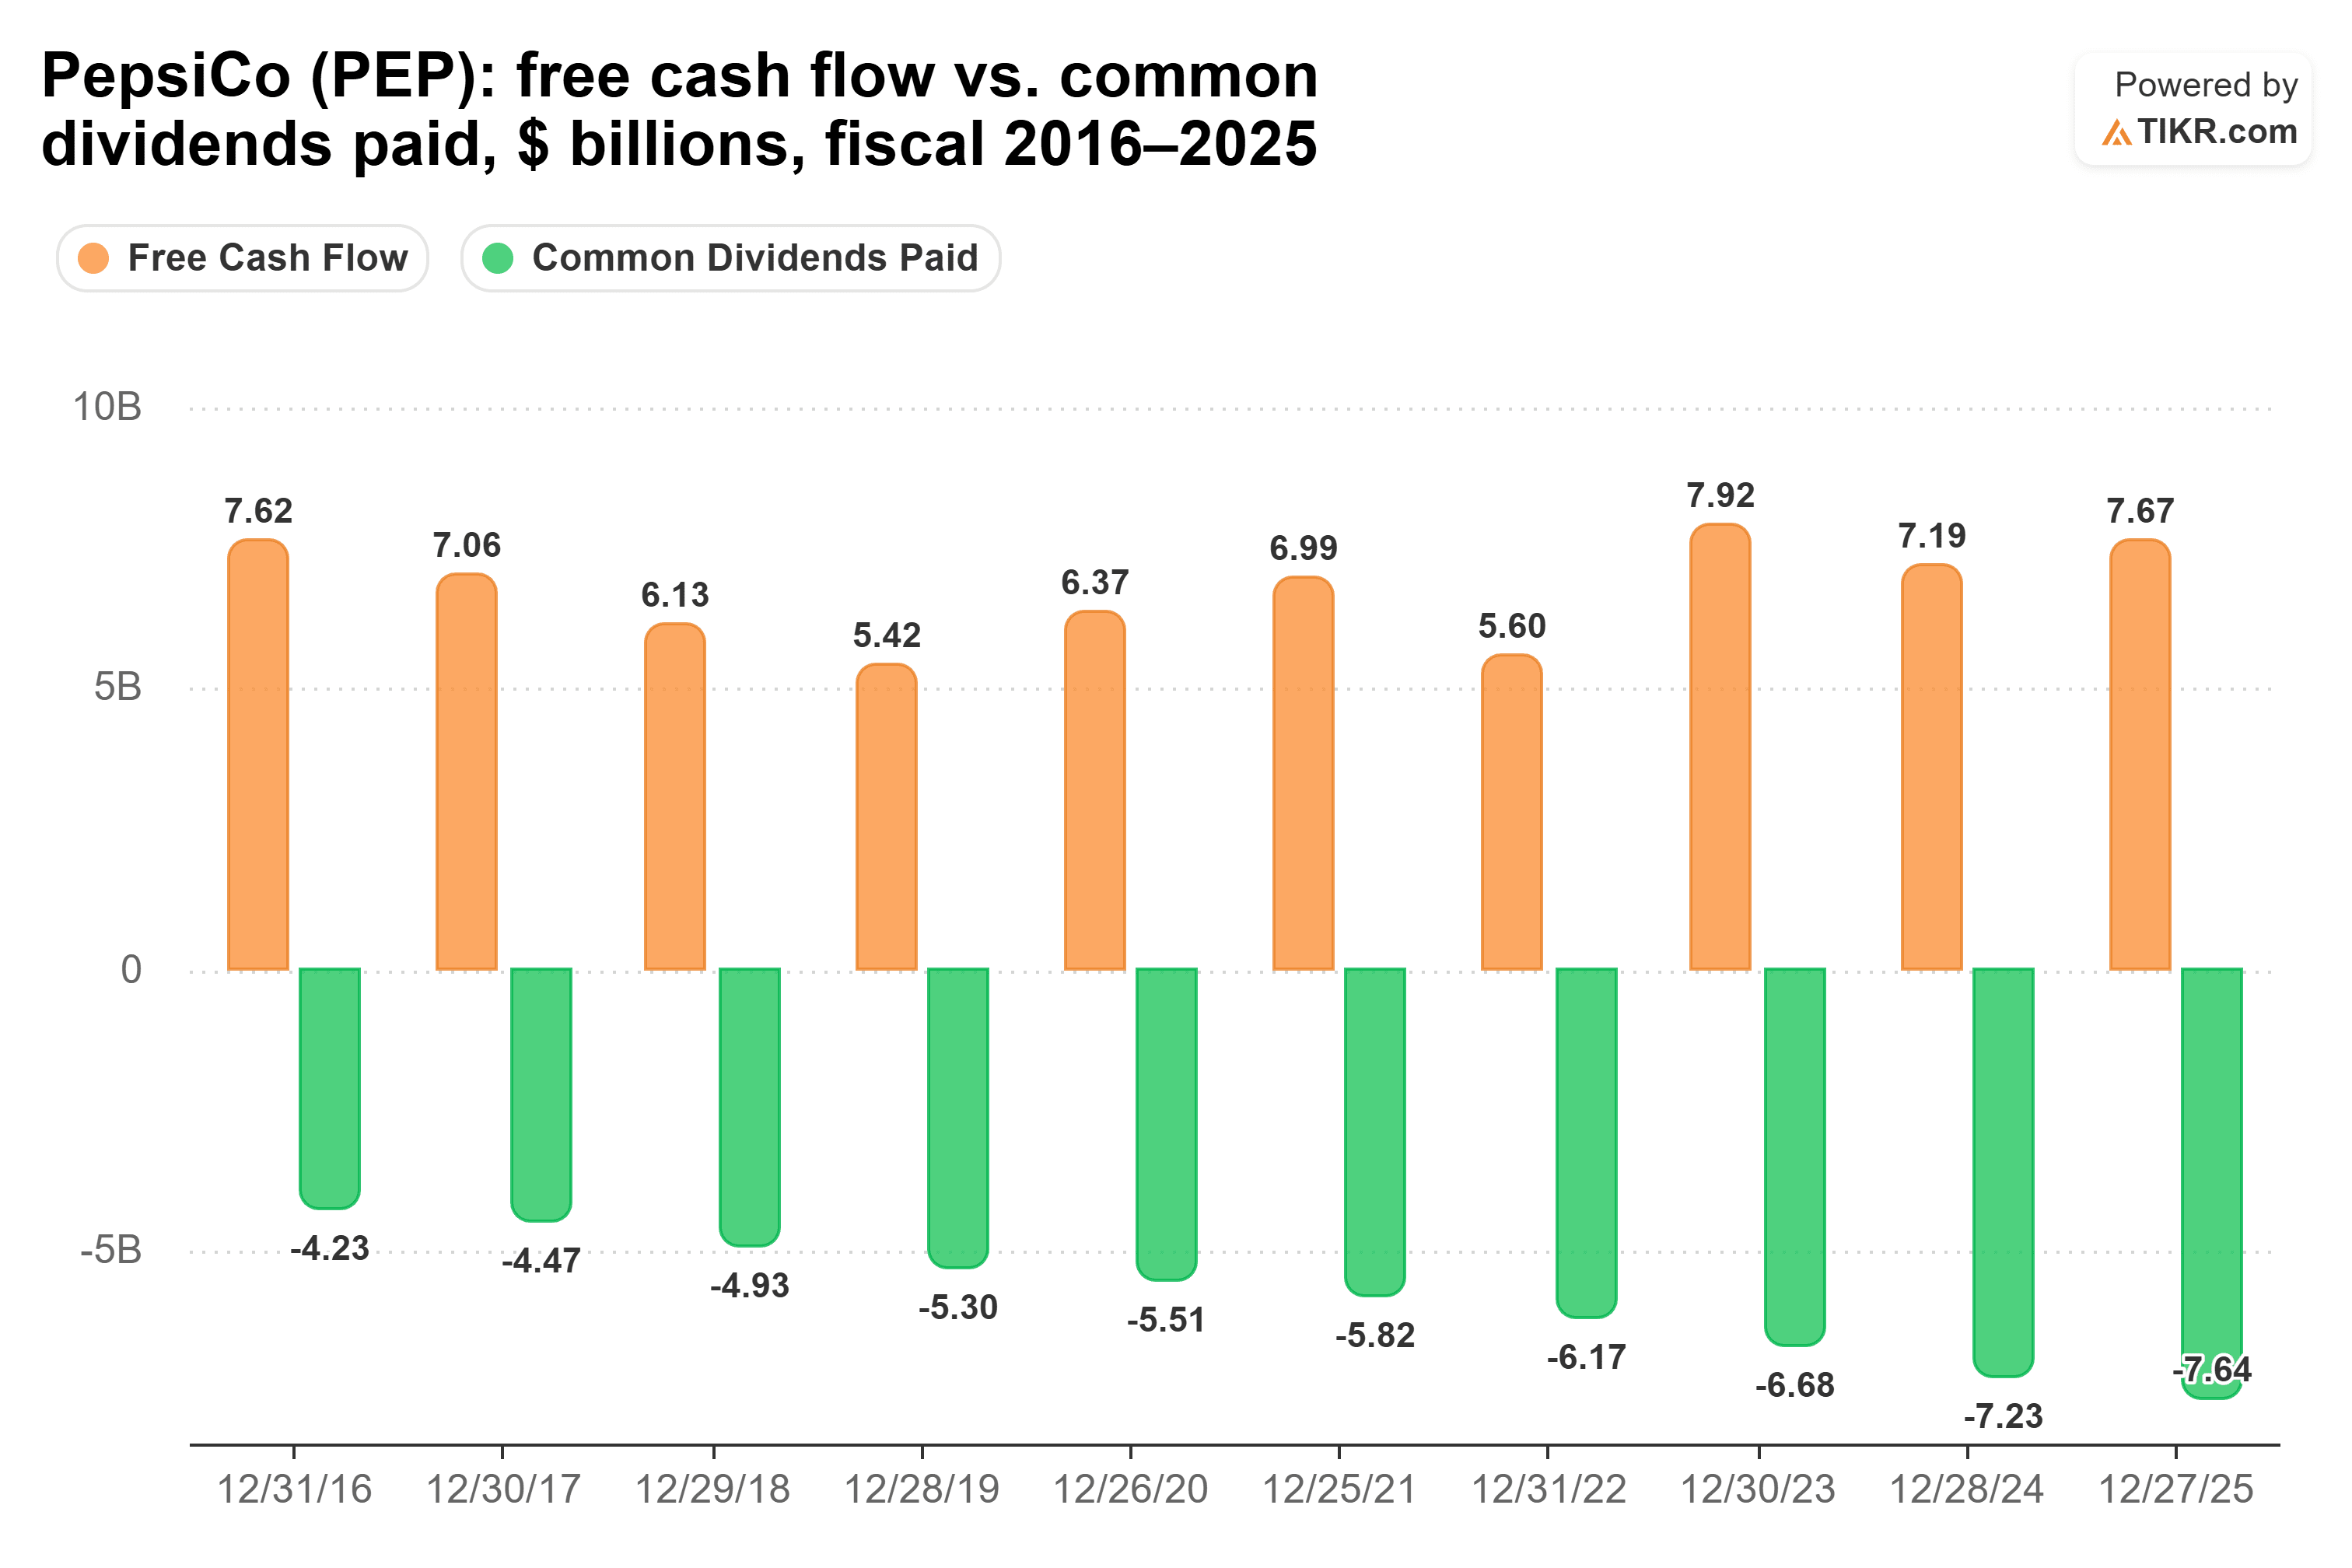
That left a risky cash dividend payout ratio of 100.6% in fiscal 2024 and 99.6% in fiscal 2025. Over the twelve months to Sept. 16, 2026, the ratio was a more manageable 75%: $7.88 billion of dividends against $10.47 billion of free cash flow.
Altria pays more from a shrinking core
Unlike PepsiCo, Altria barely grows its sales, but its profits hold up. Net revenues rose 1.0% to $6.1 billion in the third quarter of 2026 against a year before, and adjusted EPS rose 4.8% to $1.52. On Oct. 29, it raised its 2026 adjusted EPS guidance to $5.66 to $5.74, from $5.56 to $5.72.
Cigarette shipments keep falling as smokers trade down. Nicotine pouches are growing, but adjusted income from oral tobacco, pouches included, fell 3.7% to $443 million in the quarter.
In August, Altria raised its quarterly dividend 4.7% to $1.11 a share, “our 61st increase in 57 years,” as it put it on the call. It targets mid-single-digit dividend growth a year through 2028. Free cash flow has topped dividends paid every year since fiscal 2018:
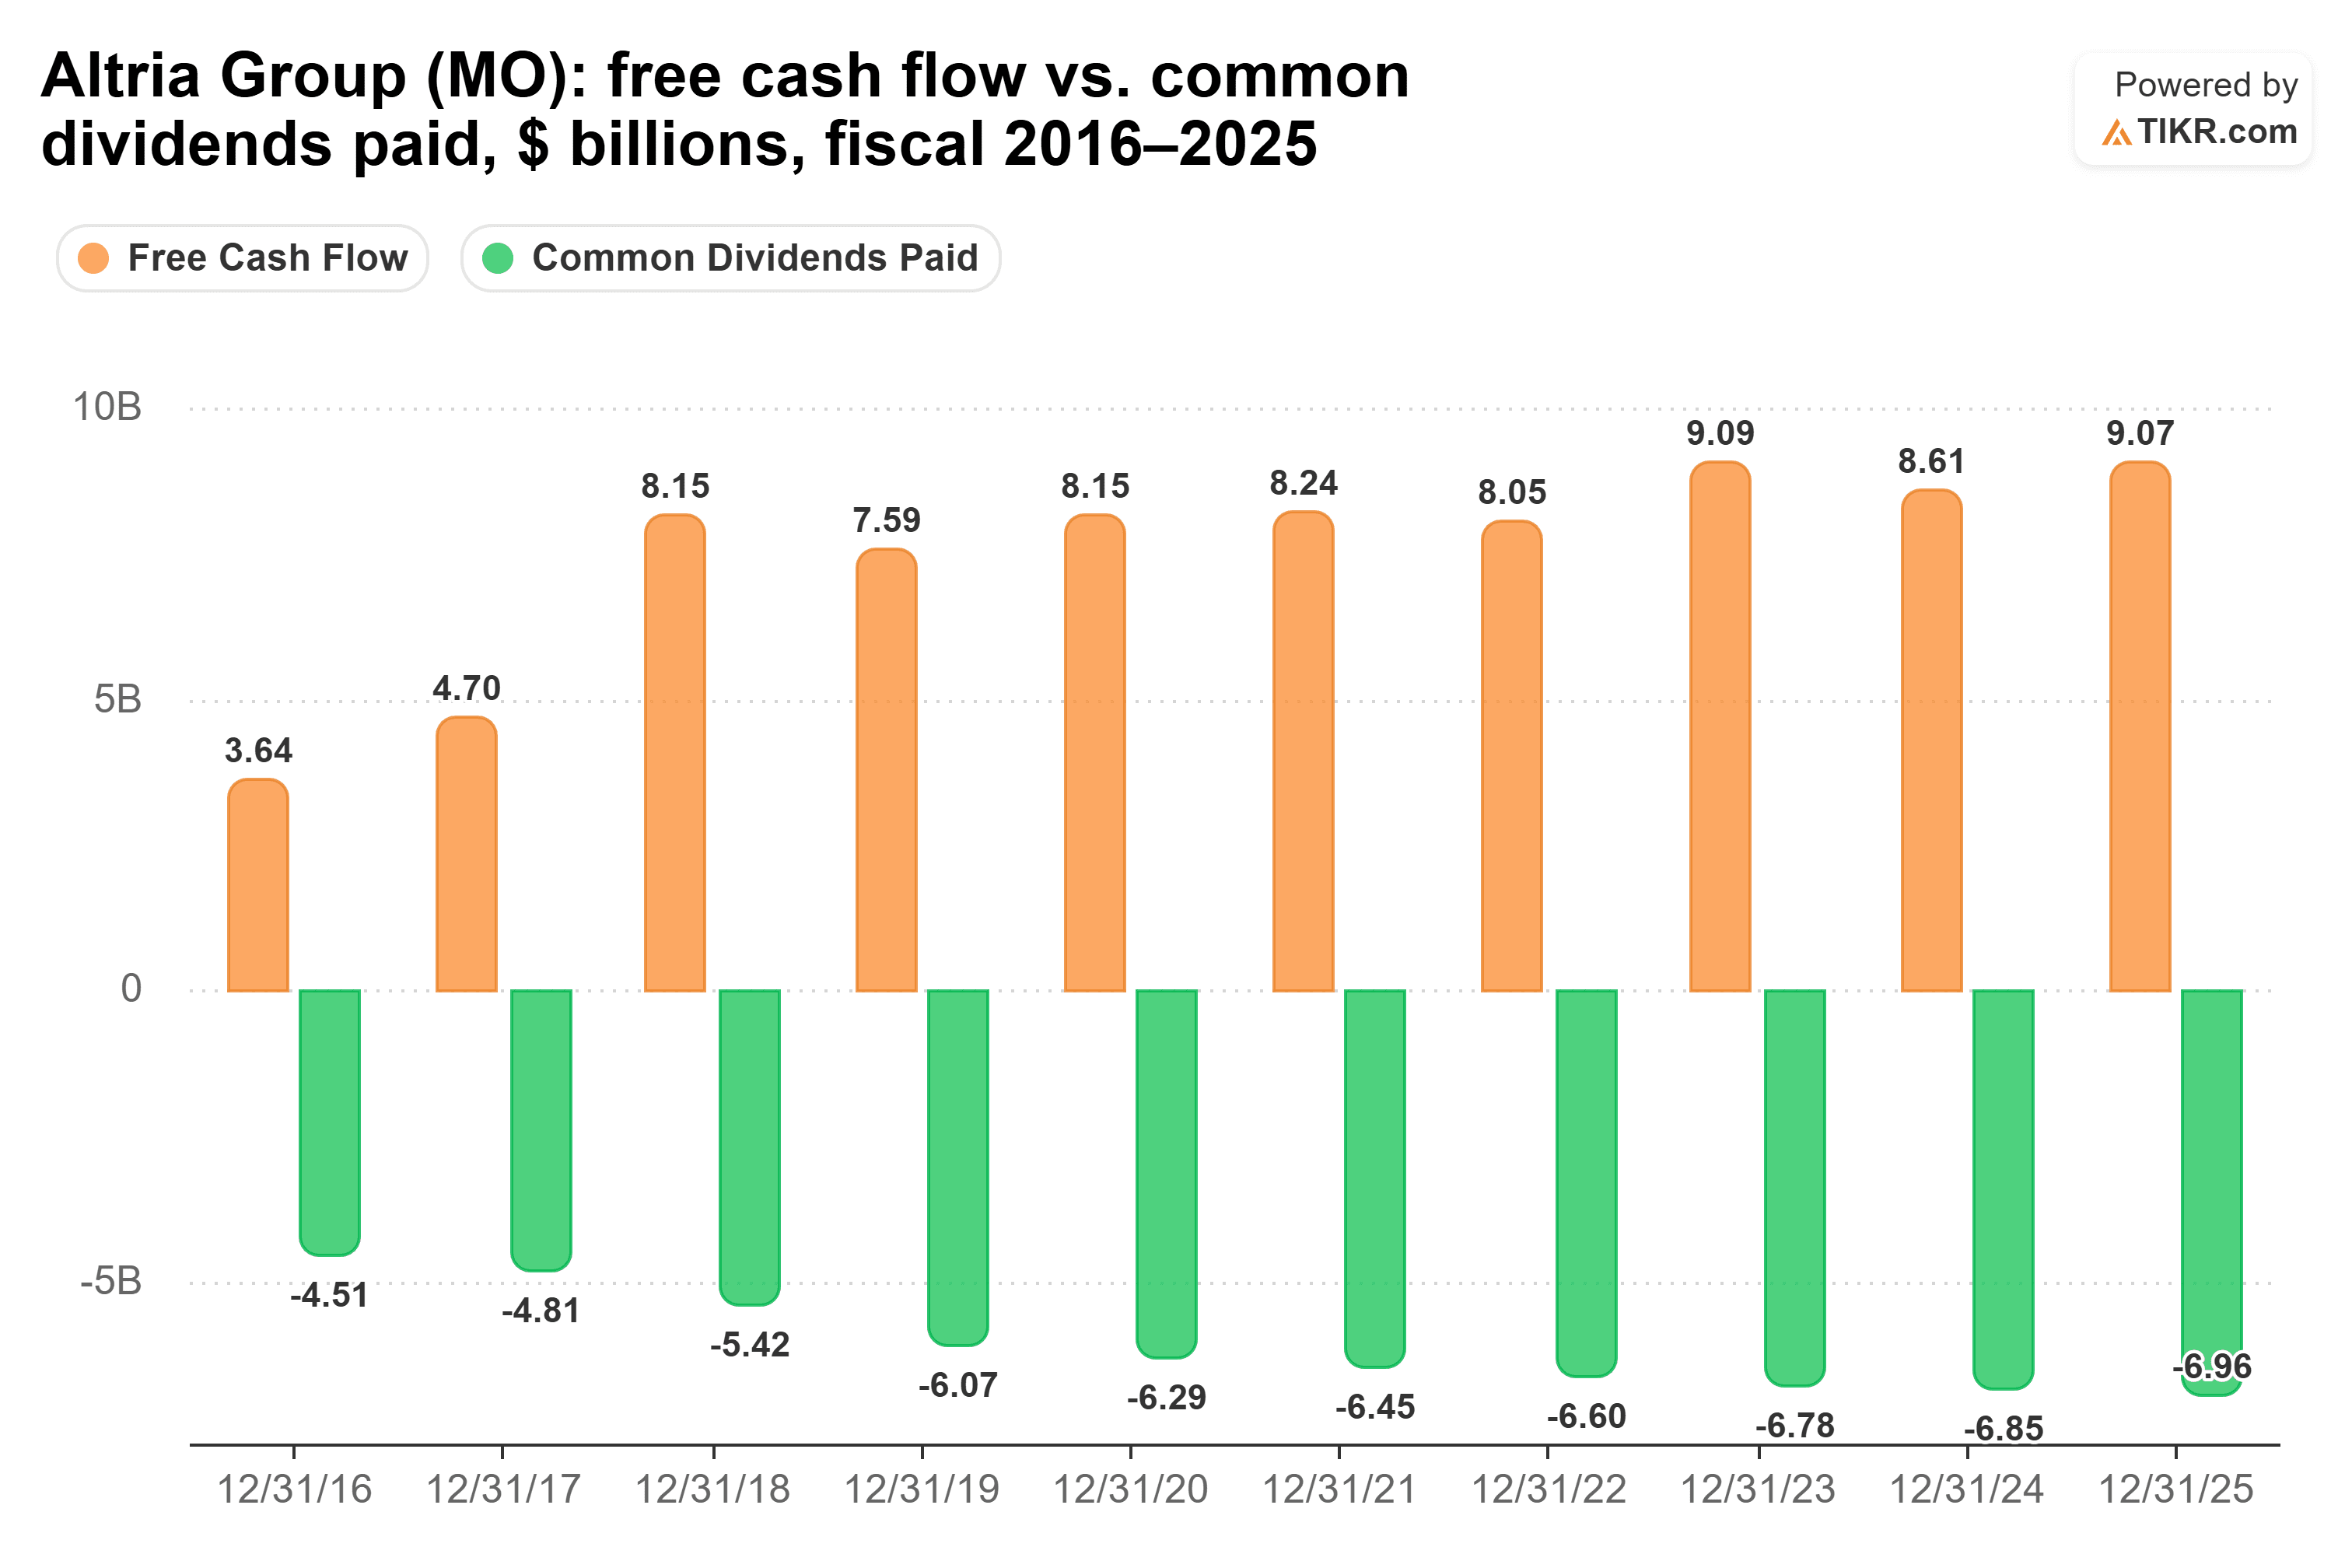
Its cash dividend payout ratio held between 74.6% and 82.0% from fiscal 2021 to fiscal 2025. Over the twelve months to Sept. 30, 2026, it was 78%: $7.12 billion of dividends against $9.07 billion of free cash flow. That’s steady coverage, with room for the raises it targets.
So which dividend wins?
PepsiCo is the better dividend stock, as long as you can wait for its income to catch up.
Coverage is about even today, so I’m deciding on the business behind each dividend.
The catch is the wait. $10,000 in PepsiCo pays $430 a year now, against $580 from Altria. At each one’s 5-year rate, PepsiCo’s income would reach about $786 in year 10, a 7.9% yield on the $10,000, and pass Altria’s around 2038.
And of course, there’s capital appreciation to consider. PepsiCo trades at 17x forward earnings, well below its five-year average of 21x and not far above its low of 14x on Oct. 7, 2026:
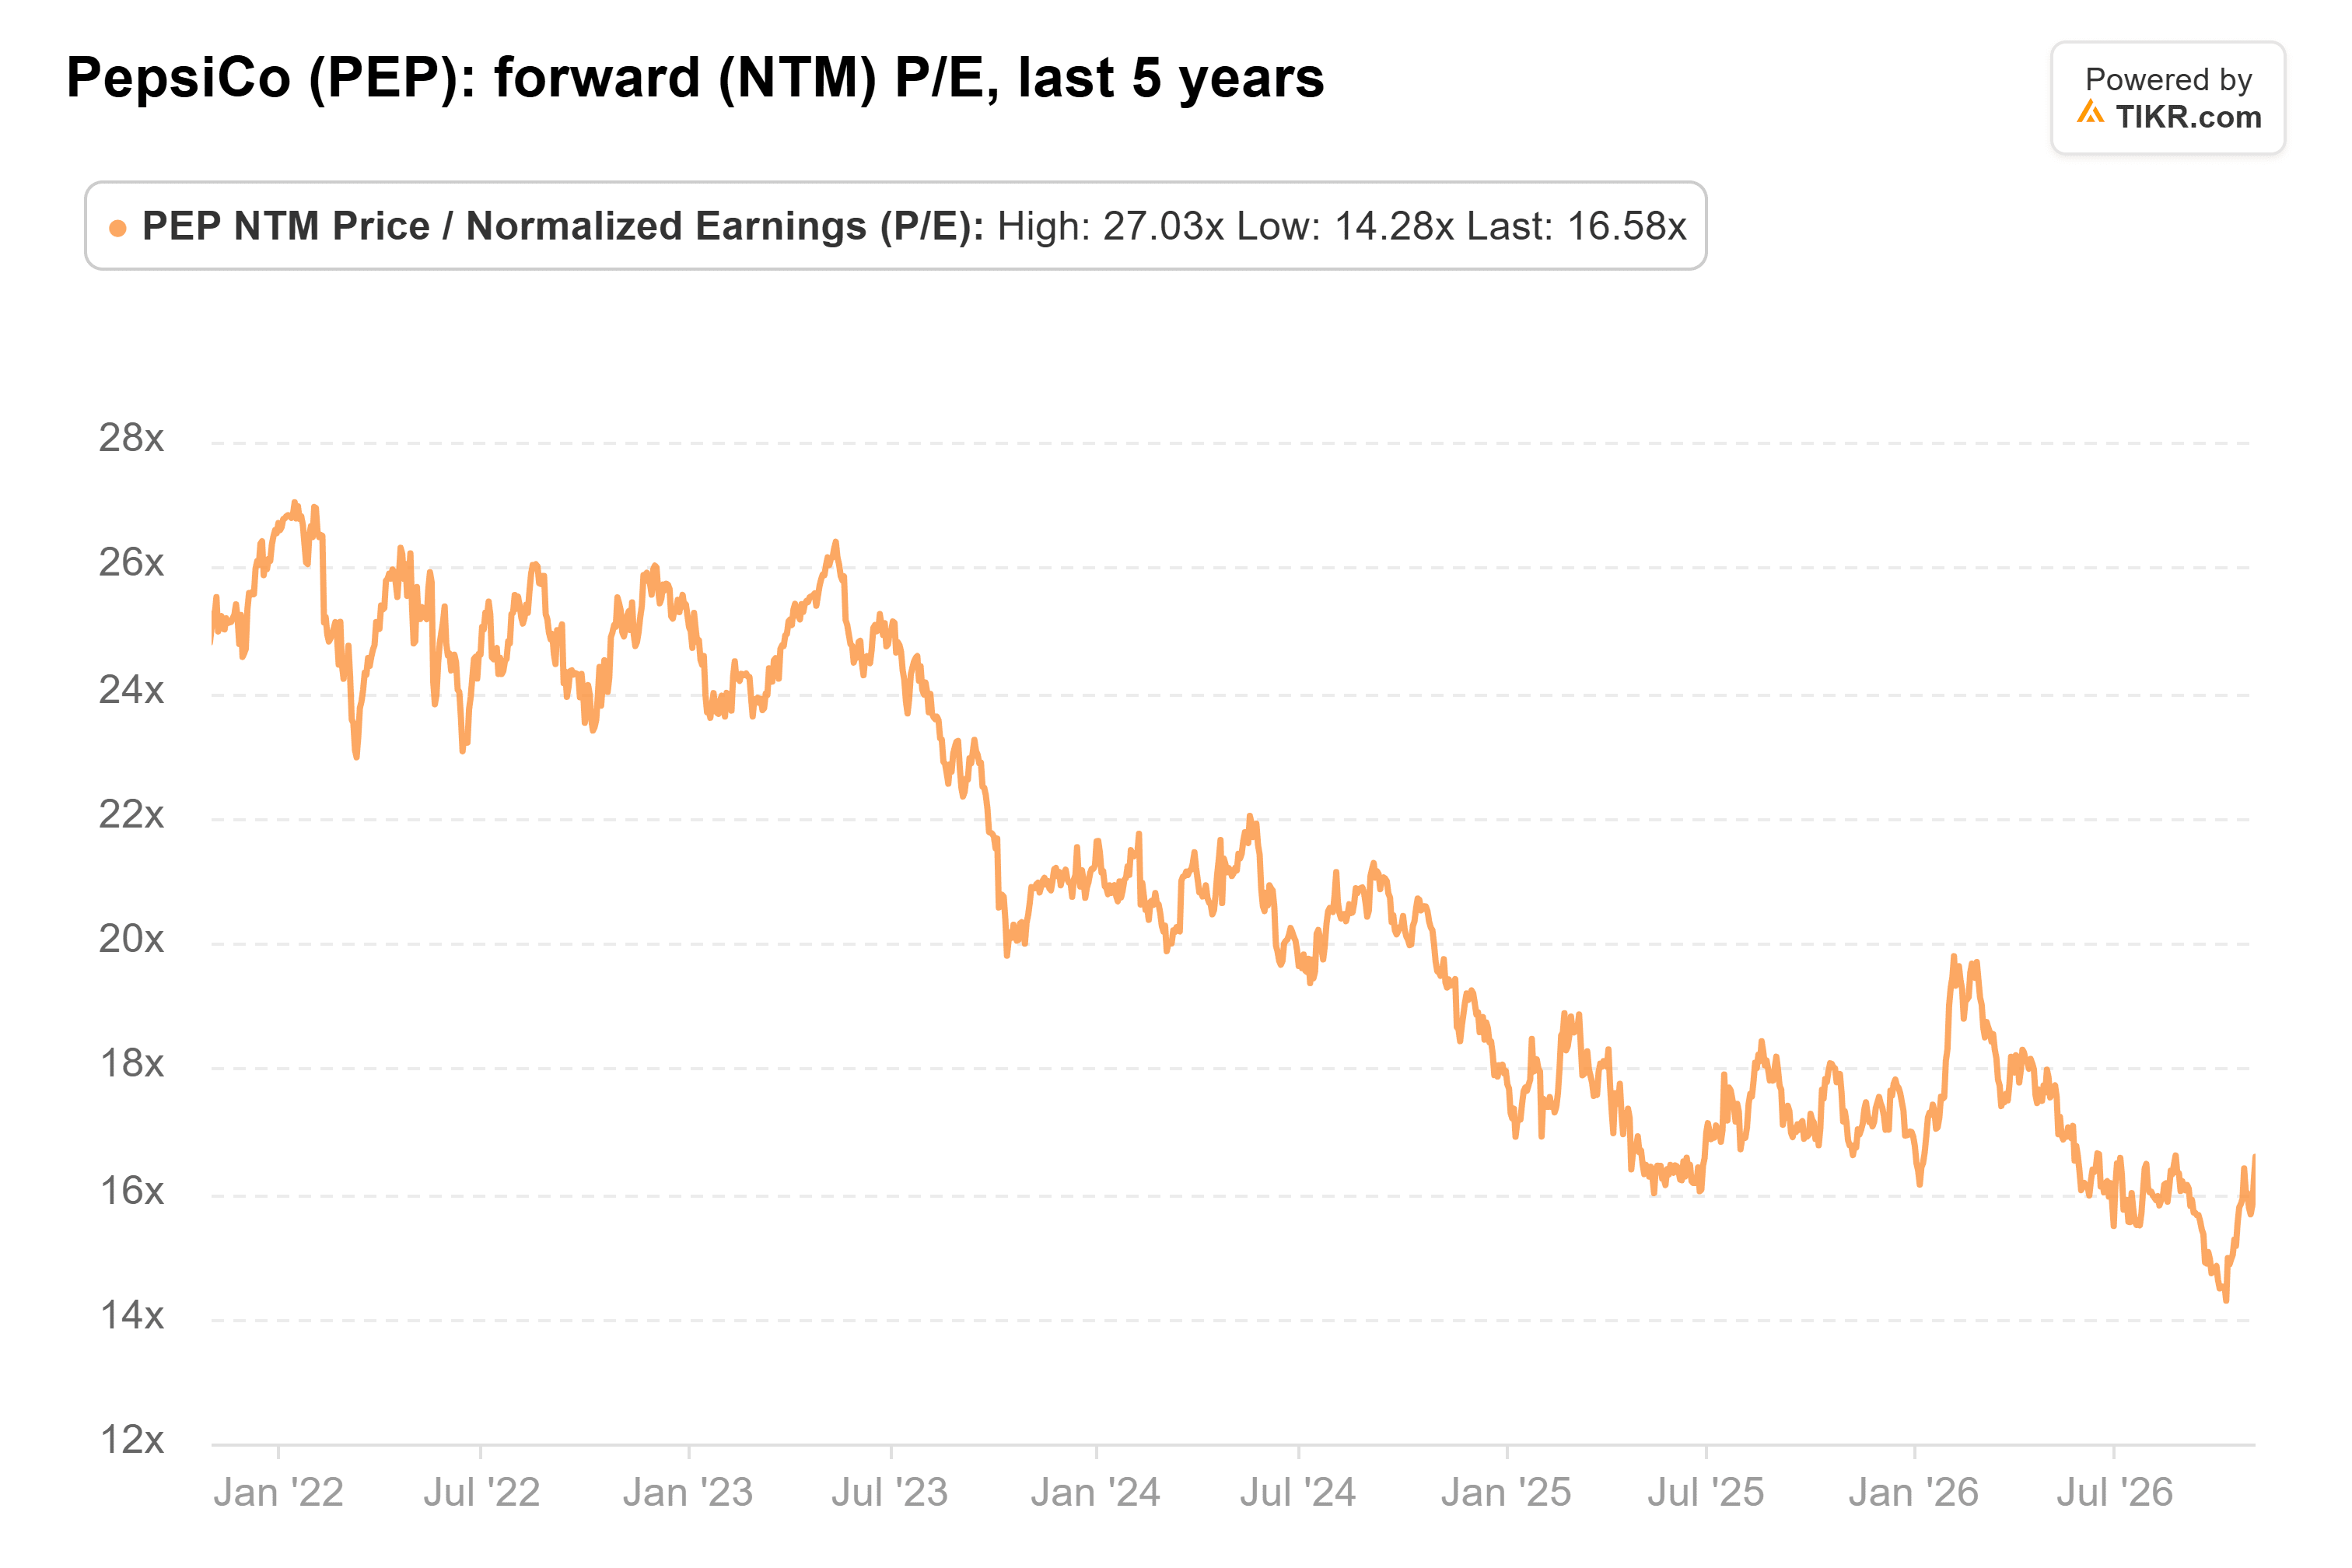
My read: the market has already priced in the guidance cut.
Altria’s dividend looks safe. It pays more today, and it would still pay more in year 10, about $834. But a dividend growing more slowly from a shrinking cigarette business is harder to count on than a faster-growing one from a business that’s still adding sales. That’s what tips it to PepsiCo.
Of course, PepsiCo still has to make its cost cuts work while input costs rise. Its next report will show whether the recovery in free cash flow holds.
Forget PepsiCo: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And PepsiCo isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!