AT&T (T) shares fell about 5% before the bell on October 21, even after the company beat on third-quarter earnings and lifted its 2026 adjusted EPS outlook to “the $2.40 range,” up from $2.25 to $2.35.
That drop erased roughly $8 billion of market value, close to the $10 billion AT&T plans to spend on buybacks this year (a plan it set in July). Postpaid phone additions roughly matched forecasts but slowed from the second quarter, and the stock was already under pressure from SpaceX’s push into U.S. wireless.
AT&T’s Quarter Beat Where It Counts
Adjusted EPS came in at $0.65, up from $0.54 a year ago and ahead of the $0.60 consensus estimate, according to the third-quarter release. Revenue rose 5.3% to $32.3 billion, and AT&T added a record 769,000 internet customers, including 442,000 on fiber.
Free cash flow reached $5.0 billion, and the $18 billion-plus full-year target held. GAAP EPS from continuing operations fell to $0.13 from $1.29, but both quarters carried one-offs: a $0.41 Mexico impairment this year and a $0.79 gain on the DIRECTV sale a year ago.
The Street Is Still Behind AT&T’s Guidance
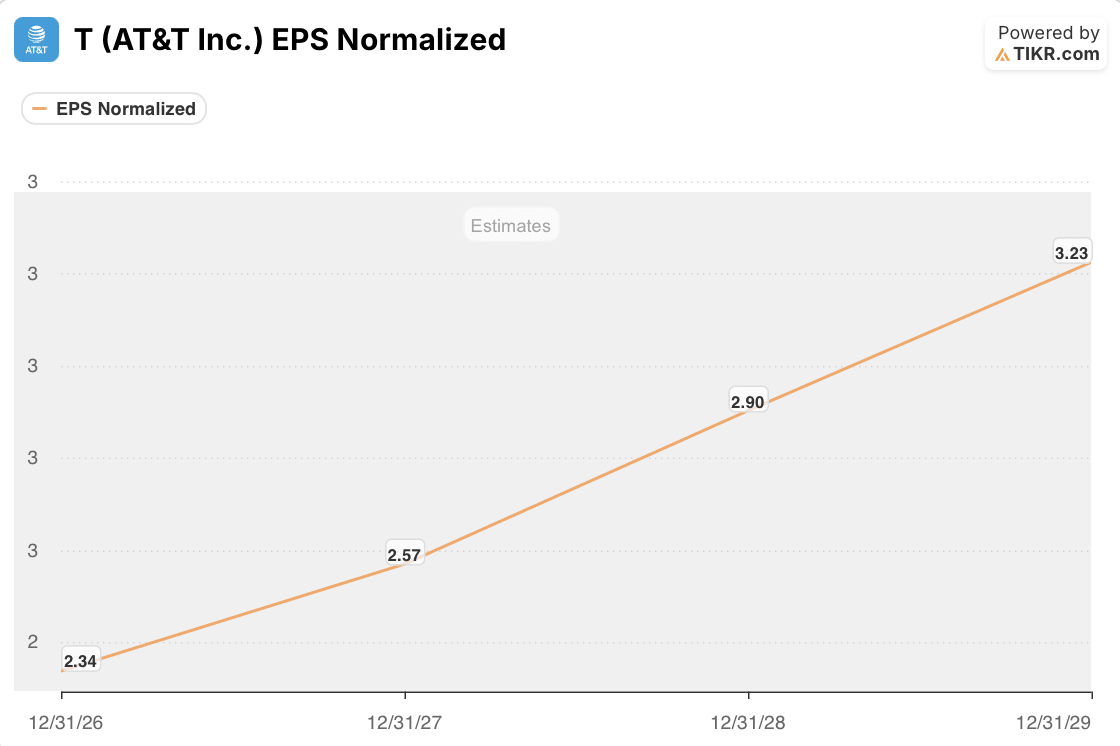
Wall Street expects $2.34 of normalized EPS this year, about 2.6% below the new $2.40 guide, so estimates have room to move up. The path after that climbs to $2.90 in 2028 and $3.23 in 2029.
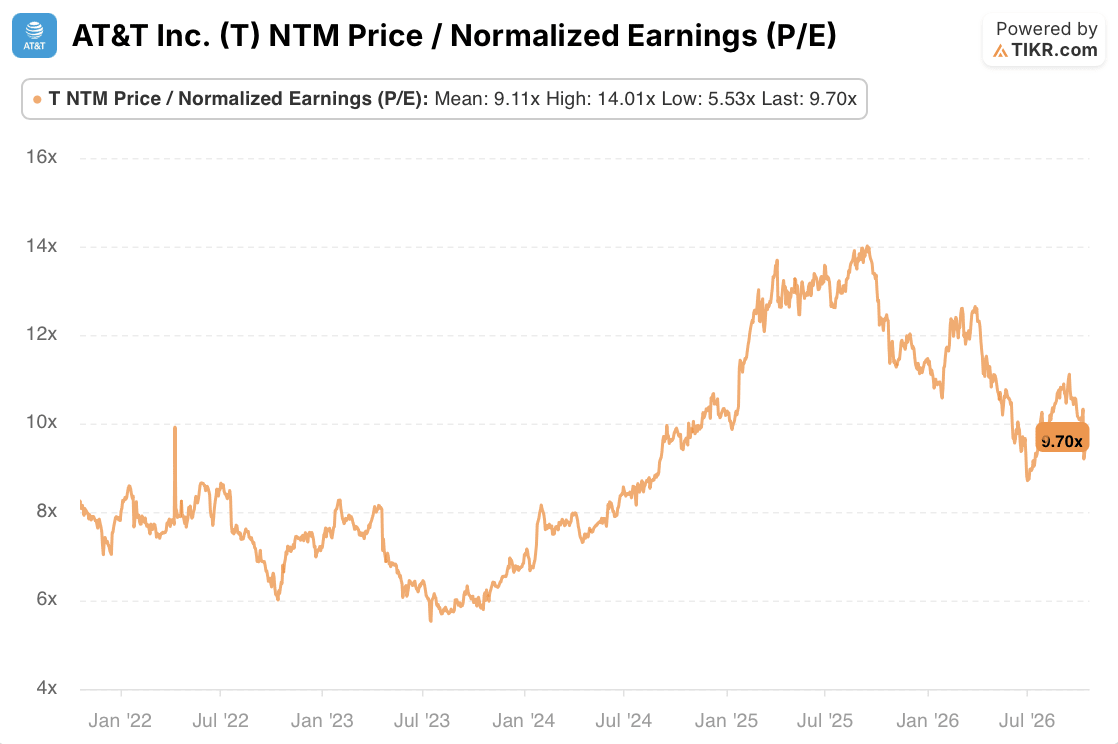
The multiple tells a less flattering story. AT&T trades at 9.70x NTM earnings, a bit above its five-year average of 9.11x and well off the 14.01x it reached in 2025. The stock isn’t a bargain by its own history. Investors have simply stopped paying a premium for the growth plan.
TIKR Tracks 25 Analysts on AT&T. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AT&T, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AT&T’s Analyst Ratings
The Wireless Number Behind the Drop
AT&T added 379,000 postpaid phone subscribers, roughly in line with estimates but down from 432,000 in the second quarter. Postpaid phone churn rose to 0.92% from 0.86%.
The release also said promotional discounts on new subscribers partly offset wireless service revenue, which still grew 5.0%, while advertising and bad-debt expenses rose with subscriber growth. That doesn’t prove each customer costs more to win, but slower adds and higher churn in the same quarter are worth watching. It’s also the second time this year AT&T stock fell after a beat, and SpaceX’s Starlink Mobile spectrum deal knocked about 6.6% off the shares before the open on October 9.
The Dates AT&T Holders Should Circle
Verizon (VZ) reports its third quarter on Monday, October 26, and T-Mobile (TMUS) follows on October 28. Both will show whether the slowdown AT&T reported is spreading across the industry or staying at AT&T.
If Verizon and T-Mobile report the same slowdown, the drop looks like a sector repricing, with SpaceX hanging over all three, that a 9.70x multiple and a $10 billion buyback can absorb. If they hold churn steady while AT&T’s rises, AT&T has a competitive problem of its own. I’d watch Verizon’s postpaid phone churn first, since it’s the cleanest read on whether customers are leaving the big carriers.
So what is AT&T stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what T stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!