Key Takeaways
- Richard Fearon, a CRH director, bought $569,700 of stock on Nov. 6, with shares 26% below their January high.
- The stock has slid as a 40% jump in diesel and weaker housing led CRH to cut its 2026 guidance, a squeeze its CEO calls temporary.
- Analysts have cut their 2026 and 2027 earnings estimates by about 9% in three months, and their consensus price target has dropped to $121 from $144 in June.
- Fearon paid about 17x forward earnings, close to the stock’s one-year average. That’s a fair price for a business analysts expect to earn more in 2027 than it did in 2025.
CRH (CRH) shares are 26% below their January high, and one of the company’s directors just put more of his own money in.
Richard Fearon bought 6,000 shares on Nov. 6 at an average $94.95, or $569,700 in all, according to a Form 4 filed Nov. 10. The stock now trades at $97.46. That’s 3% above what he paid, and the stock is down 14% over the past year.
Diesel and housing did the damage
In June, CRH agreed to buy Arcosa for about $8.5 billion, mostly with borrowed money. Then costs jumped. CEO Jim Mintern said on the third-quarter call that diesel rose 40% from its July low and pulled haulage costs up with it, while US housing softened further.
All of that showed up in the Oct. 29 report. Revenue rose 3% to $11.4 billion, but adjusted EBITDA was flat at $2.7 billion. CRH also cut its 2026 adjusted EBITDA outlook to $7.8 billion-$8.0 billion, from $8.1 billion-$8.5 billion.
Mintern called the cost squeeze “in effect, a temporary timing issue” and said “we expect a positive price/cost spread and a return to margin expansion in ’27.” Housing will take longer: he doesn’t see a recovery there “probably until mid-2028 at best.”
TIKR tracks 23 analysts on CRH. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CRH, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CRH’s Analyst Ratings
A small add to a big stake
Fearon has been on CRH’s board since 2020, and he’s a former vice chairman and CFO of Eaton. His open-market purchase raises his holding by 4%, to 150,842 shares. At the price he paid, that stake is worth about $14.3 million, so the new shares add only a little to a bet he’d already made. Still, as Peter Lynch liked to point out, insiders sell for all sorts of reasons but buy for only one. That’s why it pays to track the stocks insiders are buying.
Does $95 add up?
Analysts expect normalized EPS to dip this year, then rebound:
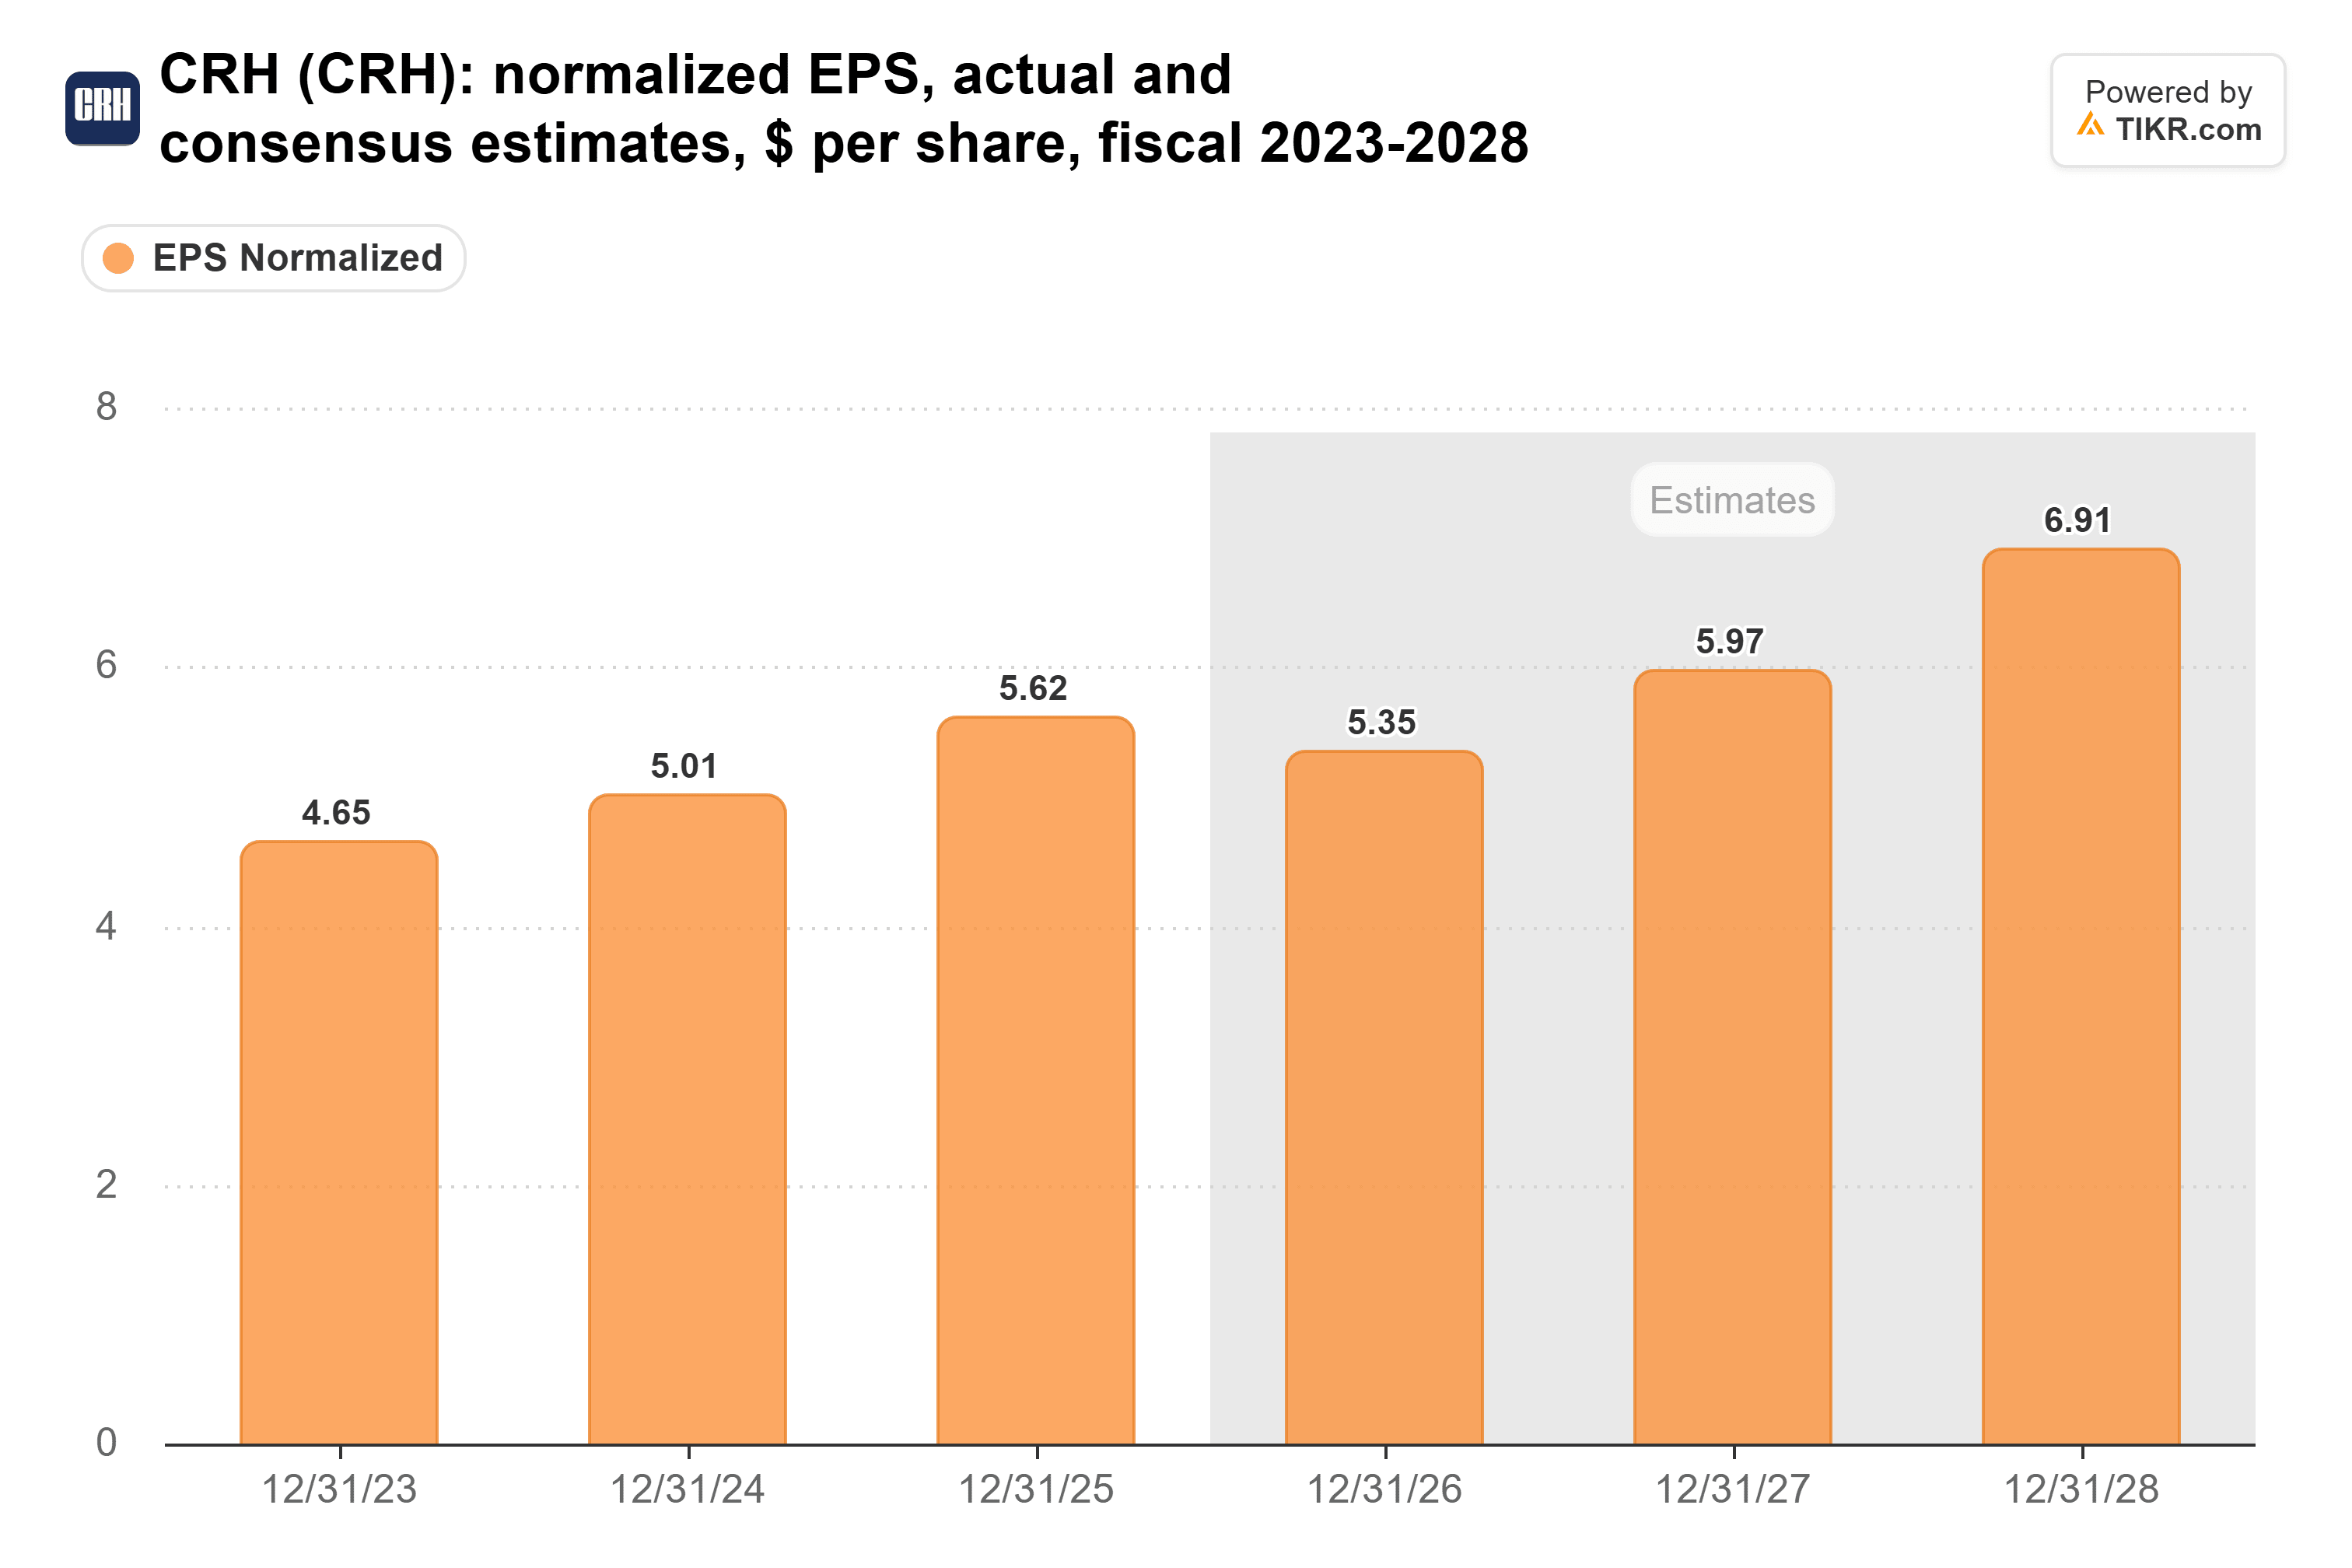
Consensus calls for $5.35 a share in 2026, down from $5.62 in 2025, then $5.97 in 2027. Those estimates are still falling, though: 2026’s was $5.89 three months ago, and 2027’s has come down about as much.
The multiple sits right around its average for the past year:
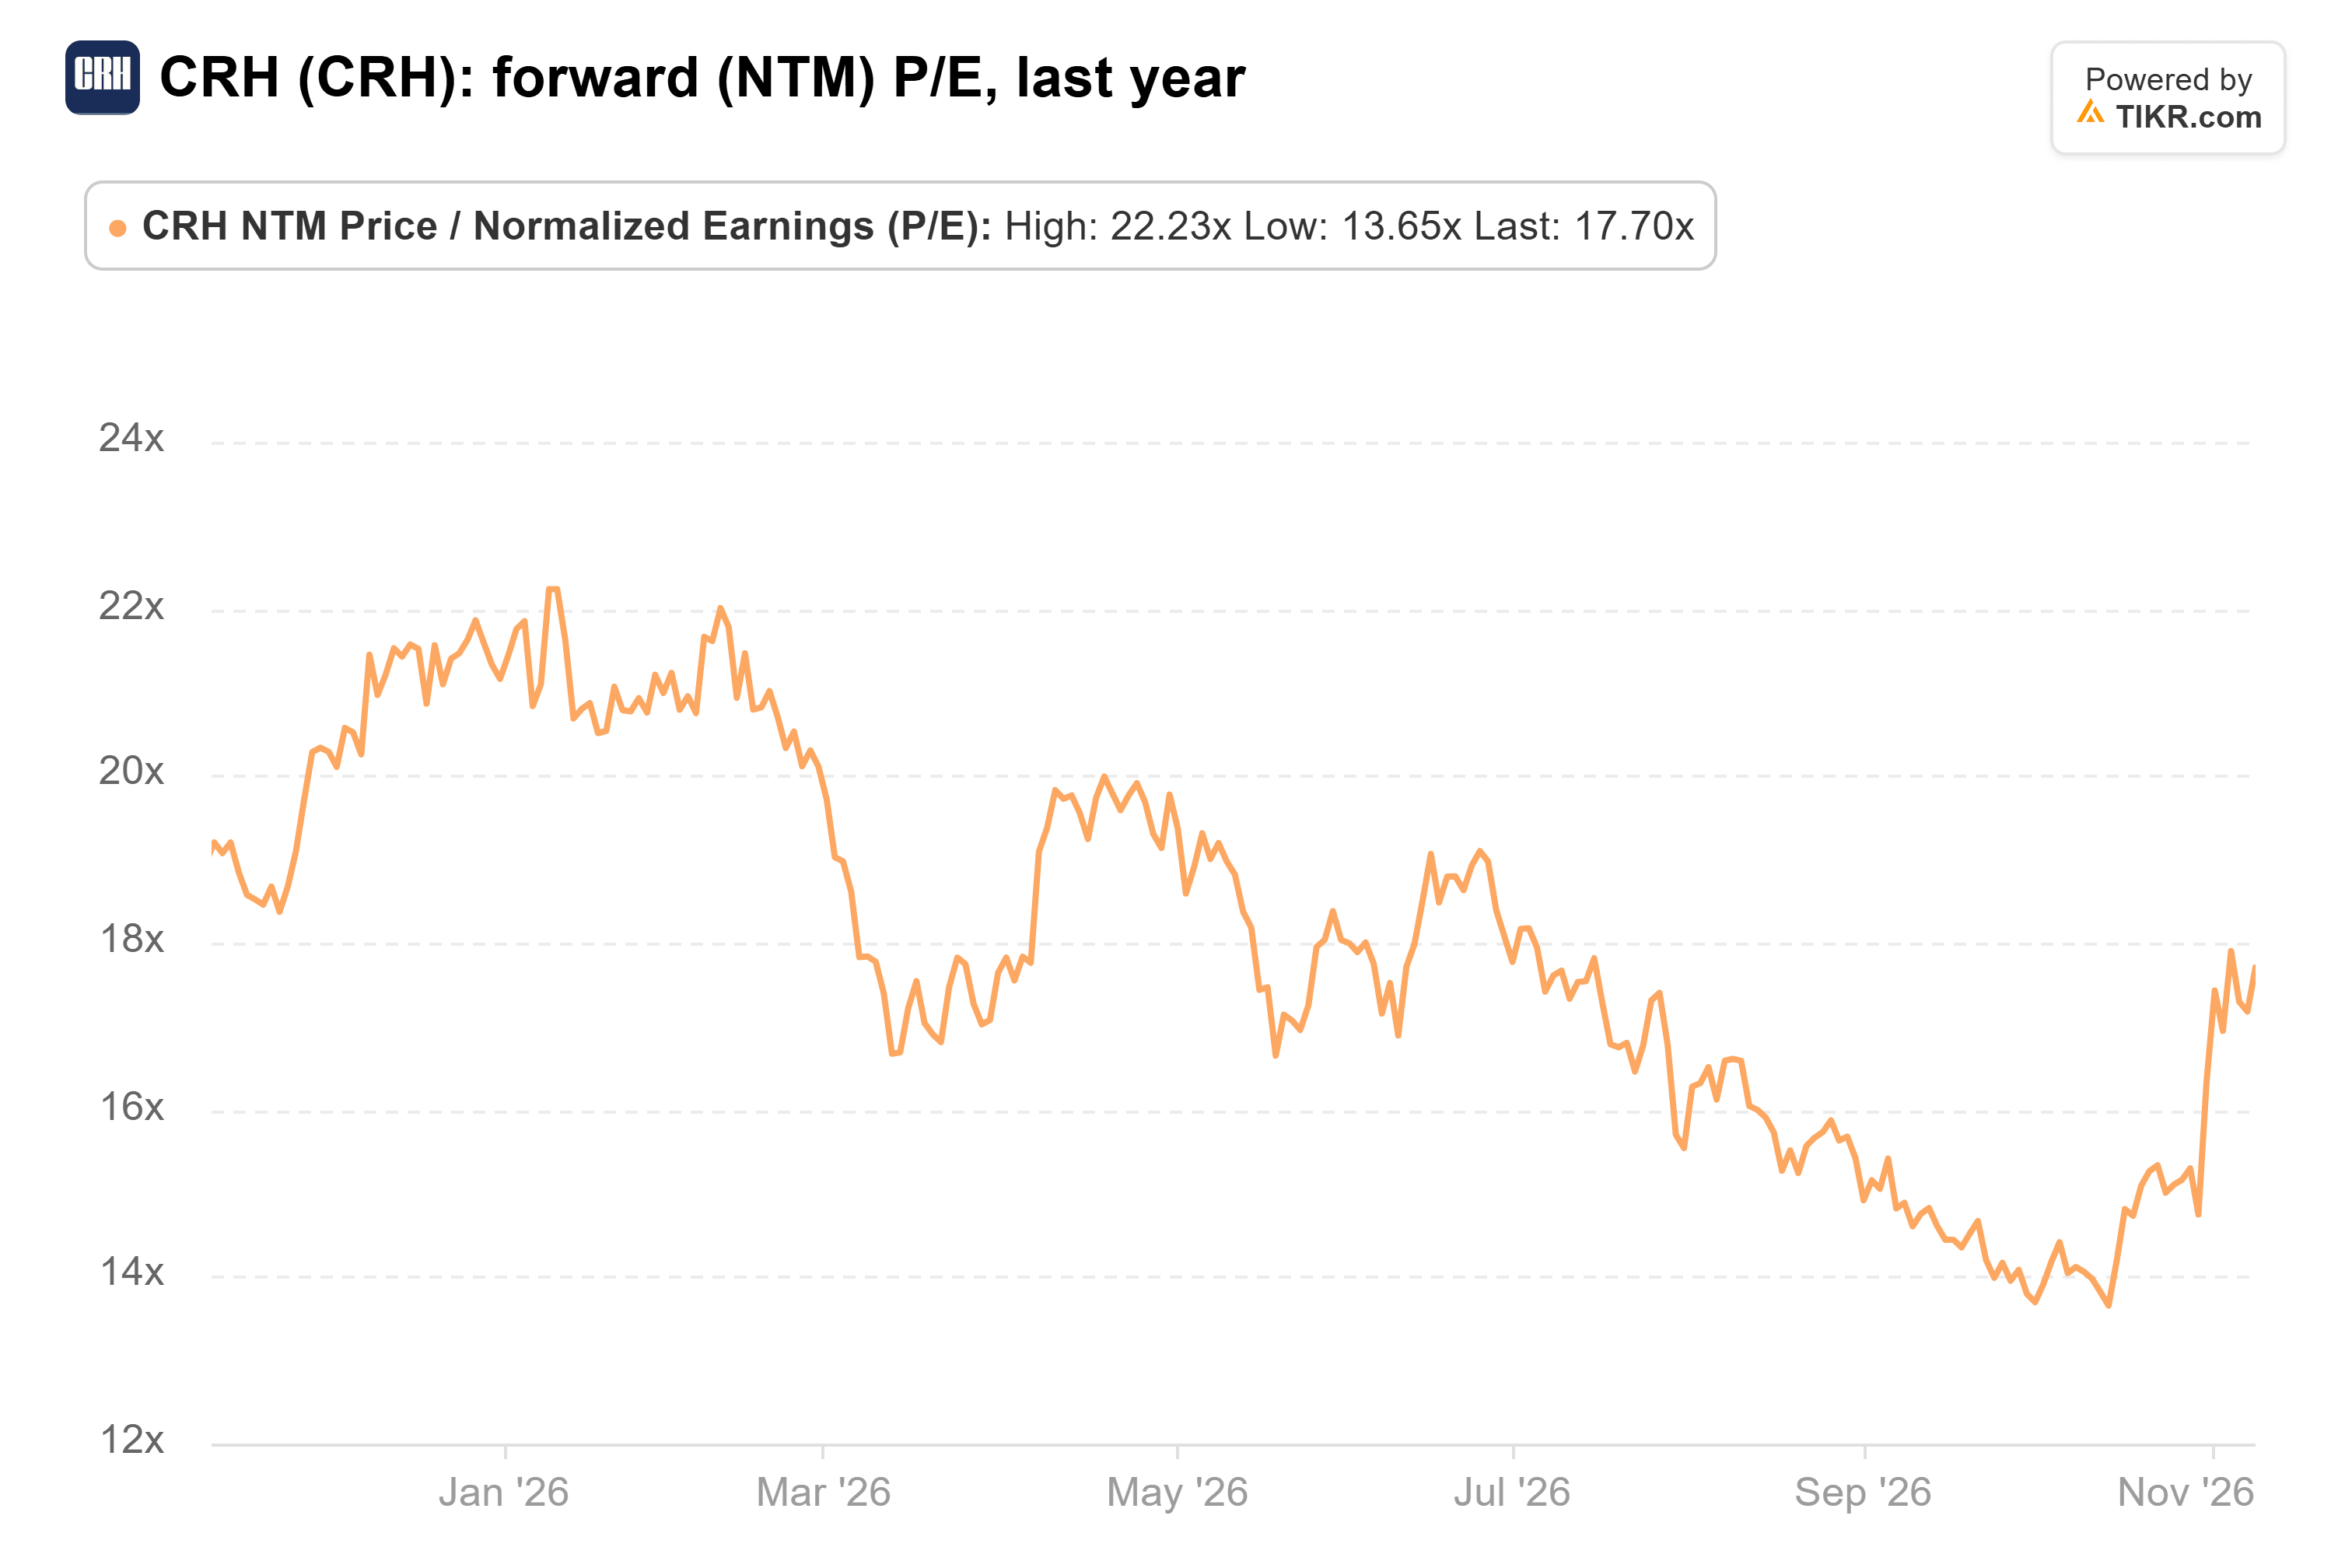
CRH trades at [18x] forward earnings. Its one-year average is 18x, and it reached 22x in January. Fearon paid about 17x, which is more than October’s low of 14x.
The Street’s targets have come down with the estimates:

The consensus target is $121, down from a $144 peak in late June, but still 24% above the current price. The lowest target on the Street is $95, about what Fearon paid.
He paid a fair price for a 2027 rebound
The main risk is debt. Net debt was $15.0 billion at Sept. 30, before the Arcosa deal closed, and CFO Aylwyn Bryan expects leverage to come back down toward about 2x over time.
Bottom line: the numbers back Fearon’s buy. He paid about the stock’s usual multiple for a business analysts expect to earn more in 2027 than it did in 2025. Management has more on the way, too, from $175 million of Arcosa cost synergies by year three to a new $6 billion buyback through 2030.
More estimate cuts would change that. CRH’s fourth-quarter report early next year is the next test of Mintern’s call for wider margins in 2027. Of course, one director adding 4% to his stake is a vote of confidence, and only that.
So what is CRH stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CRH could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!