Key Takeaways
- The Trade Desk fell 2% after third-quarter revenue of $736 million beat its own outlook but slipped 0.5% from a year earlier.
- The beat had one-time help, and profits shrank.
- Amazon’s ad sales kept growing, and a deeper Netflix integration helps, but The Trade Desk needs revenue growth back before the drop looks like a bottom.
The Trade Desk (TTD) beat its own outlook after Monday’s close, and the stock is down 2% this morning anyway.
CEO Jeff Green said in the release that the company is “still operating below the level of growth we expect from ourselves.”
He’s right. Revenue slipped while rival Amazon (AMZN) kept growing its ad sales, though a deeper tie-up with Netflix (NFLX) gives The Trade Desk something new to work with.
The beat had help
Revenue of $736 million cleared August’s floor of at least $650 million, but CFO Nate Olmstead said on the call that about three percentage points of growth came from a one-time partner benefit. Without it, revenue would have fallen about 3.5%. Net income dropped to $38 million from $116 million.
The fourth-quarter guide of at least $755 million is still about 11% below last year’s $847 million. Analysts went into the report expecting revenue to fall through 2027.
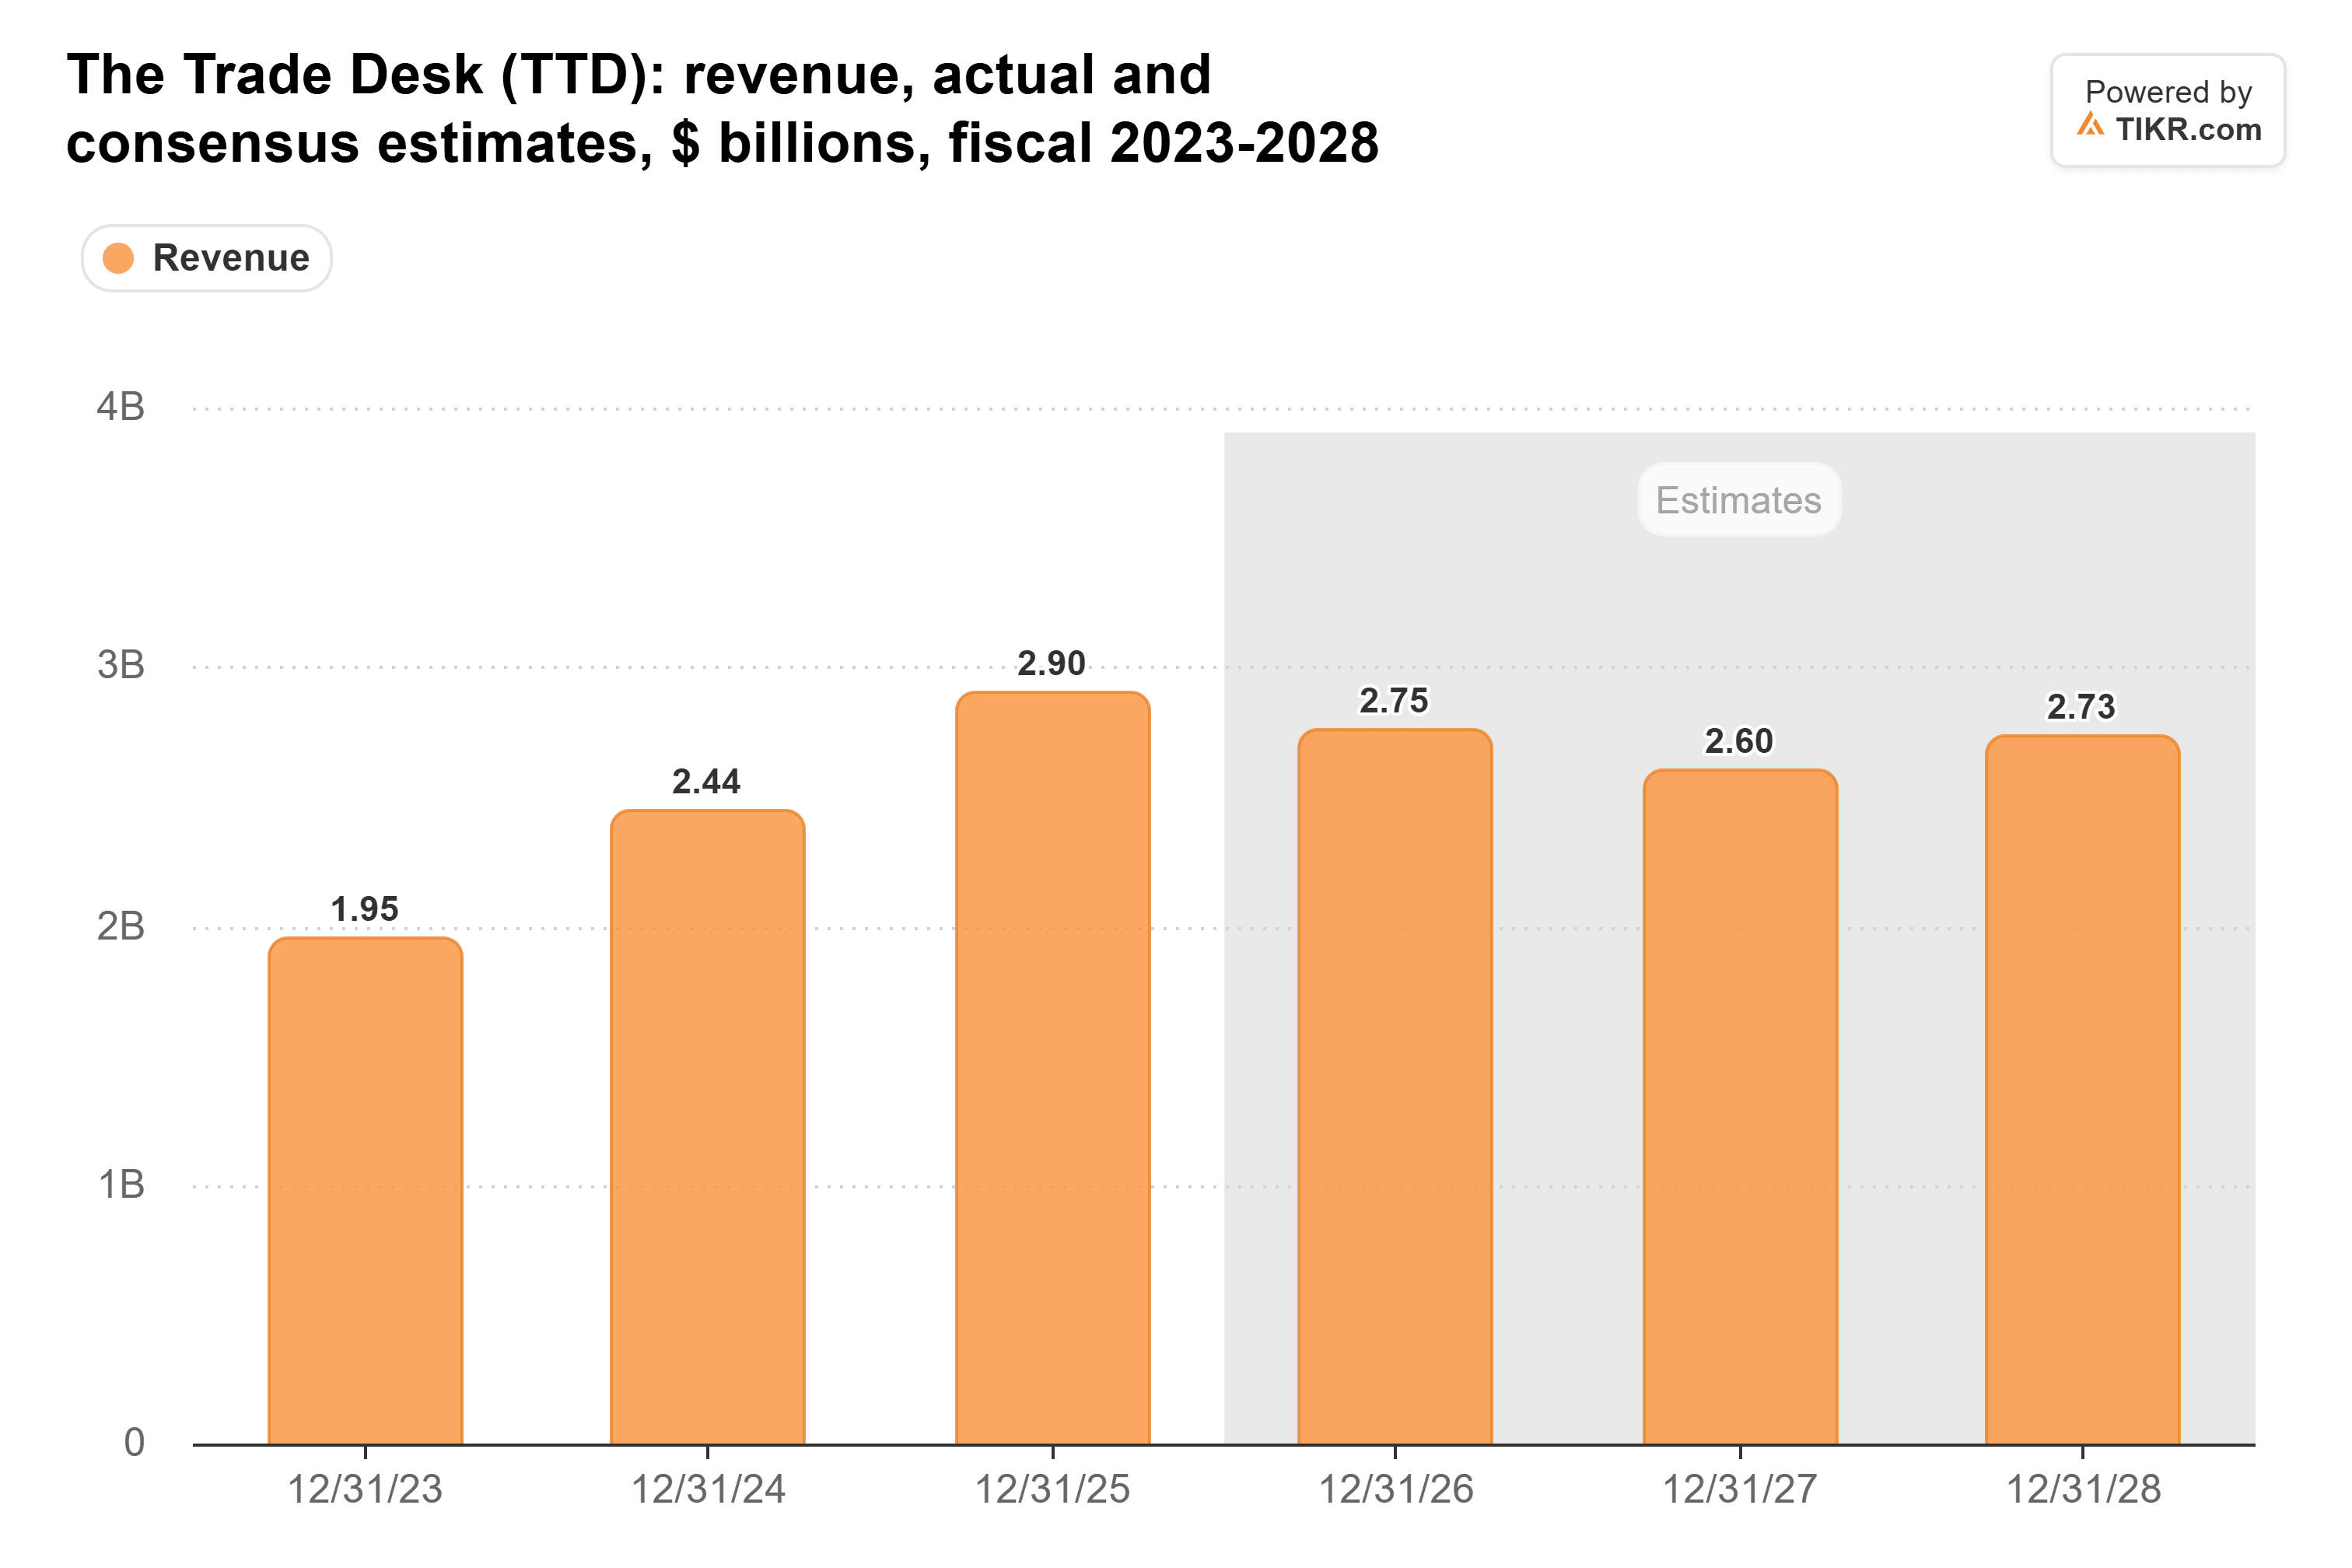
The guide puts 2026 at about 2025’s $2.9 billion, so this year’s estimate should rise. Next year’s estimate matters more.
TIKR tracks 36 analysts on The Trade Desk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on The Trade Desk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See The Trade Desk’s Analyst Ratings
Rivals are still growing
Amazon’s advertising revenue rose 12% excluding currency in the third quarter, to $19.6 billion, and Amazon expects growth in the high teens in the fourth. If Amazon hits that guide while The Trade Desk shrinks 11%, investors will have a hard time blaming the ad market.
Netflix is the brighter spot. Starting this month, advertisers can target Netflix audiences with first- and third-party data through The Trade Desk’s Kokai platform. Netflix needs the help: in its Oct. 20 shareholder letter, it cut its 2026 ad revenue forecast to about $2.7 billion from about $3 billion, citing a “slightly slower than expected rollout of some ad product capabilities.” Its January report should show whether partners like The Trade Desk help close that gap.
Cheap for a reason
The stock traded at 16x forward earnings at Monday’s close. That’s far below its five-year average of 49x but nearly double its July low of 8.6x.
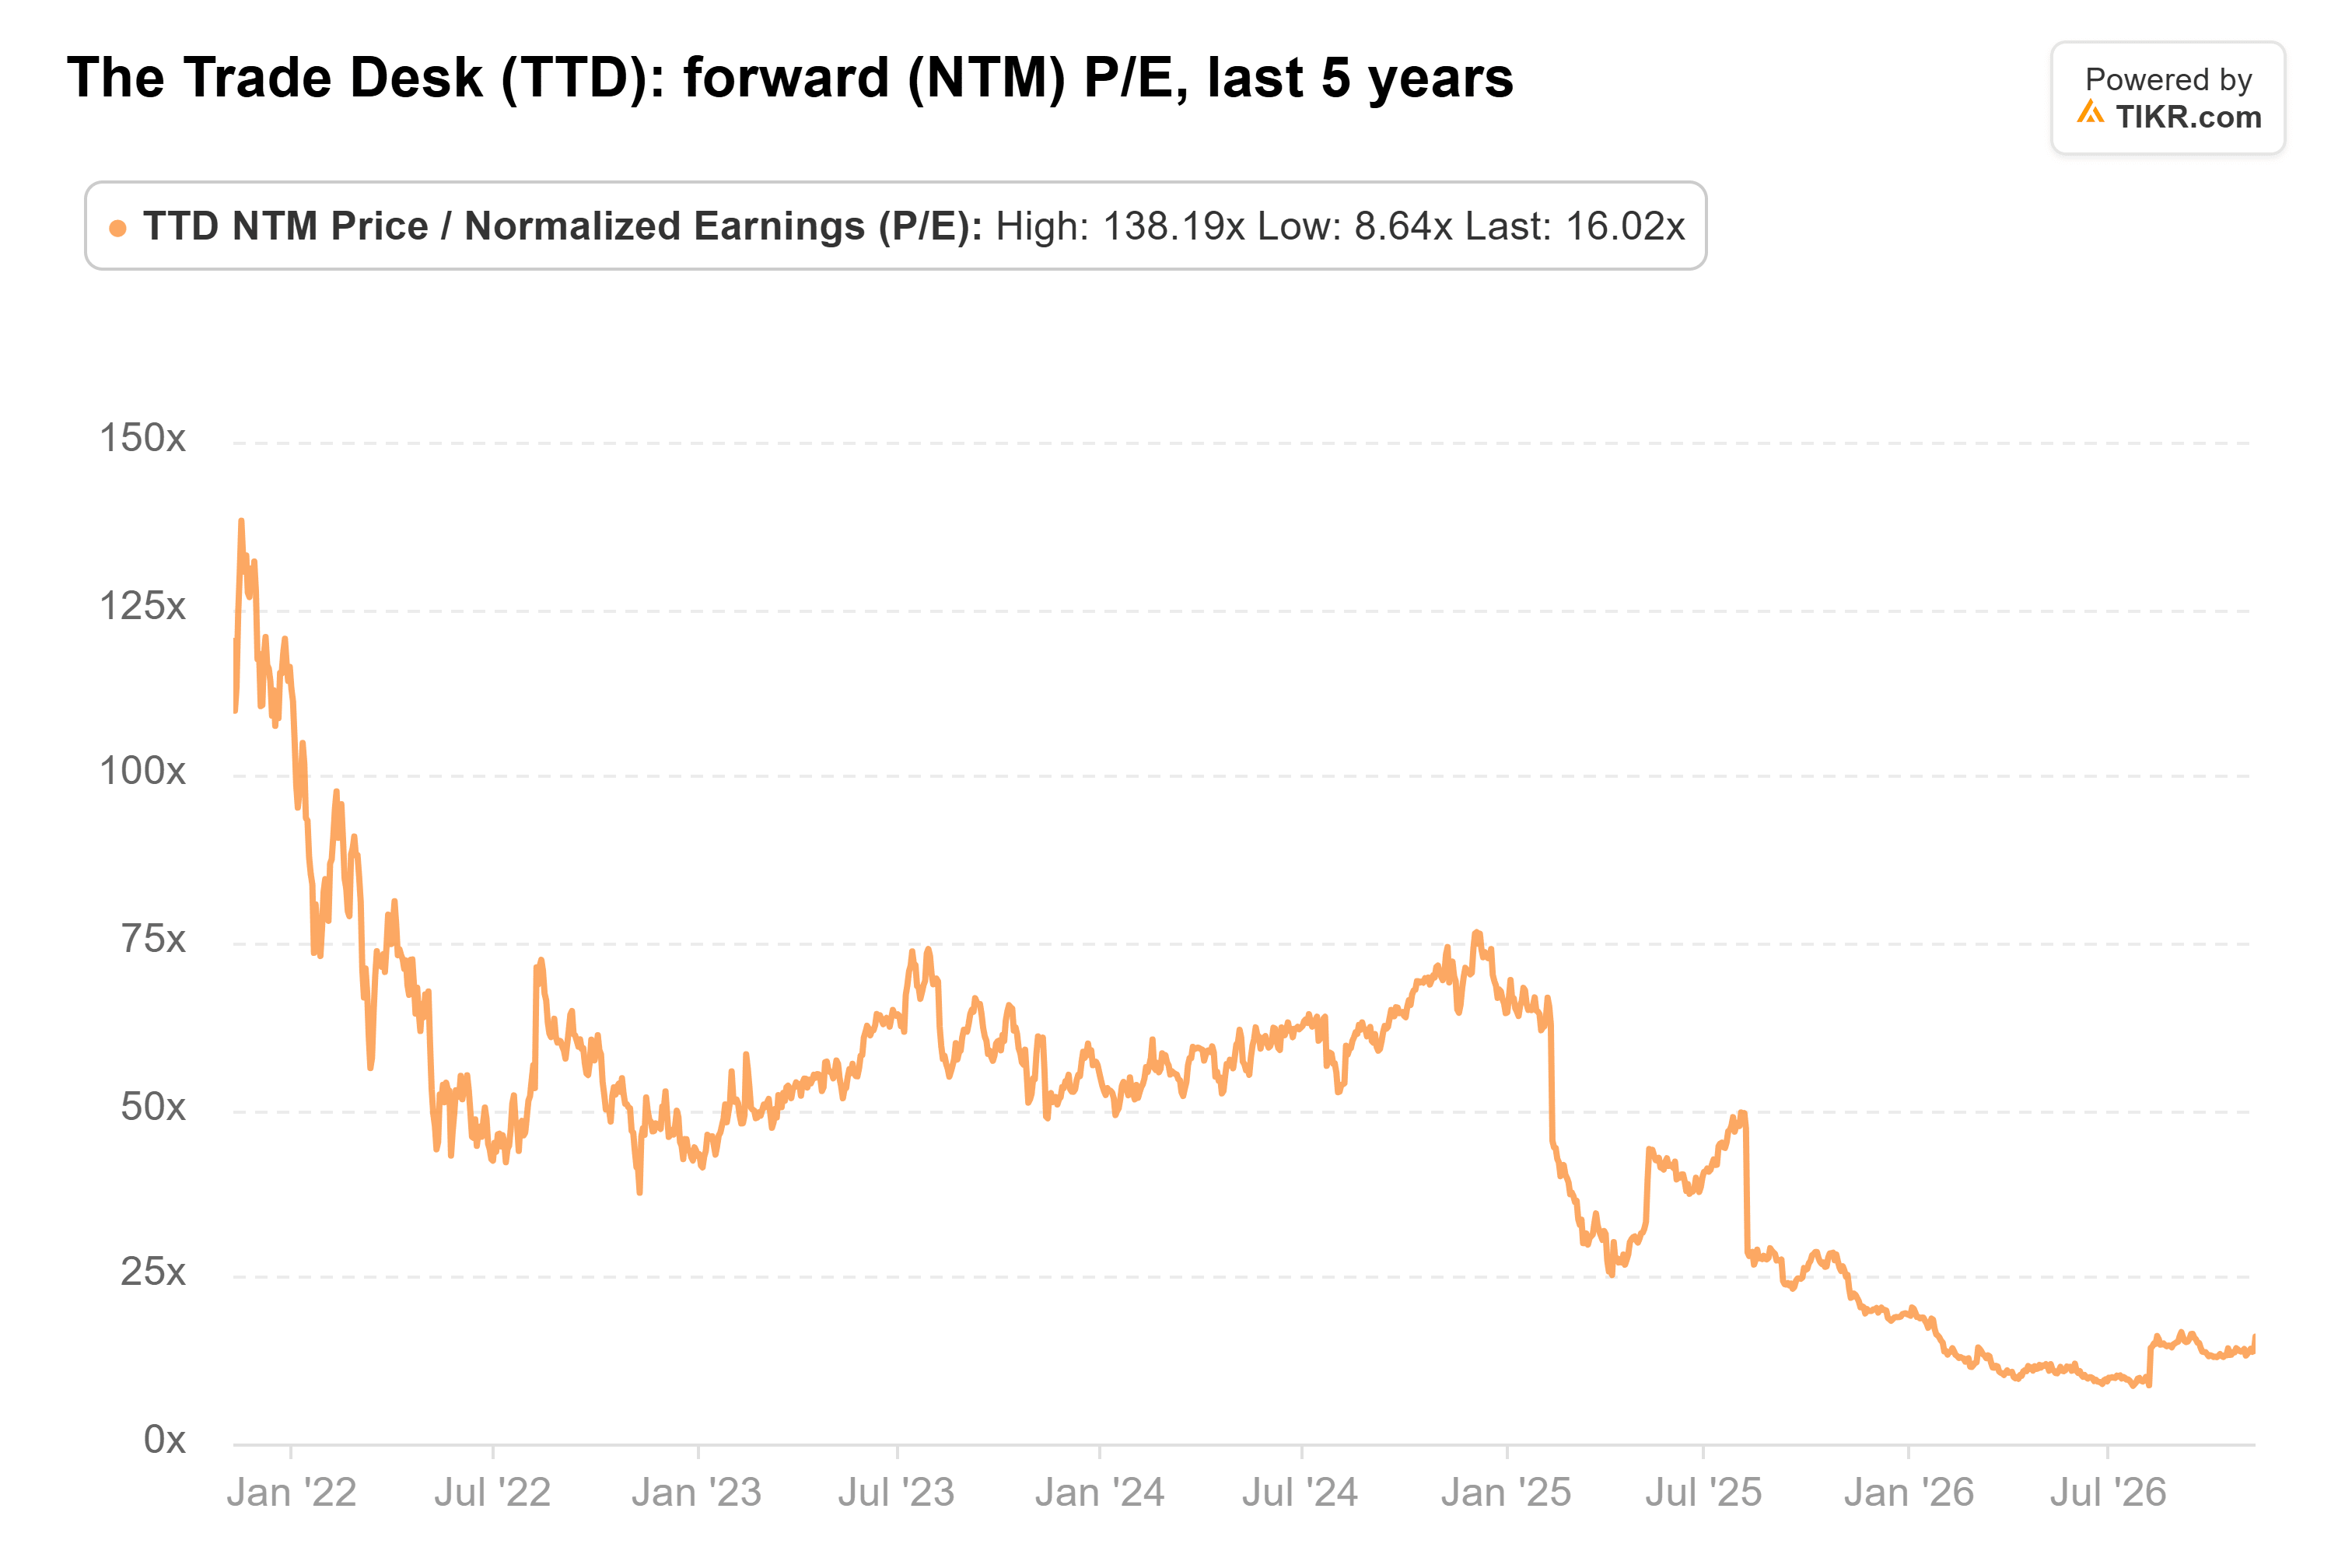
Today’s drop looks fair to me. The quarter beat a low bar, and revenue is still shrinking. I’d wait for the February report, when the Netflix integration and September’s cost cuts have had a full quarter to show up, before calling this the bottom.
So what is The Trade Desk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what The Trade Desk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!