Key Takeaways
- Foxhaven Asset Management, which manages $6.5 billion, added to Affirm and Shopify and opened a new stake in Meta Platforms in the third quarter.
- All three stocks have fallen since Sept. 30: Affirm and Meta by 18% and Shopify by 11%.
- Each one trades below its usual forward multiple, and analysts’ average targets sit 34% to 68% above the latest close.
- Meta has the strongest case of the three: 26% revenue growth at a below-average multiple, with AI spending as the main risk.
Foxhaven Asset Management isn’t a name most investors know. But its 13F for the quarter ended Sept. 30, filed Nov. 16, shows the firm, which manages $6.5 billion, loading up on three stocks they do know: Affirm (AFRM), Shopify (SHOP) and Meta Platforms (META).
Those were its three biggest new or added positions, out of $3.64 billion of US stocks in the filing. And all three have dropped since. (That’s each stock’s price change from Sept. 30. A 13F doesn’t show what Foxhaven paid or when it bought.)
Affirm’s growth is holding up
By Sept. 30, Foxhaven held 2.29 million Affirm shares, 49% more than a quarter earlier. They were worth $158 million, or 4.4% of its 13F stocks. The stock is down 18% since then and sits 37% below its 52-week high.
Gross merchandise volume rose 34% in the September quarter, and CEO Max Levchin calls 30%-plus growth the floor. The worry is credit. On monthly loans, 30-day-plus delinquencies reached 2.9%, up from 2.8% a year earlier. Since Affirm’s Nov. 5 report, RBC Capital has cut its target to $83 from $96, Cantor Fitzgerald to $84 from $97 and Truist to $86 from $88.
Even so, the $95 consensus target from 36 analysts is 68% above the latest close, and it’s barely changed in a year:
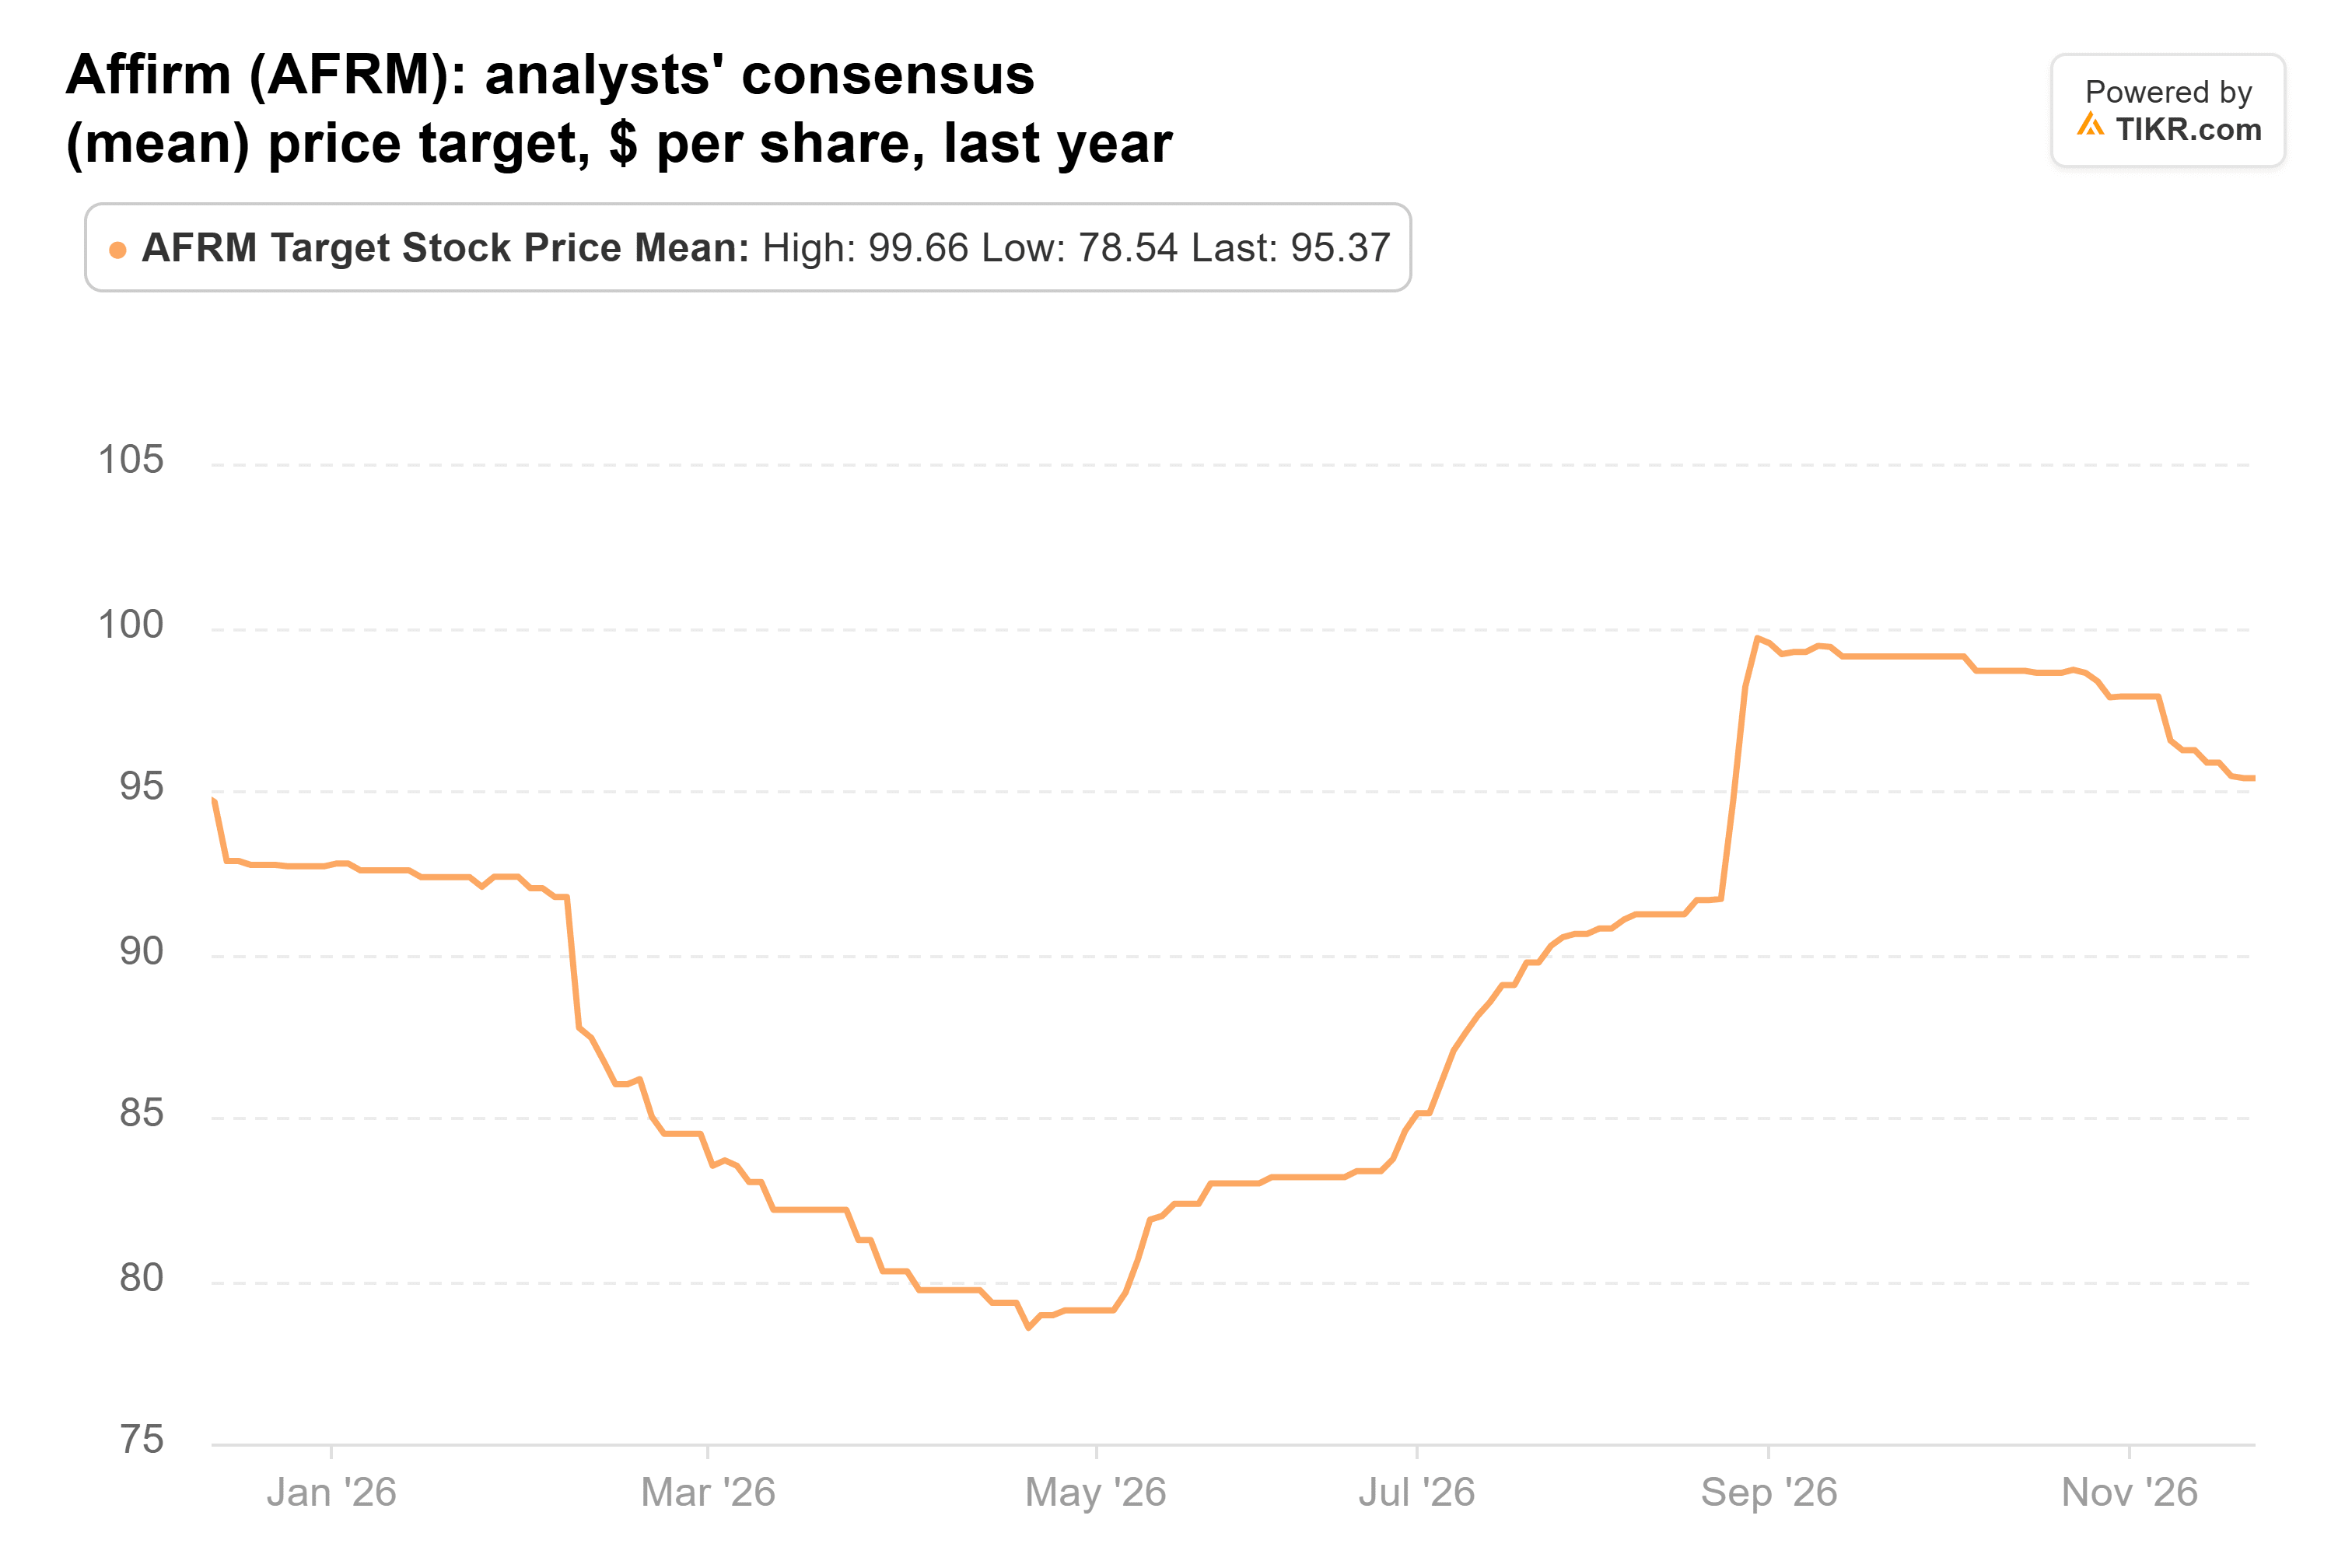
At about 25x forward earnings, Affirm trades below its 28x average since its forward P/E turned positive in September 2024.
TIKR tracks 36 analysts on Affirm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Affirm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Affirm’s Analyst Ratings
Shopify went from a sliver to a real stake
Shopify ties straight back to Affirm, which runs Shop Pay Installments. Shopify also owned $1.7 billion of Affirm stock at June 30. Foxhaven’s Shopify stake grew more than elevenfold in the quarter, to 1.03 million shares worth $153 million, or 4.2% of its 13F stocks.
The stock is down 11% since Sept. 30, after a third-quarter report in which gross merchandise volume and subscription gross profit fell short of estimates. But AI-driven orders to Shopify stores rose 3.3x from a year earlier, and President Harley Finkelstein called the quarter “the first time we saw shoppers experimenting with delegated purchasing through personal agents.” Meta’s Muse is one of the agents Shopify partners with, so merchants’ checkouts and Shop Pay work inside it.
Analysts are sticking with it. The $177 consensus target from 54 analysts is 34% above the latest close and a touch higher than a year ago:
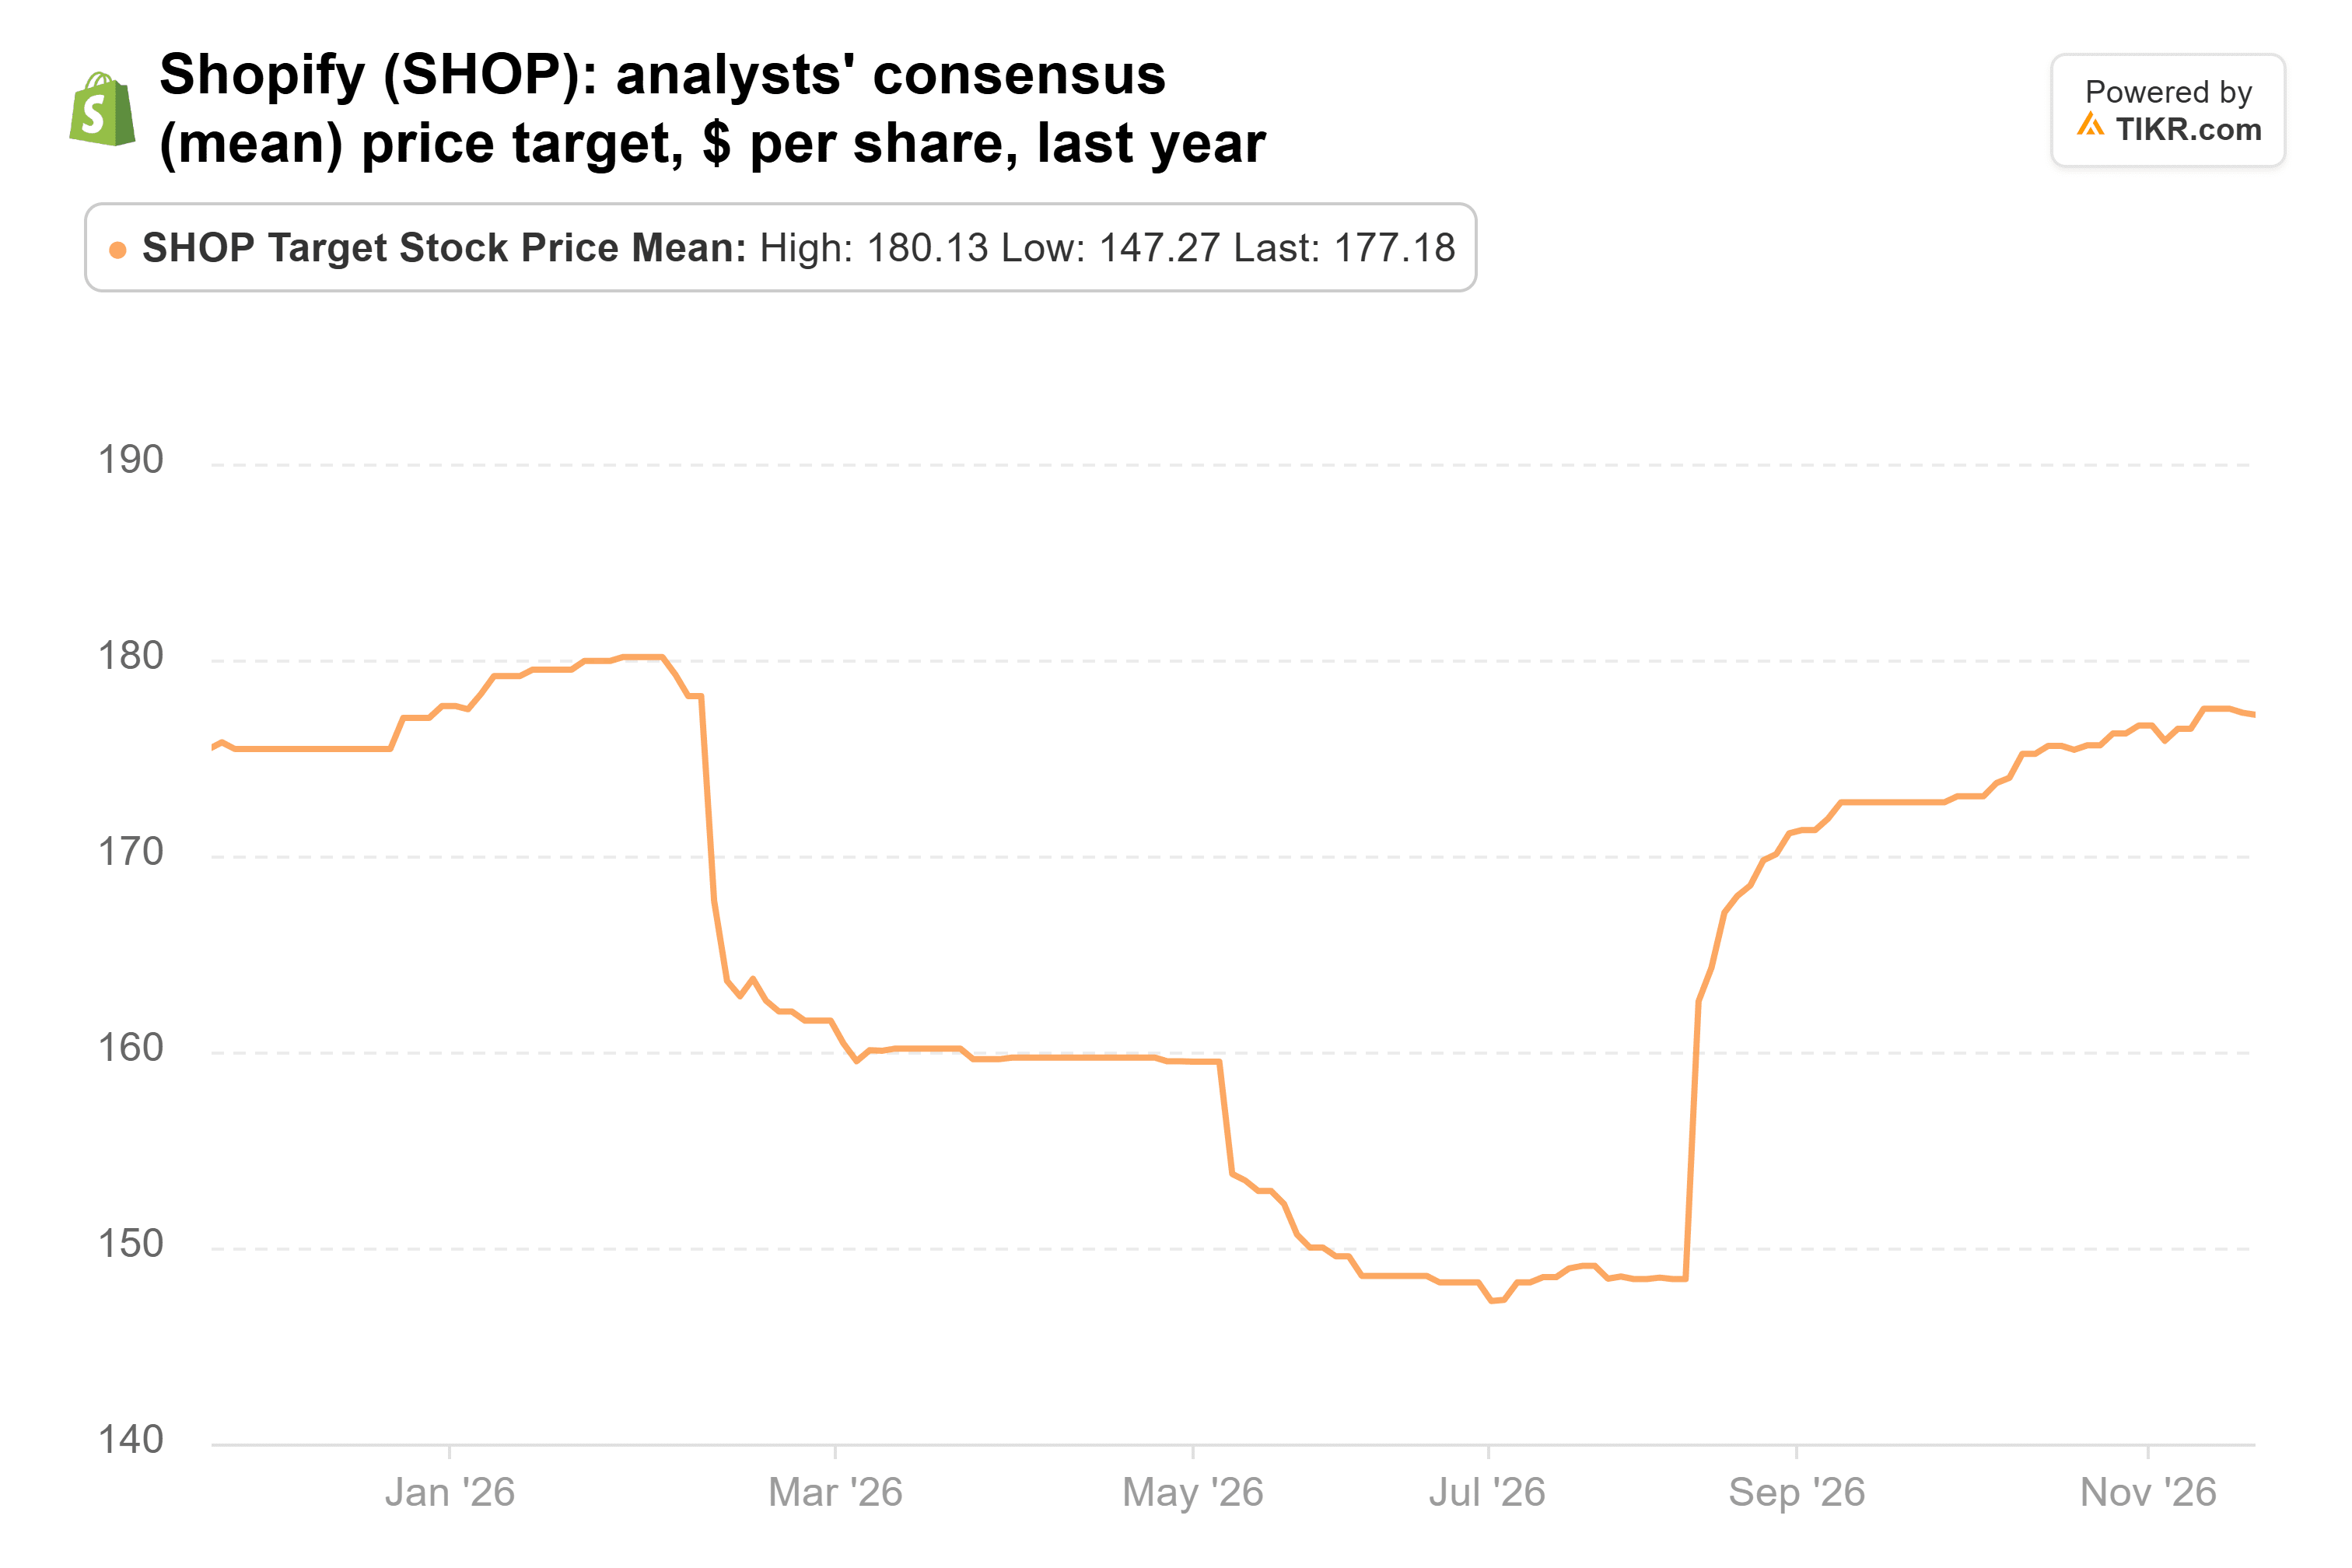
At about 59x forward earnings, Shopify isn’t cheap, though it’s below its 74x average since September 2023. And since late October, analysts have raised their 2027 revenue estimate to $19.4 billion from $19.2 billion but trimmed their 2028 EPS estimate to $3.26 from $3.32.
Meta is the brand-new bet
Meta is the only one of the three that Foxhaven didn’t own a quarter earlier. By Sept. 30, it held 174,634 shares worth $127 million, or 3.5% of its 13F stocks.
The stock has fallen 18% since then. Third-quarter revenue grew 26% to $64.6 billion. But capex of $34.9 billion was more than the quarter’s $32.8 billion of operating cash flow, and consensus now has free cash flow bottoming at negative $48.0 billion in 2027.
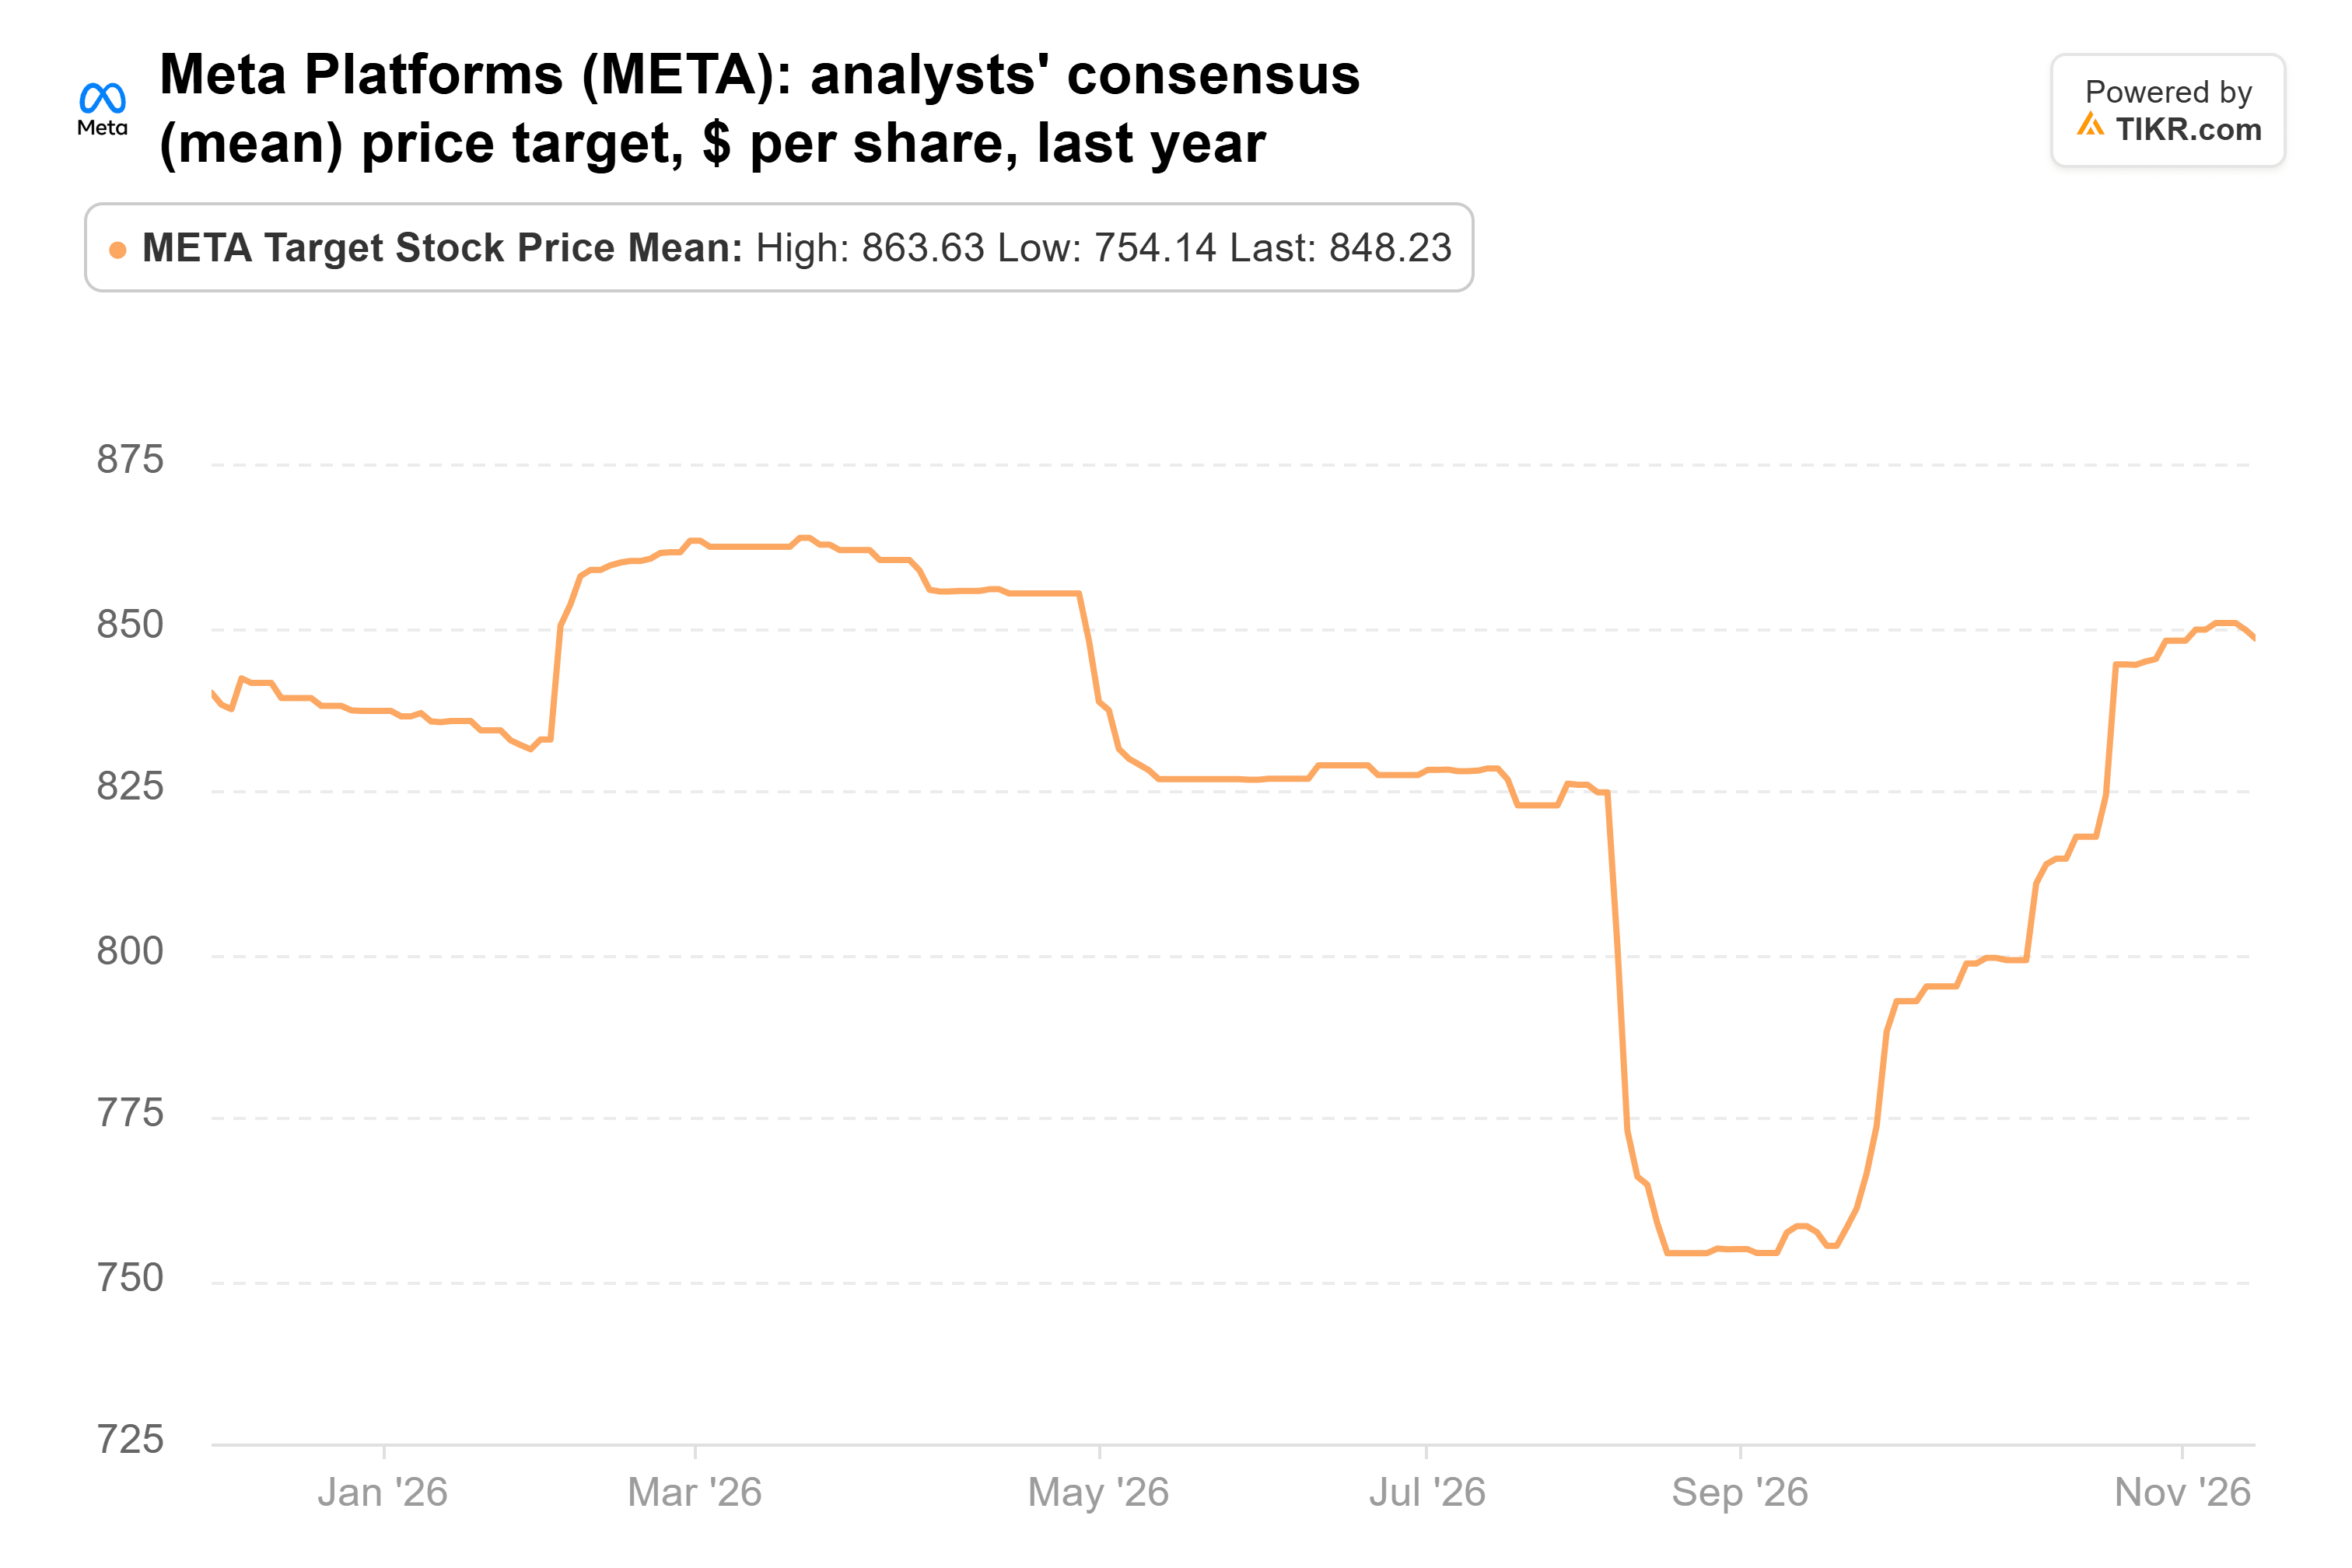
At about 18x forward earnings, Meta trades below its five-year average of 21x. Its $848 consensus target from 62 analysts is 42% above the latest close, and it’s edged up over the past year:
If I could only buy one, it’d be Meta
Of the three, the numbers back Meta best. It’s growing revenue 26% at a multiple below its own average. I’d rather own that than bet on Affirm’s credit holding up or pay nearly 60x earnings for Shopify.
The risk is the spending. If Meta’s 2027 capex plan comes in well above the roughly $210 billion analysts expect, with no new revenue to show for it, that below-average multiple could fall further.
Meta reports its fourth quarter in late January, when management sets out its 2027 budget. Affirm and Shopify both report in February. Foxhaven’s next 13F, due in mid-February, will show whether it stuck with all three.
So what is Affirm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Affirm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!