

Key Takeaways
- A $12 billion fund sold every share of Honeywell, Honeywell Aerospace and TJX Companies in the third quarter, its latest 13F shows.
- In the same quarter it added to Alphabet, now its second-biggest holding, and Cadence Design. Both are down since Sept. 30, while the three it sold are up.
- Analysts’ consensus targets sit 17% to 24% above the three stocks it sold, but Honeywell Aerospace’s target is at its lowest since the stock listed in June.
- Of the three sales, the numbers argue hardest against Honeywell’s, after a raised 2026 outlook and a consensus target that has climbed since the spin-off.
A fund with $11.90 billion of US stocks has cleared out three household names.
Unisphere Establishment’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows it held no shares of Honeywell (HON), Honeywell Aerospace (HONA) or TJX Companies (TJX) at the quarter’s end. It had owned all three on June 30. That $11.90 billion, spread across 55 positions, is what its 13F holds in US stocks. In the same quarter, it added to Alphabet (GOOGL) and Cadence Design Systems (CDNS).
Honeywell raised its outlook
The fund held 2.05 million Honeywell shares on June 30, worth $459 million and 3.9% of the fund. By Sept. 30 it held none. Honeywell’s third quarter was its first full one without the aerospace business it spun off in June. Adjusted EPS rose 34% to $2.27 on organic sales growth of 7%. It also raised its 2026 outlook to adjusted EPS of $8.40-$8.45, up 30% to 31%. The spin-off reset Wall Street’s consensus target, which bottomed at $230 on June 30 and has climbed to $254 since:
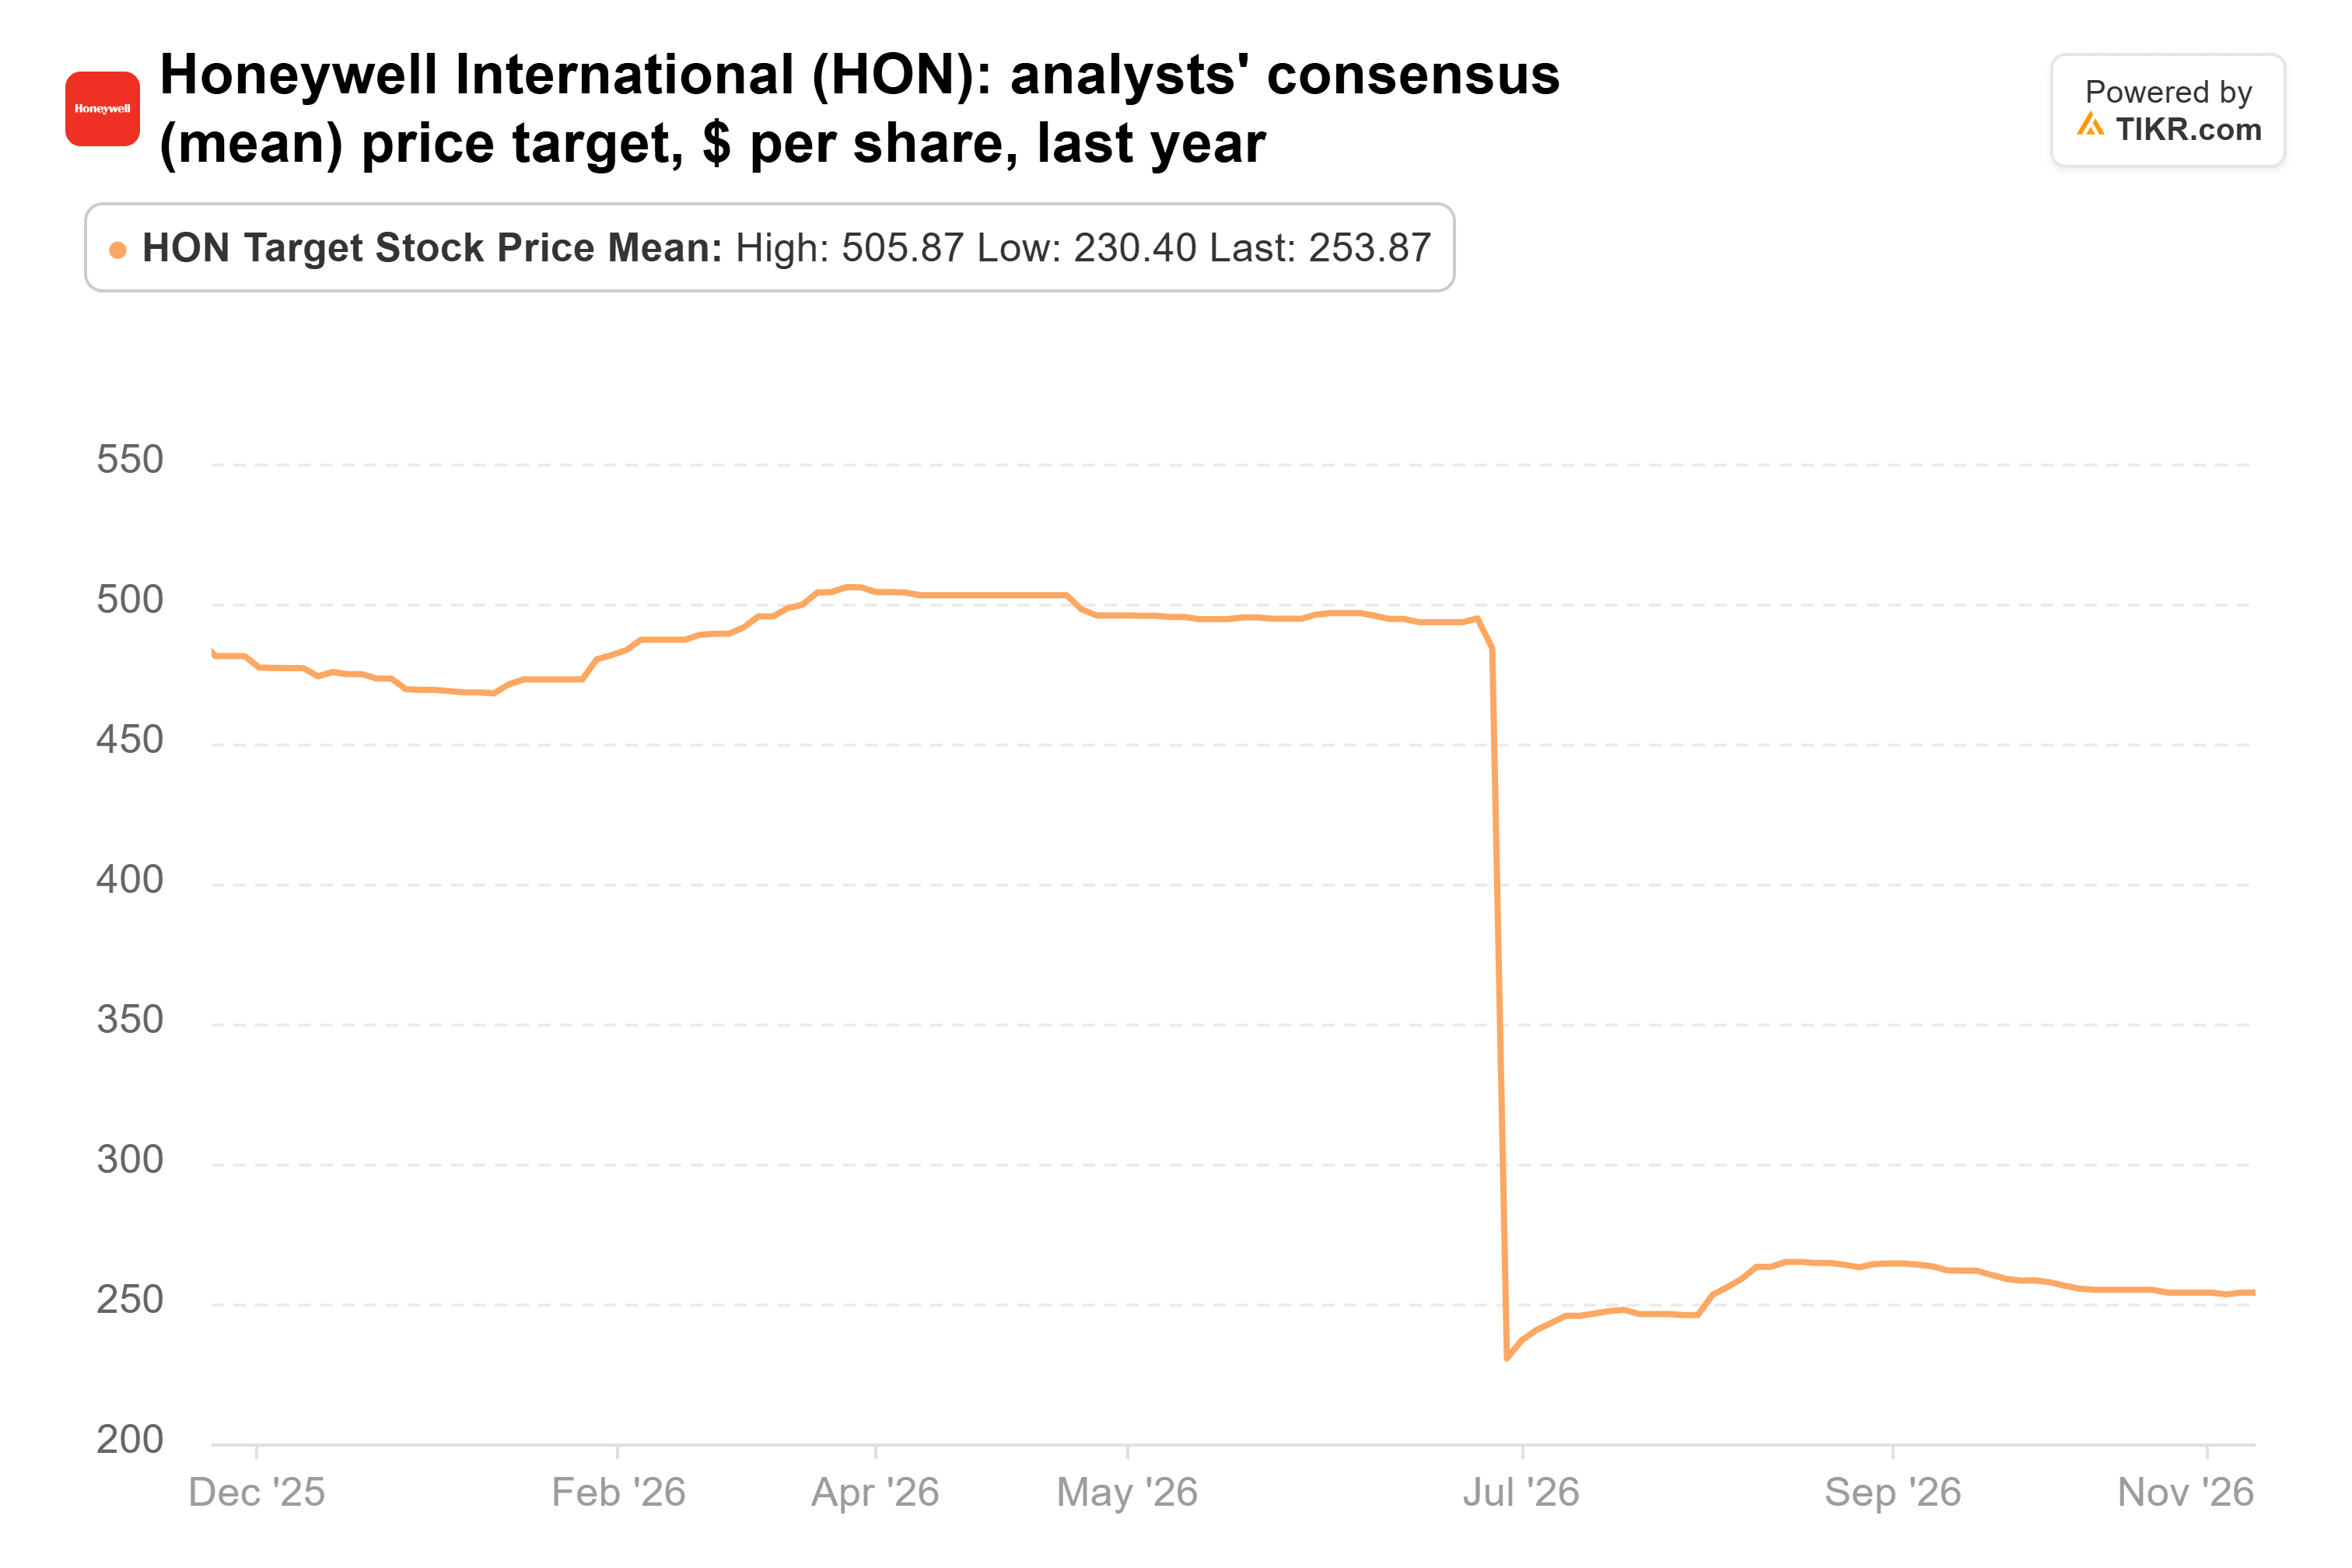
That’s 17% above the last close of $217.84, and the stock is up 3% since Sept. 30.
TIKR tracks 24 analysts on Honeywell. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Honeywell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Honeywell’s Analyst Ratings
Analysts keep cutting Honeywell Aerospace
The fund’s 2.08 million Honeywell Aerospace shares, also worth $459 million on June 30, were gone by Sept. 30 too. The stock has barely moved since, up 0.6%. In late October, Honeywell Aerospace beat on its third quarter and still sank 11% as its supply constraints persisted. Analysts have cut their consensus target from $300 when the stock listed in June to $193, the lowest it’s been:
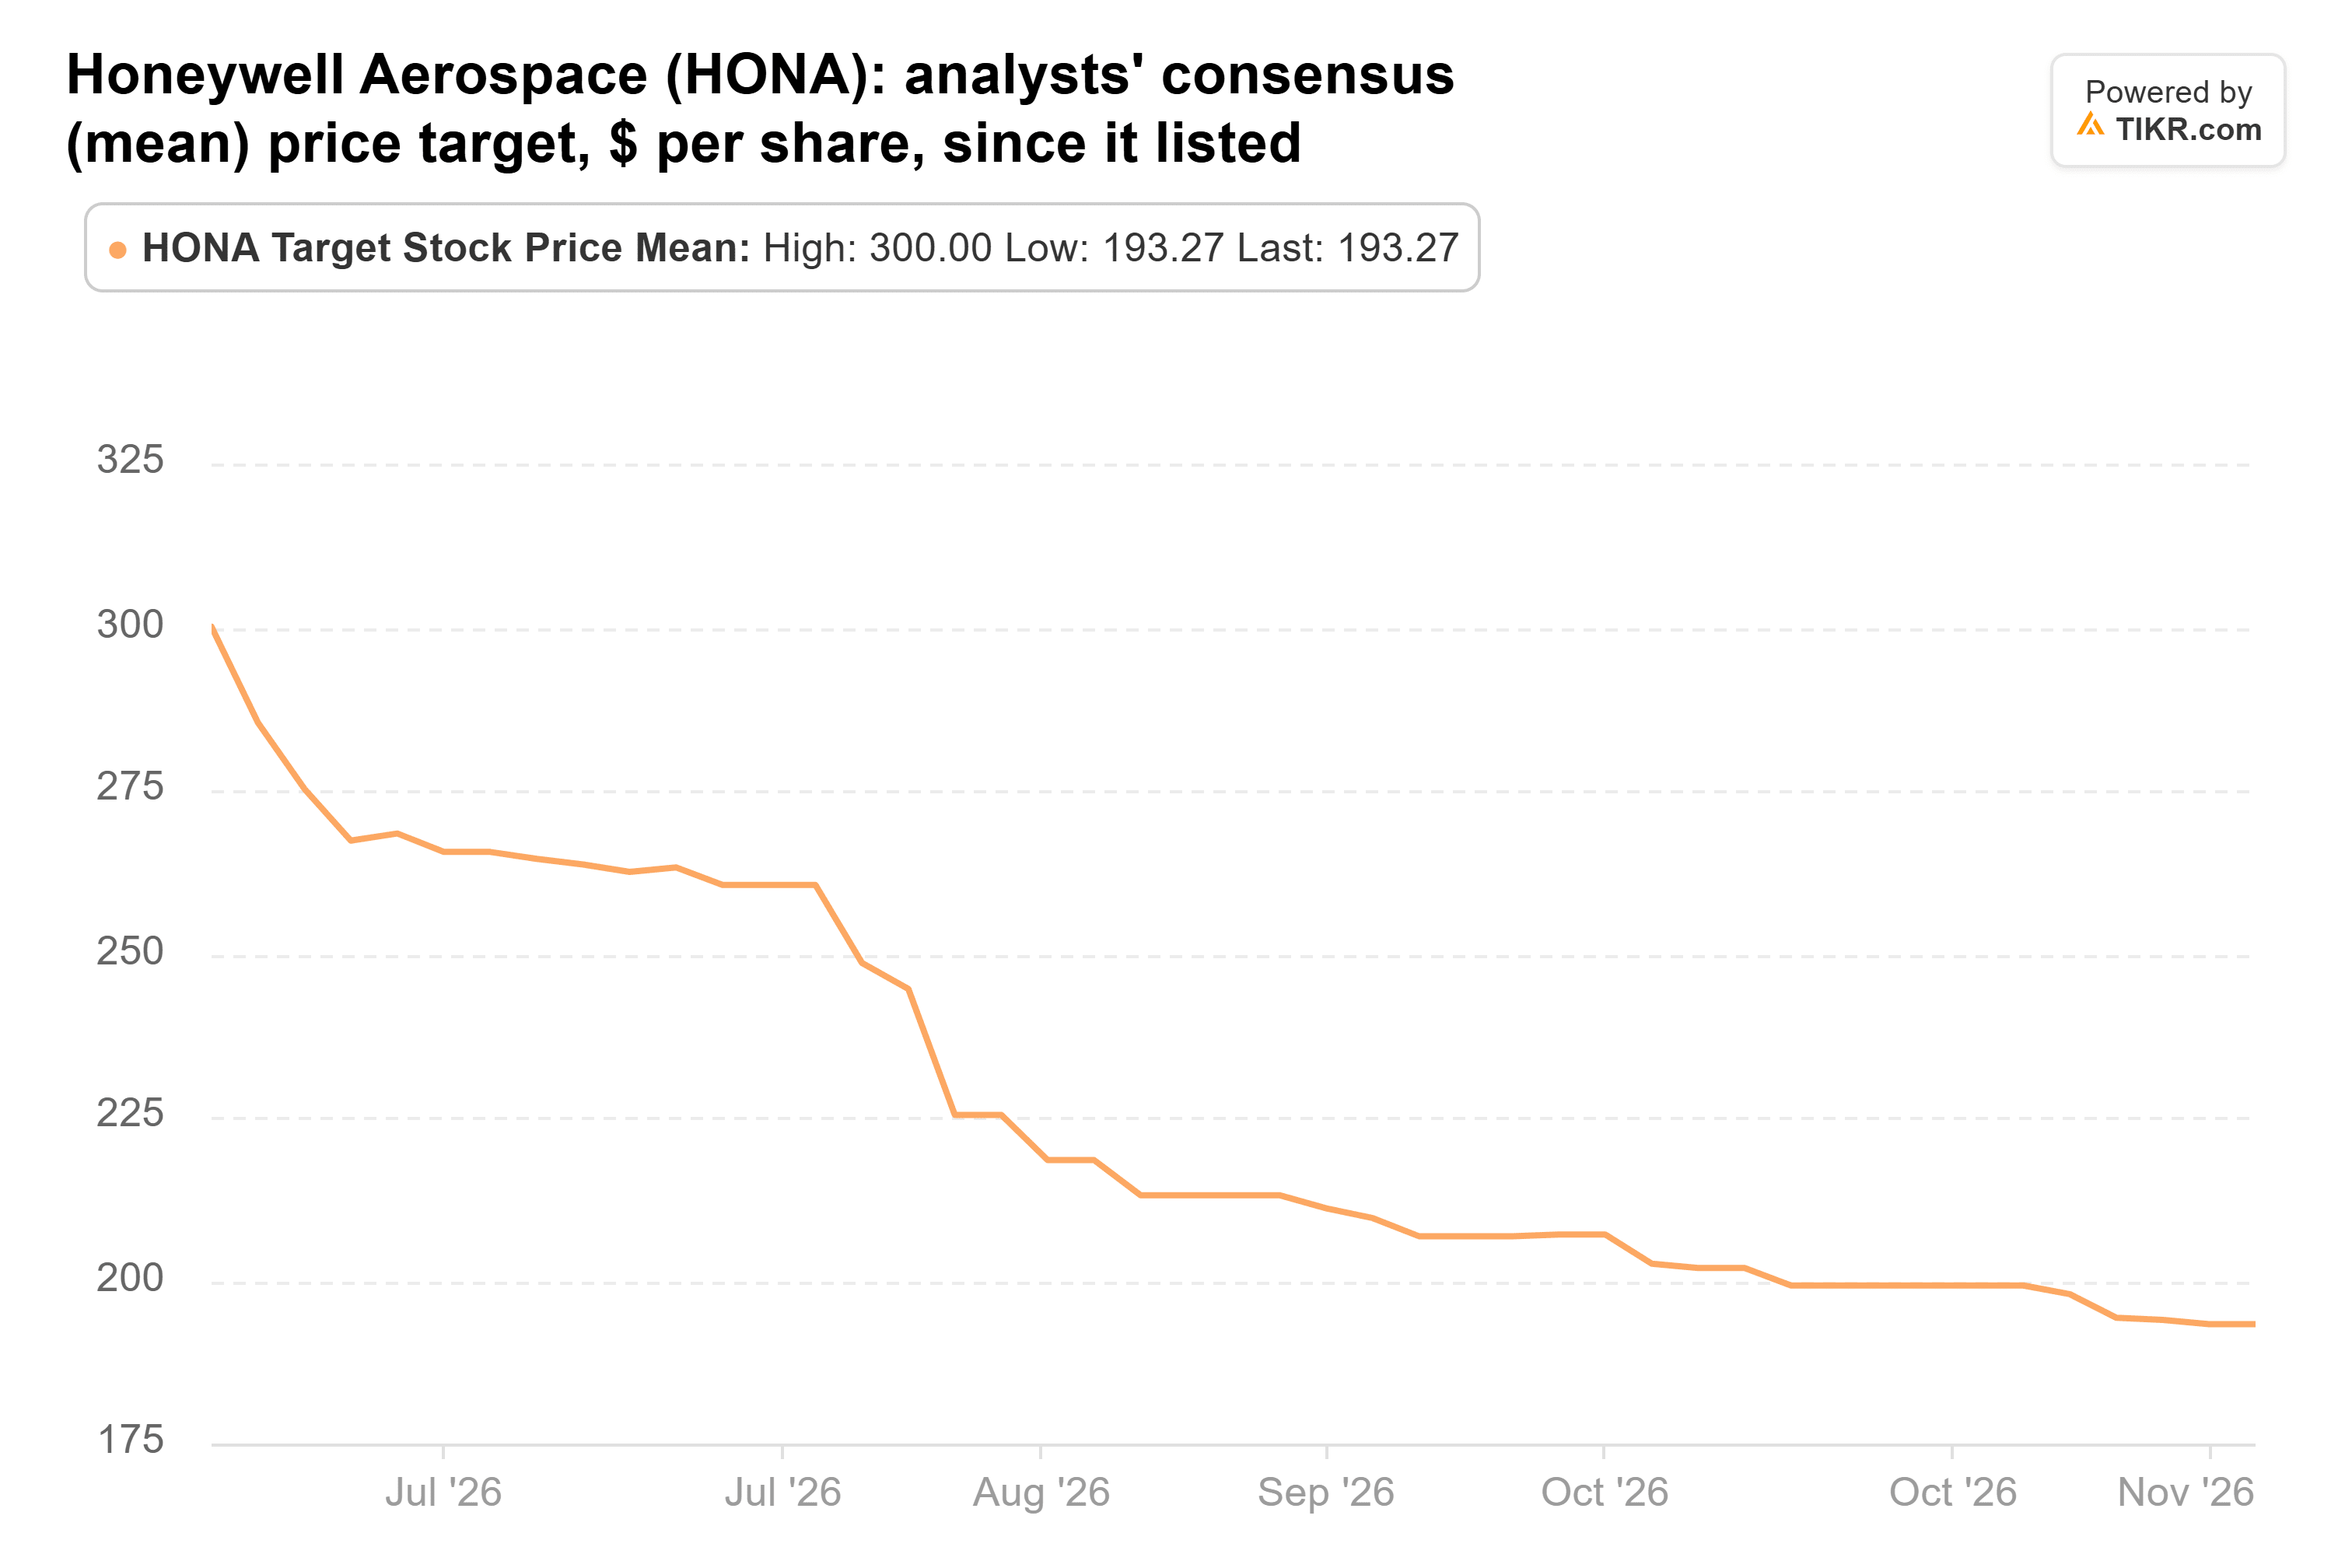
Even the lowest target, $170, sits above the $155.84 close, and the average is 24% above it. At about 19x forward earnings, the stock isn’t expensive. But I’d want to see the supply problems ease and the target cuts stop before I trusted that upside.
Analysts have cooled a bit on TJX
TJX was the smaller sale: 1.37 million shares worth $208 million on June 30, 1.8% of the fund. It’s up 5% since Sept. 30. Wall Street’s consensus target rose from $153 a year ago to a peak of $178 in May, and it has come back to $165 since:
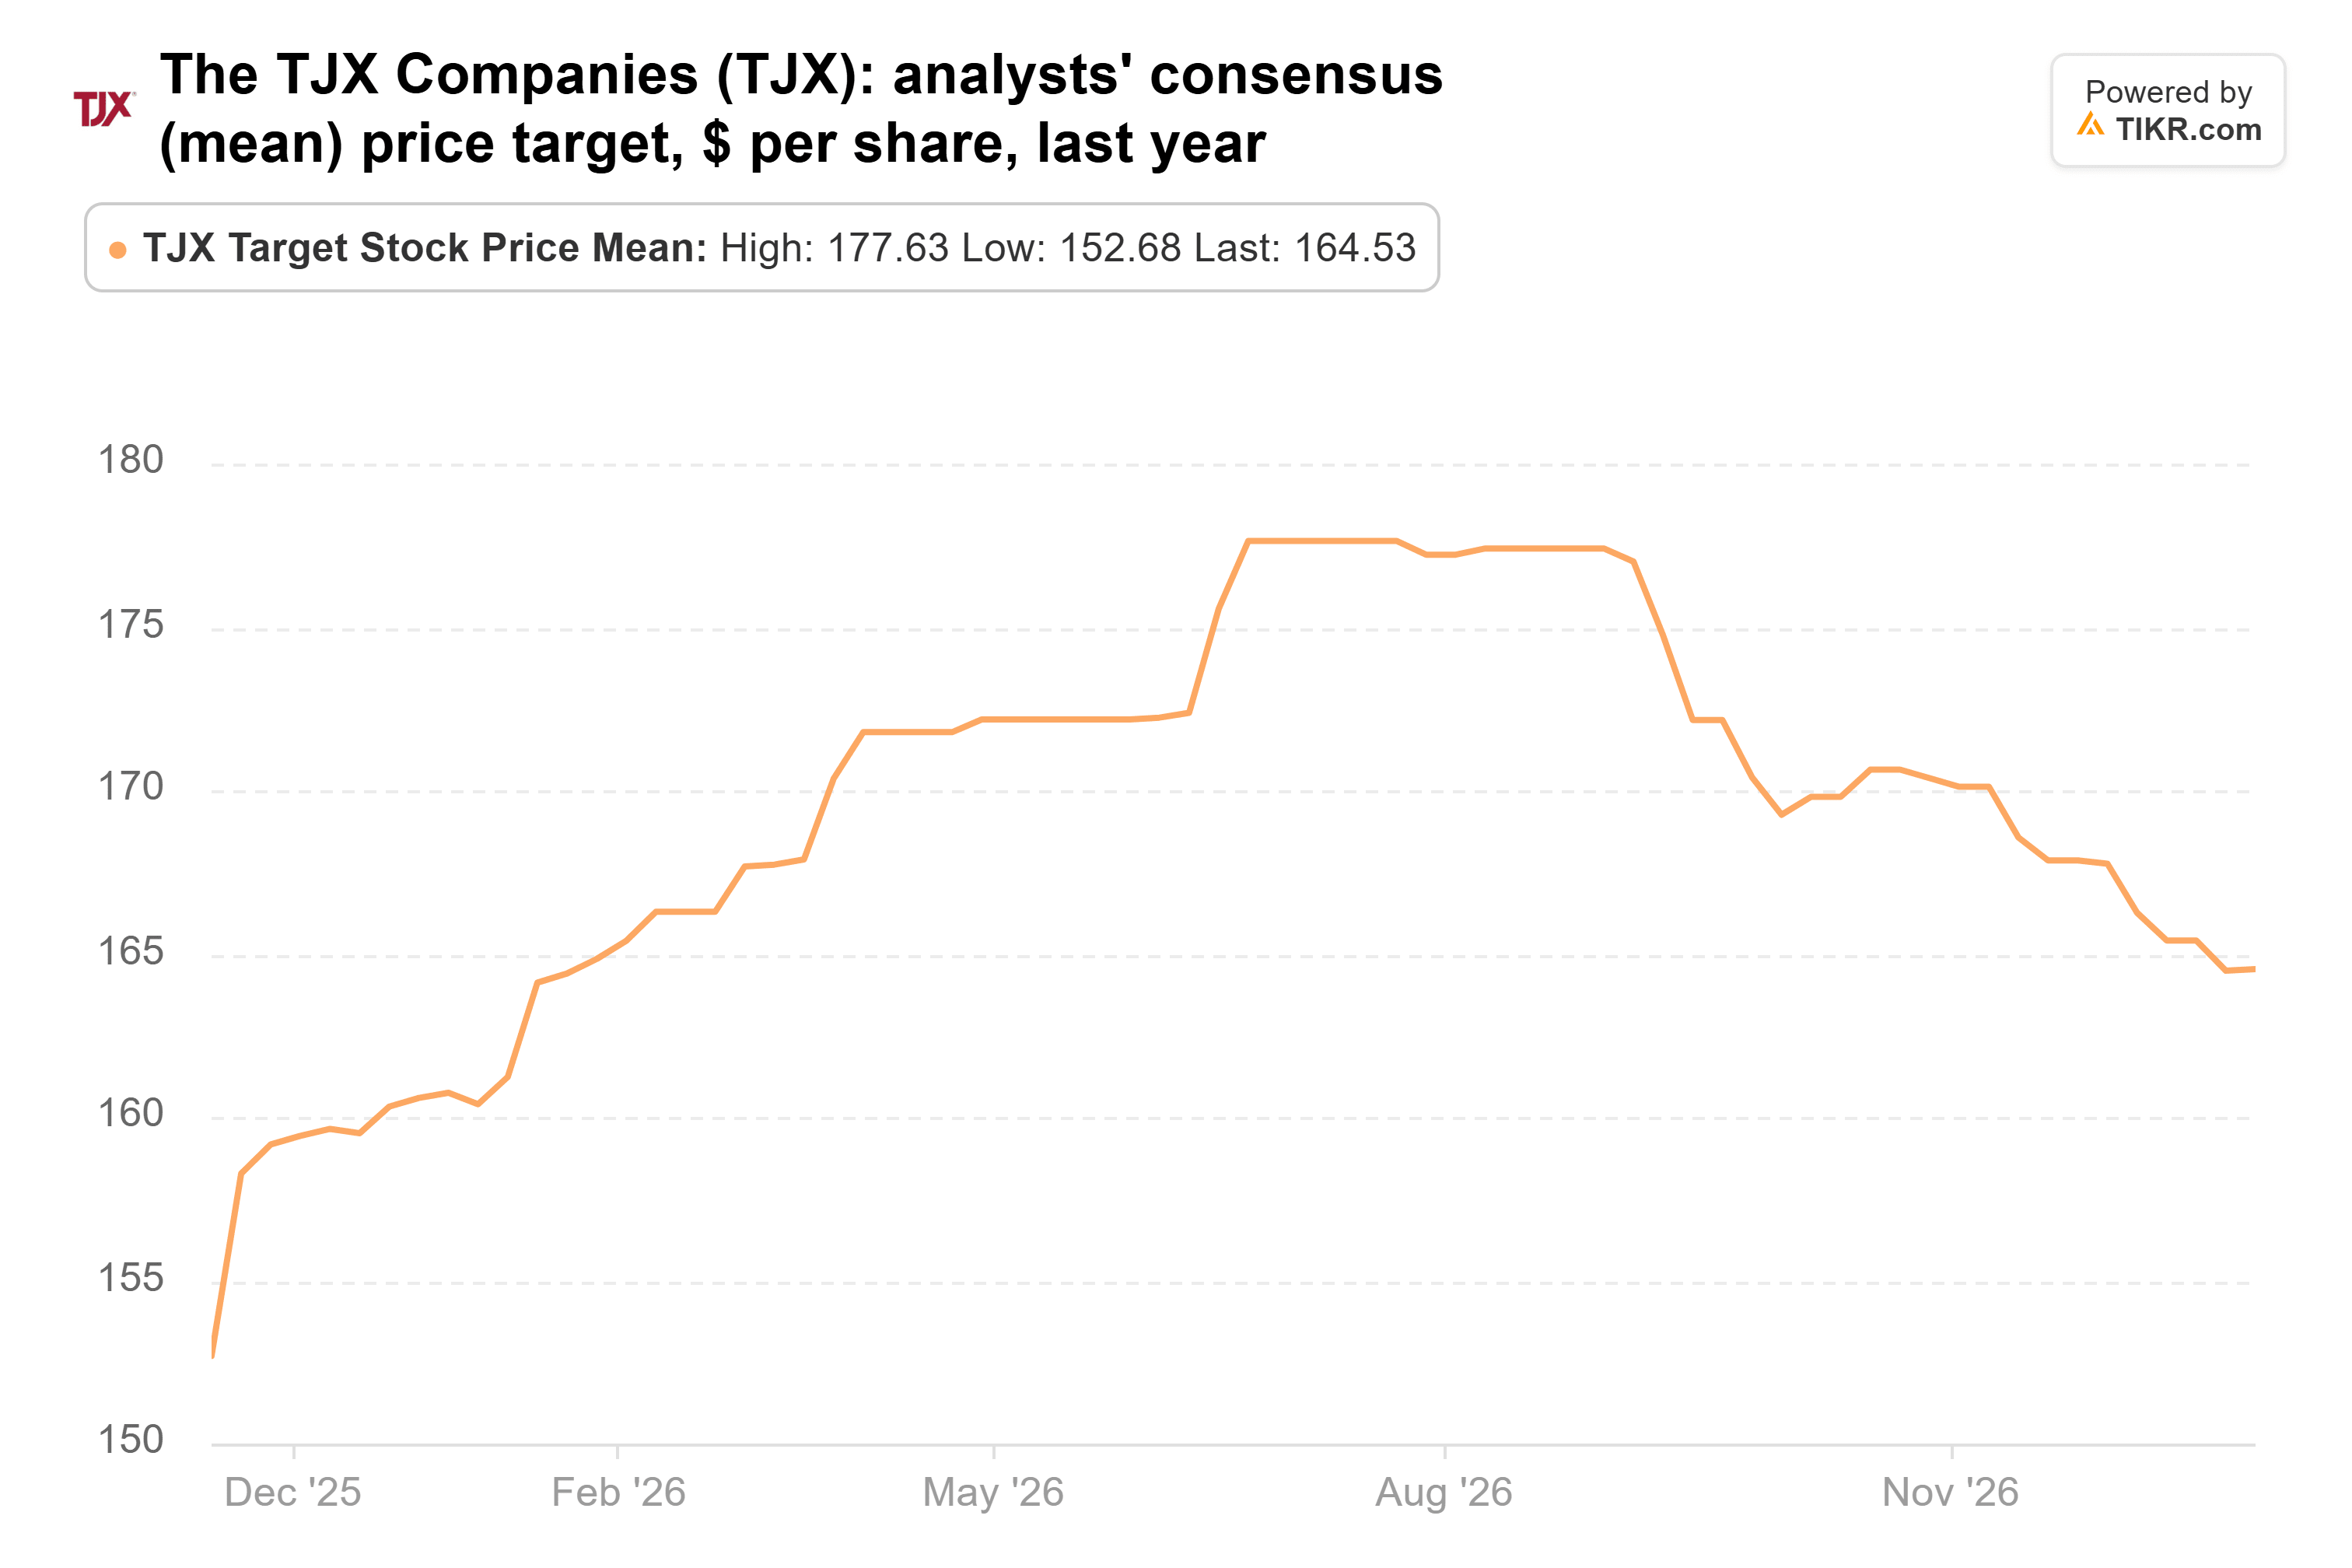
That’s 18% above the $139.41 close. At about 25x forward earnings, though, that’s a lot to pay for a stock whose target analysts have trimmed since May.
The stocks it added are down since
Selling was only half of the fund’s quarter. It added 36% to its Alphabet stake, to 4.34 million shares worth $1.49 billion on Sept. 30. That’s its No. 2 holding, at 12.5% of the fund. It also added 46% to Cadence Design, to 437,700 shares worth $145 million, 1.2% of the fund. Since Sept. 30, Alphabet is down 21% and Cadence is down 8%, while all three stocks it sold are up.
Analysts haven’t followed Alphabet down. Their consensus target has risen from $318 a year ago to $400:
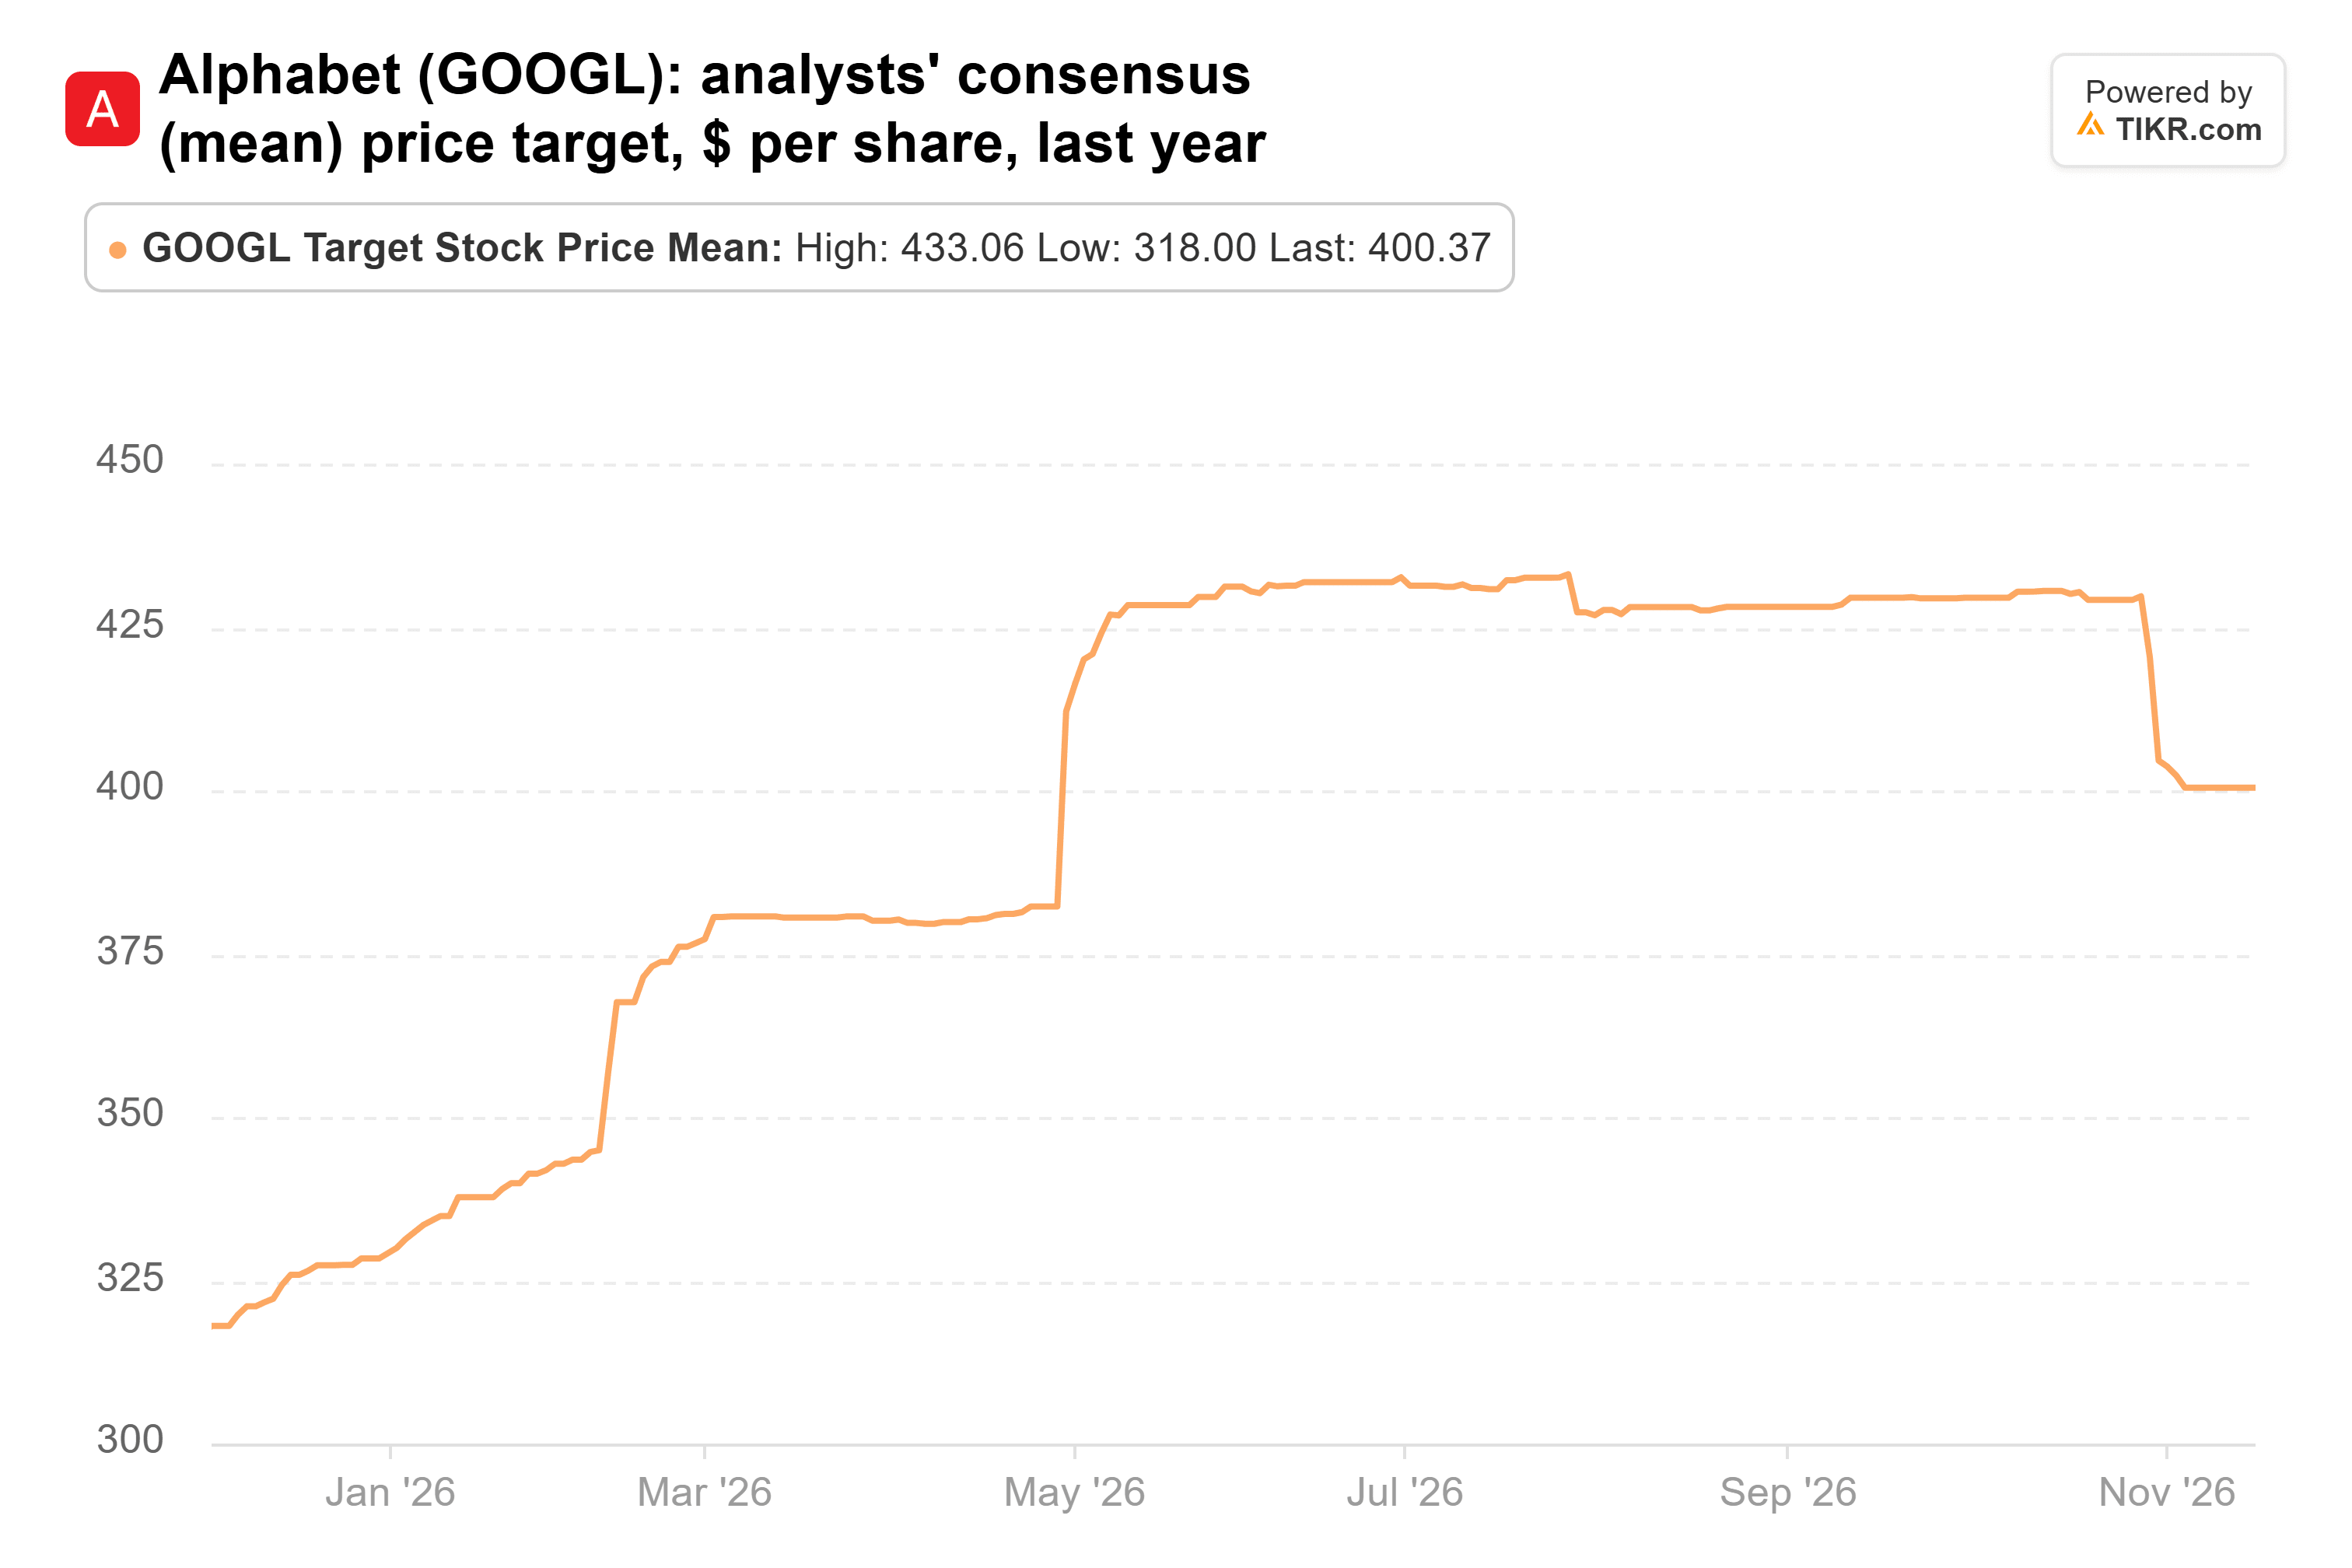
That’s 47% above the $272.66 close, at about 20x forward earnings, and Morgan Stanley sees Alphabet’s TPU sales jumping to $84 billion. The near-term risk is Anthropic’s IPO, whose lock-ups free nearly 40% of the deal on day one. That’s a big risk for Alphabet as an Anthropic shareholder.
Honeywell is the one I’d buy back
If I could buy back one of the three, it’d be Honeywell. Management raised its 2026 outlook after a strong third quarter, and analysts have lifted their target since the spin-off. At about 23x forward earnings, it also costs less than TJX. The risk is that fatter margins are doing most of the work: Honeywell guides 2026 organic sales growth of just 4% to 5%, against adjusted EPS growth of 30% to 31%.
Selling Honeywell Aerospace looks right while analysts are still cutting, and selling TJX looks reasonable at its price. The fund’s next 13F, due by Feb. 16, will show whether it came back to any of them. Honeywell’s fourth-quarter report early next year will show whether that outlook holds.
So what is Honeywell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Honeywell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


