Key Takeaways
- Alphabet rose on Nov. 12 as investors bet Nvidia’s CEO exit sends more AI chip spending to Google’s TPUs.
- A widely shared post calling Alphabet “the most obvious buy” leans on a Morgan Stanley estimate of $84 billion of TPU sales in 2027.
- Morgan Stanley assumes a 30% gross margin on those sales, while Alphabet plans about $200 billion of capex this year.
- At 21x forward earnings, Alphabet looks like a buy, but not an obvious one.
Nvidia (NVDA) announced on Nov. 12 that Jensen Huang had resigned as CEO, and its stock fell. Alphabet (GOOG) rose the same day, as investors bet more AI chip spending will go to Google’s TPUs.
The next day, one investor asked in both r/stocks and r/ValueInvesting: “Is GOOG not the most obvious buy here?”
The post’s boldest number is Morgan Stanley’s: $84 billion of direct TPU system sales in 2027, up from about $8 billion in 2026. That’s a tenfold jump in a year, and Morgan Stanley made the call in late August, before Nvidia’s shake-up gave chip buyers a new reason to shop around.
$84 Billion Would Be a Big Slice of Alphabet
Analysts expect Alphabet’s revenue to climb from $403 billion in 2025 to $638 billion in 2027.
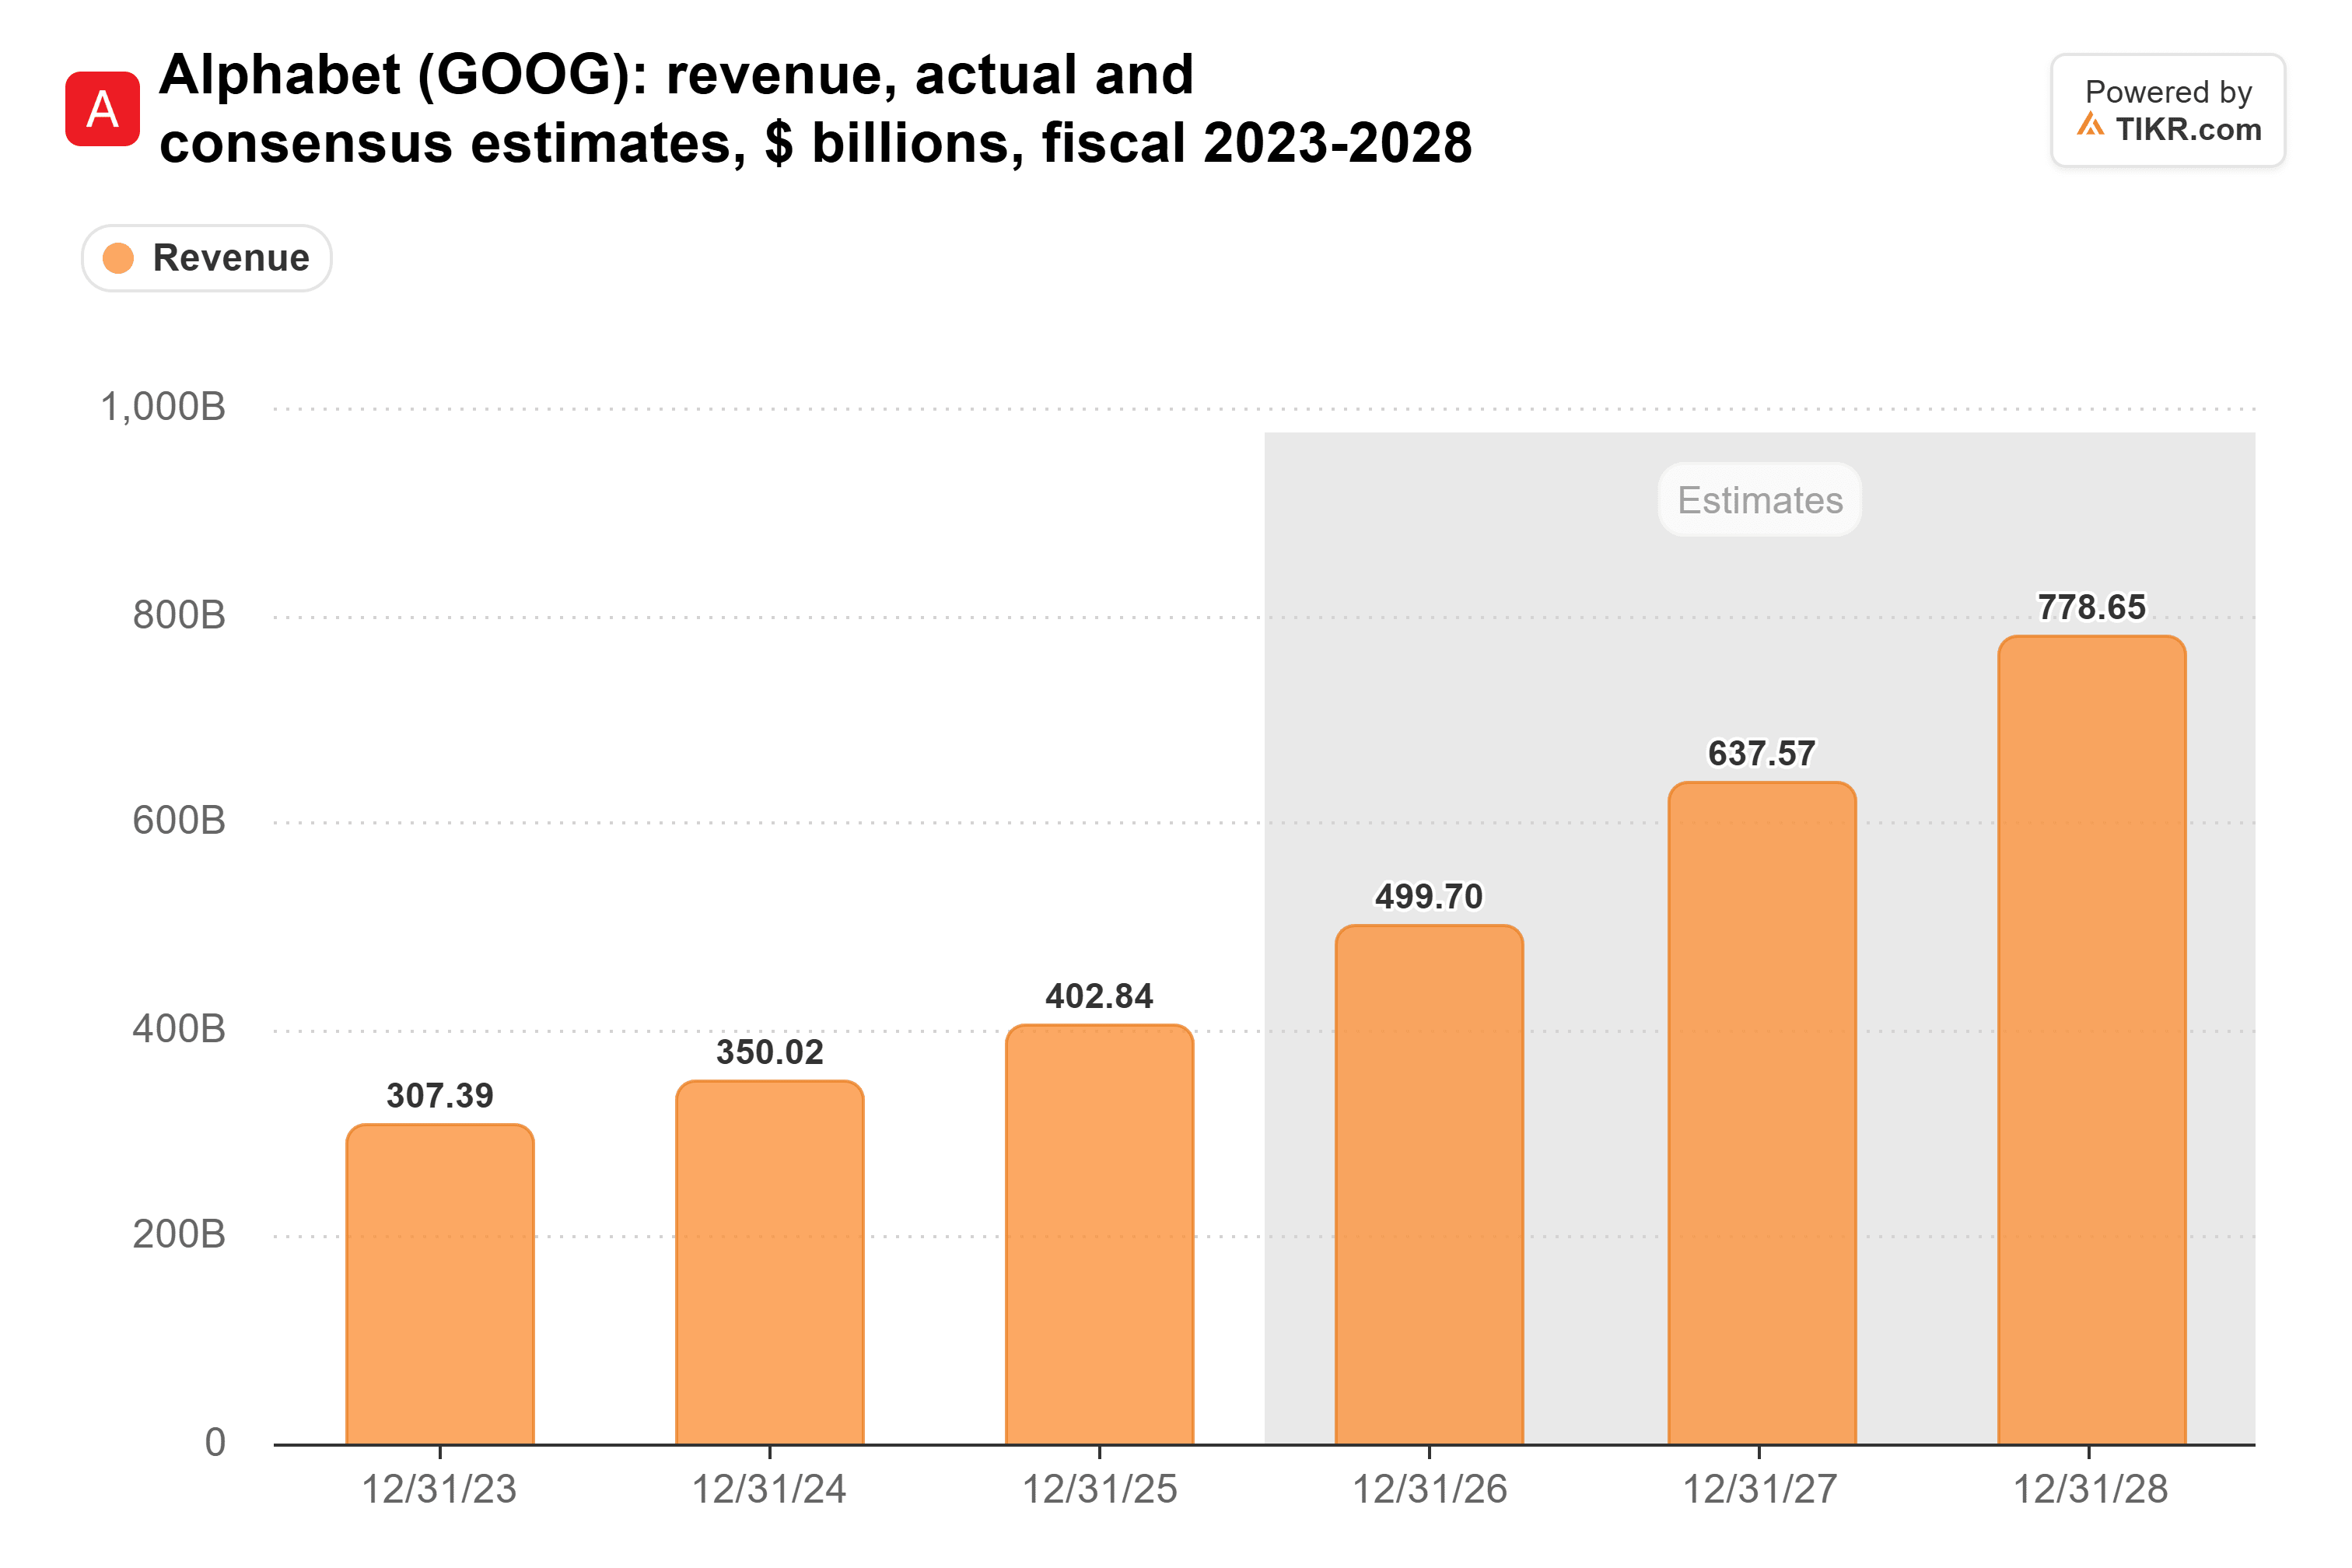
If Morgan Stanley is right, TPU sales would be about 13% of that 2027 total, and the jump from $8 billion alone would equal more than half of the $138 billion of growth analysts expect from 2026 to 2027. Bloomberg Intelligence goes further, expecting TPU sales above $135 billion by 2028.
The sales have started. Alphabet’s third-quarter release called TPU systems sales a meaningful contributor as Cloud revenue jumped 103% to $30.7 billion, a $123 billion run rate.
The Catch Is Alphabet’s Margin
Nvidia’s first-ever board chair, Harvey Jones, said “we expect the company’s operations, customer commitments and product roadmap to continue without interruption.”
Google is competing on price. Bloomberg Intelligence’s Mandeep Singh said on Bloomberg Tech: “that price advantage that Google has with TPU being priced much lower than NVIDIA could actually be a big factor.”
Lower prices thin margins. Morgan Stanley assumes a 30% gross margin on TPU sales, about $25 billion of gross profit on $84 billion, before operating costs. Cloud’s operating margin, after those costs, was 36.2% last quarter.
The poster applies that 36% to more than $200 billion of 2027 Cloud revenue, then puts 25x on it to value Cloud at $1.8 trillion. That’s a multiple on a forecast built on tenfold TPU growth. Alphabet doesn’t report what TPU hardware earns, so Cloud’s margin over the next few quarters is the best clue.
TIKR Tracks 58 Analysts on Alphabet. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Cheap Enough to Buy, Cash Burn and All
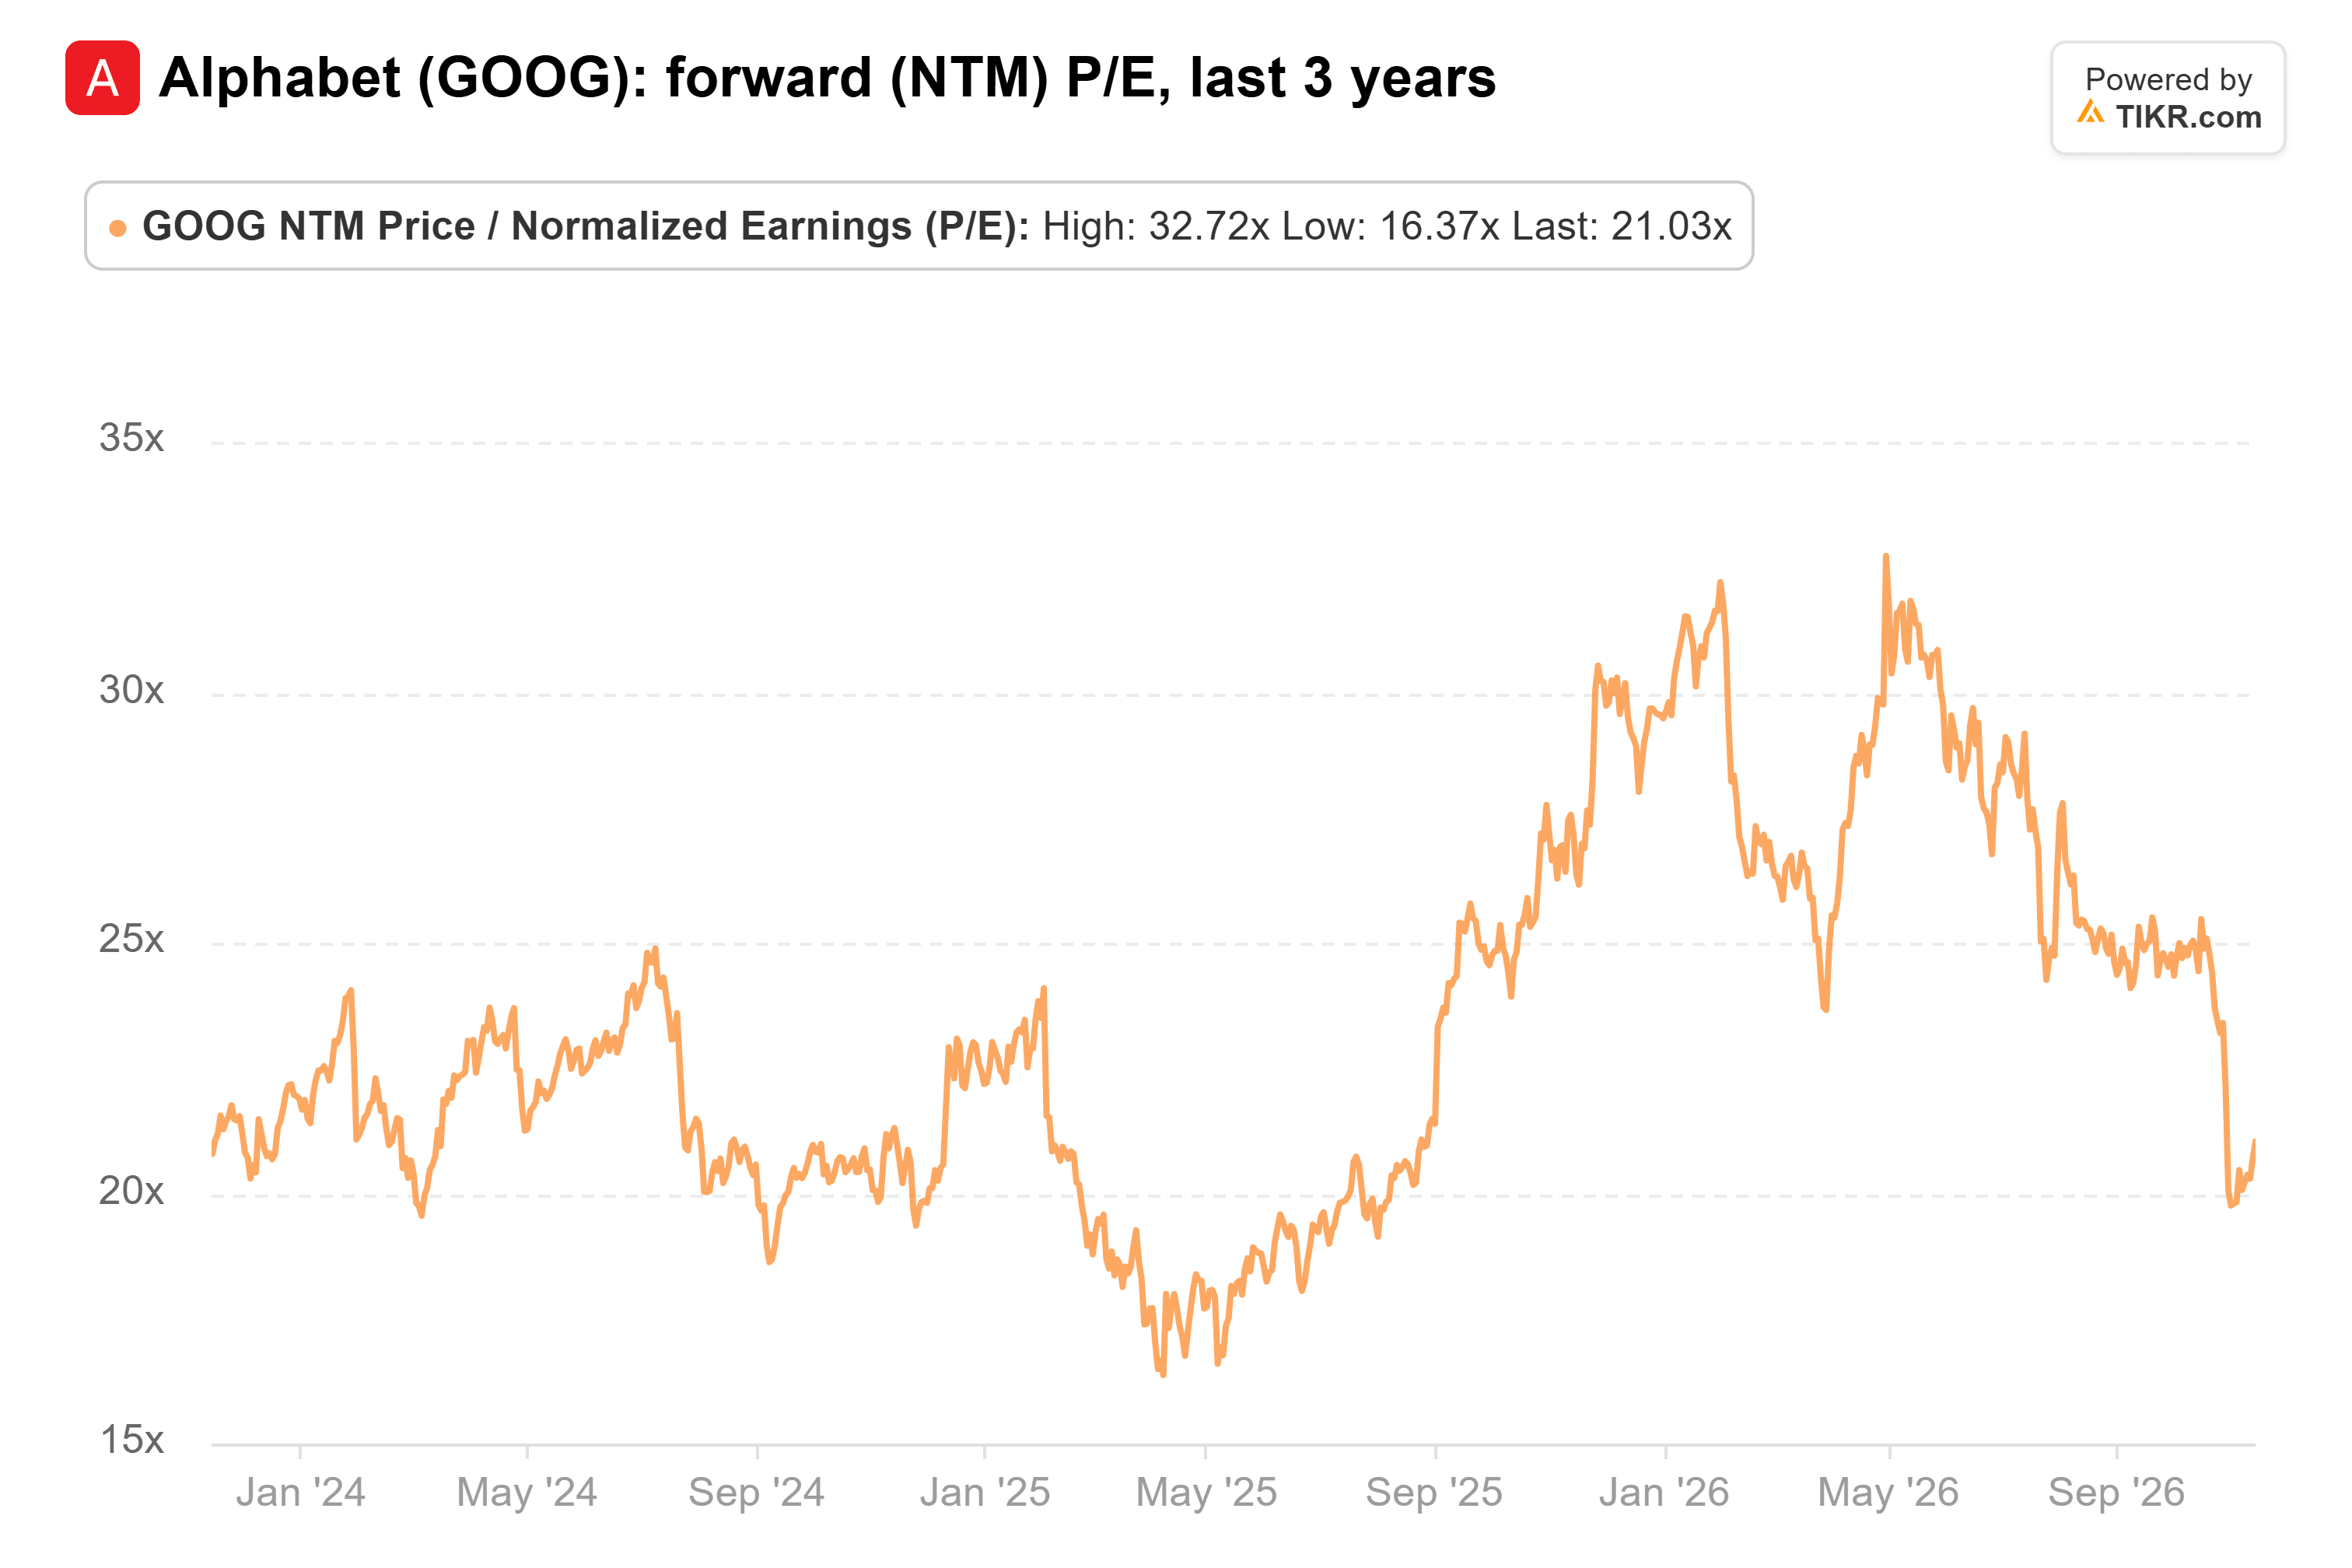
The poster puts Alphabet at 19x forward earnings. It’s 21x, below its three-year average of 23x and well off the 33x it reached in April.
Investors are pricing the cost of the buildout instead: capital spending nearly quadrupled from 2021 to 2025.
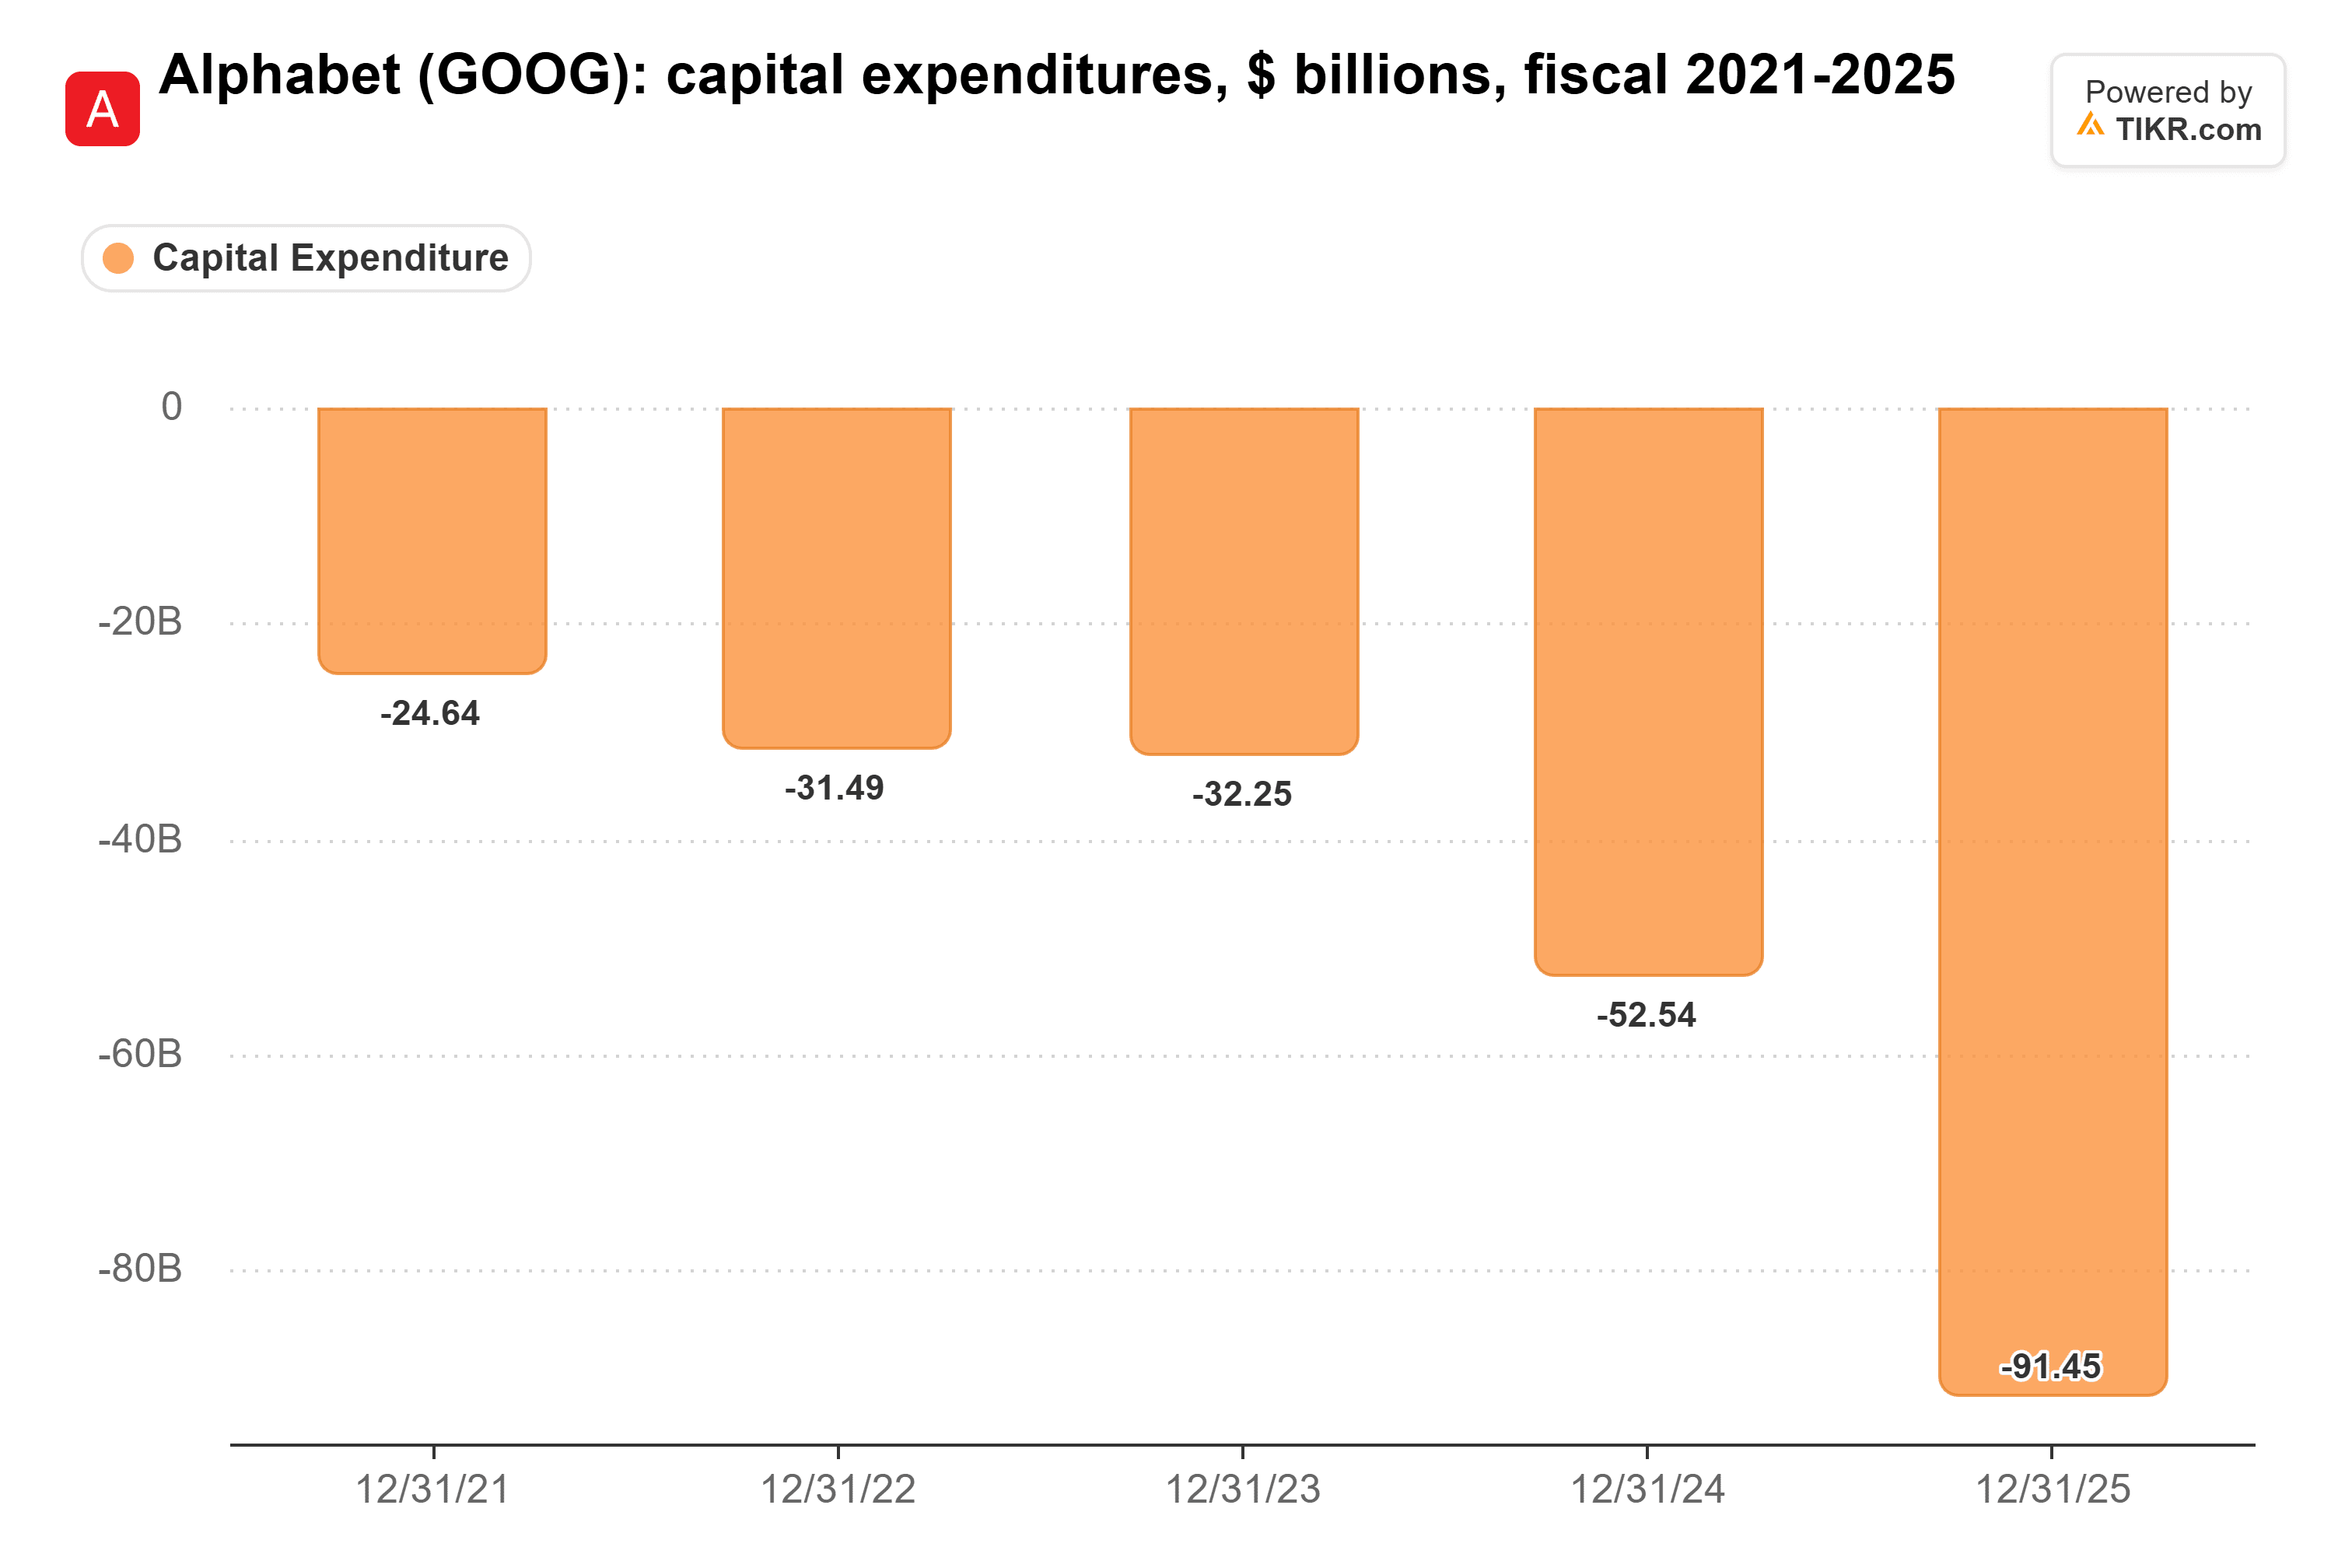
Alphabet kept 2026 capex guidance of $195 billion to $205 billion, more than double last year’s. Third-quarter capex was $51.4 billion, and free cash flow came in at negative $9.1 billion, including a $5.2 billion EU fine payment.
I’d buy Alphabet at 21x. I just wouldn’t call it obvious while it’s spending about $200 billion this year on data centers. If TPU sales get near Morgan Stanley’s figure, even at 30%, the stock looks cheap against its own history. If not, Search and Cloud still support a stock below its usual multiple. Nvidia’s Nov. 17 report will show whether its customers are staying put.
So What Is Alphabet Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!