

Key Takeaways
- Meridiem Capital Partners sold all of its UnitedHealth, Charles River Laboratories and Alphabet shares in the third quarter, its latest 13F shows.
- By Sept. 30, Microsoft, a new position, and Visa, which it added to, were the fund’s two biggest holdings.
- Analysts’ average targets sit 41% above Alphabet’s price, 16% above UnitedHealth’s and 4% above Charles River’s.
- Of the three, Alphabet looks like the one to buy back, since every analyst’s target sits above its price.
Meridiem Capital Partners, a $2.4 billion fund, sold every share it held of UnitedHealth (UNH), Charles River Laboratories (CRL) and Alphabet (GOOGL) in the third quarter, according to its 13F for the quarter ended Sept. 30, filed Nov. 16. By Sept. 30, its two biggest positions were Microsoft (MSFT), new in the quarter, and Visa (V), after a 55% increase in its shares.
UnitedHealth is on the mend at a fair price
Meridiem held 211,050 UnitedHealth shares at June 30, worth $88 million and 4.0% of its 13F stocks, and it held none at Sept. 30. The stock is down 0.9% since then.
The business is healing. Medical costs took 88.4% of premiums in the third quarter, against 89.9% a year earlier. Management has also raised its 2026 outlook three times this year, most recently to at least $20.50 of adjusted EPS. Analysts have noticed. The consensus target has climbed from $387 a year ago to $476:
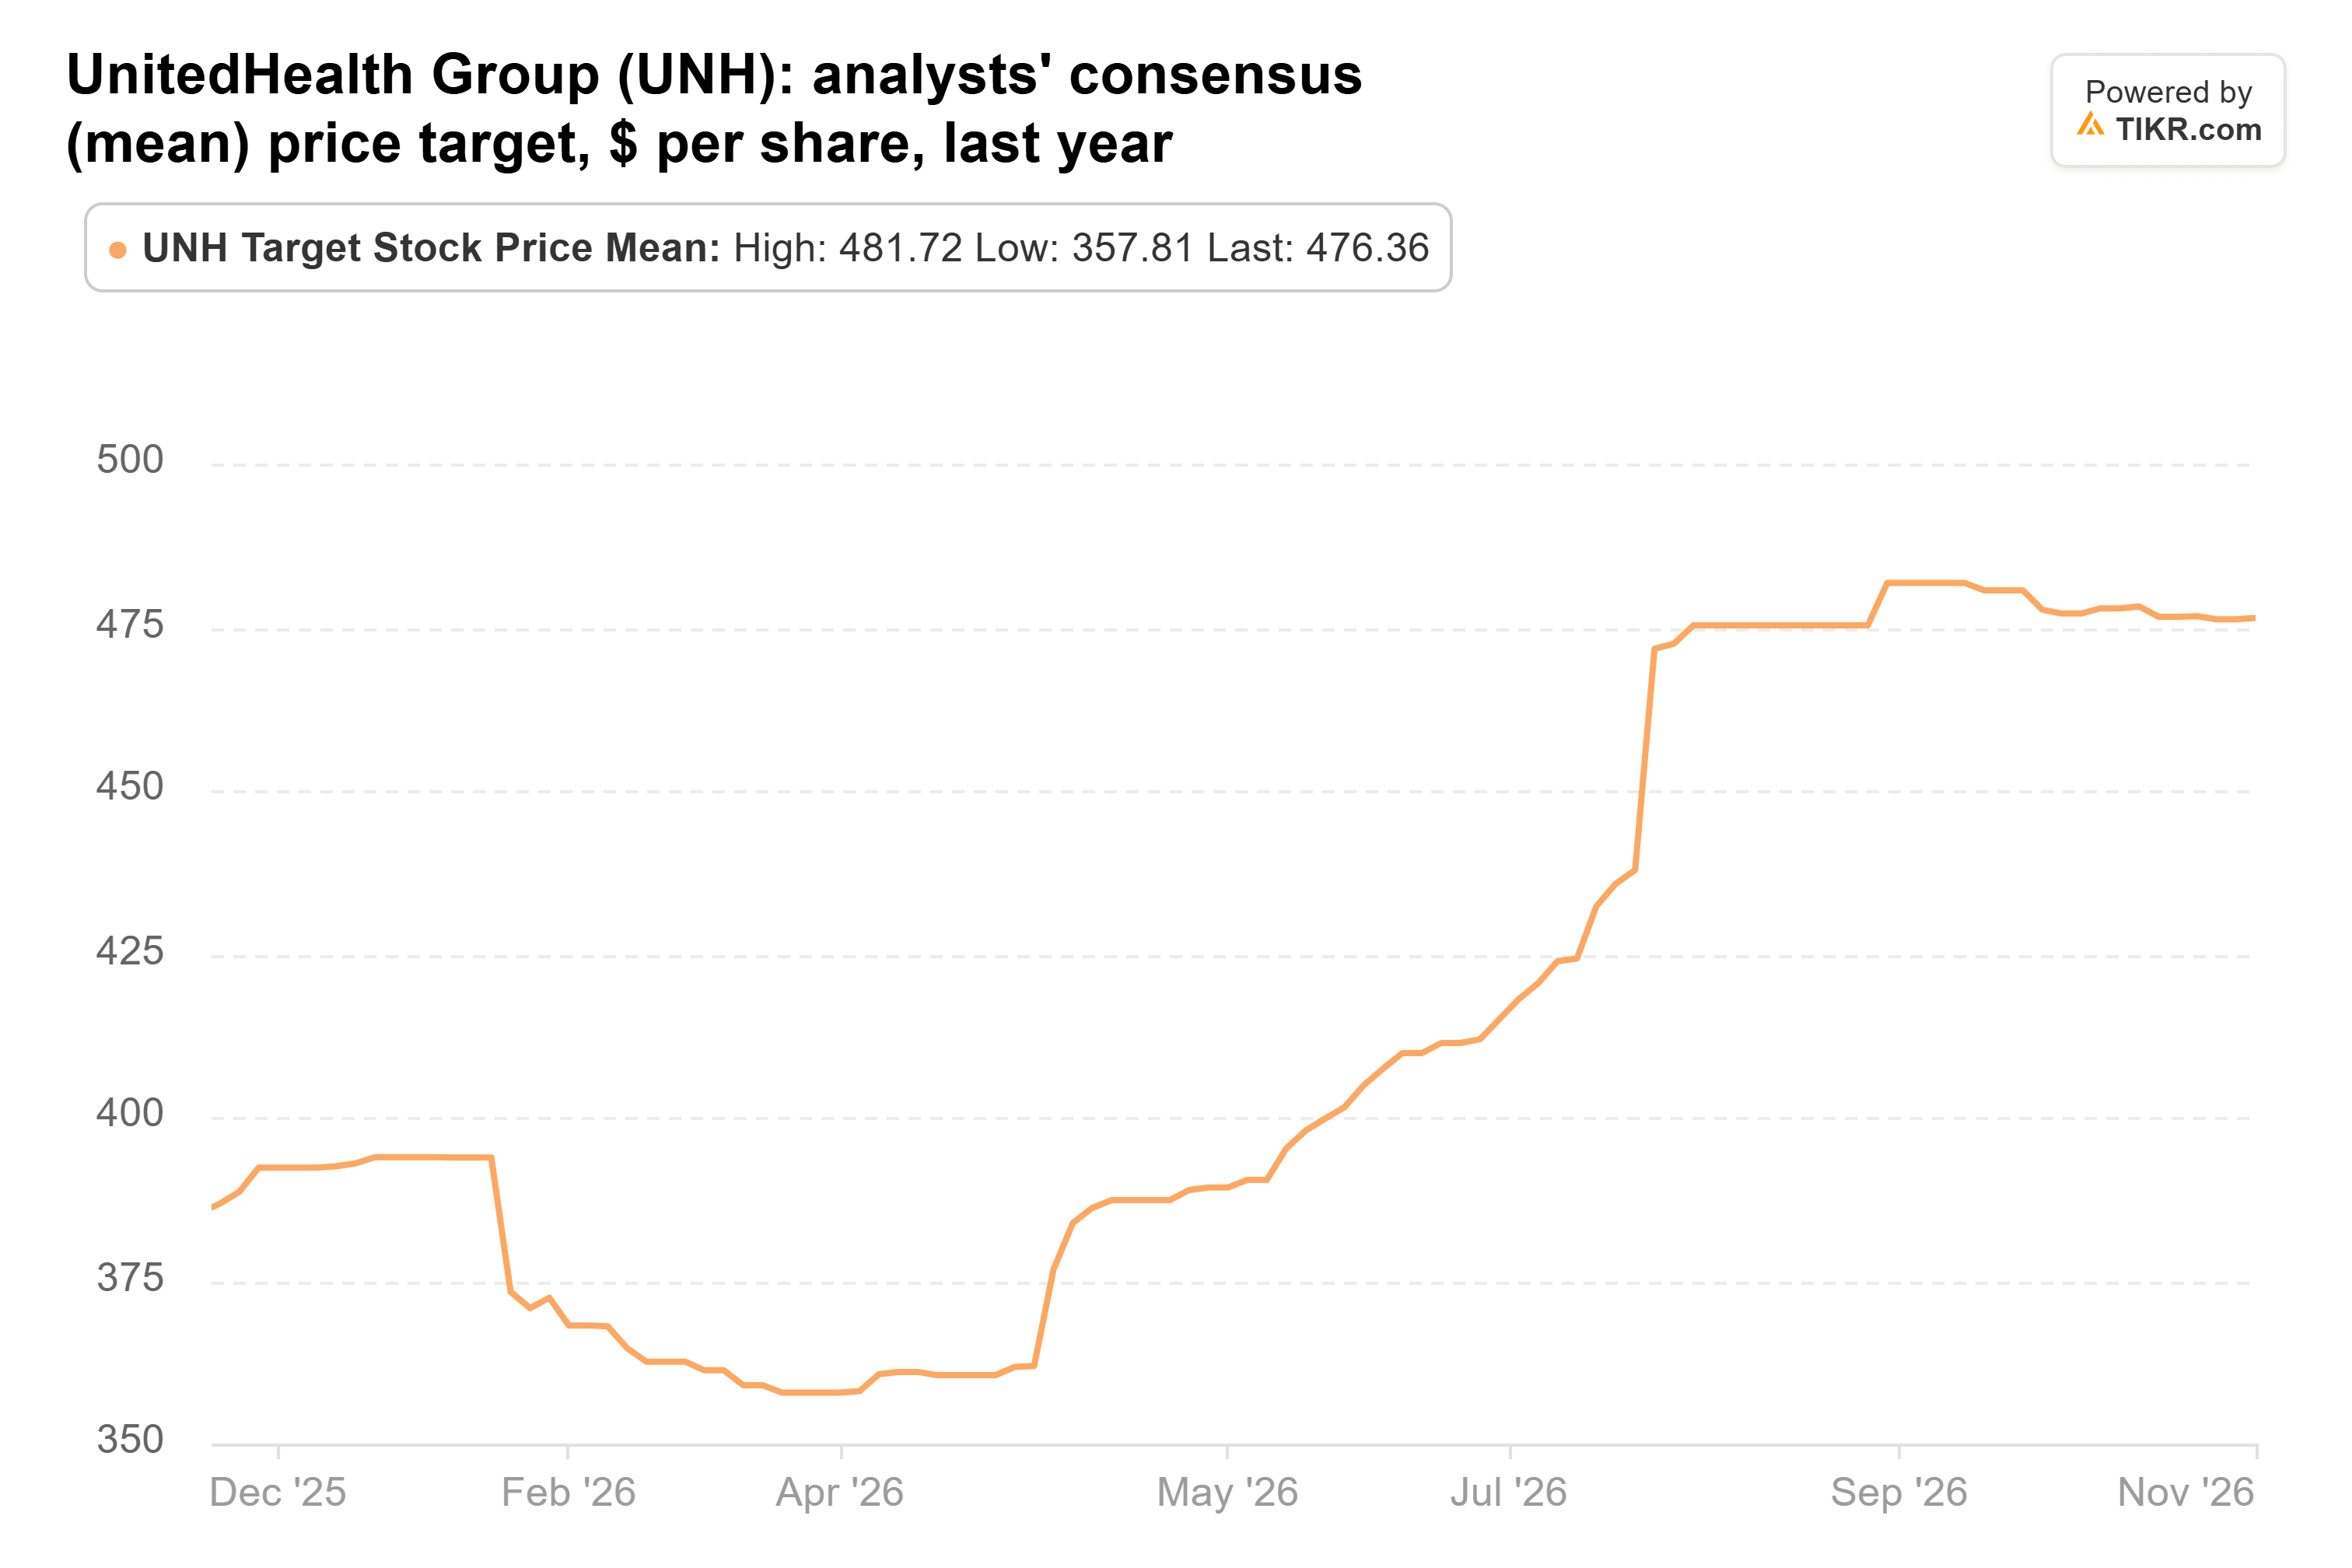
That’s 16% above Monday’s close of $412.02, from 26 analysts. At about 18x forward earnings, UnitedHealth trades just under its 19x average since 2014, so investors are paying for the recovery to keep going and not much more. The risk is political: with Democrats winning Congress, Sen. Elizabeth Warren has made UnitedHealth a target. Management has promised its 2027 outlook before the year is out, and that’s the next real test.
TIKR tracks 26 analysts on UnitedHealth. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on UnitedHealth, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See UnitedHealth’s Analyst Ratings
Analysts see little left in Charles River
Meridiem’s 246,979 Charles River shares were worth $56 million at June 30, 2.6% of its 13F stocks. The stock is up 48% since Sept. 30, and it has more than doubled in a year.
The business explains a good chunk of that. Charles River’s third-quarter release on Nov. 4 showed:
- 4.7% organic revenue growth, its second straight quarter of growth
- a non-GAAP operating margin up 330 basis points to 23.0%
- non-GAAP EPS up 27.2% to $3.09
It also raised its 2026 guidance to $11.35-$11.55 of non-GAAP EPS.
Analysts have spent the year catching up to the stock. The consensus target has climbed from $189 to $351, a new high this month:
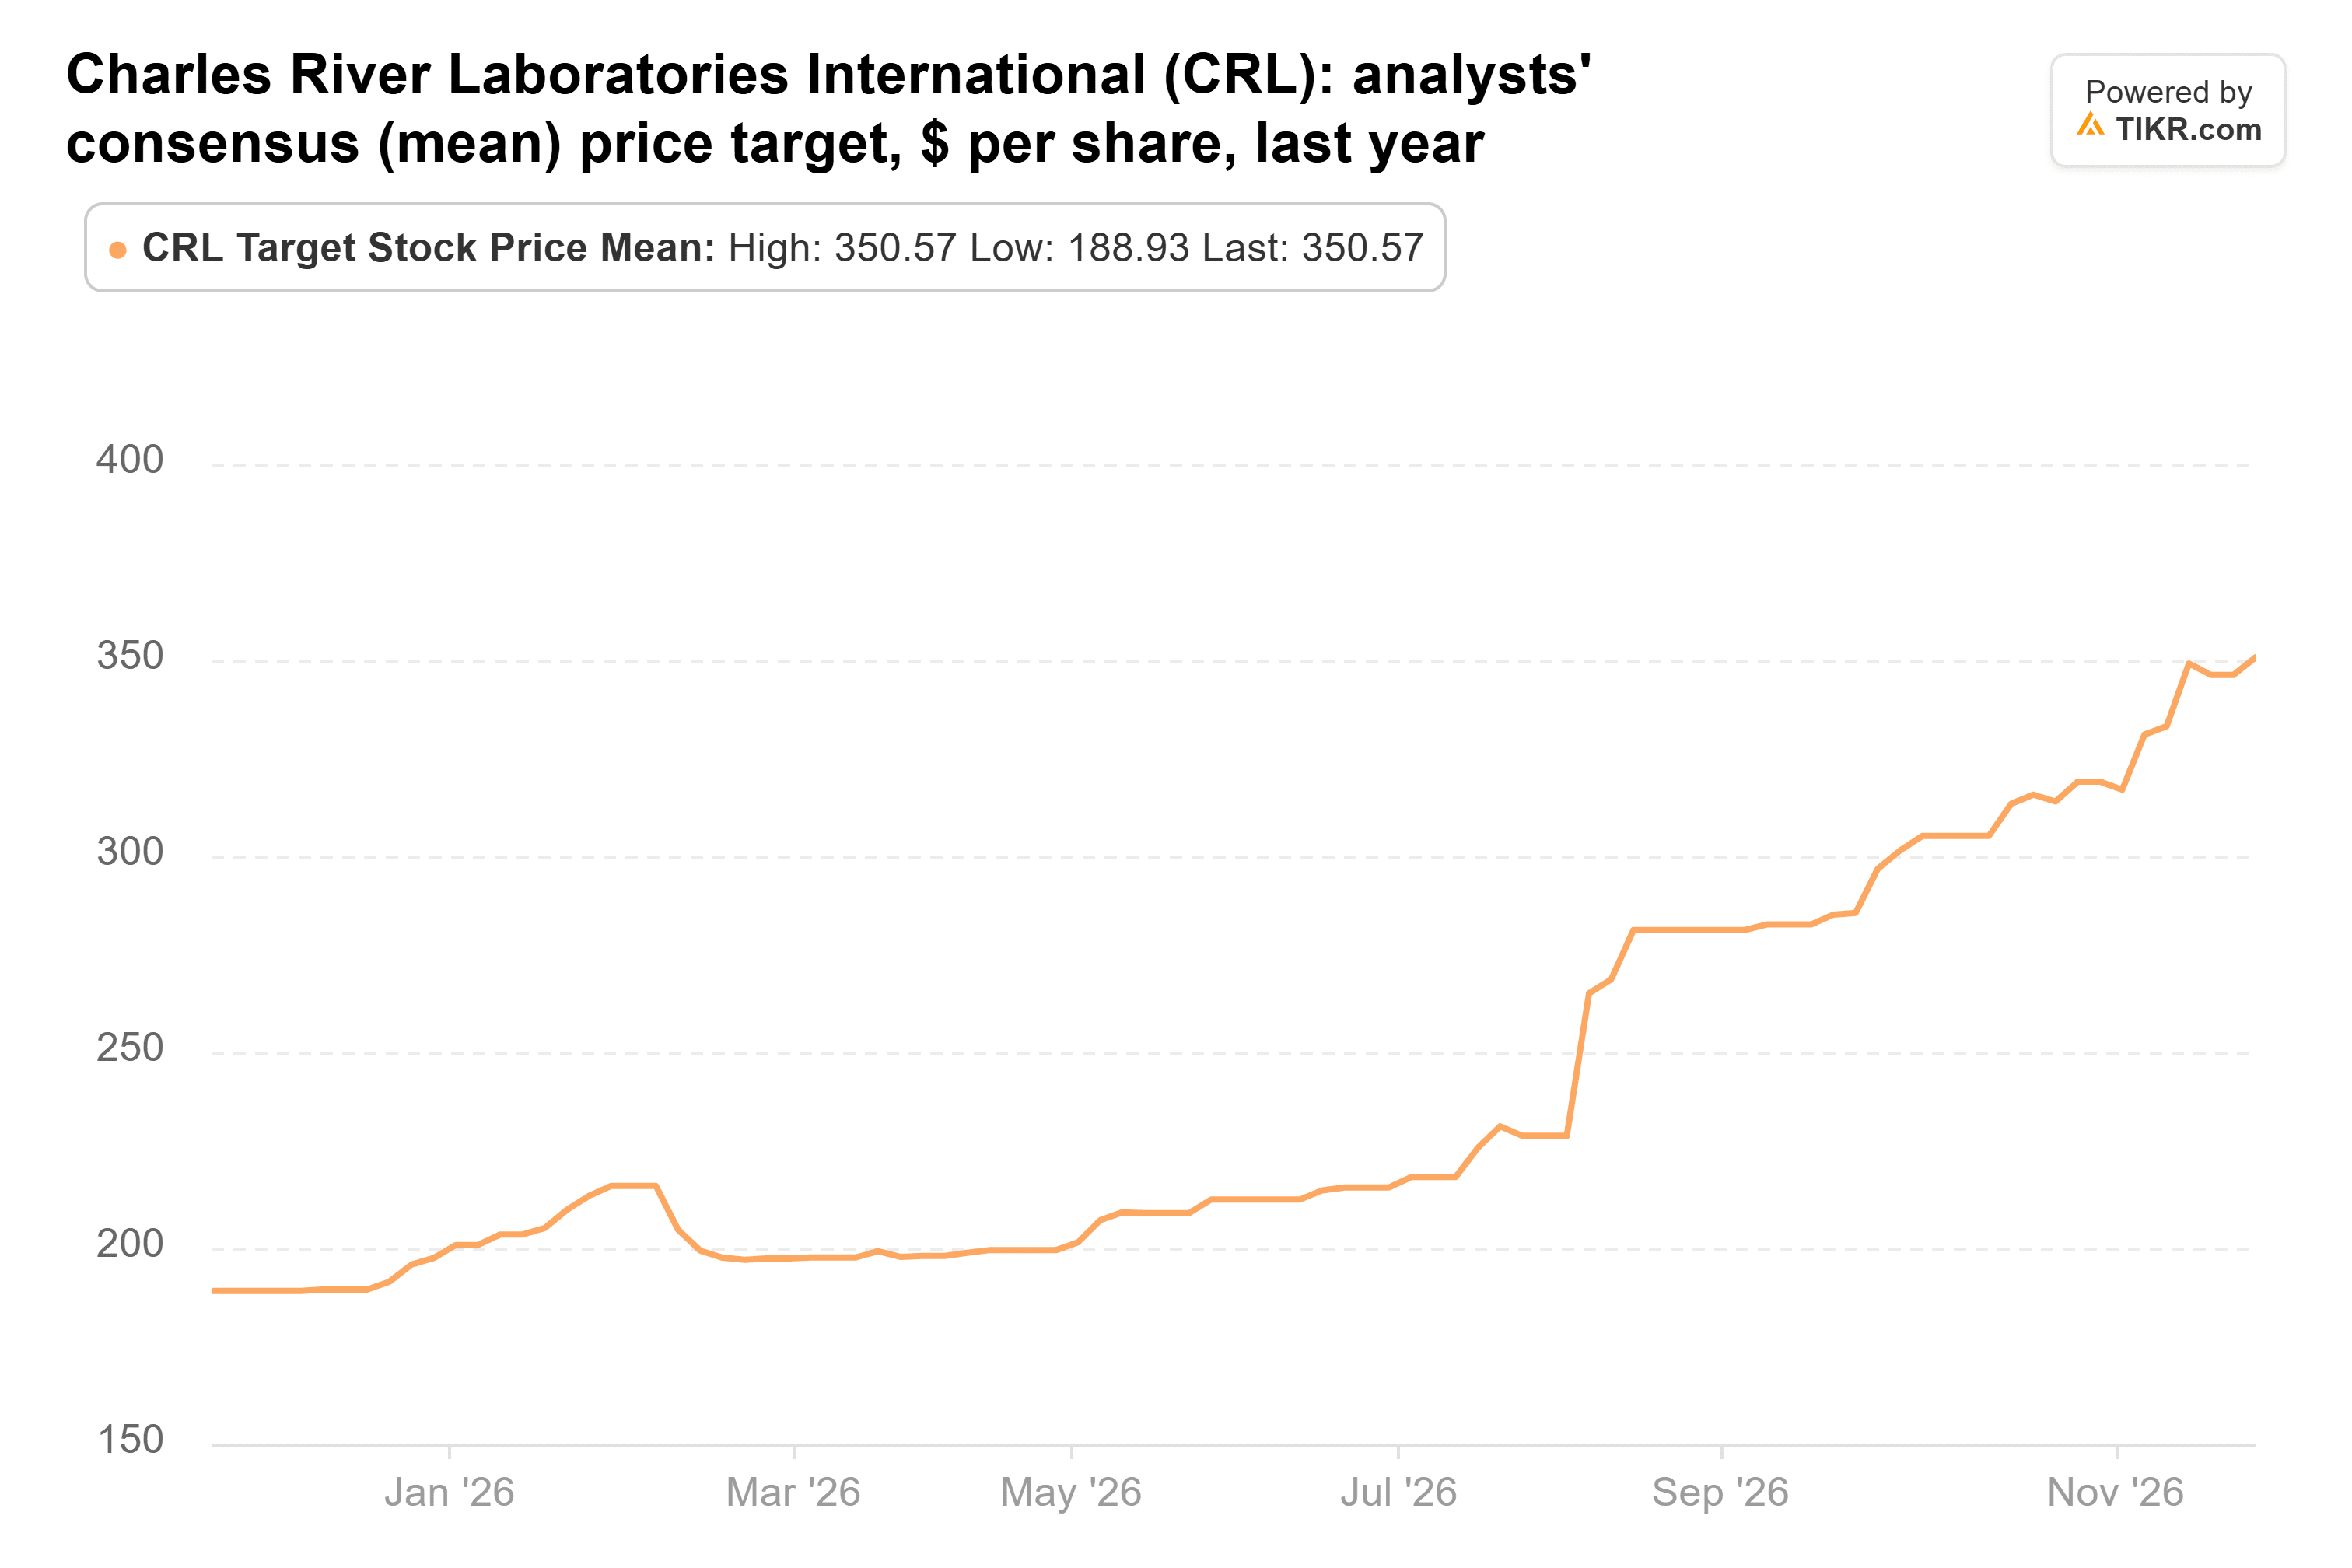
But that’s just 4% above Monday’s close of $335.52. At about 26x forward earnings, plenty of good news is already in the price, and the lowest of the 17 analysts’ targets is all the way down at $145. On the numbers alone, this is the easiest of the three exits to defend.
Alphabet is the exit I’d argue with
The fund’s 144,678 Alphabet shares were worth $52 million at June 30, 2.4% of its 13F stocks. Alphabet has had a much rougher stretch since. It’s down 21% since Sept. 30 and sits 31% below its 52-week high.
Analysts haven’t moved nearly as far. The consensus target has slipped from its July peak of $433, but at $400 it’s still above the $317 of a year ago:
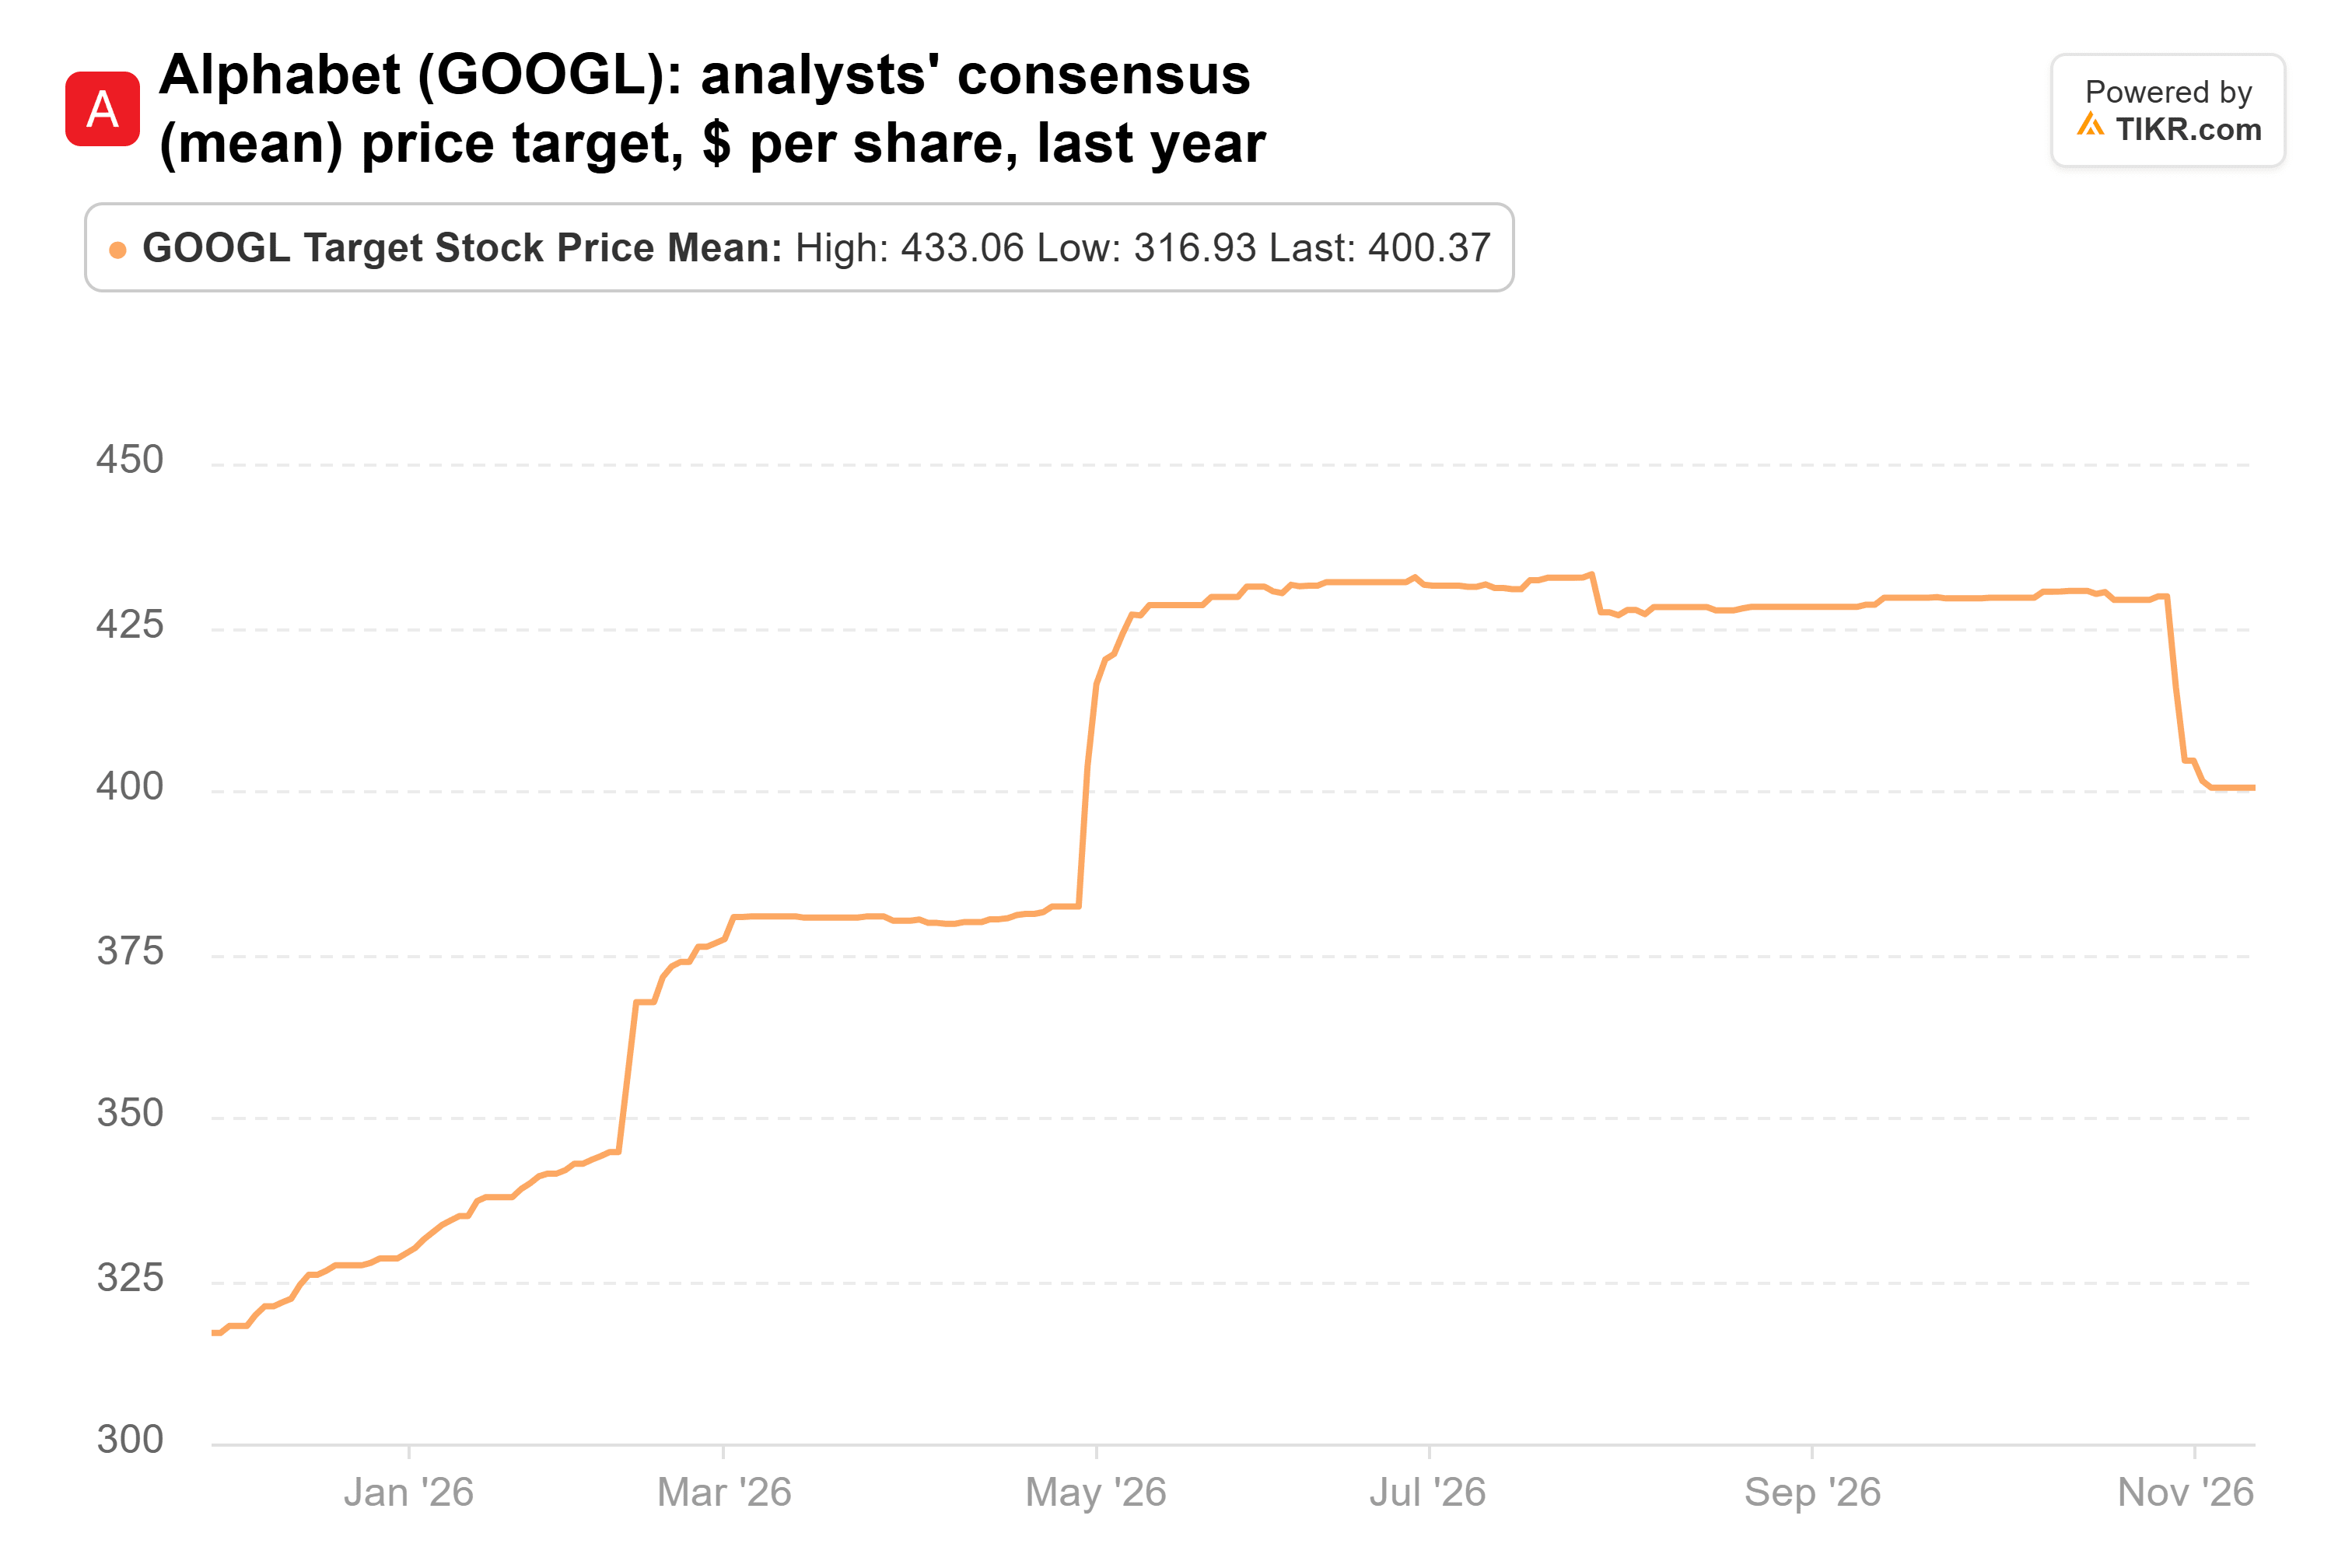
That’s 41% above Monday’s close of $283.72, from 58 analysts, and even the lowest target, $300, is above the price. At about 21x forward earnings, Alphabet is also cheaper than either of the fund’s two biggest holdings. The bulls have a growth story to point to, too: Morgan Stanley sees Alphabet’s TPU sales jumping to $84 billion. The near-term worry is Anthropic, which Alphabet has backed. Anthropic’s lock-ups free nearly 40% of the deal on day one, a real risk for Alphabet’s shares.
Its two biggest bets cost more
By Sept. 30, Microsoft was Meridiem’s No. 1 position: 353,536 shares worth $181 million, or 7.7% of its 13F stocks, all of it new in the quarter. Visa was No. 2, at 306,970 shares worth $110 million, or 4.7%.
Microsoft is up just 1% since Sept. 30, and analysts see 23% upside to their $636 average target. At about 25x forward earnings, it trades right around its 26x average since 2014. Visa is up 19% since Sept. 30, so its $449 average target is now just 5% above the price. It trades at about 28x forward earnings, in line with its own long-run average.
If I could buy back one, it’s Alphabet
The Charles River and UnitedHealth exits are easy to live with. Alphabet is different. If I could only buy back one of the three, it’d be Alphabet: the average target is 41% above the price, and not one analyst has a target below today’s price. The risk is that the consensus target has drifted lower since July, and another leg down would mean analysts are losing faith too.
Of course, Meridiem’s next 13F, due in mid-February, will show whether it owns any of the three again.
So what is UnitedHealth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what UnitedHealth could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



