Key Takeaways
- Seth Klarman’s Baupost Group took a new position in Honeywell Aerospace in the third quarter: 1.13 million shares, worth $175 million at Sept. 30.
- The stock is 45% below its 52-week high because supply shortages have held back how much the newly spun-off company can deliver.
- Honeywell Aerospace trades at about 20x forward earnings, below its average since the spin-off, and analysts expect its earnings to grow every year through 2028.
- The numbers back Klarman’s buy, as long as supply eases in 2027 the way management expects.
Seth Klarman is one of the best-known value investors around, and his latest filing shows him buying a spin-off that has lost nearly half its value from its high. Baupost Group’s 13F for the quarter ended Sept. 30, filed Nov. 13, shows a new position in Honeywell Aerospace (HONA): 1.13 million shares, worth $175 million at quarter-end.
Baupost manages $25 billion in all, and its 13F holds $5.05 billion of US stocks across 21 positions. The new stake is 3.5% of its 13F stocks, its 12th largest. The stock is up 5% from its Sept. 30 price, though the filing doesn’t say when in the quarter Baupost bought or what it paid.
TIKR tracks 17 analysts on Honeywell Aerospace. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Honeywell Aerospace, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Honeywell Aerospace’s Analyst Ratings
Supply problems sank the spin-off
Honeywell Aerospace finished its spin-off from Honeywell on June 29, and the trouble showed up in its first report. With its second-quarter results, it revised its full-year sales and adjusted EBIT guidance. CEO Jim Currier said “it is prudent to align our guidance to our supply chain’s demonstrated capabilities at the end of the second quarter.”
The third quarter looked better. Sales rose 2% organically to $4.6 billion, management raised its full-year adjusted EPS guidance, and the board declared a first quarterly dividend of $0.40 a share. The stock still sank 11% after the report as supply constraints persisted.
CFO Josh Jepsen said on the call that strong domestic defense demand “is intensifying supply constraints in this end market and deferring accretive international sales, which declined in the quarter.” Customers want more than Honeywell Aerospace can build right now.
Do the numbers back Klarman?
Analysts expect earnings to climb every year through 2028:
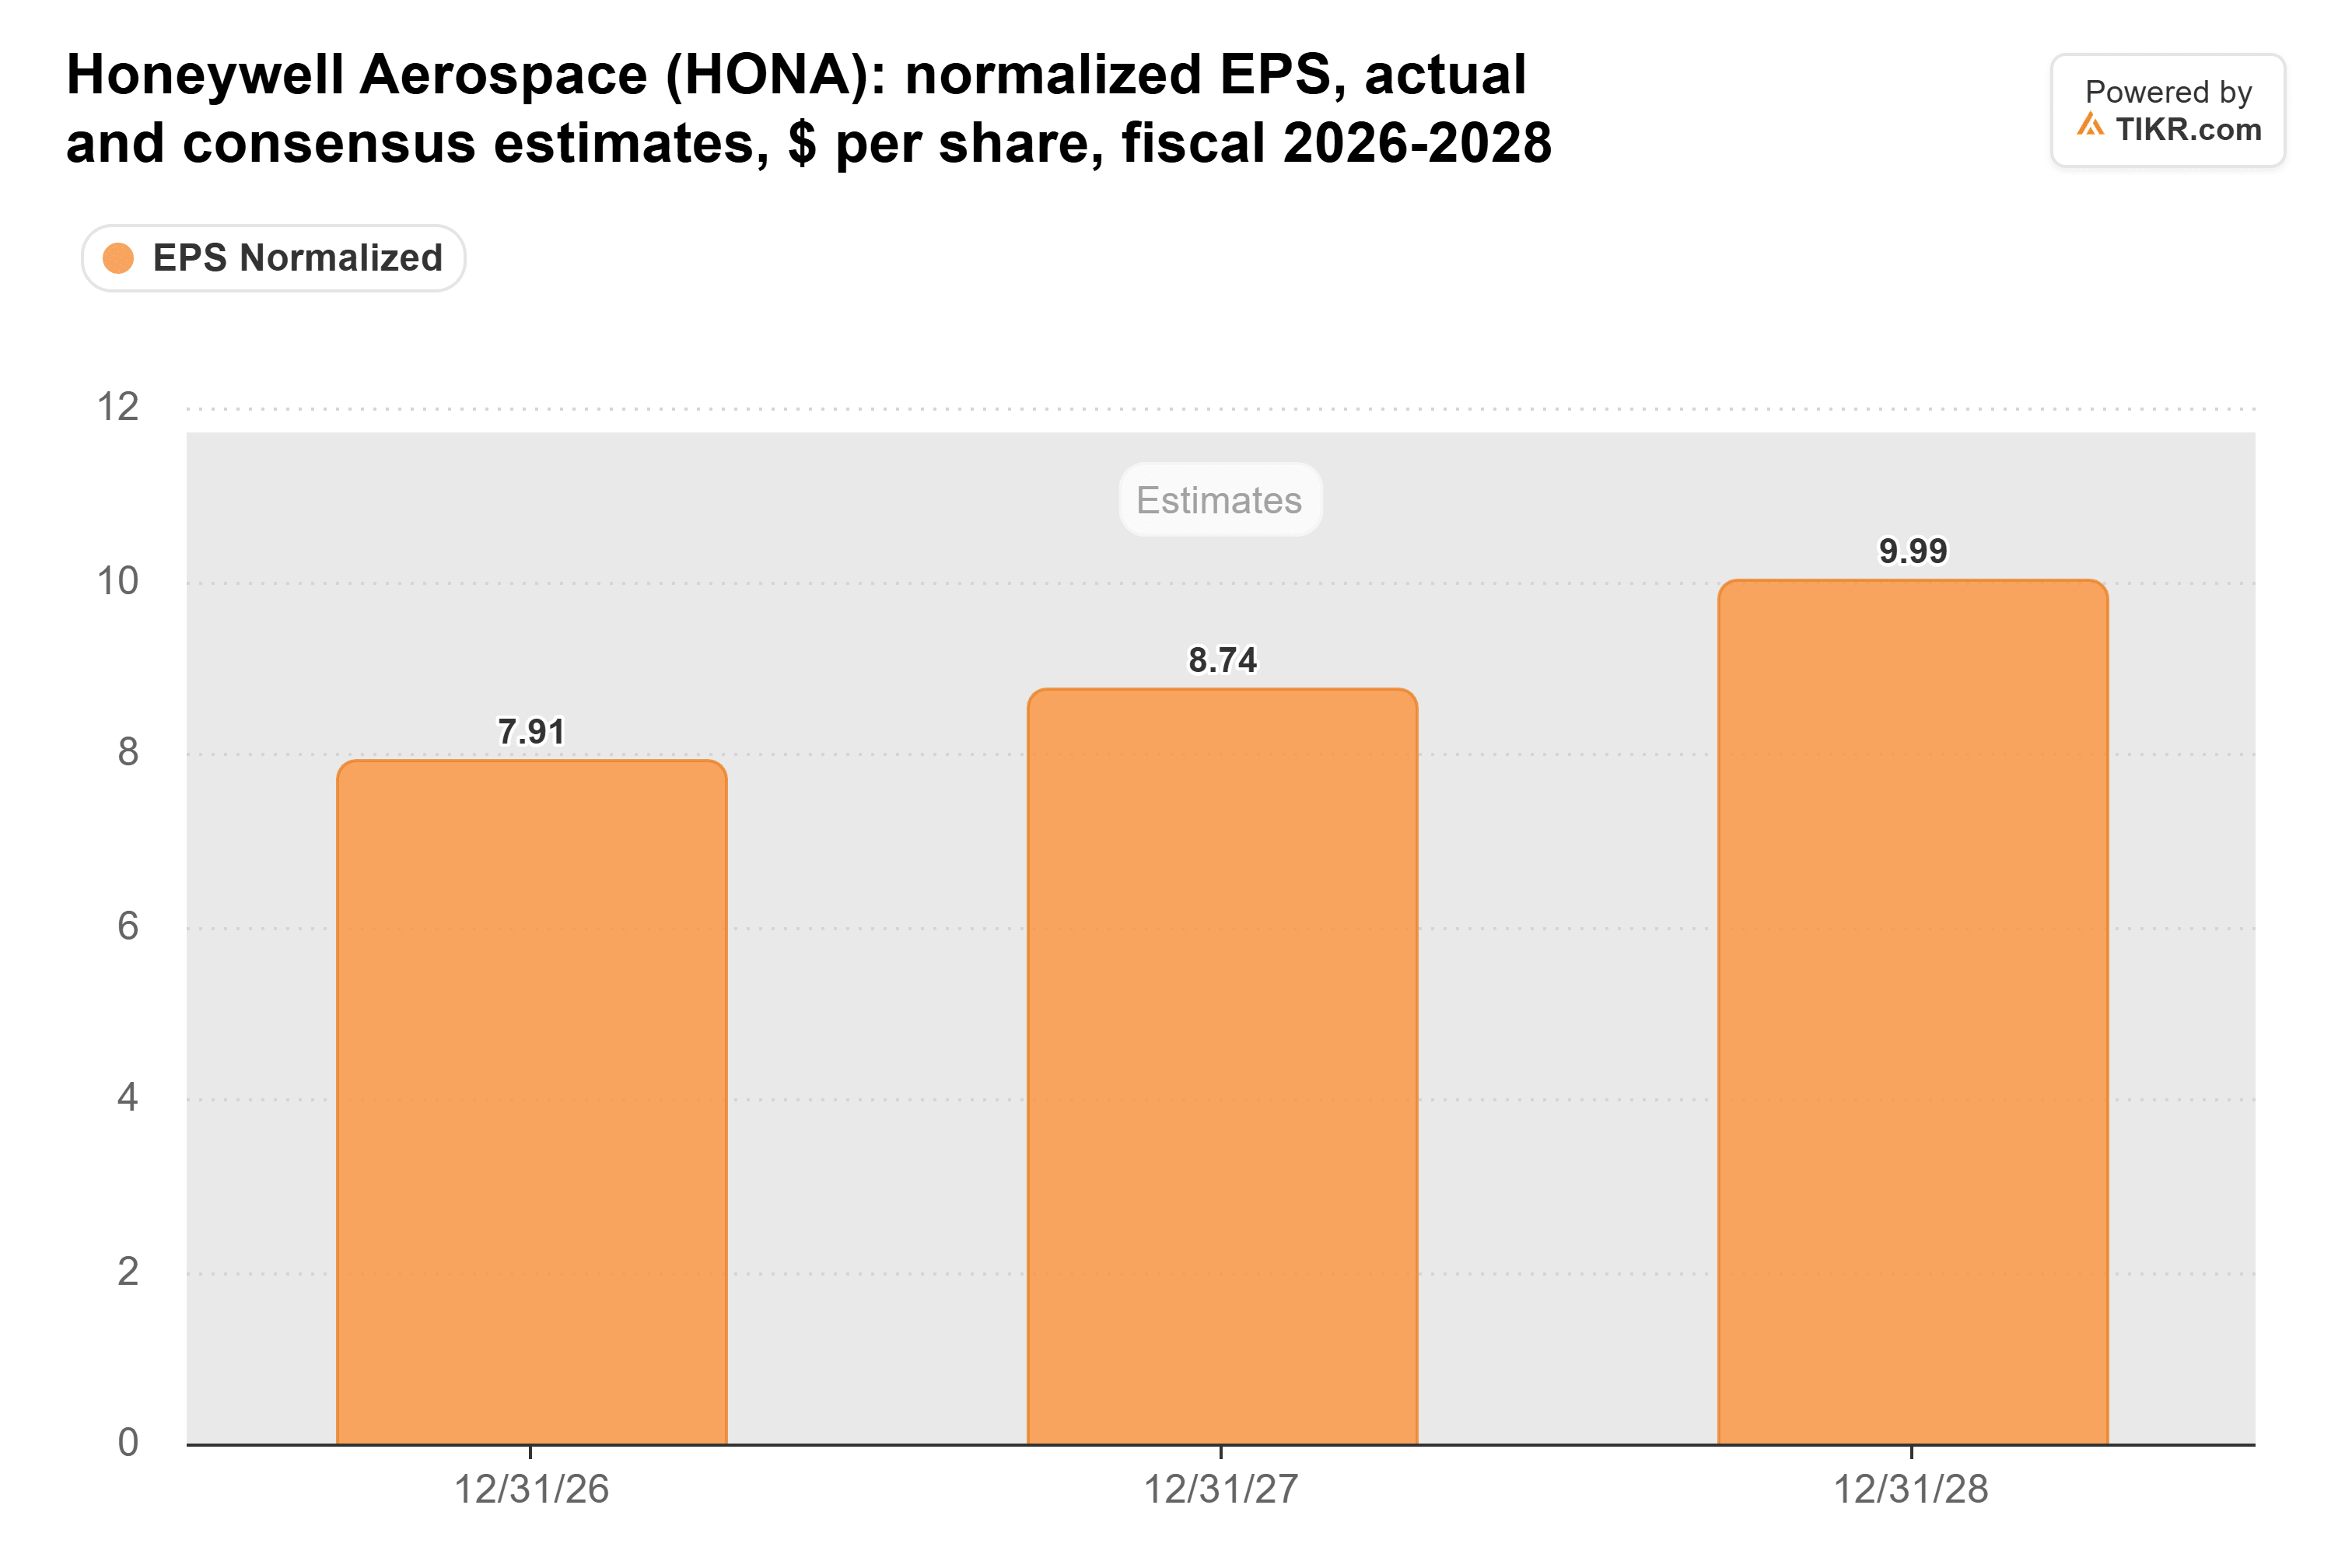
That’s $7.91 a share this year, $8.74 in 2027 and $9.99 in 2028, which is double-digit growth in each of the next two years. Even with the supply problems, the Street sees a growing business.
The stock doesn’t price in much of that growth. Honeywell Aerospace trades at 20x forward earnings, a bit below its 21x average since it listed:
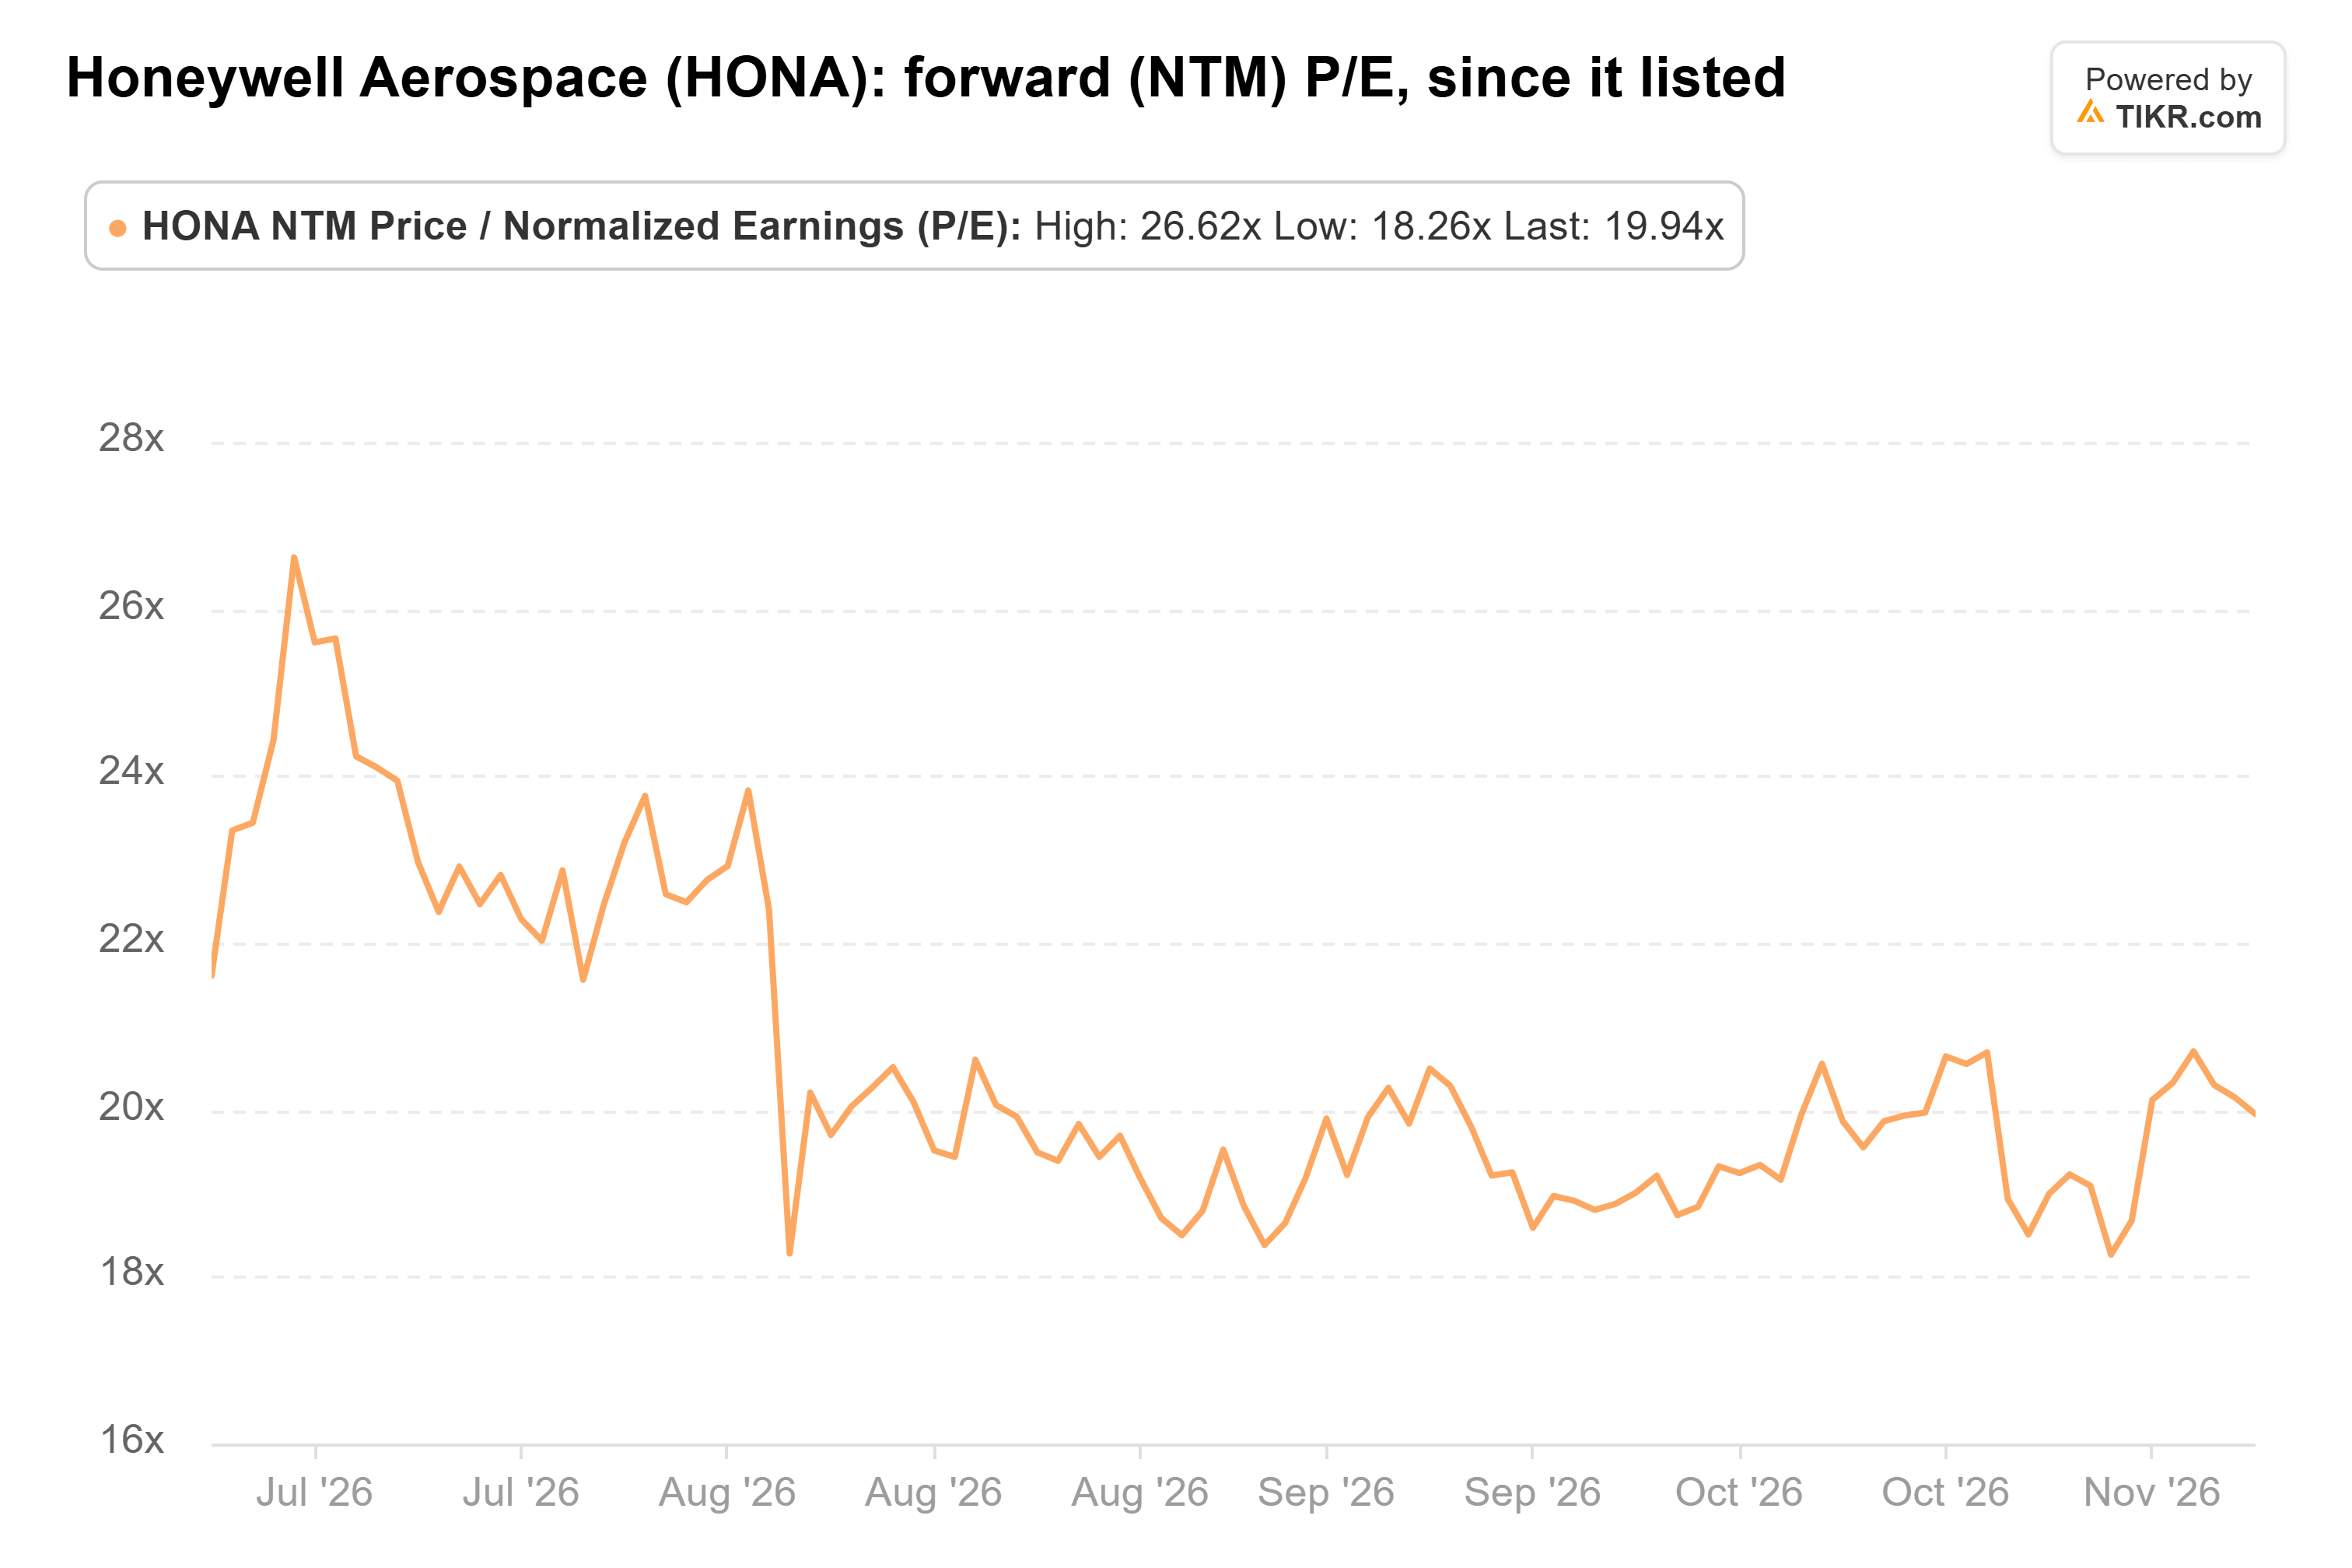
It peaked at 27x in early July and hit a low of 18x on Nov. 5. Five months is a short history, but the trend is clear: investors have marked the stock down much faster than analysts have cut their earnings estimates.
Analysts have also lowered their price targets sharply since the spin-off. The consensus target has fallen from $300 at listing to $193:
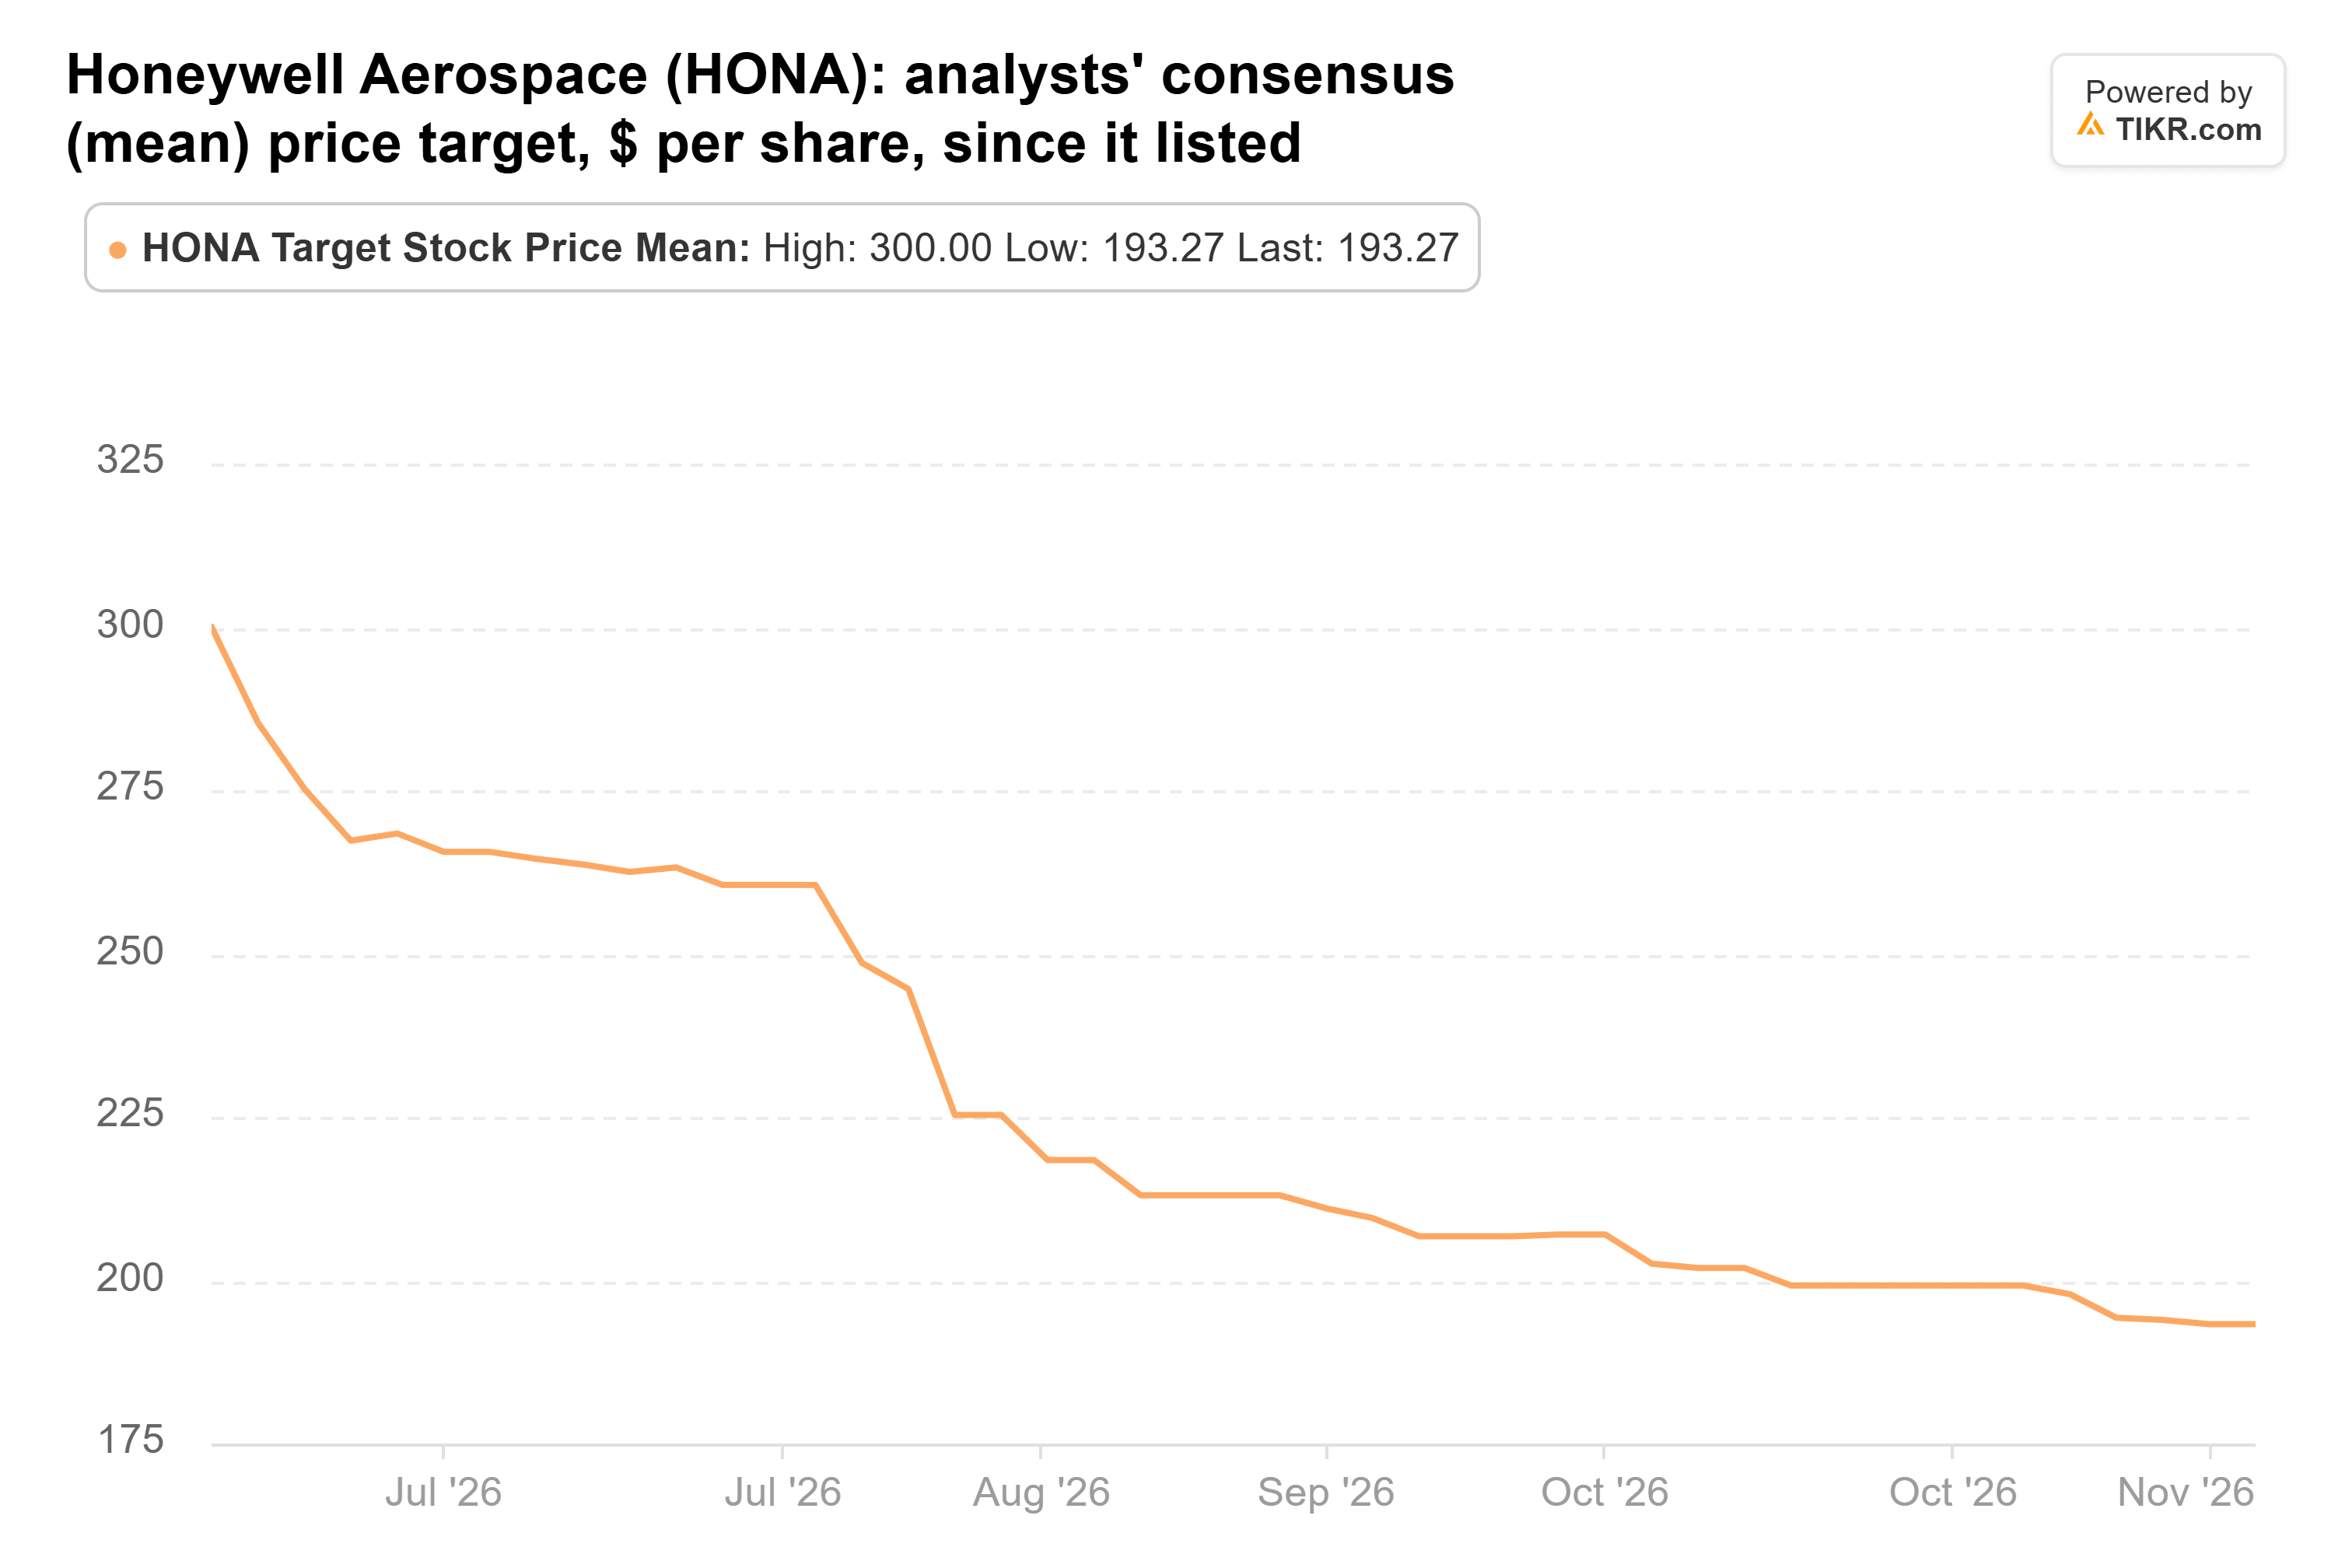
That $193 average, from 17 analysts, is 18% above the last close of $163.36. Even the lowest target, $170, is above the stock’s price, and the highest is $261. Expectations are now a lot more modest than they were in June. That gives Honeywell Aerospace an easier bar to clear.
Supply decides this one
The risk is simple: if suppliers don’t catch up, the earnings estimates in that first chart will come down, and a cheap multiple won’t look so cheap. Management said on the call that a second bearings supplier is ramping up and that another supplier should add capacity in the second quarter of 2027. That’s the timeline to hold it to.
Bottom line: the numbers back Klarman. A company whose problem is too much demand, trading below its own average multiple with earnings expected to grow and every analyst’s target above the price, is a setup worth owning. At 3.5% of Baupost’s 13F stocks, it’s a real bet without being a reckless one.
Of course, the supply fix is still a plan. The fourth-quarter report, expected early next year, should show whether output is really catching up. Baupost’s next 13F, due in mid-February, will show whether Klarman added to the stake.
So what is Honeywell Aerospace stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Honeywell Aerospace could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Honeywell Aerospace for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!