Key Takeaways
- Upstart fell [8%] today after BofA cut its price target to $30 from $37, a day before its third-quarter report.
- SoFi and Affirm rose and Pagaya just posted a record quarter, so the selling looks specific to Upstart.
- Upstart needs about $727 million of revenue and $177 million of adjusted EBITDA in the second half to hit its guidance.
- The stock trades far below its usual multiple, so holding the guide Tuesday would go a long way.
Upstart (UPST) sank 7% today after BofA cut its price target to $30 from $37. Upstart reports third-quarter results Tuesday morning.
Investors didn’t sell the rest of fintech lending with it. SoFi Technologies (SOFI) and Affirm (AFRM) rose modestly, and Pagaya Technologies (PGY) is coming off a record quarter.
Upstart needs a second half like its second quarter
Analysts expect revenue to climb to $1.42 billion this year and $1.86 billion in 2027:
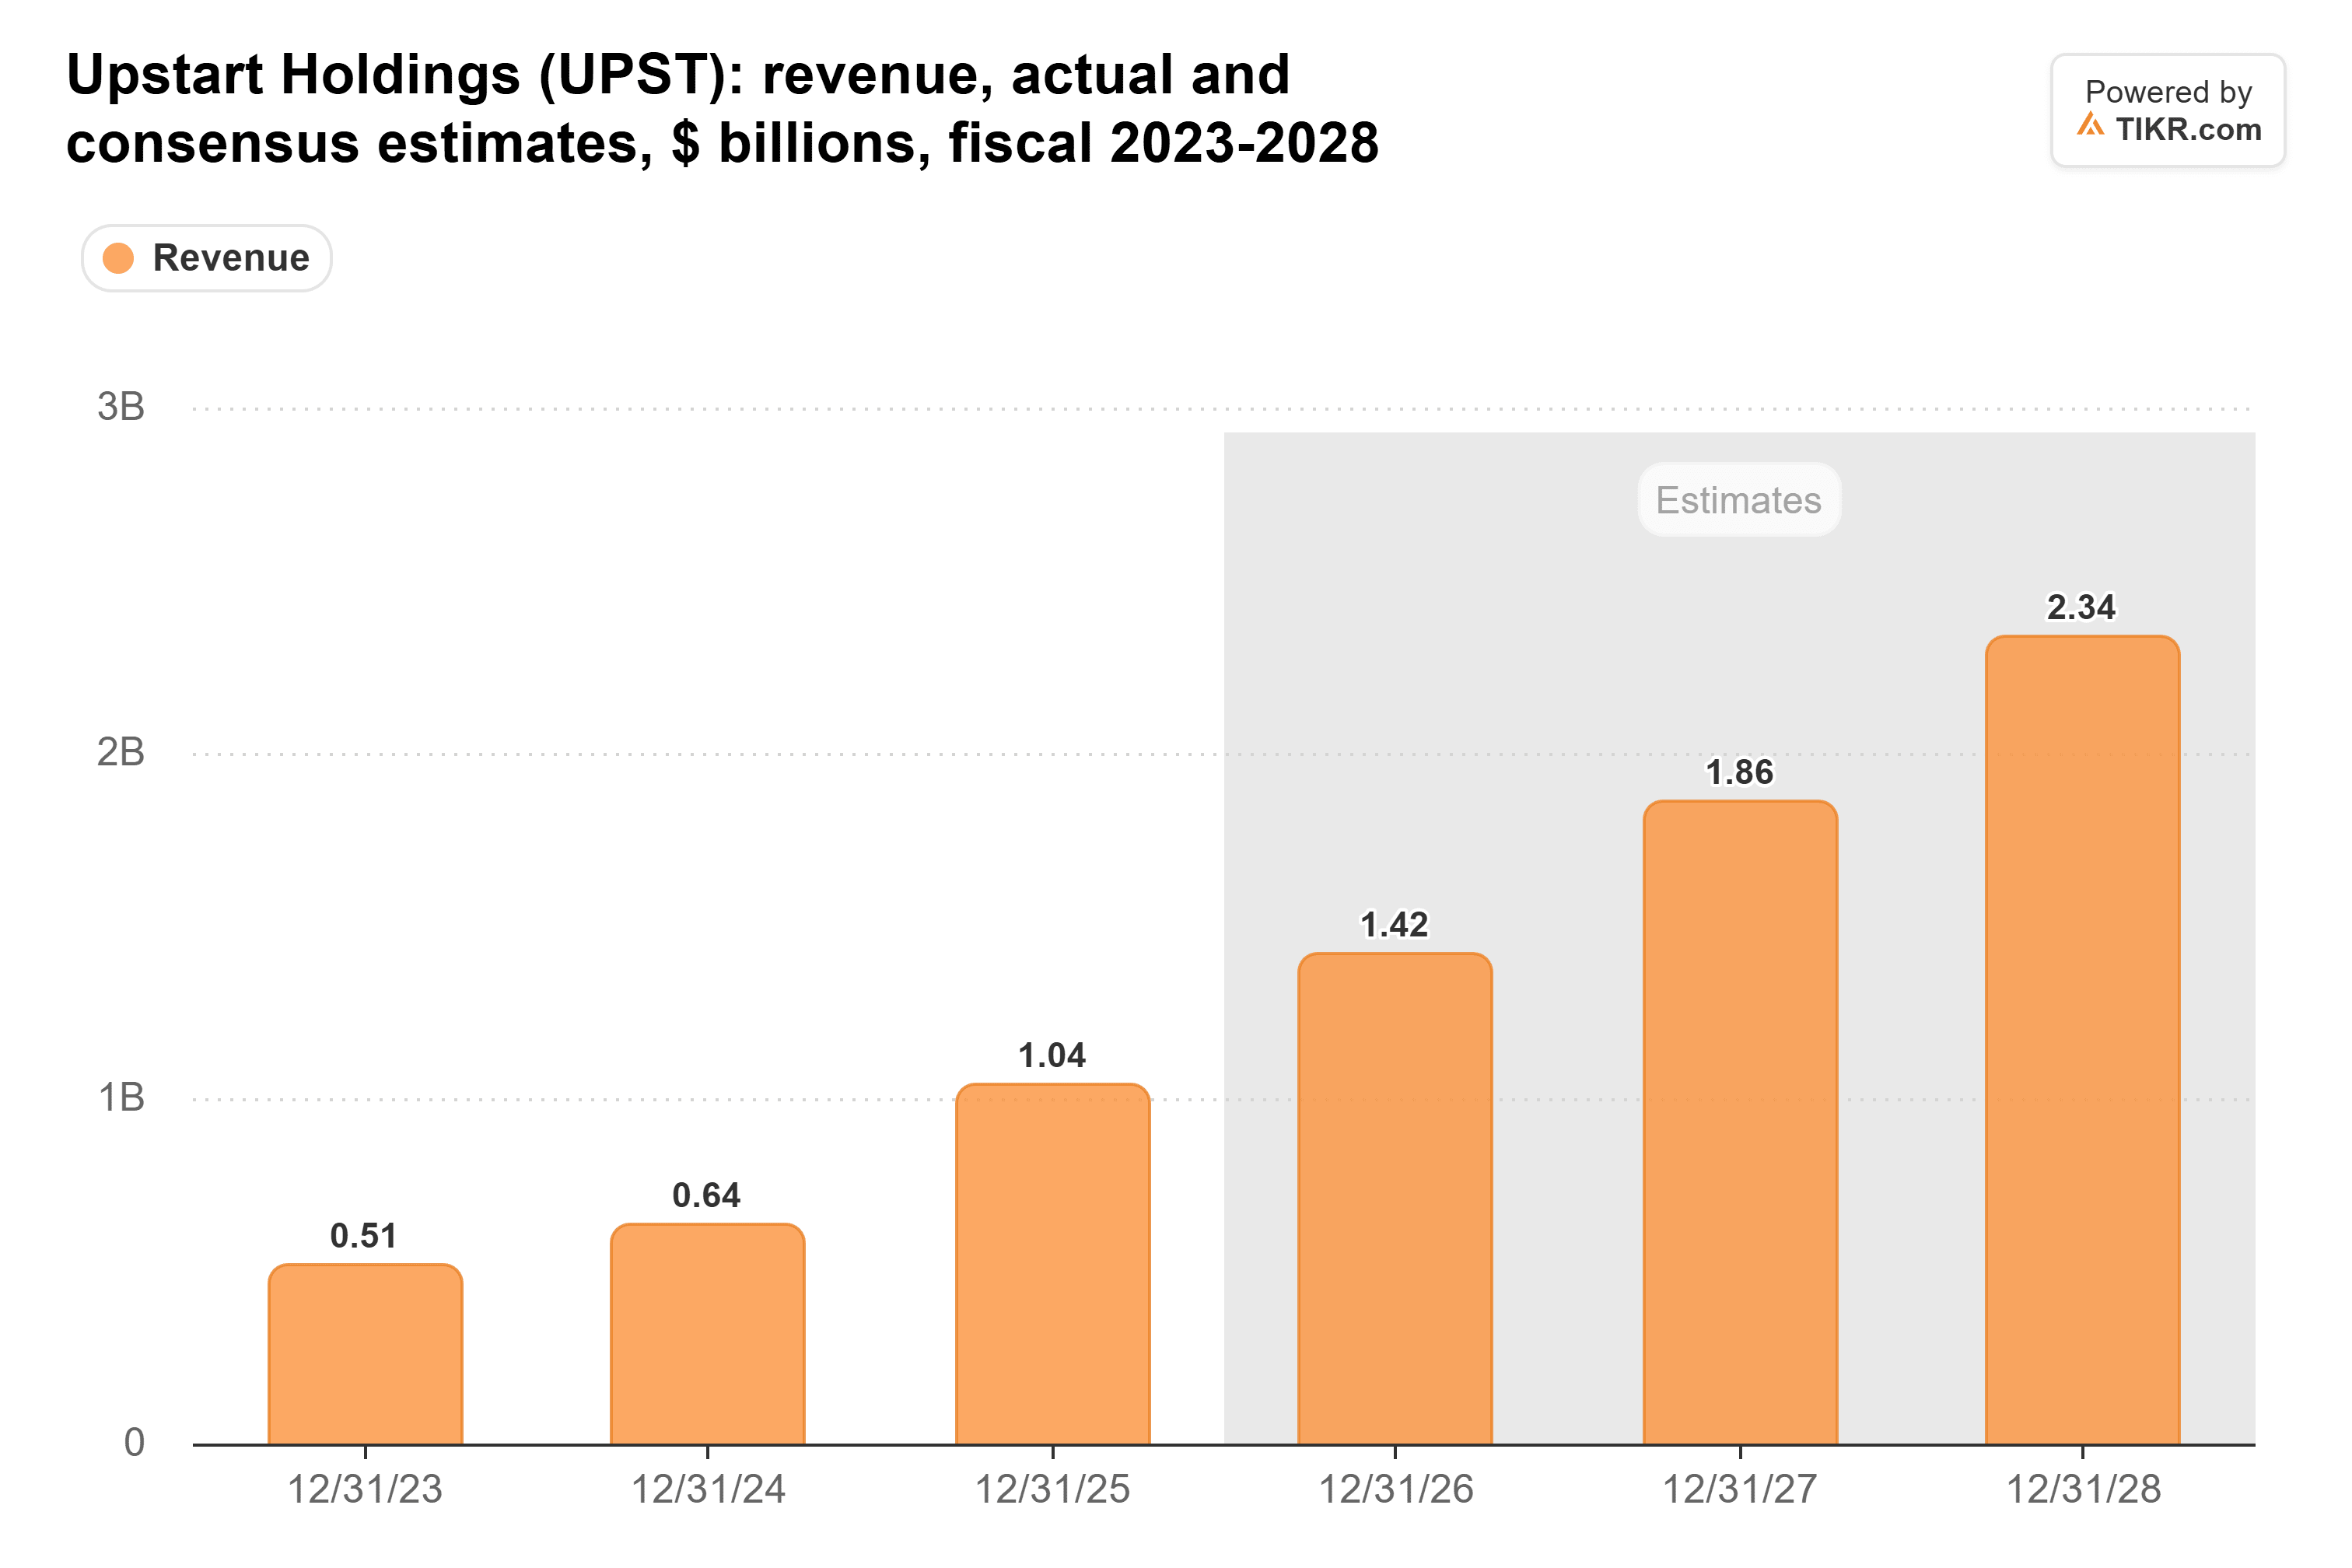
That 2026 estimate matches management’s guide of about $1.4 billion, so a reaffirmed guide on Tuesday would leave it standing.
Upstart made $672.9 million of revenue and $117.4 million of adjusted EBITDA in the first half. To hit its guide, it needs about $727 million and $177 million in the second half. That’s two more quarters like the second quarter’s $364.7 million of revenue, at a 24% margin against 21% then.
TIKR tracks 16 analysts on Upstart. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Upstart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Upstart’s Analyst Ratings
The loan buyers haven’t gone anywhere
Pagaya’s network volume rose 29% from a year earlier to a record $3.6 billion in the third quarter. So if Upstart’s volume disappoints on Tuesday, that’s on Upstart.
SoFi has a funding edge Upstart lacks: deposits made up 90% of its average liabilities in its record third quarter. Upstart is building its own bank, which still needs FDIC and Federal Reserve approval before a planned launch in early 2027.
Affirm reports Thursday. Like Upstart, it relies on outside investors to fund its loans, and its outlook assumes short-term rates rise. Does its margin hold up with funding costing more?
Cheap, with a catch
Upstart traded at 7.6x forward earnings at Friday’s close, against about 14x on average over the past year. But that’s on normalized earnings: analysts expect $3.57 a share for 2027 on that basis, against $1.88 under GAAP.
BofA’s $30 is also below the Street’s average target of $38, which has roughly halved in a year:
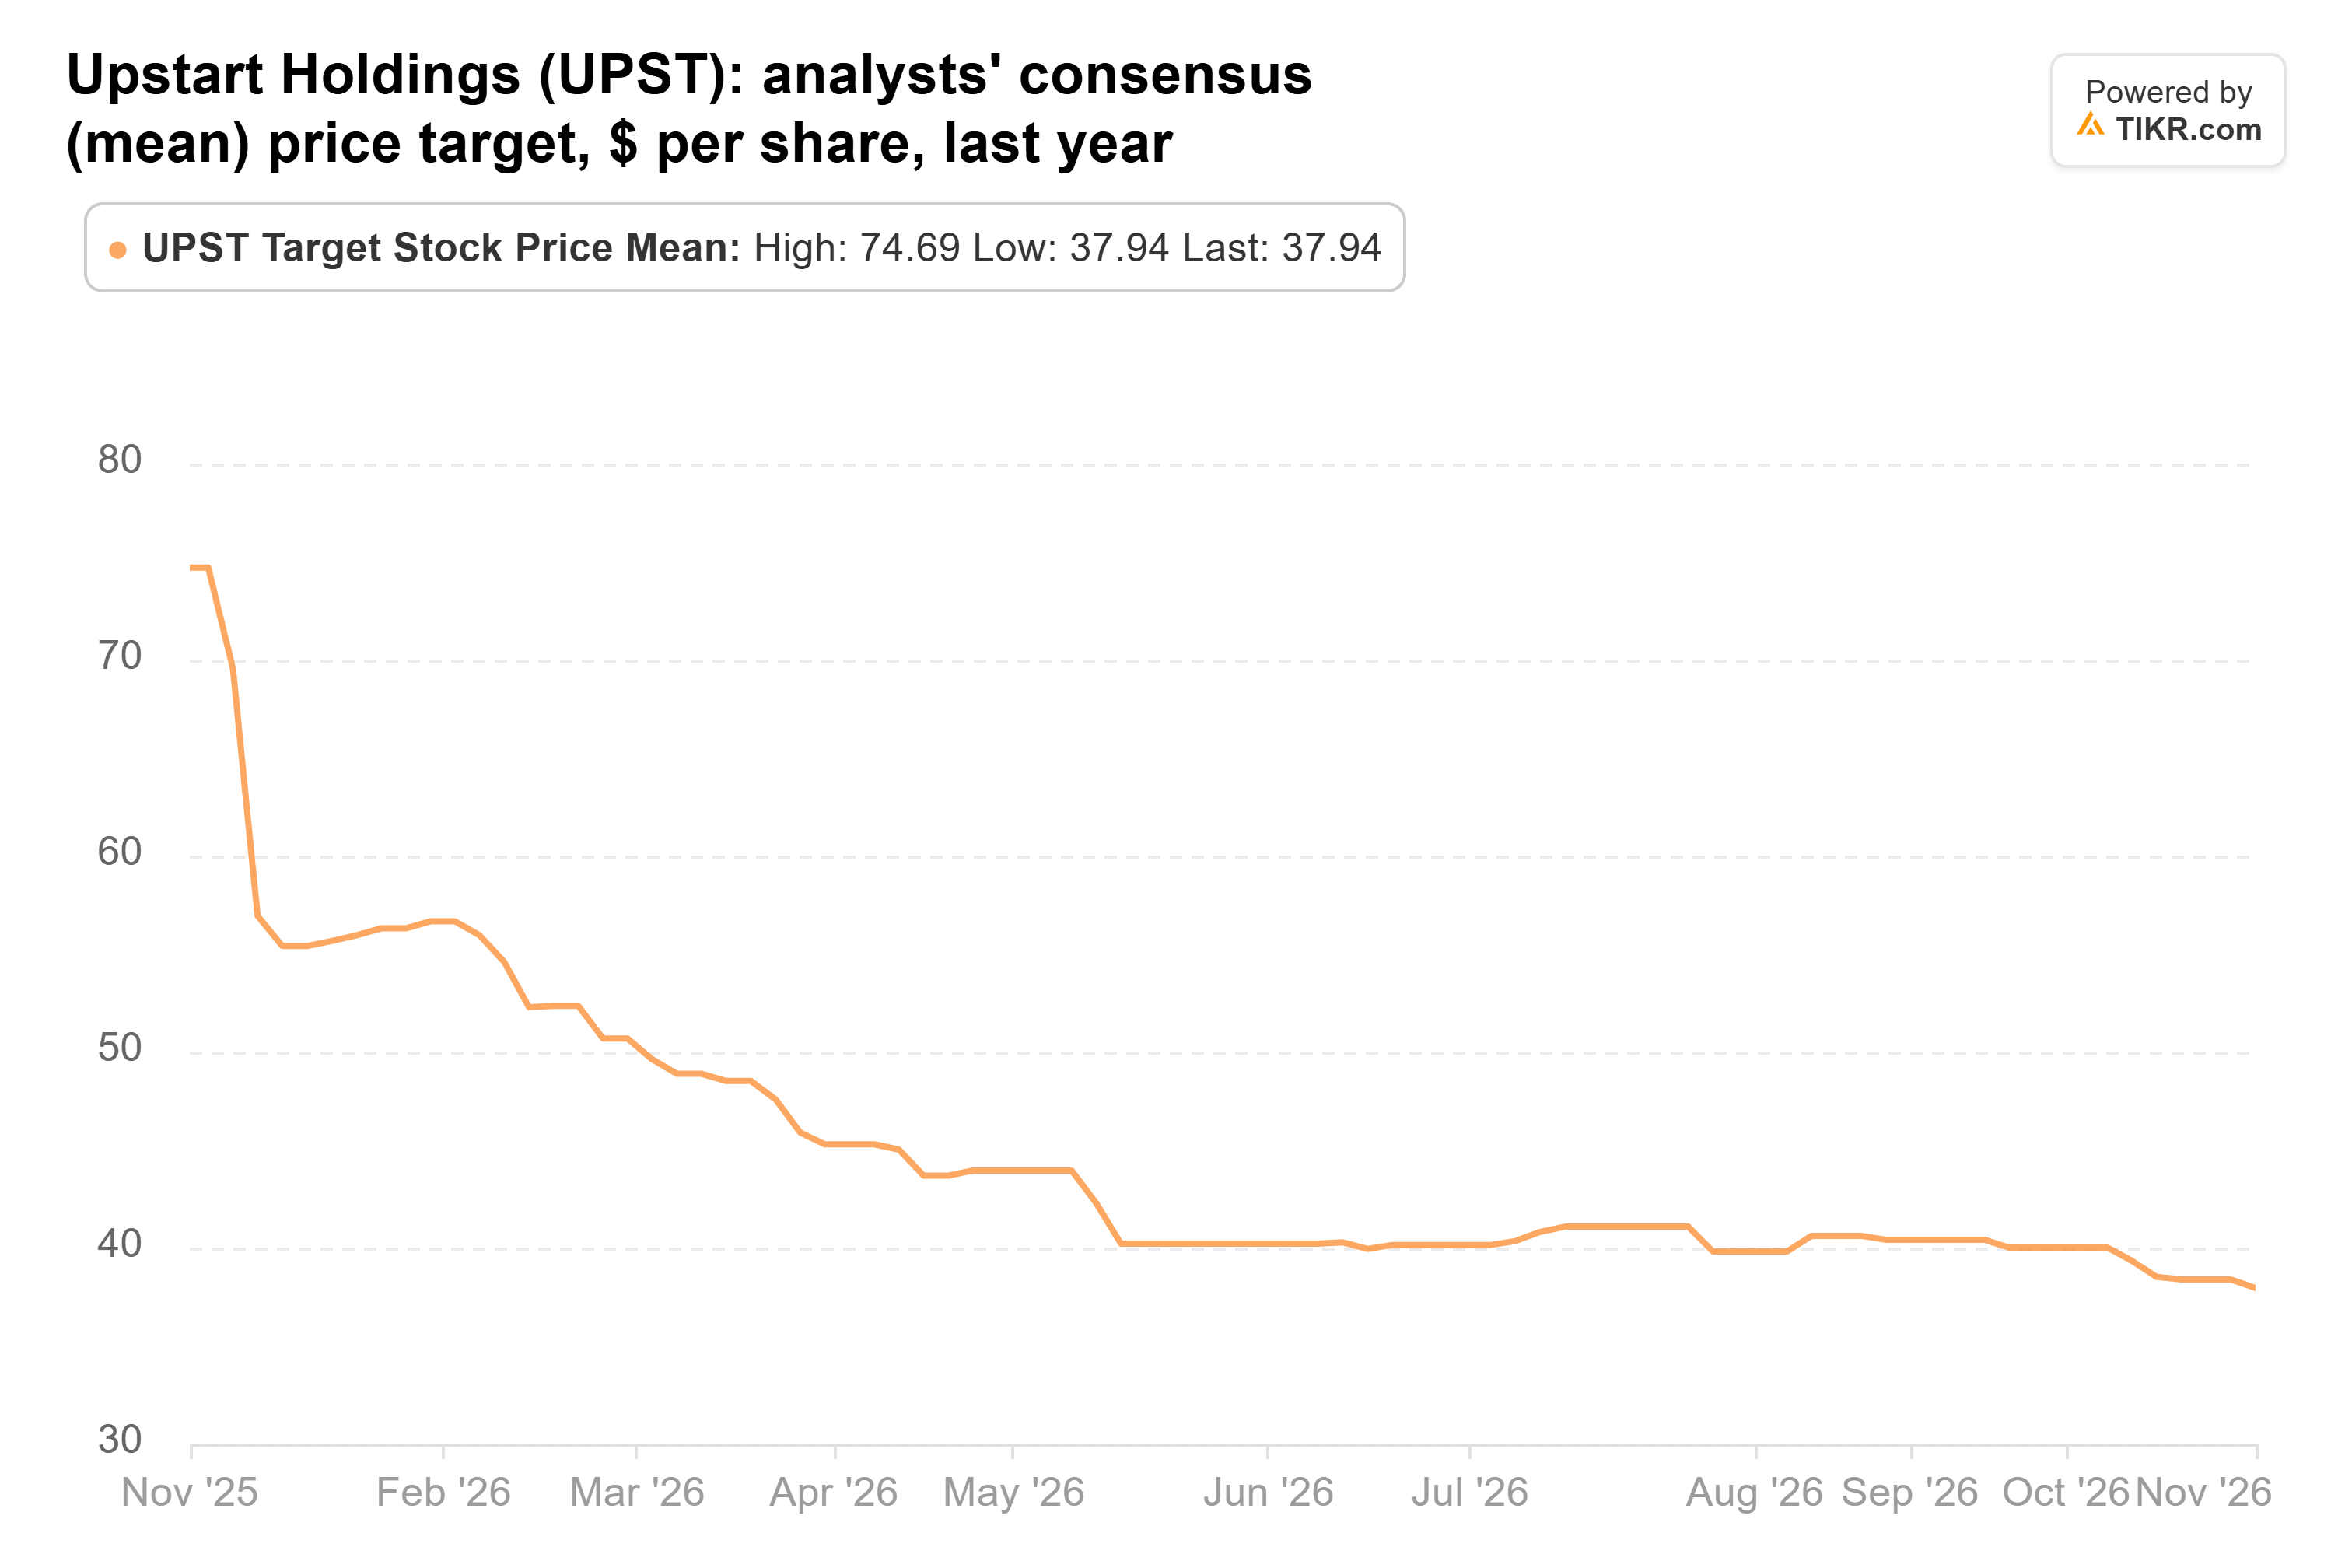
The way I see it, a stock this cheap is already priced for a bad quarter. If Upstart holds its full-year guide Tuesday, today’s drop looks like an overreaction. A cut to the $294 million adjusted EBITDA guide would prove BofA right.
So what is Upstart stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Upstart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!