Key Stats for Vistra Stock
- Current Price: $138.37
- Target Price (Mid): ~$155
- Street Target: ~$205
- Potential Total Return: ~12%
- Annualized IRR: ~3% / year
What Happened?
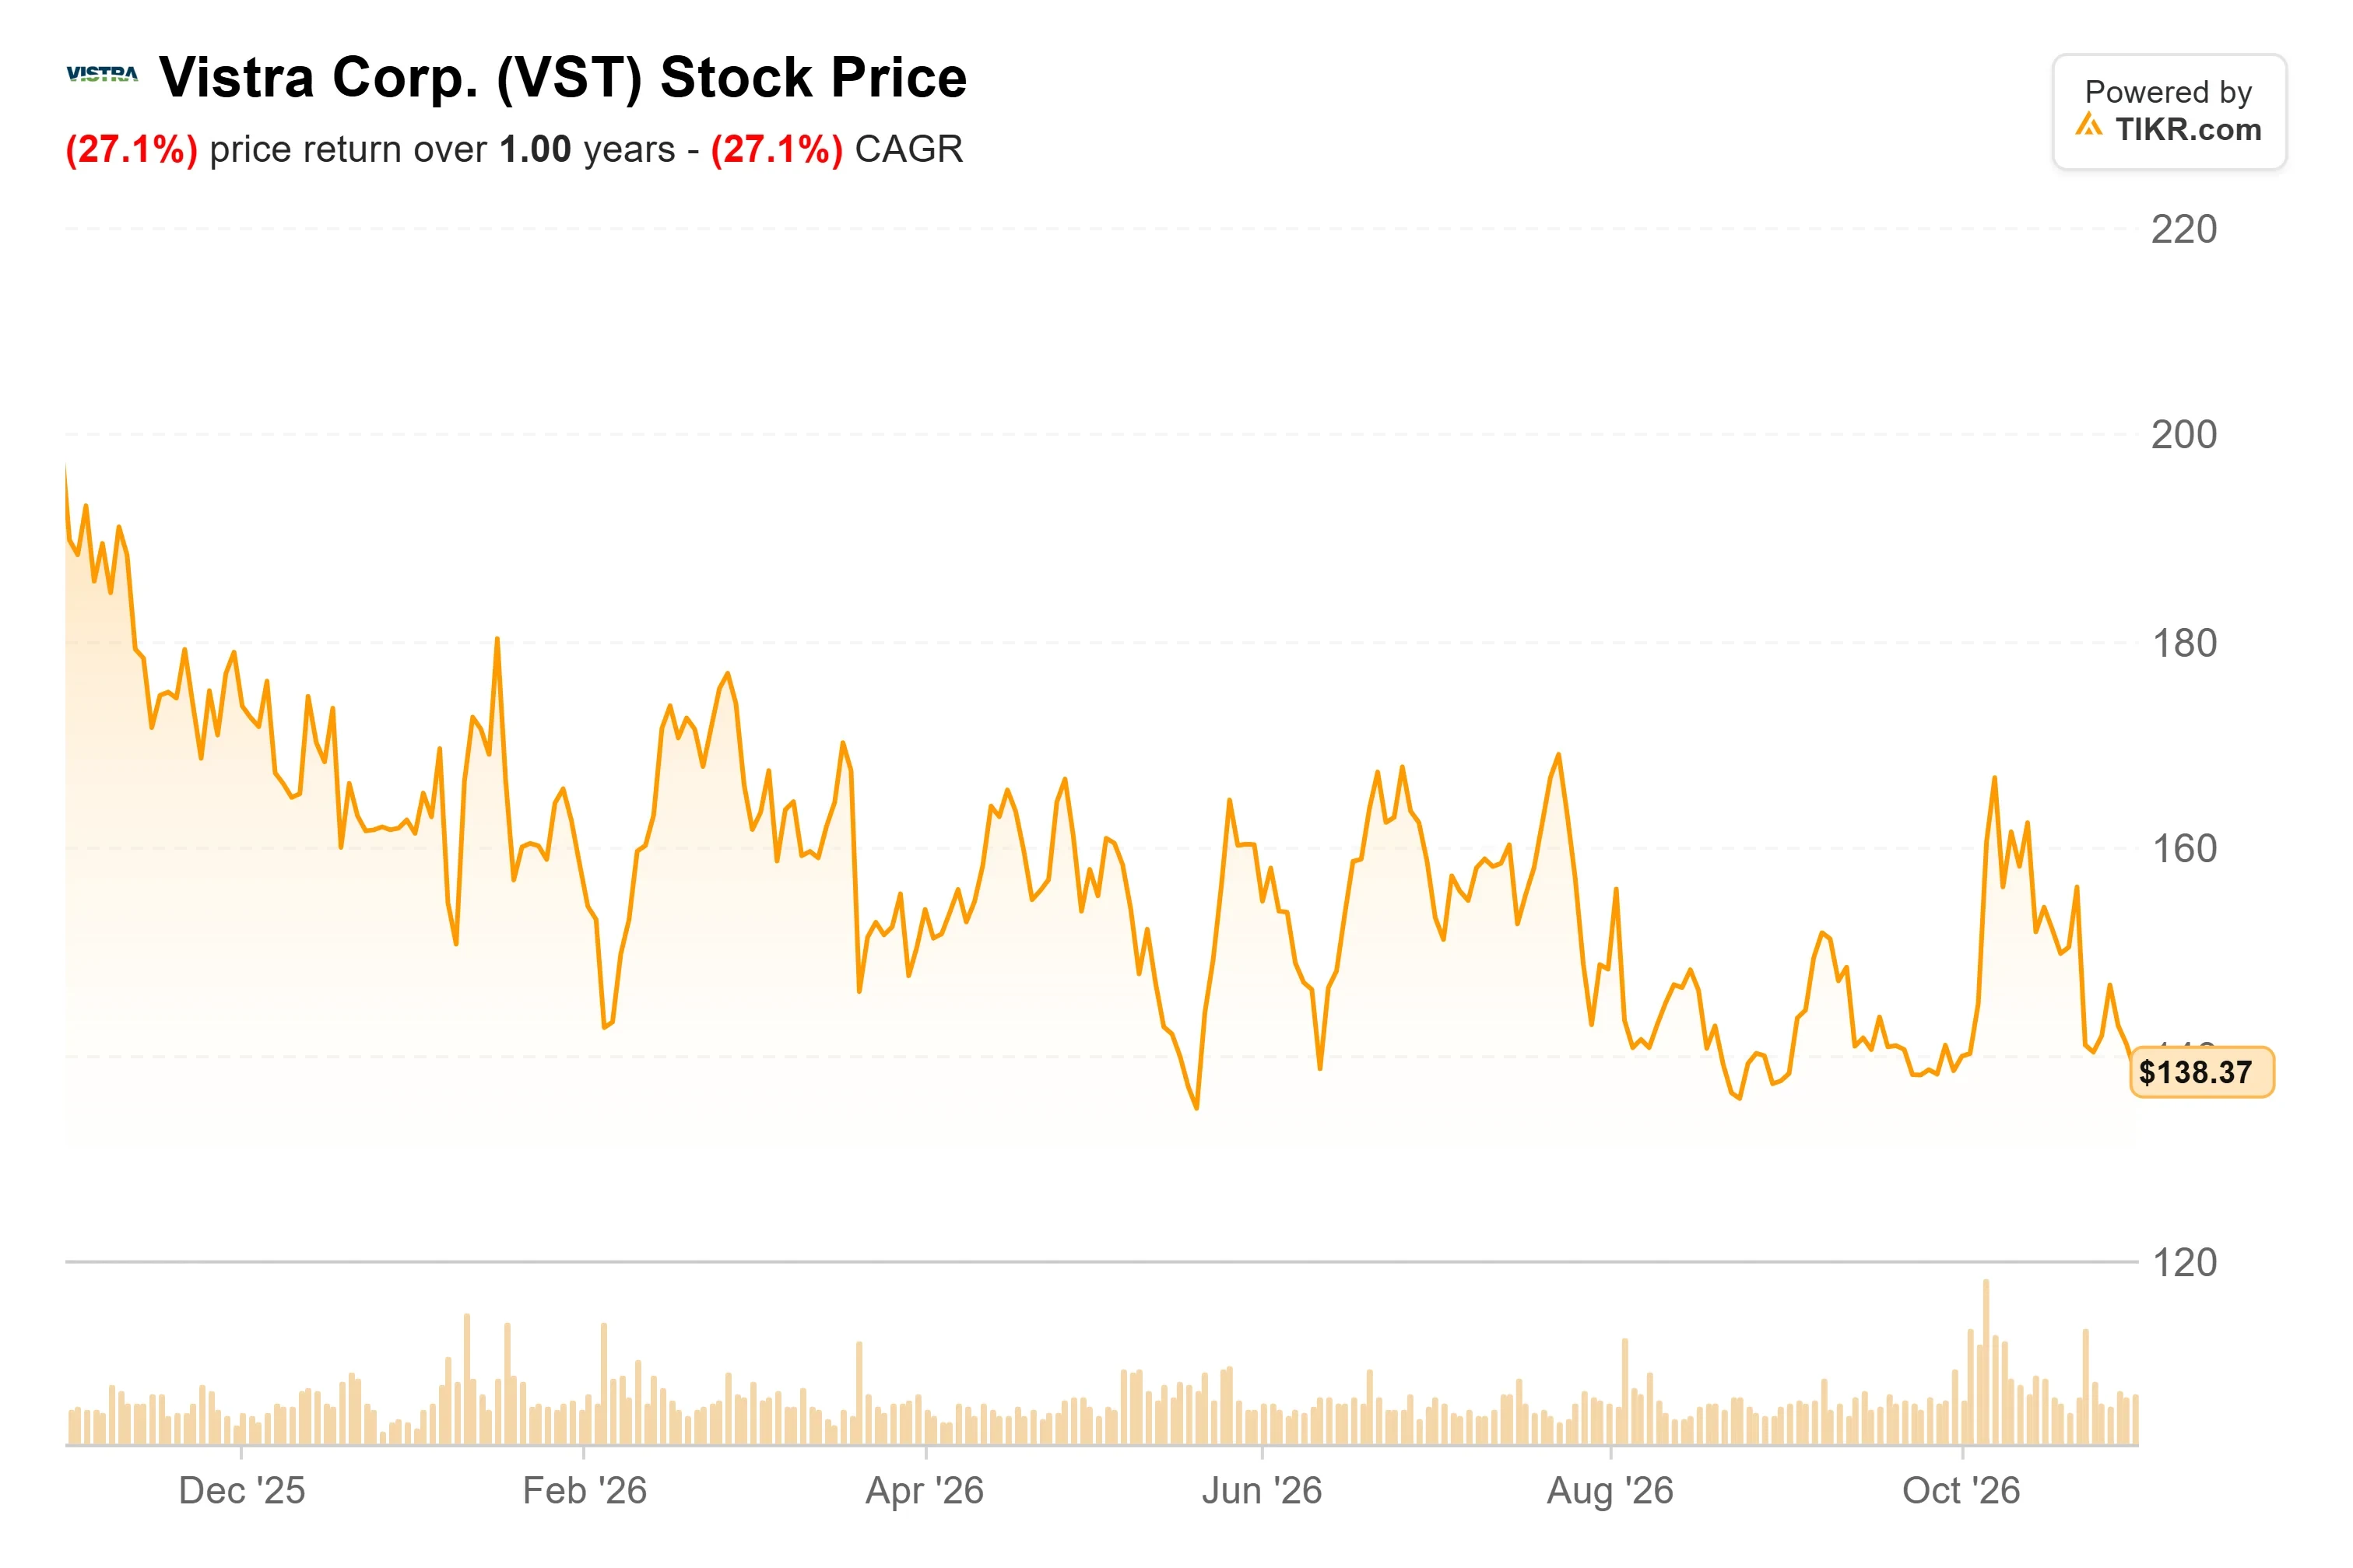
Vistra (VST) closed its purchase of Cogentrix Energy from funds managed by Quantum Capital Group on October 30, adding 10 natural gas plants with 5,496 MW of capacity a week before its November 6 third-quarter report. Only one of them, the 583 MW Altura cogeneration plant, is in Texas, the market behind Vistra’s softer 2027 outlook. Shares slipped 1.83% to $138.37 that day, in step with Constellation Energy, NRG, and Talen Energy, and closed 4.3% above their 52-week low of $132.66.
Nine of the 10 Plants Land Outside Texas
PJM, the mid-Atlantic and Midwest grid, gets 3,163 MW, or about 58% of the new capacity. New England gets 1,750 MW (about 32%) and Texas 583 MW (about 11%). The two largest, Patriot and Hamilton-Liberty in Pennsylvania, are 881 MW combined-cycle plants that came online in 2016, and Vistra now owns both outright. Its fleet now totals nearly 50,000 MW.
That tilt matters because weaker Texas forward prices have weighed on Vistra’s 2027 outlook, while management said in August that PJM prices were strengthening.
In January, Vistra agreed to pay about $4 billion net of expected tax benefits, through cash, 5 million shares, and assumed debt. It put that at about 7.25 times the plants’ expected 2027 adjusted EBITDA, compared with roughly 9 times next-12-month EBITDA for Vistra itself on TIKR. New plants keep getting costlier to build. On the August 7 call, CEO Jim Burke said “the price of equipment, in some cases, has doubled, if not tripled,” adding that “what was an acceptable price to build at a year or 2 ago is no longer an acceptable price.” Plants already running skip that bill.
A Closed Deal Sets Up the 2027 Update
Vistra plans to update 2026 and 2027 guidance on November 6. In August, CFO Kris Moldovan said the 2027 update would likely wait if Cogentrix had not closed. Explaining why Vistra held its 2026 range that month, he said “it’s not typical for us to change guidance absent if there’s a deal has closed or something at this time of the year.”
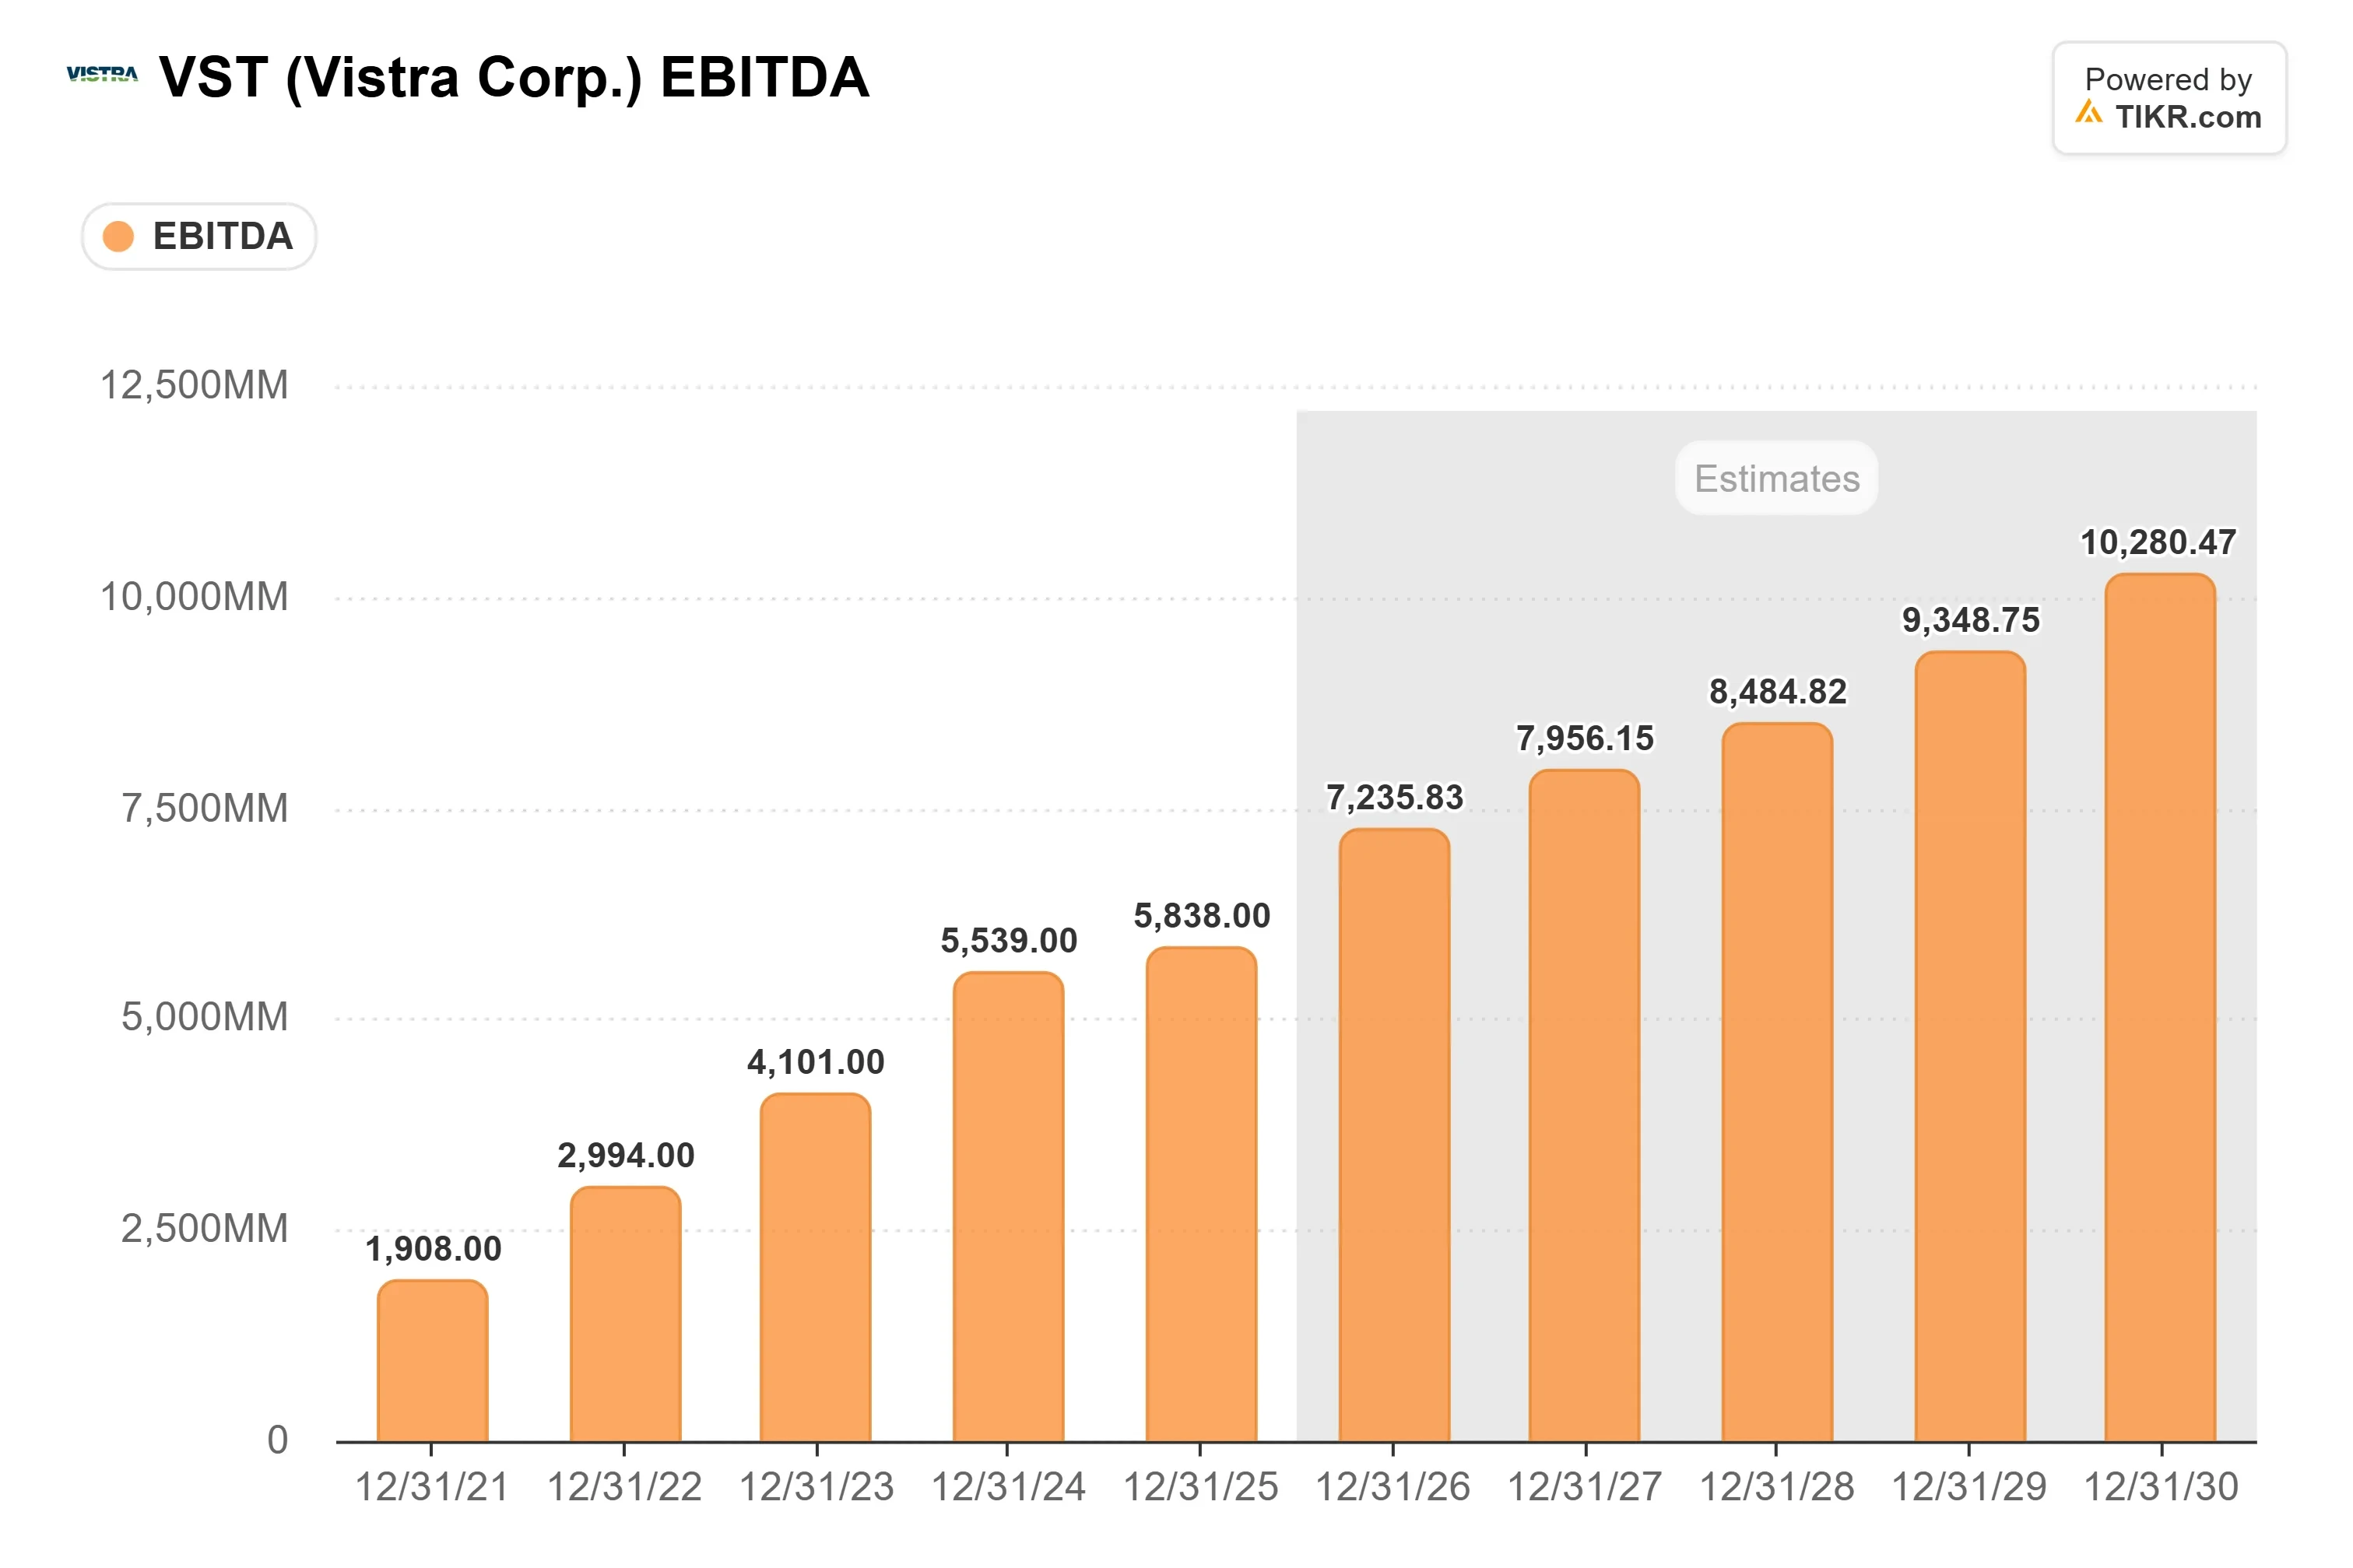
The current 2027 range of $7.4 billion to $7.8 billion of adjusted EBITDA excludes Cogentrix, and management said it was trending toward the low end. By Vistra’s January math, about $4 billion at 7.25 times implies the plants add around $550 million of 2027 adjusted EBITDA, before any change in power prices since then.
TIKR tracks 22 analysts on Vistra. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Vistra, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Vistra’s Analyst Ratings
The Third Quarter and the Street Set Their Own Bars
The quarter itself matters too. TIKR’s consensus calls for about $2.1 billion of third-quarter EBITDA, roughly 37% above a year earlier on TIKR’s basis. In the second quarter, revenue and GAAP EPS missed estimates while EBITDA beat.
Analysts stay bullish but have trimmed. The Street mean target slipped to about $205 across 22 estimates from about $213 at the end of September, even as Buy ratings rose to 18 from 15. CIBC cut its target to $181 from $201 on October 28, Morgan Stanley trimmed to $224 from $226 on October 30, and one analyst rates the stock Underperform.
TIKR Advanced Model Analysis
- Current Price: $138.37
- Target Price (Mid): ~$155
- Potential Total Return: ~12%
- Annualized IRR: ~3% / year

The TIKR model’s mid case puts Vistra at about $155 by December 31, 2030, roughly 12% above the October 30 close, or about 3% a year, well below the ~ $205 Street mean. Across its separate 2025 to 2035 forecast table, the mid case assumes revenue growth near 6% a year, net margins near 15%, and a slightly lower P/E. The main risk is Texas: if ERCOT prices keep sliding, Cogentrix offsets less of the damage. A Cogentrix contribution near Vistra’s January math would support a higher multiple than the model uses. A 2027 guide stuck near $7.4 billion with the deal included would make even this case look full.
Conclusion
November 6 shows whether Cogentrix adds growth or mostly patches Texas. If Vistra breaks out the deal’s 2027 contribution, a figure near $550 million would match its January math. A figure well below that would mean softer prices or hedges have already eaten into the deal.
So what is Vistra stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Vistra could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!