Key Takeaways
- TSMC stock fell 11% in October, and two sessions did most of the damage: the chip selloff after Lam Research’s Oct. 21 report and Intel’s weak outlook on Oct. 29.
- TSMC’s own news was good: a record $46.7 billion quarter, fourth-quarter guidance of $52.3 billion to $54.3 billion, and a reported price increase of up to 20% on its AI chip packaging.
- The main risk is TSMC’s customers. If AI funding tightens or leaner models need fewer chips, orders could slow while TSMC spends $60 billion to $64 billion on capacity this year.
- Earnings per share are expected to more than double from 2025 to 2027, and the stock trades below its usual multiple, so the selloff looks like a chance to buy before TSMC’s mid-January report.
Taiwan Semiconductor Manufacturing (TSM) stock fell 11% in October, and very little of that came from TSMC itself.
Two sessions did most of the damage. Chip stocks sold off on Oct. 22, the morning after Lam Research said supply shortages had held back its December-quarter outlook, and TSMC fell about 4.5%. Then Intel (INTC) gave a weak outlook after the Oct. 29 close, and TSMC fell about 6% on Oct. 30 in a broad chip selloff that also hit Nvidia (NVDA) and Advanced Micro Devices (AMD). Strip out those two days, and TSMC stock was roughly flat for the month.

Intel’s Problem Is PCs, Not Servers
Intel’s third-quarter revenue rose 21% to $16.5 billion, and data center sales jumped 78% to $7.3 billion. The trouble is PCs. Intel guided fourth-quarter revenue to $15 billion to $16 billion, and CFO David Zinsner said he sees “the PC slowdown continuing at least through the first half of next year.” Intel stock fell 47% in October.
Supply is the other half of the story. CEO Lip-Bu Tan said in the release that Intel’s immediate priority is “to unlock additional supply to meet extraordinary demand for our Xeon family.” Intel has spent years trying to win foundry customers from TSMC, and a company that can’t make enough of its own server chips is in a weak spot to do that.
TSMC Just Had Its Best Quarter Ever
On Oct. 15, TSMC’s third-quarter revenue hit a record $46.72 billion. That was up 41.2% from the third quarter of 2025 and beat the high end of the company’s guidance range. Gross margin was 66.4%, and 2-nanometer chips already made up 8% of wafer revenue.
Fourth-quarter guidance points to about 58% year-over-year growth at the midpoint, and TSMC now expects about 44% growth in US dollars for the full year. CFO Wendell Huang said in the release that he expects “continued strong demand for our leading-edge process technologies, including the steep ramp-up of our 2-nanometer technology.”
Wall Street’s normalized EPS estimate for 2027 sits at $23.39, more than double the $10.65 TSMC earned in 2025:
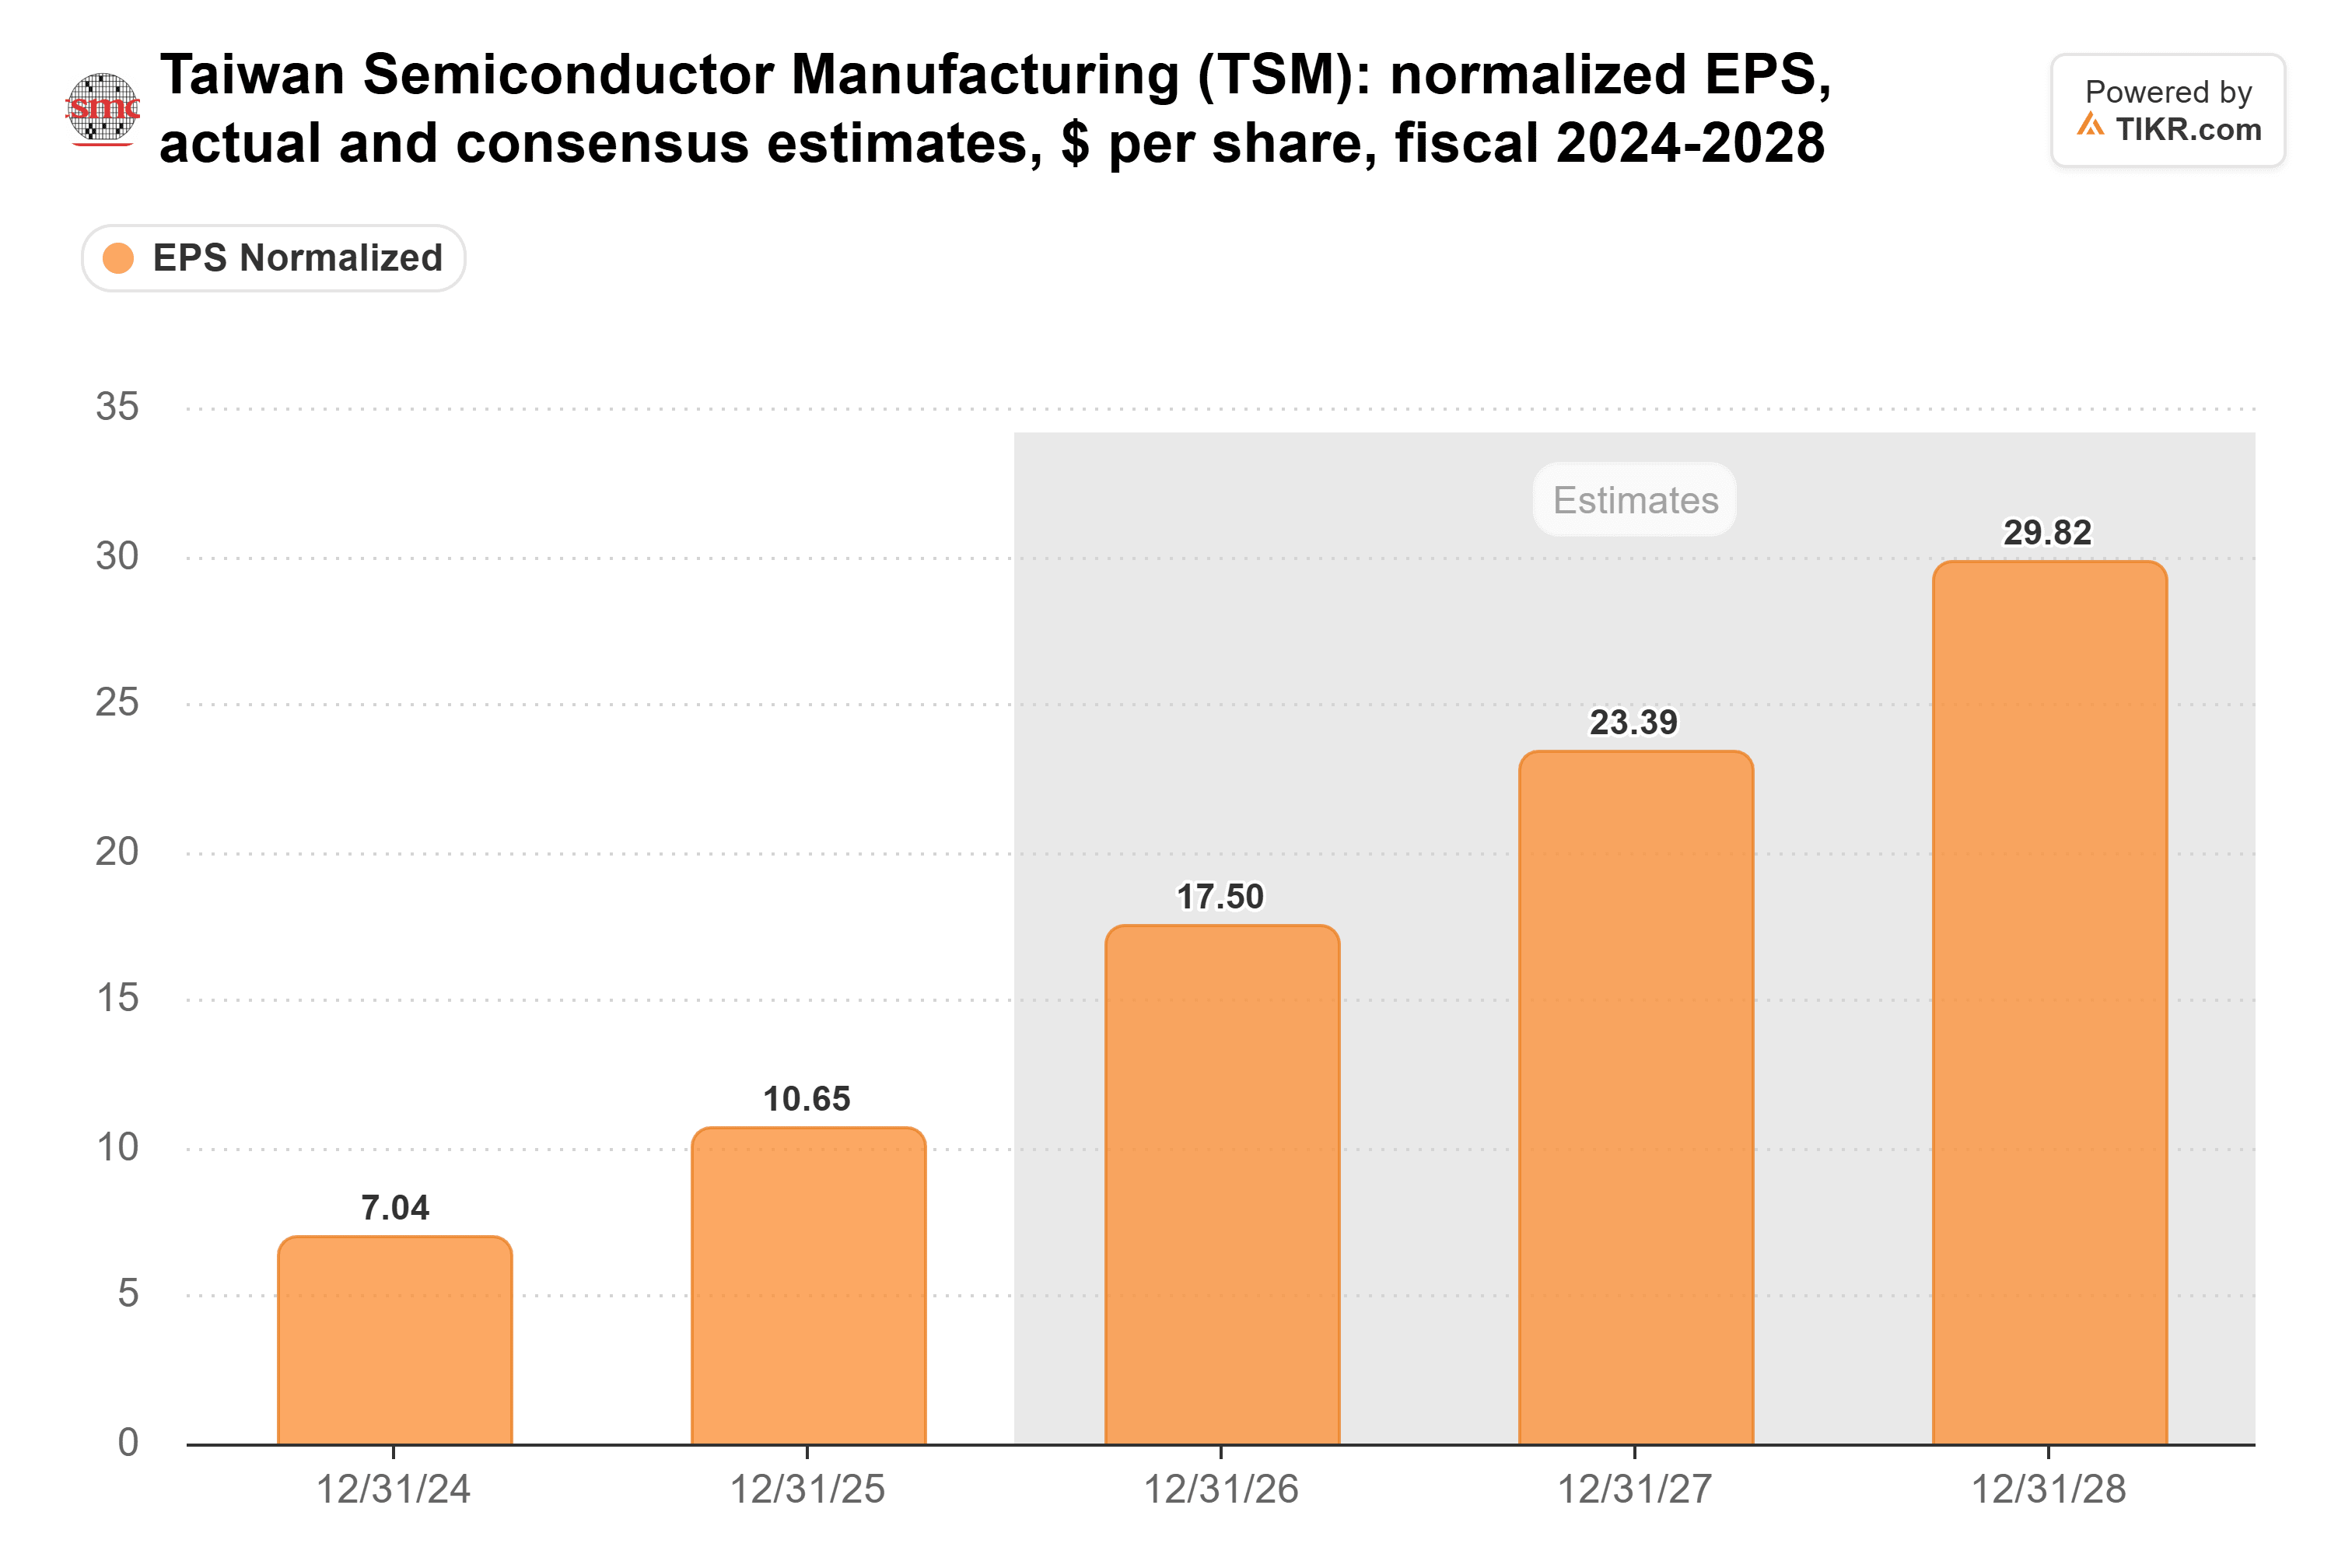
Analysts have raised that 2027 figure by 16% since the end of June, and TSMC’s October numbers gave them no reason to reverse course.
TIKR Tracks 21 Analysts on TSMC. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on TSMC, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See TSMC’s Analyst Ratings
Nvidia and AMD May Soon Pay More
Taiwan’s Commercial Times reported on Oct. 26 that TSMC is preparing to raise CoWoS prices by up to 20%, and TSMC stock rose 3% the next day. CoWoS is the packaging step that joins an AI processor to its high-bandwidth memory. TSMC hasn’t confirmed the increase.
Even a full 20% is a small number for TSMC. Advanced packaging made up slightly over 10% of revenue in 2025, and management expects a low-teens share this year. CoWoS is only part of that business, so even if all of it got the full increase, sales would rise less than 3%.
The bill lands on Nvidia and AMD, down 11% and 17% in October, and both need more packaging than TSMC can supply. ByteDance, Alibaba and Tencent ordered more than $35 billion of Nvidia’s RTX PRO 5500 cards, though Nvidia warned partners they may get only 5% to 10% of what they asked for. AMD reports on Nov. 3, and its data center margin will show how much of a bigger packaging bill it can absorb.
Watch the Customers’ Budgets
The bear case rests on two worries. One is whether the companies building AI data centers can keep raising money, with CoreWeave at the center of that debate. The other is whether leaner models like DeepSeek’s need less hardware. Either would hit while TSMC spends $60 billion to $64 billion this year, and CEO C.C. Wei said in January that this year’s spending would add little output before 2028. TSMC has been here before: after record capex in 2022, its 2023 revenue fell about 9% in US dollars.
I’d Load Up Under 17x
TSMC traded at 17x forward earnings on Oct. 29. That’s under the 18x it has averaged over five years and well short of the 25x it hit in July 2024:
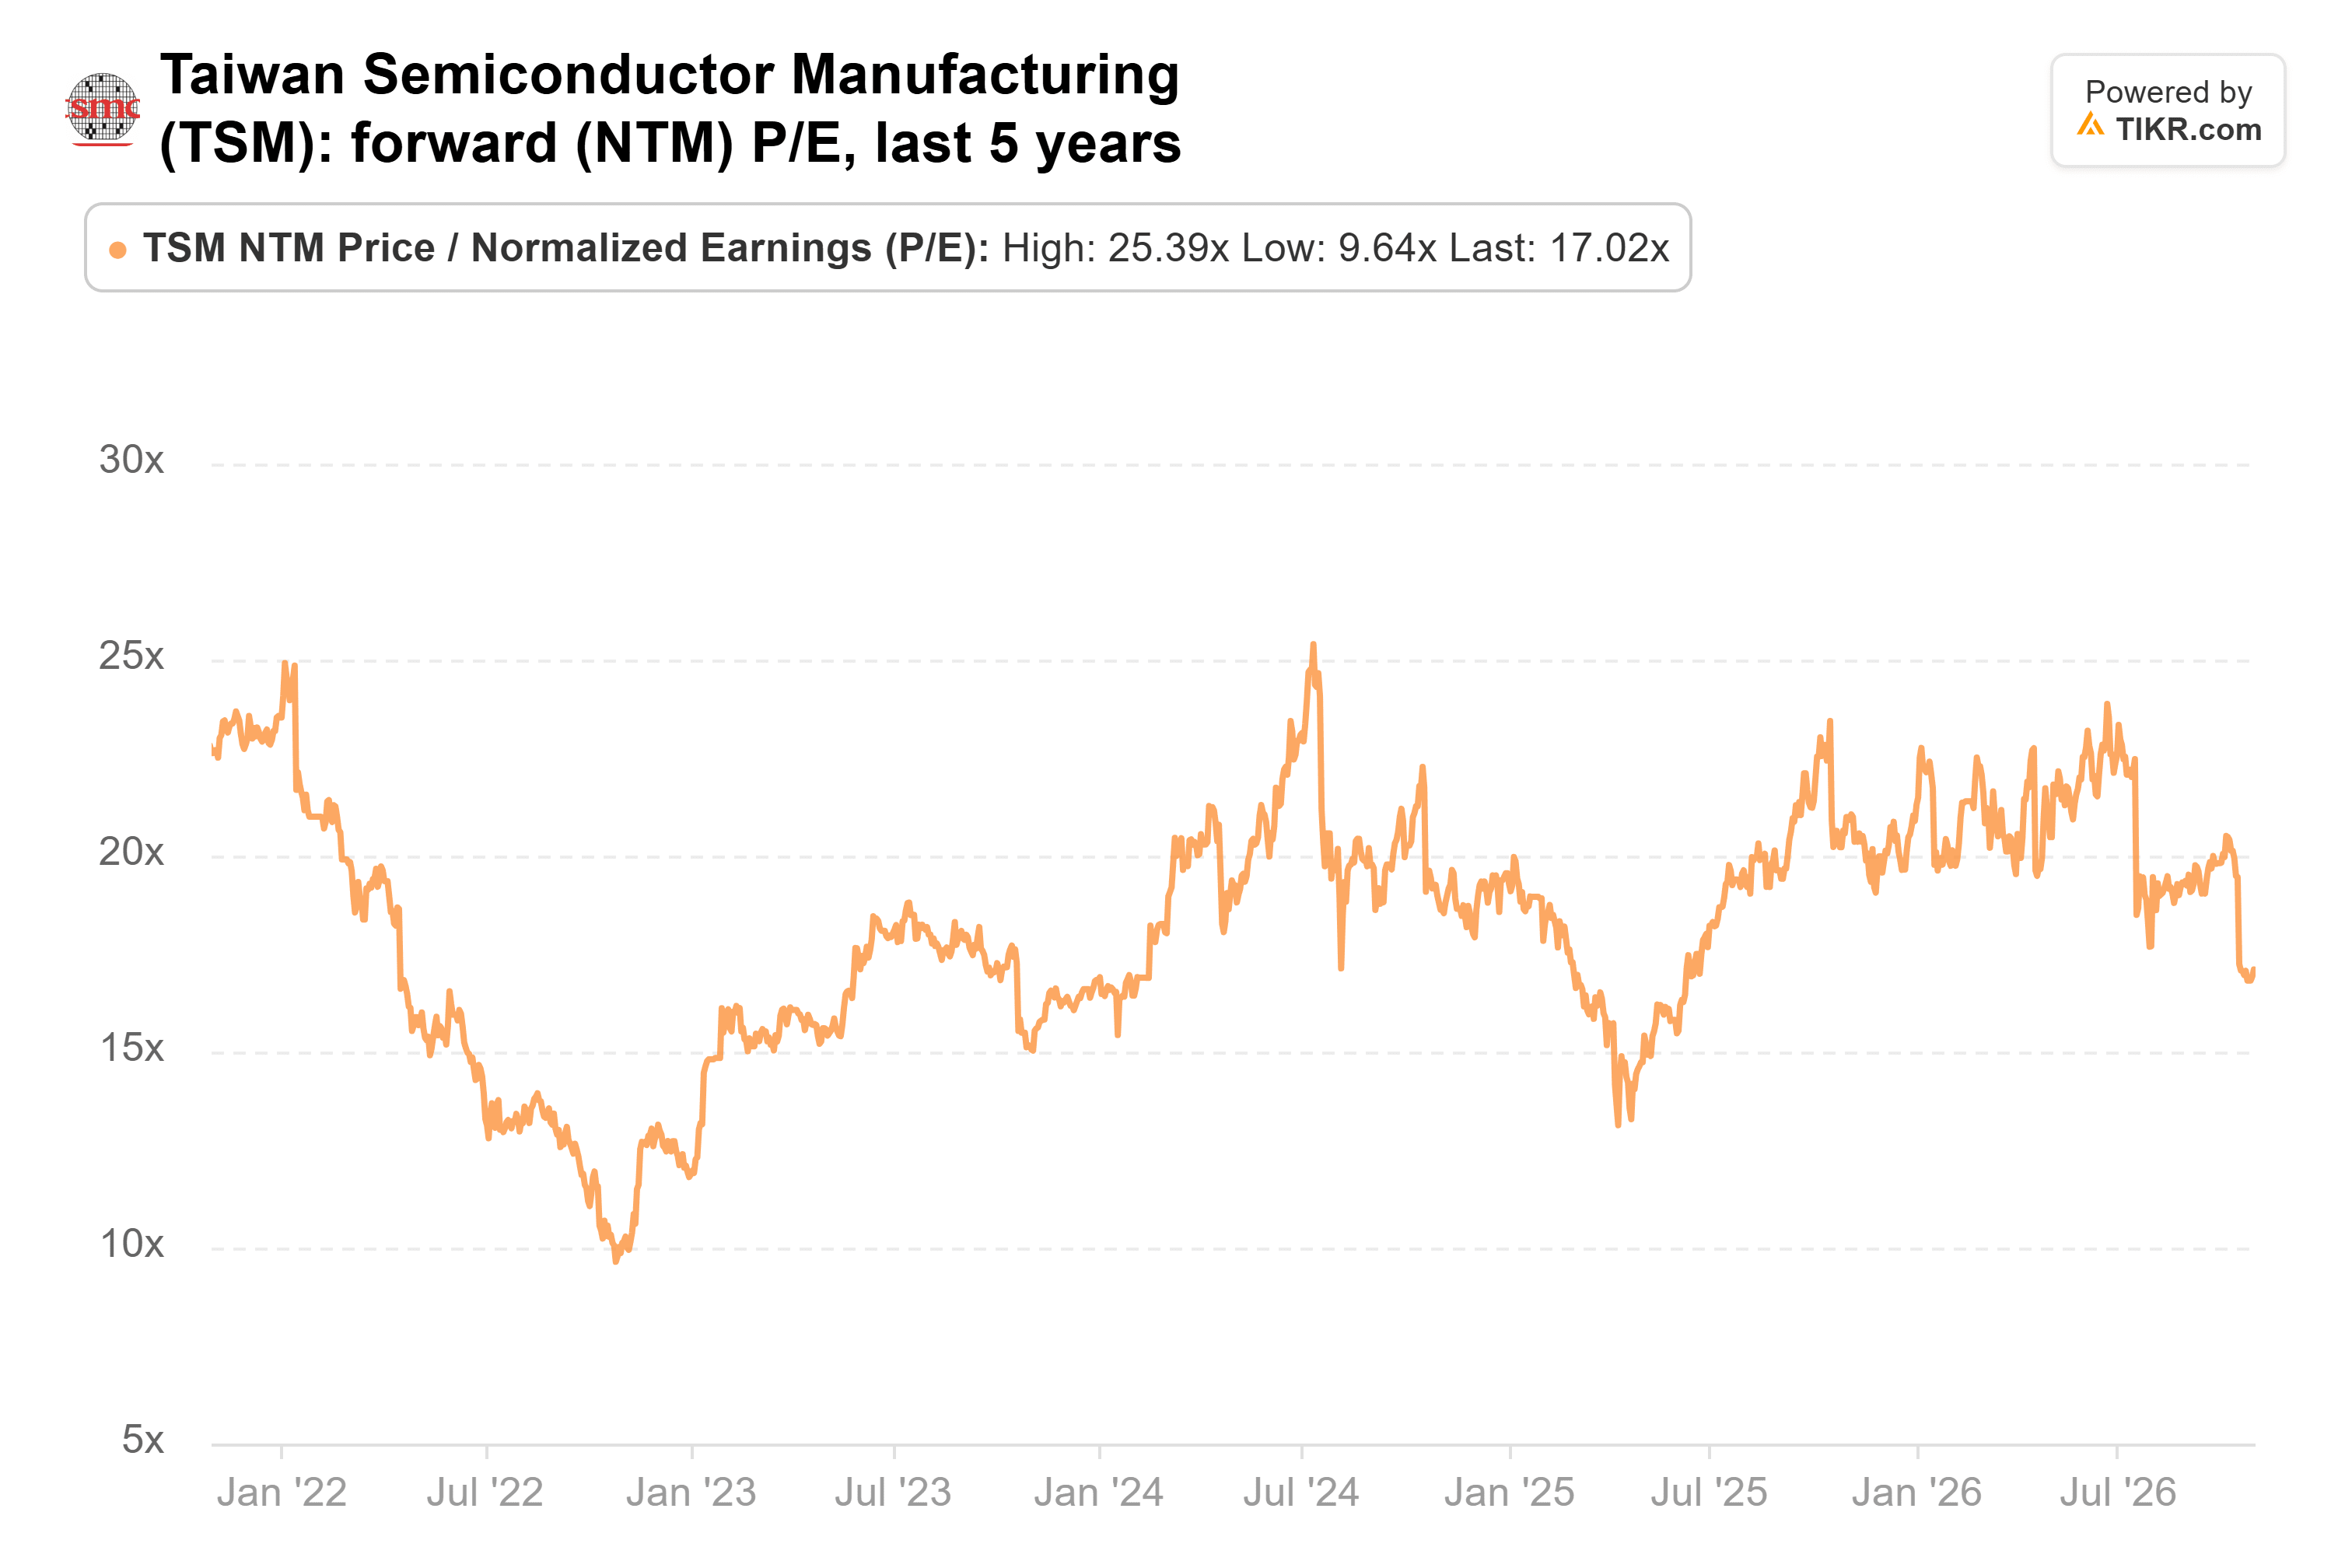
The Oct. 30 drop took it to about 16x, if estimates held.
TSMC reports October revenue around Nov. 10. Then, in mid-January, it reports fourth-quarter results and gives its 2027 guidance. That report will show whether revenue landed in the guided range and whether gross margin held near 66% as 2-nanometer production ramps.
I’d rather buy this dip than sell it. Earnings estimates are rising, customers may soon pay more for scarce capacity, and the stock costs less than usual for that growth.
Of course, if the big AI spenders trim their 2027 budgets, those estimates come down, and 17x won’t look so cheap anymore.
So What Is TSMC Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TSMC could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!