


Taiwan Semiconductor Manufacturing (TSM) posted its sixth straight quarter of record profit on Thursday, October 15, but the more important number came after it. Net profit rose 68.7% to NT$763.06 billion, ahead of the NT$746.3 billion LSEG estimate, on revenue of US$46.72 billion (Reuters). TSMC then guided fourth-quarter revenue to US$52.3 billion to US$54.3 billion, about 14% above the third quarter at the midpoint.
The timing was rough. Taipei-listed shares closed down 2% before the release, as the Taiex fell 3.41% in a chip selloff that also knocked more than 10% off Samsung Electronics (A005930) and SK Hynix (A000660).
TSMC Raised the Bar Again
CEO C.C. Wei now expects 2026 revenue to grow “around 44%” in U.S. dollar terms, he said on the Q3 earnings call. Capex stays at $60 billion to $64 billion. High-performance computing, the segment that holds AI chips, made up 68% of third-quarter revenue, and 3nm and 2nm together made up 41% of wafer revenue.
The catch is margin. Gross margin came in at 66.4%, down from 67.7% in the second quarter, and the 65% to 67% fourth-quarter guide doesn’t promise a rebound. CFO Wendell Huang said dilution from overseas fabs should run close to 2% this year and widen to 3% to 4% later as more U.S. fabs ramp.
What TIKR’s Data Says About TSM
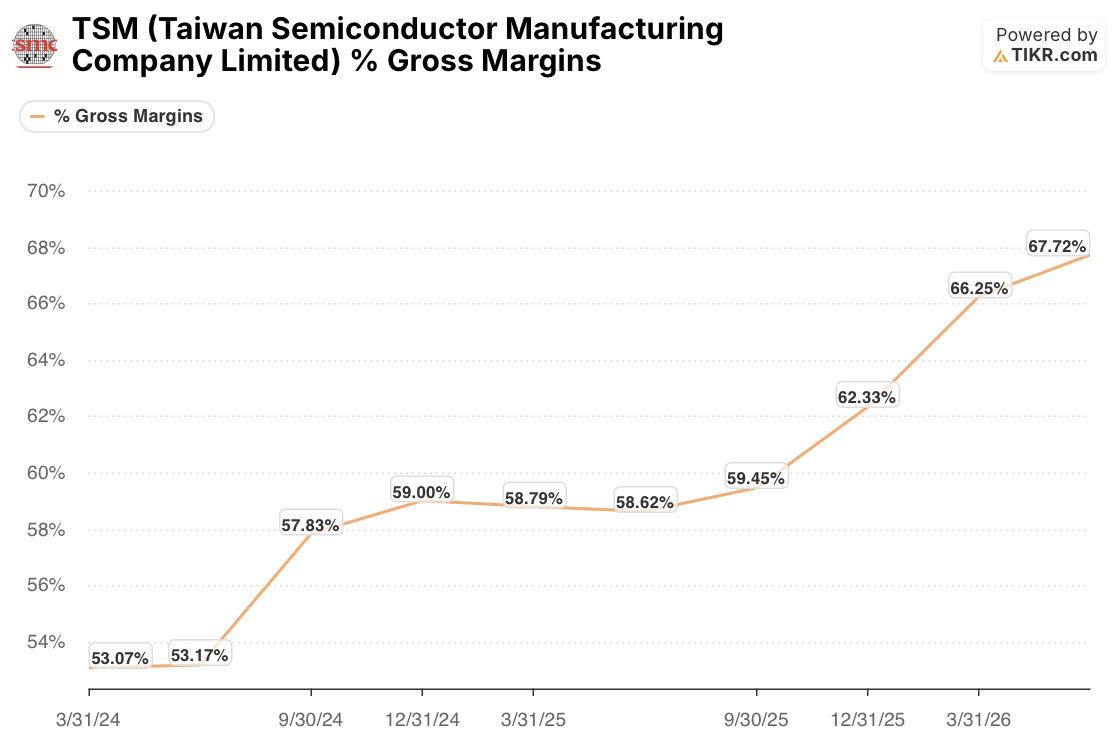
Gross margin climbed from 53.07% in early 2024 to 67.72% in the second quarter of 2026. The third quarter’s 66.4% gives back about 1.3 points, and it still beats every quarter on the chart except the one right before it.
That’s a dip from a record, not a break in the trend.
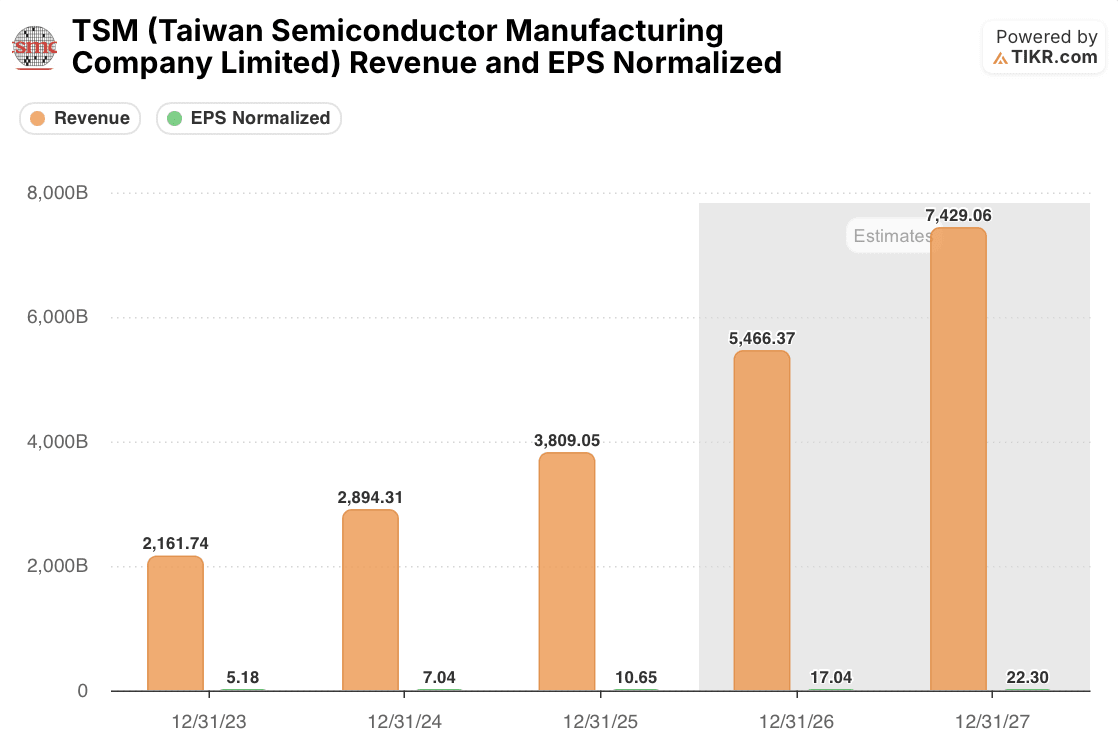
Growth is doing the heavier lifting. Consensus has 2026 revenue at NT$5,466 billion, up 43.5% in Taiwan dollars. Wei’s 44% is in U.S. dollars, so the two don’t line up neatly: in the third quarter alone, revenue grew 50.9% in Taiwan dollars but 41.2% in U.S. dollars. The bigger number is 2027: NT$7,429 billion, another 36%, with normalized EPS rising from $17.04 to $22.30 per ADR.

The stock isn’t pricing in much of that. TSM trades at 19.48x forward earnings, almost exactly its 19.32x average on the chart and well below the near-24x peak it hit in mid-2026.
Is the Margin Peak Already in the Price?
The bear case writes itself: margins have topped out, capex keeps climbing, and the U.S. fabs will dilute margins for years. Broadcom CEO Hock Tan added to the nerves this week by likening many AI investors to casino gamblers.
But a peak-margin worry usually shows up as a falling multiple, and TSM’s has already done most of that falling. At about 19x, the stock is priced for an average year, while the Street is modeling a second straight year of 30%-plus growth.
Where Wall Street Has TSM Stock
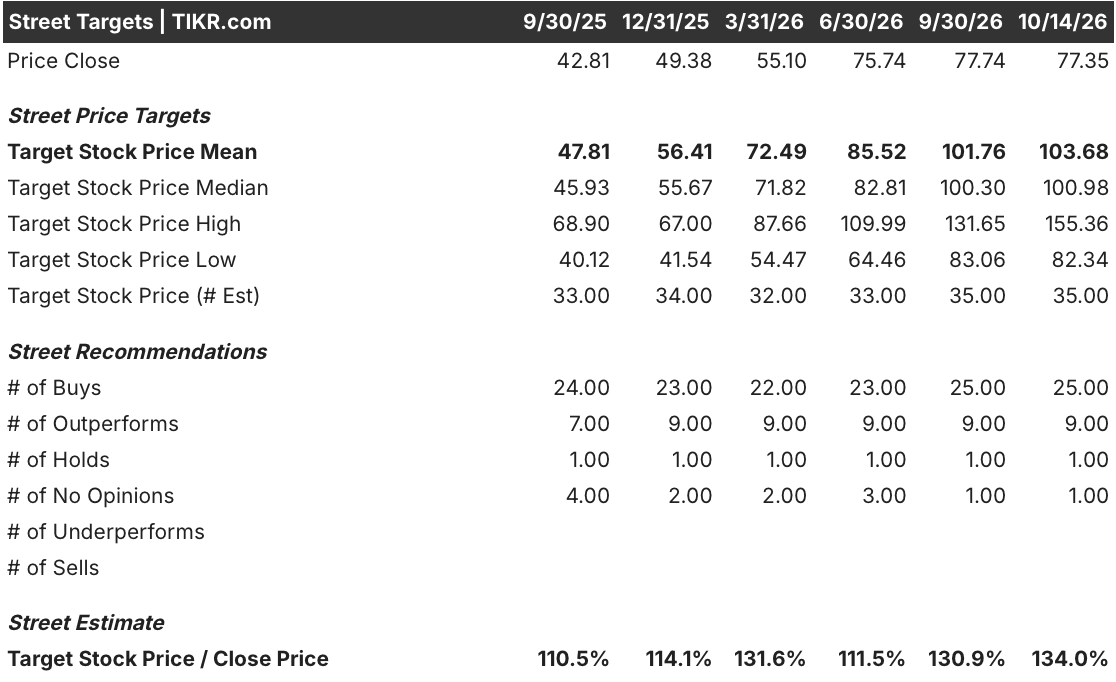
Analysts were already leaning bullish before the results. The mean target for TSMC’s Taipei-listed shares works out to $103.68 in U.S. dollars, 34% above the October 14 close of $77.35. Even the lowest target, $82.34, sits above that price.
The ratings tilt the same way: 25 buys, 9 outperforms, 1 hold and no sells. The mean target has also more than doubled from $47.81 a year ago, faster than the 81% rise in the share price, and it held steady through the past two weeks of chip selling.
Conclusion
Record profit was the expected part. The new information is the guide for roughly 14% sequential revenue growth in the fourth quarter, which landed after Thursday’s chip selloff had already run its course in Taipei. Nvidia (NVDA) and Broadcom (AVGO), whose AI chips TSMC builds, are getting the clearest demand signal they’ll see before their own reports.
With the stock at its average multiple and every analyst target above the price, TSM looks like a selloff casualty rather than a peak. The test is the fourth-quarter gross margin: a print below 65%, the bottom of the guide, would be the first sign that margin pressure is running ahead of TSMC’s own plan.
Want to see how analysts’ targets for TSMC have moved quarter by quarter, or check the margin and P/E charts yourself? Pull up the same data on TIKR for free. Learn more here.
So what is TSMC stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TSM could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Taiwan Semiconductor Manufacturing Company Limited for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


