


Key Stats for The Trade Desk Stock
- Current Price: $13.92
- Target Price (Mid): ~$23
- Street Target (mean): ~$14
- Potential Total Return: ~65%
- Annualized IRR: ~12% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
The Trade Desk (TTD) has reached the point in a decline where the average analyst target no longer sits ahead of the price. On September 18, Guggenheim raised its target to $13 from $12 and kept a Neutral rating. The stock closed that day at $13.92. What makes the raise revealing is its reason: Guggenheim lifted the number on the company’s recent layoffs, raising its 2027 EBITDA estimate by about 23% on roughly $150 million of expected annualized savings. The most constructive analyst action in weeks was a bet on cost discipline, and even that could not lift the target above the market price.
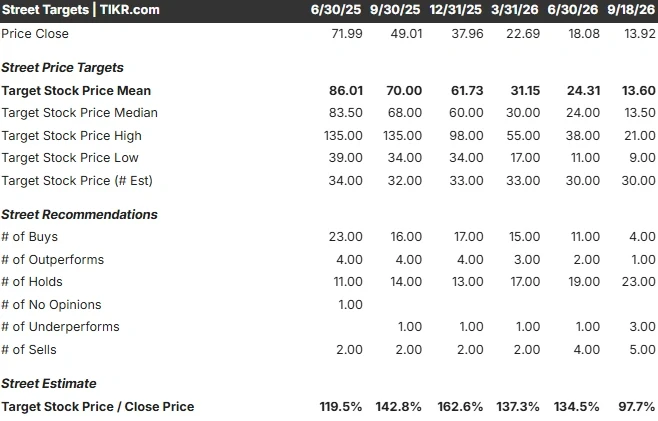
The mean Street target now sits near $13.60, just under the current price, per TIKR data. A year ago, that same panel carried a mean above $70. The question is whether a company still generating cash and gaining share deserves to trade with the median forecast underwater.
A Year of Targets Chasing the Price Down
The collapse in expectations has been methodical. TIKR’s Street target history shows the mean falling from about $86 in mid-2025 to $70, then $62, then $31 by March, and to $13.60 now. Each cut followed the price down rather than leading it. A year ago, the panel leaned heavily Buy; today it holds 4 Buys, 1 Outperform, 23 Holds, 3 Underperforms, and 5 Sells, with individual targets spanning $9 to $21. The Street has not turned violently bearish so much as surrendered its conviction.
The cause was the Q2 print on August 6. Revenue of $715 million grew just 3% year-over-year and missed the roughly $751 million expected; adjusted EPS of $0.34 came in under the $0.40 estimate. Worse was the guide: third-quarter revenue of at least $650 million, implying a decline of about 12% from a year ago. For a company that compounded revenue at a 34% rate over its public life, a guided contraction is what broke the models. CEO Jeff Green did not soften it, telling investors the company “didn’t execute as well as we could have,” and putting much of the rest on macro pressure in consumer-packaged-goods and automotive advertisers, which together make up around 25% of the platform’s business.
See historical and forward estimates for The Trade Desk stock (It’s free!) >>>
The Reset Investors Are Actually Paying For
What separates this quarter from the prior down-legs is that the company is now shrinking itself to fit. On September 3, it announced a cut of roughly 15% of staff (about 575 roles), with $39 to $51 million in charges landing in Q3. A day later, S&P Dow Jones Indices confirmed TTD would leave the S&P 500 at the September 21 rebalance, dropping two tiers into the SmallCap 600 barely a year after joining. The index move changes no revenue, but the layoffs are the number the constructive analyst case now rests on.
New CFO Nate Olmstead, who joined in July from Penguin Solutions, framed the philosophy plainly on the call: invest “with conviction in areas where we see attractive returns” and be “equally disciplined everywhere else.” The indicators he inherited are healthier than the revenue line suggests, with revenue under Joint Business Plans still compounding at six times the overall company rate and connected TV and audio both growing double digits. The bet embedded in the $13 target is that this discipline protects margin while the growth team stabilizes the top line.
TTD trades near 8.8x forward EV/EBITDA, against DoubleVerify at about 7.0x and Magnite at 12.4x, a mid-pack multiple for the clear scale leader in independent programmatic buying. The premium the market once paid for the category’s clear quality leader has almost entirely gone, which is what makes the level worth a look rather than a reflexive pass.

See how The Trade Desk performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $13.92
- Target Price (Mid): ~$23
- Potential Total Return: ~65%
- Annualized IRR: ~12% / year

See analysts’ growth forecasts and price targets for The Trade Desk stock (It’s free!) >>>
TIKR’s mid-case scenario, realized at the end of 2030, values the stock near $23, a total return of around 65%, and an IRR of roughly 12% a year off today’s price. It does not need a return to hypergrowth. The two revenue drivers are continued CTV and audio expansion, where audio is already the fastest-growing channel, and the Joint Business Plan flywheel, where revenue under those long-term brand commitments grows several times faster than the company overall. The margin driver is the multi-year shift of workloads from public cloud to owned data centers, a 2026 cost headwind management frames as later operating leverage, now reinforced by the layoffs. The primary risk is that CPG and auto weakness proves structural rather than cyclical, which would pull the whole growth case lower.
The honest tension cuts in the stock’s favor here. TIKR’s low case still lands near $19, above today’s $13.92 price, which means the market is currently pricing the stock below even the model’s bearish outcome. The upside is that a stabilizing macro plus real cost discipline restores mid-single-digit growth and a re-rating toward the mid case. The downside is that the guided decline extends into 2027 and the multiple compression that has defined two years has further to run.
Conclusion
The next real test is the third-quarter report, due November 5. Management guided revenue to at least $650 million, so the printed number against that bar is the first read: a beat that narrows the implied decline points to cyclical pressure, while a number at or below the guide confirms the Street’s surrender. Watch adjusted EBITDA as closely as revenue, because Q3 is the first quarter to show whether the layoffs protect margin while the top line contracts, and watch the fourth-quarter guide just as hard. Until then, TTD sits in the rare spot of trading above the average target of the analysts who cover it, with a model that suggests the last two years overshot.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in The Trade Desk?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up The Trade Desk, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track The Trade Desk alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze The Trade Desk on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


