


Key Stats for Celsius Stock
- Current Price: $28.02
- Target Price (Mid): ~$45
- Street Target: ~$42
- Potential Total Return: ~61%
- Annualized IRR: ~12% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Celsius Holdings (CELH) closed at $28.02 on September 18, down roughly 51% over the past year and a few dollars above a 52-week low of $23.56. Then the ownership ledger changed. Between September 10 and September 15, three insiders bought about $1.8 million of stock on the open market, led by CEO John Fieldly, and they did it with a securities class action and fresh margin warnings hanging over the name.
That is what investors are searching for now: the people running the company are buying near the lows, but the reasons the stock fell this far have not gone away. Celsius still carries a shrinking flagship brand, a gross margin stuck in the high 40s, and unproven legal claims tied to Alani Nu.
Three Insiders, One Week, and $27 a Share
Fieldly purchased 18,000 shares at a weighted average of $27.44 on September 10, lifting his direct stake to 956,063 shares, per his SEC Form 4. Director Damon DeSantis followed with 20,000 shares at $27.65 on September 14 and 16,000 more at $27.95 the next day. Lead Director Hal Kravitz bought 12,000 shares at $28.00 on September 15, paying above that day’s close. Across the three, that is roughly $1.8 million of personal cash into a stock down more than half over the prior year, and insiders already hold about 13% of the company.
These were the largest insider purchases by dollar size in two years, and they reverse a pattern: other executives were net sellers through much of 2025. Clustered buying from multiple insiders, at prices within pennies of each other, near a 52-week low, is the version of the signal that tends to carry the most information. It is still a disclosed open-market purchase, not a forecast. Fieldly framed the logic at the Barclays Global Consumer Conference on September 8, saying the integration of all three brands is finished and “now it’s really time to unlock that value.”
Several securities class actions cover purchases between February 21, 2025, and June 3, 2026, with a November 3 lead plaintiff deadline. The complaints allege Celsius misled investors about the safety of Alani Nu for teenagers, following a June 4 Texas Attorney General investigation into whether the drinks were marketed to minors. The allegations are unproven, and that June disclosure already cut the stock 7.5% in a session.

See historical and forward estimates for Celsius stock (It’s free!) >>>
The Flagship Brand Is Still the Problem
The reason the stock sits here is the namesake Celsius brand, whose net sales fell 11.7% in Q2 as scanner data ran down 5% to 10%. Management caused part of it. Fieldly admitted at Barclays, the company “went too deep on simplifying the Celsius portfolio for this year,” cutting the assortment so hard it left no permanent innovation to cycle against last year’s launches.
CFO Jarrod Langhans pointed to productivity: dollars per point of distribution rose 16% from Q1 to Q2, even as the brand shed 7% of its distribution points, and the remaining singles SKUs, about 70% of the business, are growing double digits. The drag fades into the first half of 2027 as permanent innovation returns, alongside a new 16-ounce line and the ESPN College GameDay sponsorship now activating on campuses. Alani, meanwhile, is doing the heavy lifting, delivering $364 million in Q2 net sales, up 21%, and running the Witch’s Brew limited-time offer that Fieldly calls the biggest in energy drink history.
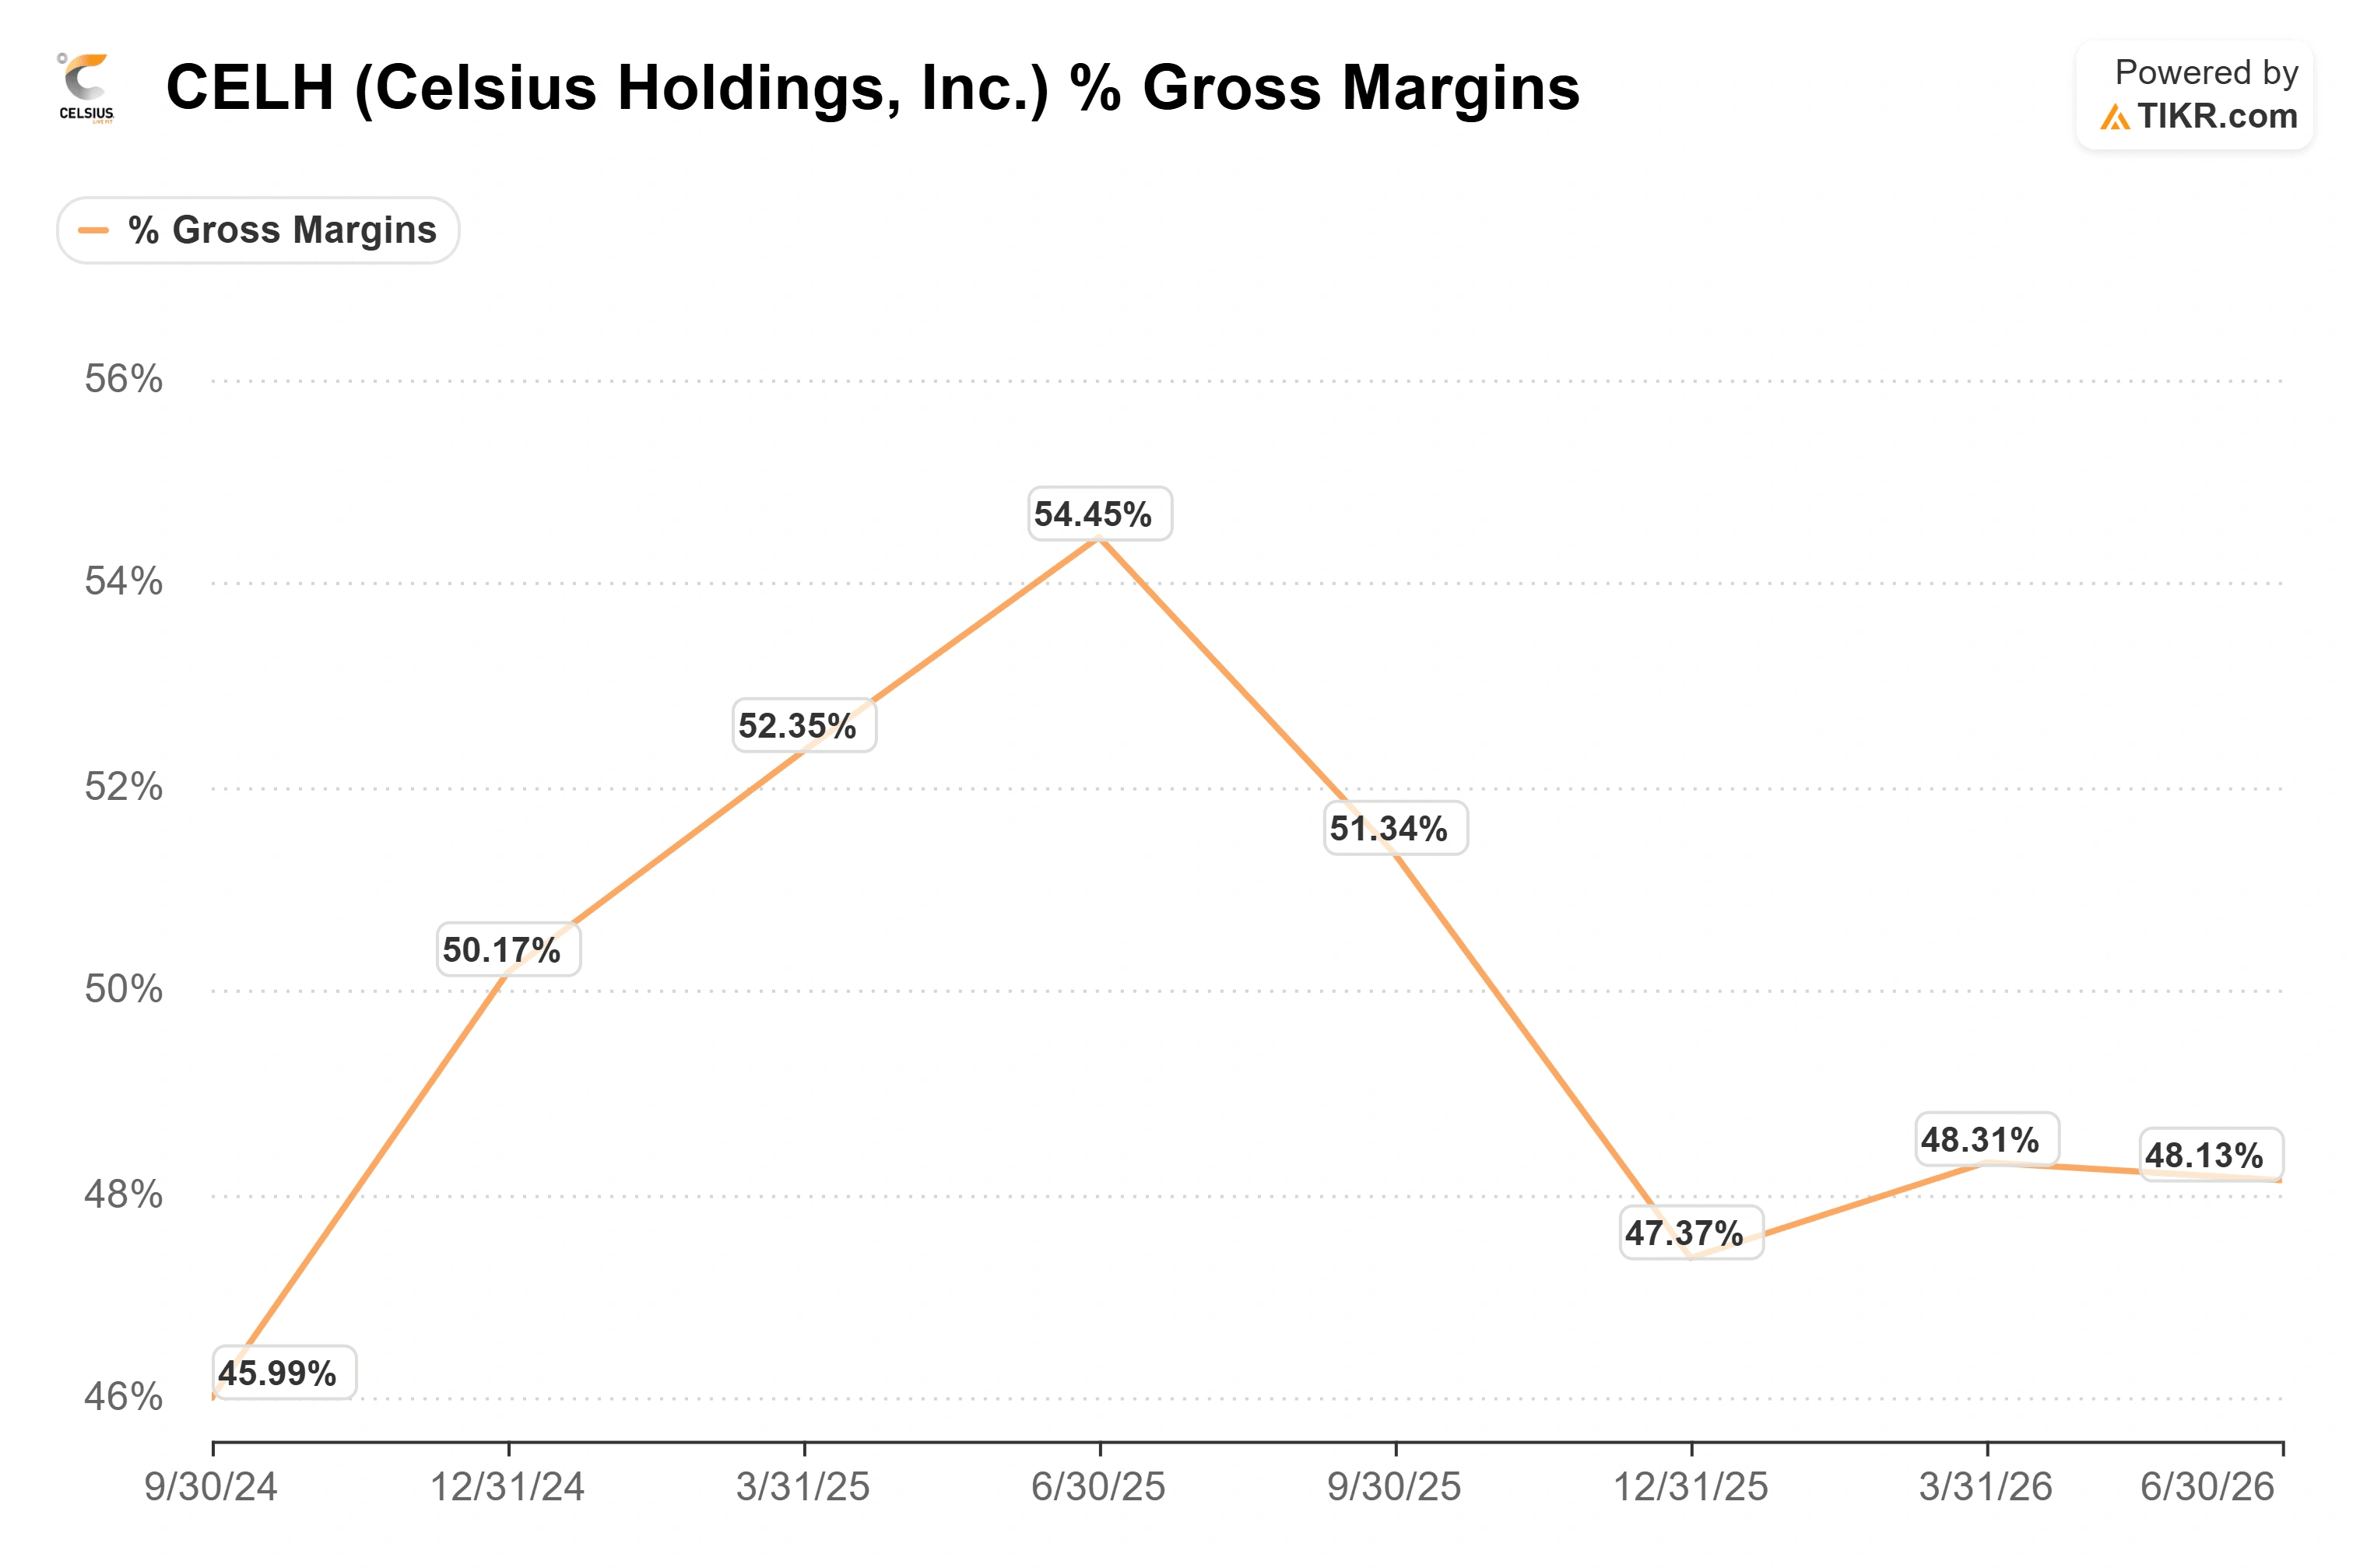
On cost, Celsius carries a 48% gross margin, a clear discount to larger peers Monster Beverage (MNST) and Keurig Dr Pepper (KDP), which both report structurally higher margins. Langhans blamed aluminum, the tariff-linked Midwest premium, and freight, then laid out the offsets: supply-chain integration of Alani and Rockstar, going direct on ingredients, a second manufacturing line fully online for Q4, and a revenue growth management program he called the biggest multi-year opportunity. The discount to Monster is real, but it rests on integration overhead that Monster does not carry. On September 17, Morgan Stanley trimmed its second-half gross margin and EBITDA estimates on the fuel and freight spike, a reminder that the commodity math still works against the timeline.
See how Celsius performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $28.02
- Target Price (Mid): ~$45
- Potential Total Return: ~61%
- Annualized IRR: ~12% / year

See analysts’ growth forecasts and price targets for Celsius stock (It’s free!) >>>
TIKR’s mid-case model values Celsius at approximately $45, implying around 61% total return from $28.02, or roughly 12% annualized over about 4.3 years. The revenue path leans on two drivers: continued Alani expansion into convenience and international markets, and the Celsius brand returning to growth as permanent innovation replaces the over-cut assortment. The margin driver is the cost program, integration freight savings, plus revenue-management pricing, carrying net income margin toward the low-teens. The primary risk is that commodity costs hold the recovery back, exactly what Morgan Stanley flagged.
The upside case is that insiders are right, the flagship stabilizes into 2027, and the multiple re-rates off a depressed base as the discount to Monster narrows. The downside is that the class action drags on, commodities stay elevated, and a stock at 18.7x forward earnings has less cushion than the drawdown suggests. Analysts still lean bullish: 12 Buys, 6 Outperforms, and 6 Holds, no Sells, with a $42 mean target that has itself fallen from $58 in June.
Conclusion
The insiders bought a thesis, and that thesis has a checkpoint. Q3 2026 reports in early November, and the number that matters is not headline EPS but the Celsius brand scan trend. Management guided to weakness through year-end with stabilization into early 2027, so a scan trend that stops deteriorating, paired with a gross margin holding the high 40s, would confirm the recovery is on schedule. A further leg down in the flagship, or a margin print below 47%, says the execution and commodity drag is winning. The lead plaintiff deadline also lands on November 3, so the legal picture sharpens in the same window. Insiders have said where they think the stock goes. The scanner data will tell you whether they were early or right.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Celsius?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Celsius, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Celsius alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Celsius on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!