


Key Takeaways
- Soros Fund Management’s latest 13F shows its five biggest positions at Sept. 30 were Intel, Amazon, Taiwan Semiconductor, Alphabet and NVIDIA.
- Among its positions of 2% or more, those five are also where Wall Street sees the most upside, with analysts’ average targets 27% to 71% above the latest prices.
- Four of the five have fallen sharply since Sept. 30 in a selloff in chip and AI stocks, which accounts for much of that upside.
- Taiwan Semiconductor looks like the best buy of the five: its sales are still growing fast, and analysts kept raising its target through the selloff.
Few names in investing are as big as George Soros, so his firm’s filings get read closely. Soros Fund Management’s 13F for the quarter ended Sept. 30, filed Nov. 13, shows $6.48 billion of US stocks spread across 234 positions.
Its five biggest positions were all AI bets: three chip companies and two cloud giants. Among its positions of 2% or more, they’re also the five where Wall Street sees the most upside, partly because four of them have fallen hard since Sept. 30. (Those moves are from each stock’s Sept. 30 price, since a 13F doesn’t show what the fund paid, or whether it still owns the shares.)
1. NVIDIA at 13x earnings, without Jensen Huang
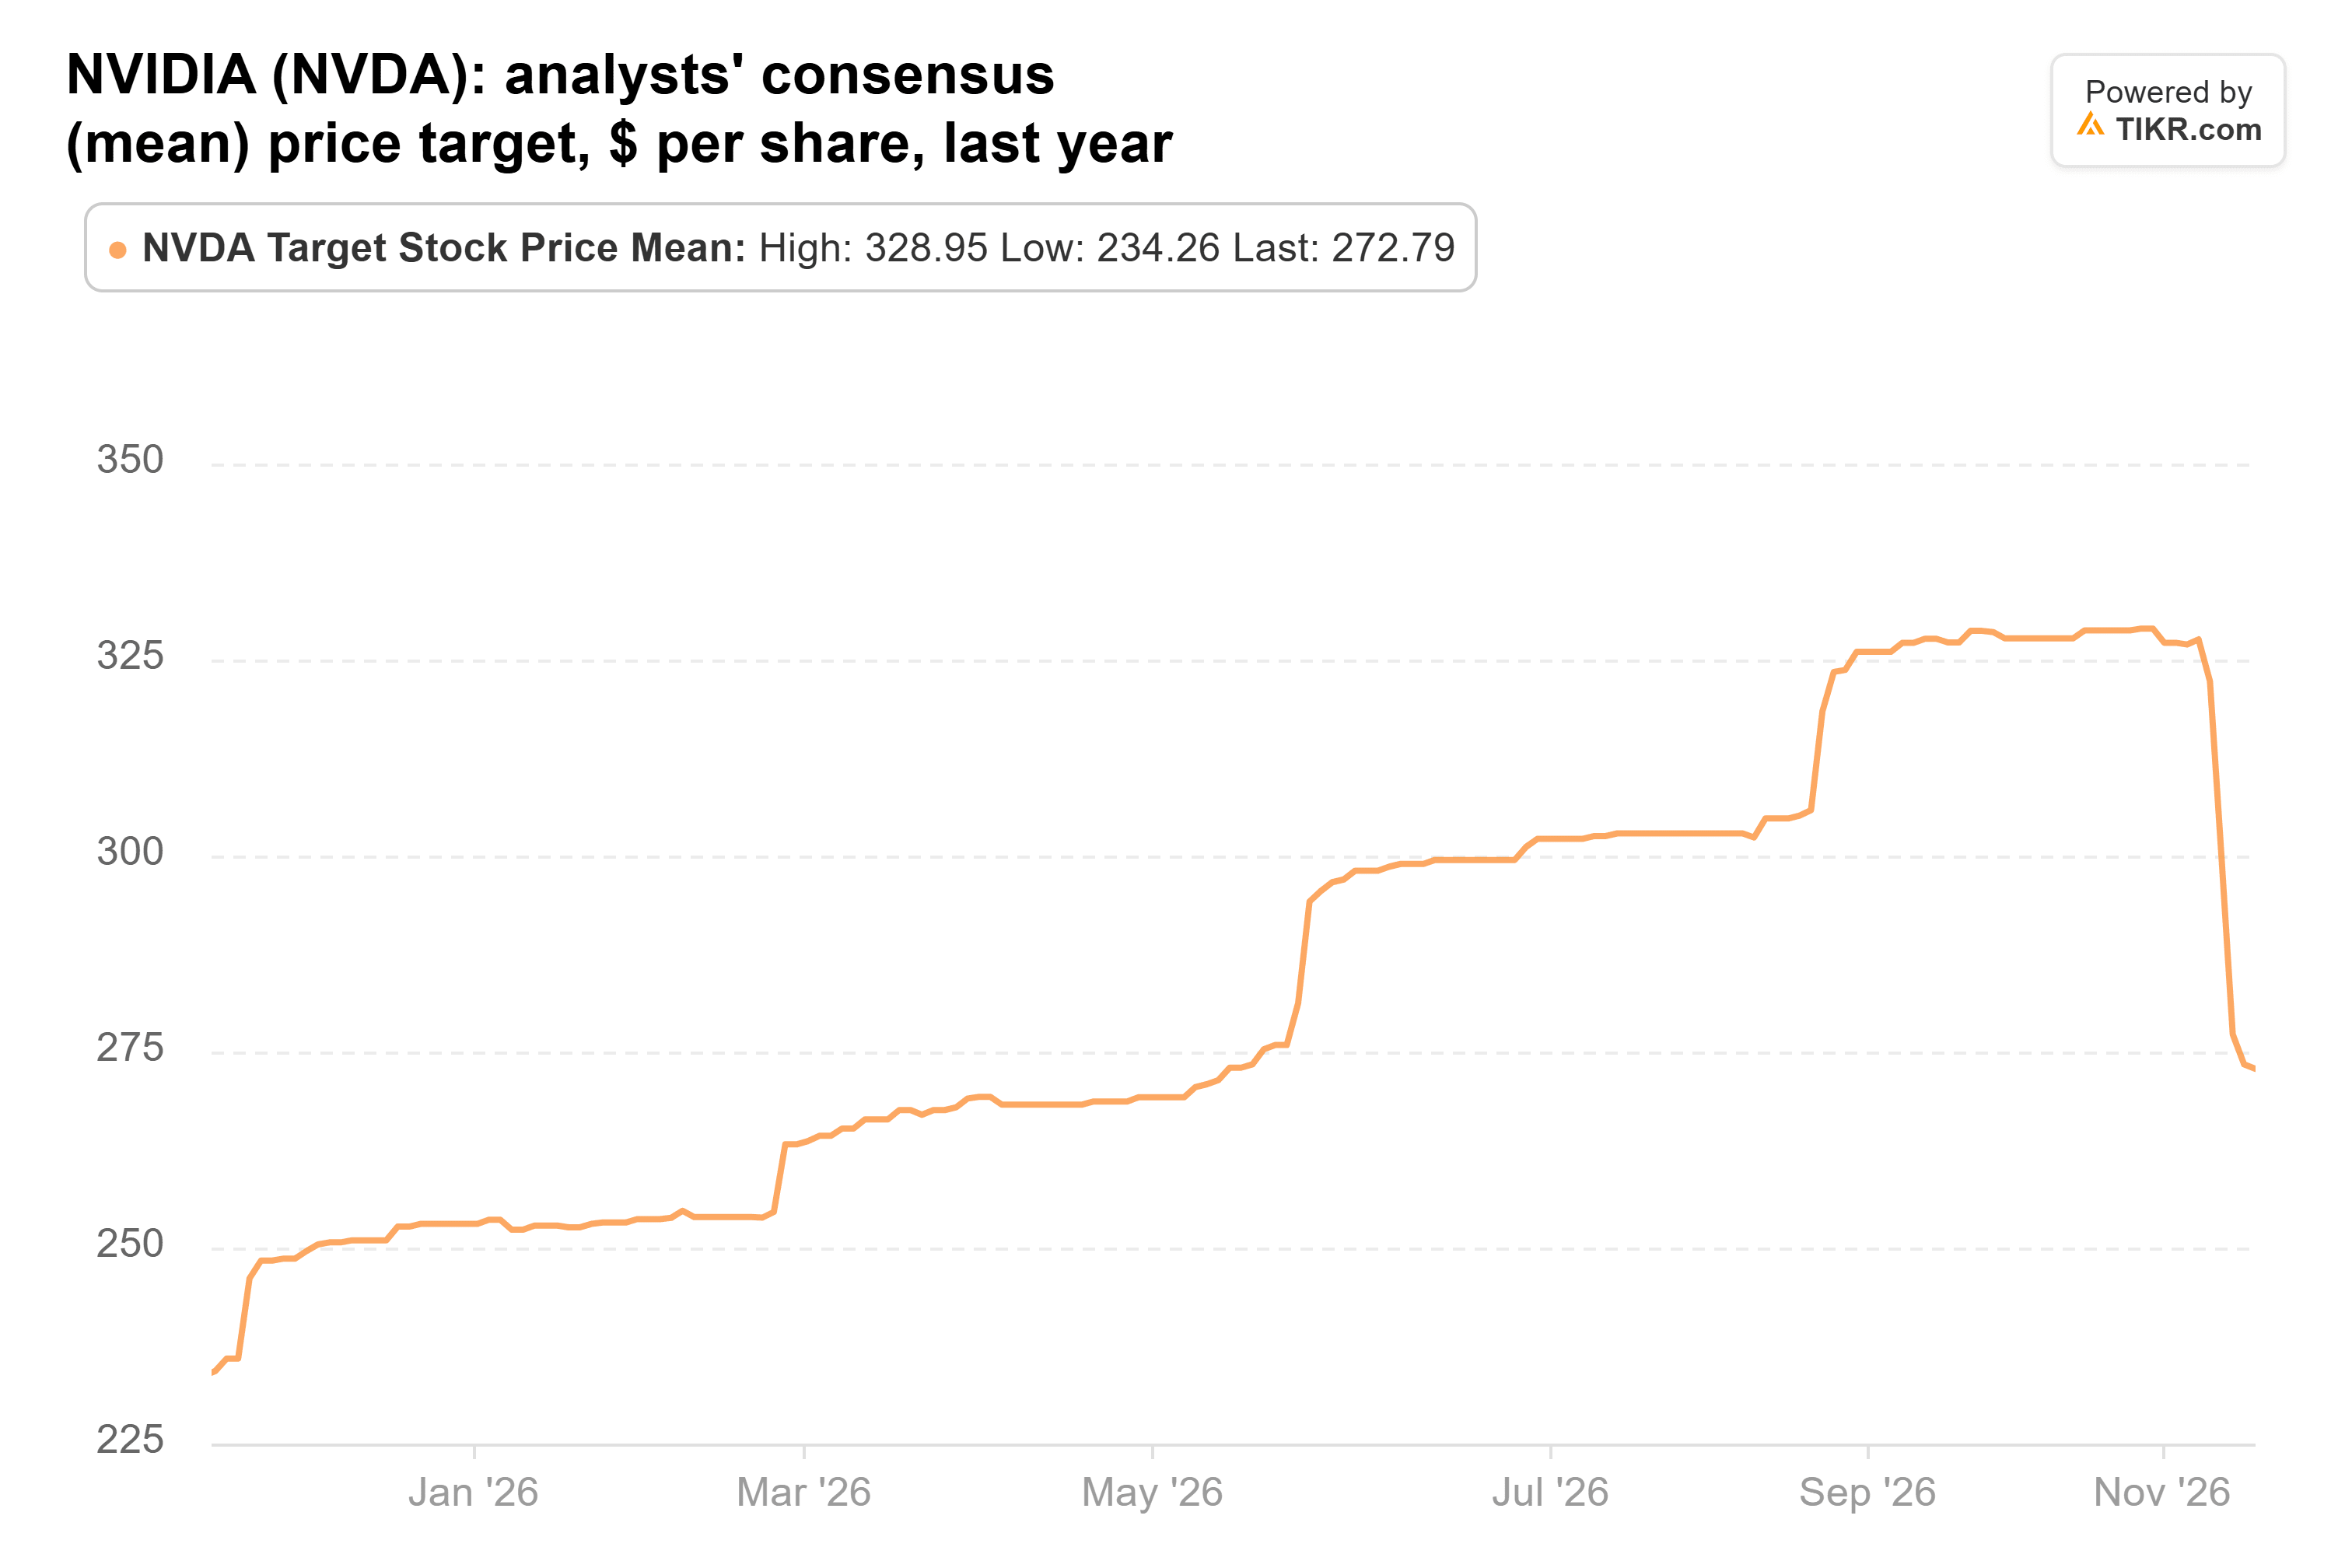
NVIDIA (NVDA) was the fund’s fifth-biggest position: 858,822 shares worth $196 million at Sept. 30, or 3.0% of the portfolio, after it cut the stake 19% in the quarter. It also held NVIDIA put options with a notional value of $80 million, which offset part of that bet. The stock has dropped 32% since, and on Nov. 12 Jensen Huang resigned as CEO, with CFO Colette Kress stepping in as interim CEO. The 62 analysts covering NVIDIA still see it reaching $268 on average, 71% above the last close. That target rose from $234 a year ago to a peak of $329 in late October before falling back:
At about 13x forward earnings, NVIDIA trades far below its five-year average of 36x. But its board is still looking for a permanent CEO, and the company reports its quarter this week.
TIKR tracks 62 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
2. Intel needs its estimates to stop falling
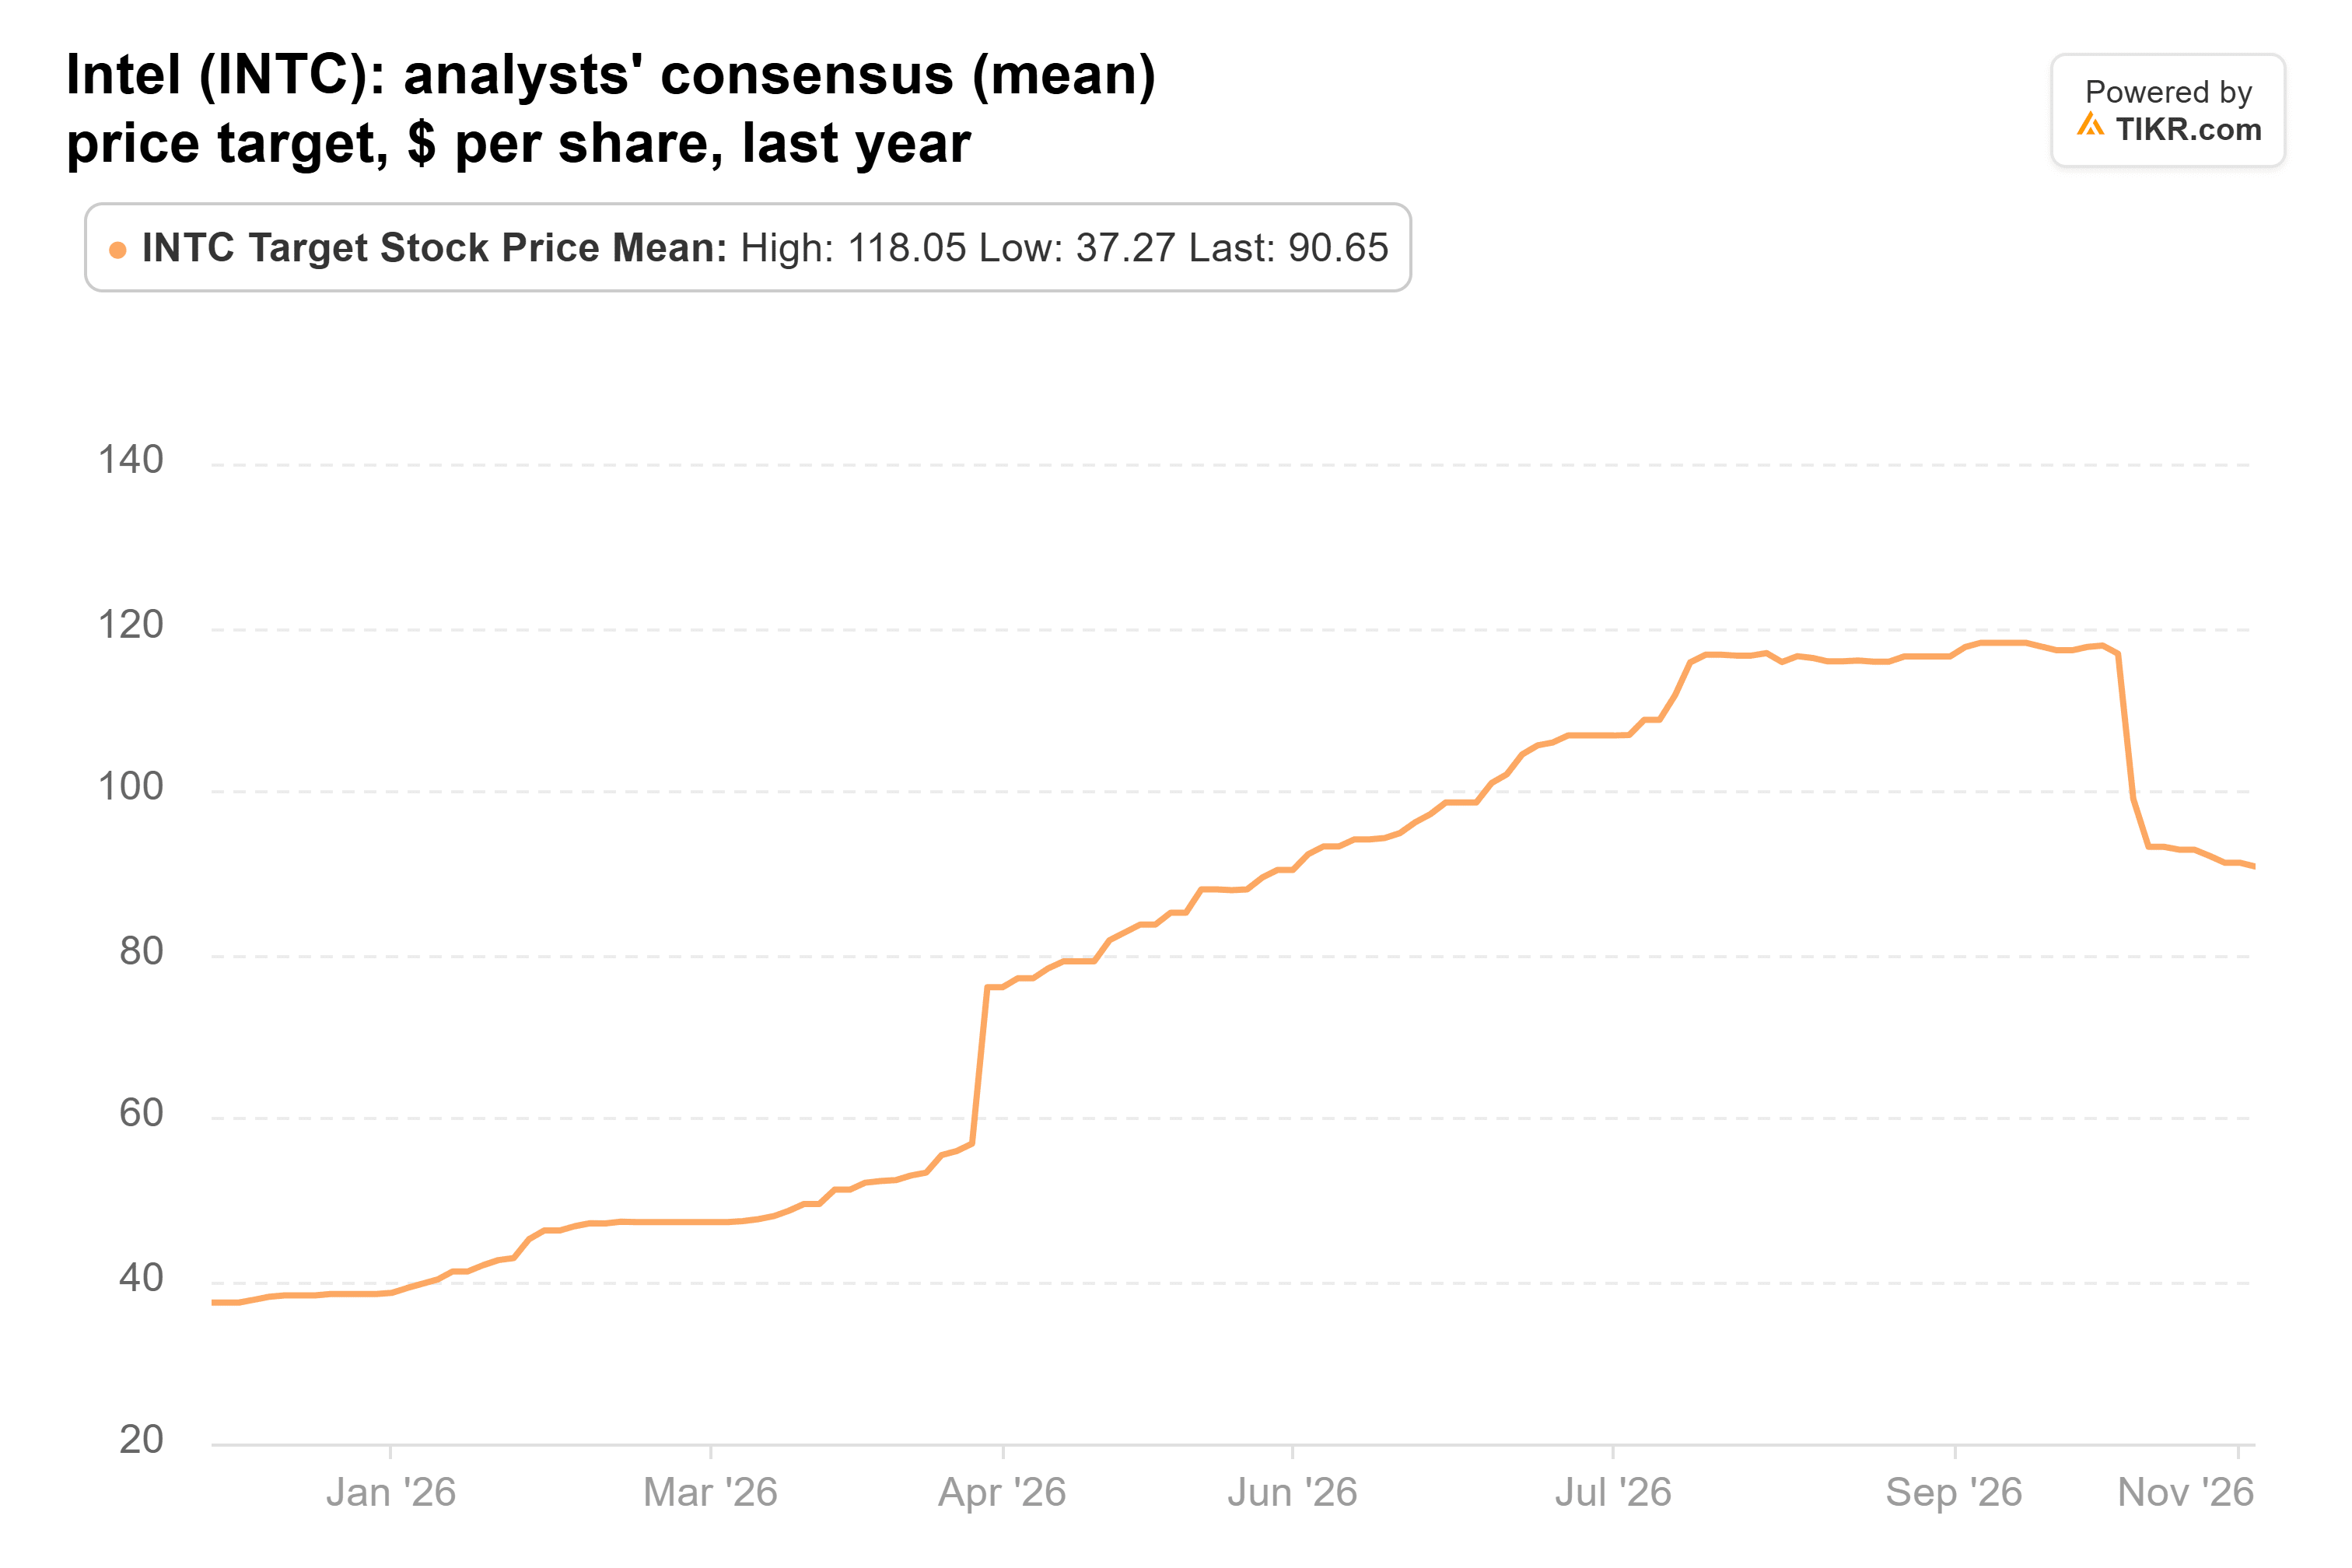
Intel (INTC) was the fund’s biggest position: 2.83 million shares worth $340 million, or 5.3% of the portfolio, after it grew the stake 2,730% in the third quarter. The stock has dropped 54% since Sept. 30, much of it after a weak fourth-quarter outlook on Oct. 29. CEO Lip-Bu Tan said in Intel’s third-quarter release that the immediate priority is “to unlock additional supply to meet extraordinary demand for our Xeon family.” Since that report, analysts have cut their 2027 earnings estimate to $1.79 a share, from $2.11. Their average target has fallen from a peak of $118 in early October to $91, still 63% above the last close:
Intel trades at about 40x forward earnings. That’s below its five-year average of 50x, but well above the 13x it averaged from 2014 to 2022, when it was a mature, profitable chipmaker. Tan bought $9.7 million of stock on Nov. 2, but I’d want to see the estimates stop falling before following him (or Soros) in.
3. Taiwan Semiconductor’s targets are still rising
Taiwan Semiconductor Manufacturing (TSM), or TSMC, was No. 3: 548,915 shares worth $250 million, or 3.9% of the portfolio, after a 5% add. The fund also held puts on it with a notional value of $46 million. The stock is down 18% since Sept. 30, but the business hasn’t slowed: October sales rose 59.7% from a year earlier to NT$586.89 billion, a 2026 high. Analysts kept raising their targets right through the selloff, taking the average from $340 a year ago to $587, its high for the year:
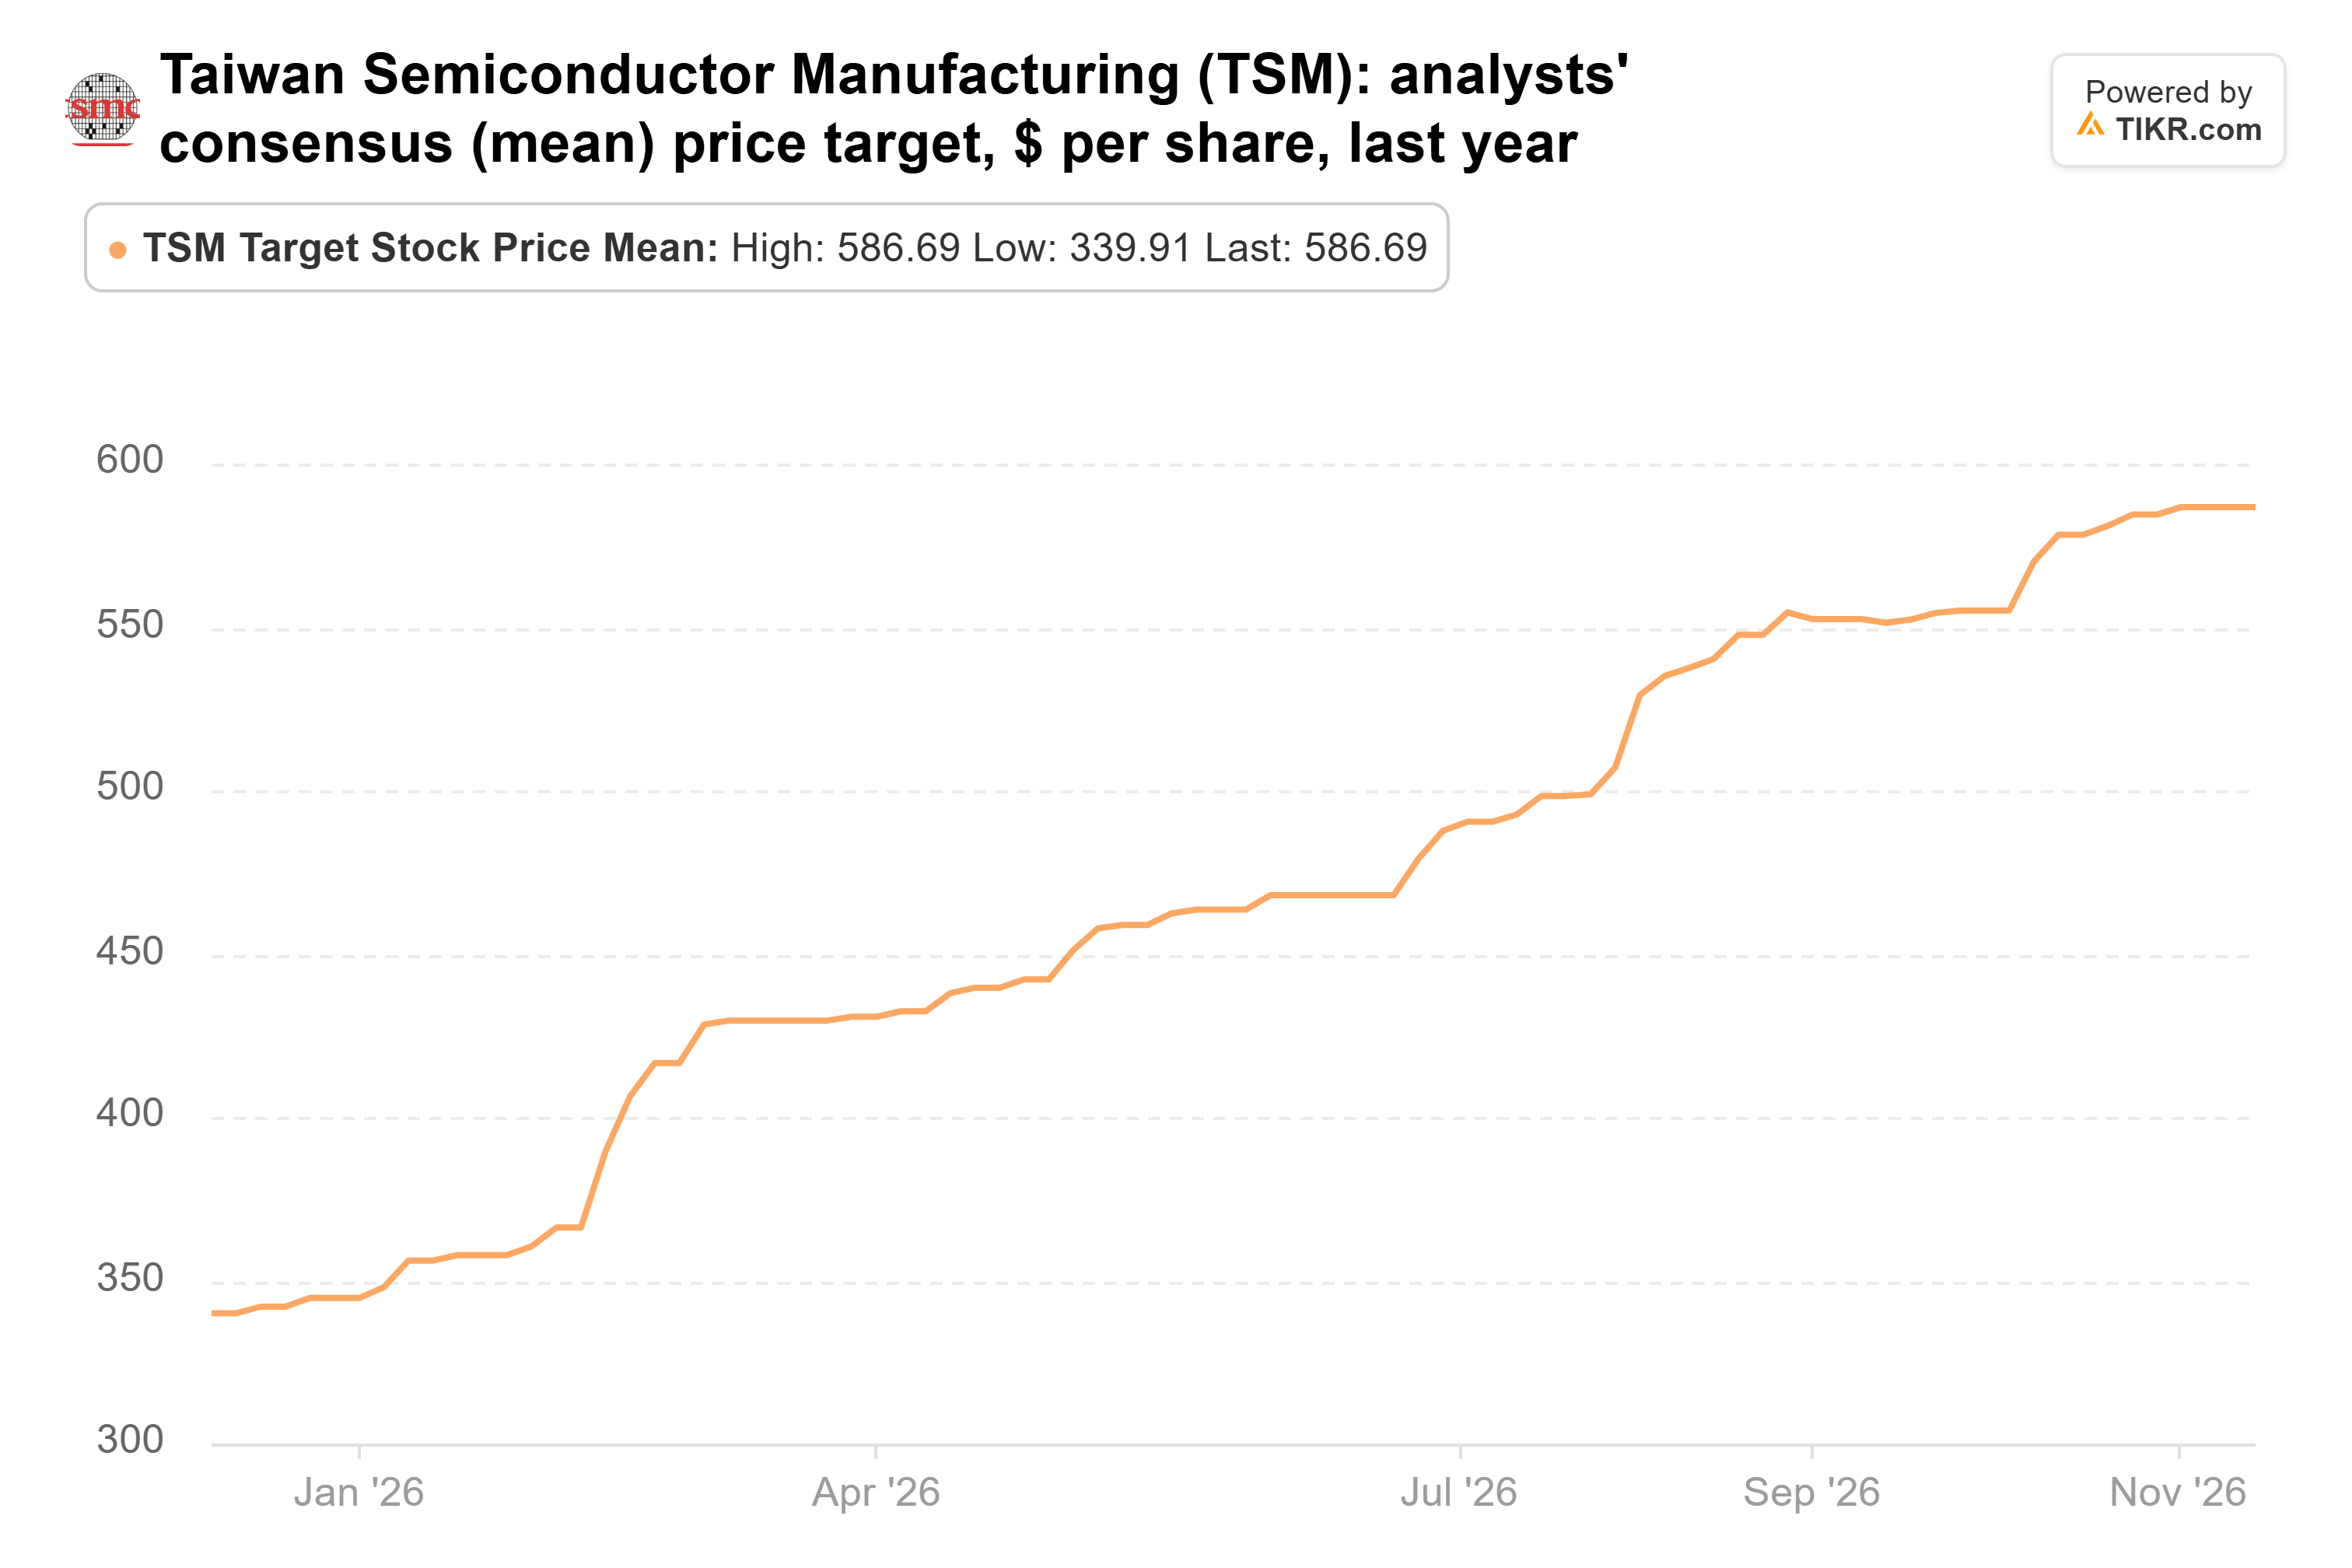
That’s 57% above the last close, and TSMC trades at about 18x forward earnings, right around its five-year average. The main risk is its build-out. TSMC plans to spend $60 billion to $64 billion on capital projects this year, mostly for capacity that starts producing in 2028 and 2029, so an AI slowdown before then would leave it paying for fabs it can’t fill.
4. Alphabet has a chip business of its own
Alphabet (GOOGL) was No. 4: 600,960 shares worth $207 million, or 3.2% of the portfolio, about the same as at June 30. The stock is down 18% since Sept. 30 and 31% from its 52-week high. Its own AI chips are a growing part of the case. Google Cloud revenue jumped 103% to $30.7 billion in the third quarter, with TPU sales a meaningful contributor, and Morgan Stanley sees direct TPU sales reaching $84 billion in 2027, up from about $8 billion this year. The average target has slipped from its July peak of $433, but it’s still well above where it was a year ago:
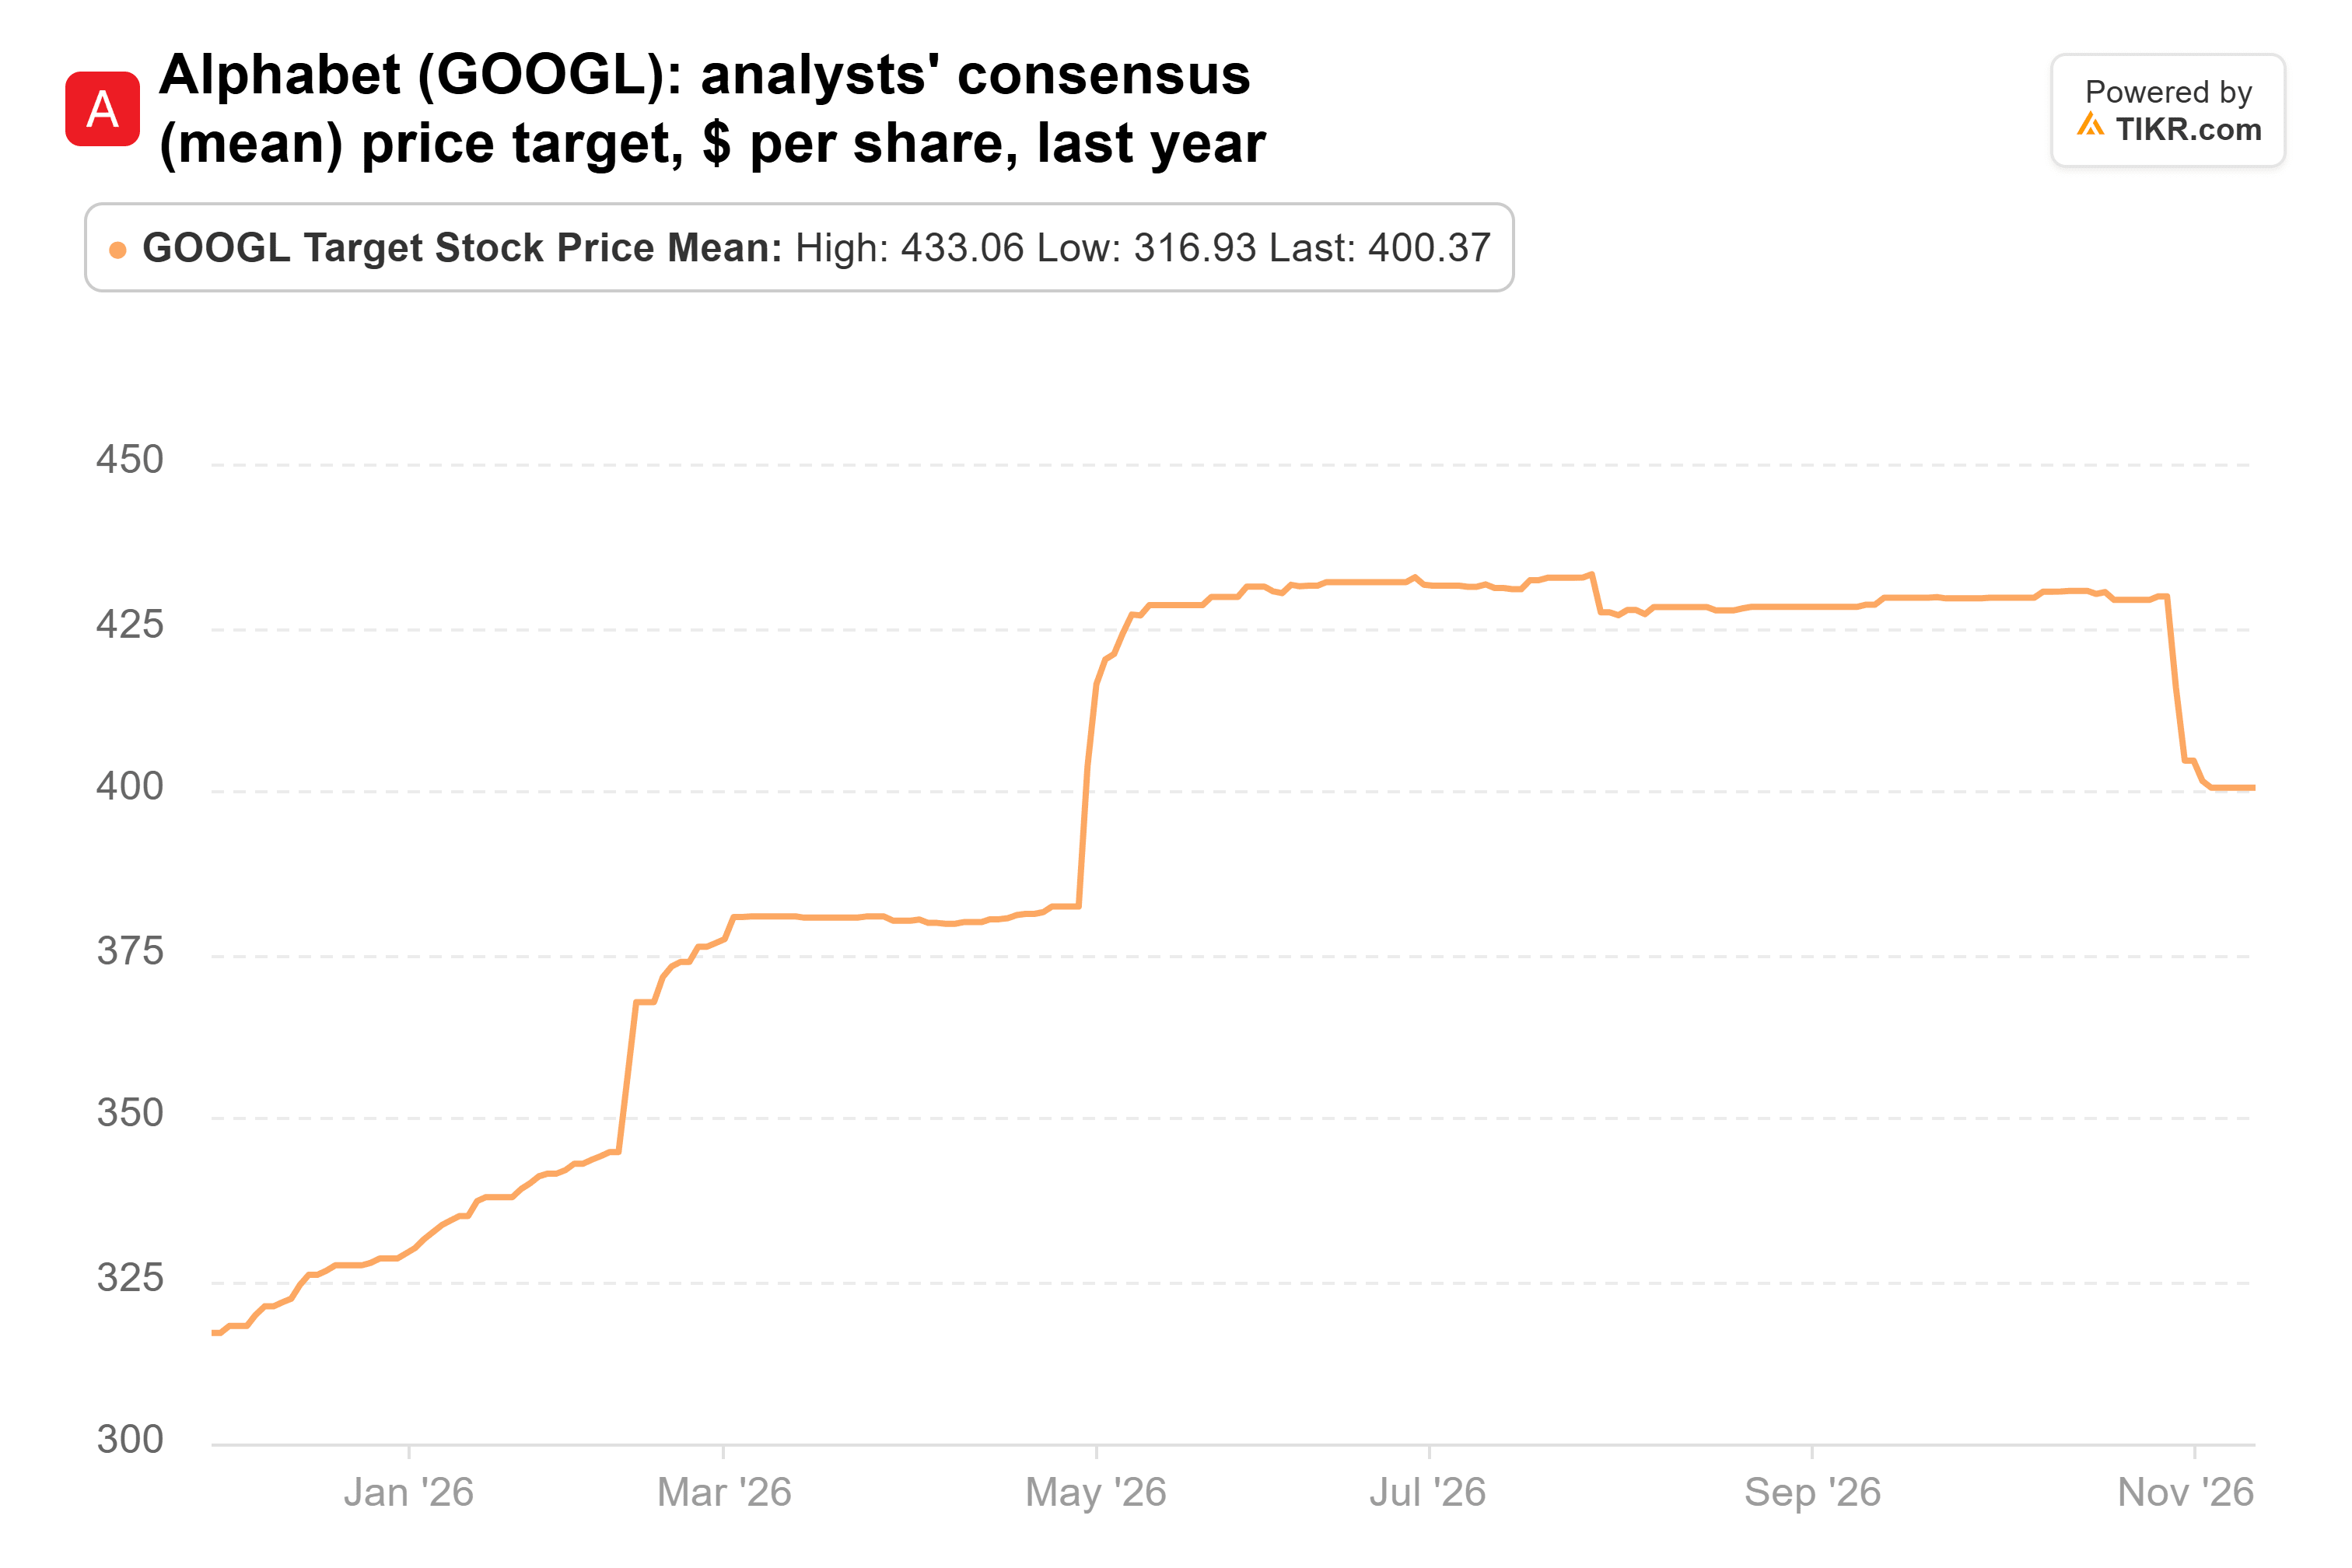
At $400, it’s 41% above the last close, and Alphabet trades at about 21x forward earnings. The risk is the spending: Alphabet plans about $200 billion of capital spending this year.
5. Amazon’s AWS is booming, and so is its borrowing
Amazon (AMZN) was No. 2: 1.06 million shares worth $263 million, or 4.1% of the portfolio, after it trimmed the stake 11%. It’s the only one of the five that’s up since Sept. 30, by 3%. AWS grew 39% in the third quarter, its fastest in five years. AWS CEO Matt Garman says it’s adding a GPU every 14 seconds and still expects to be short of capacity for the next couple of years. Analysts’ average target dipped to $280 in February and has since climbed to $326:
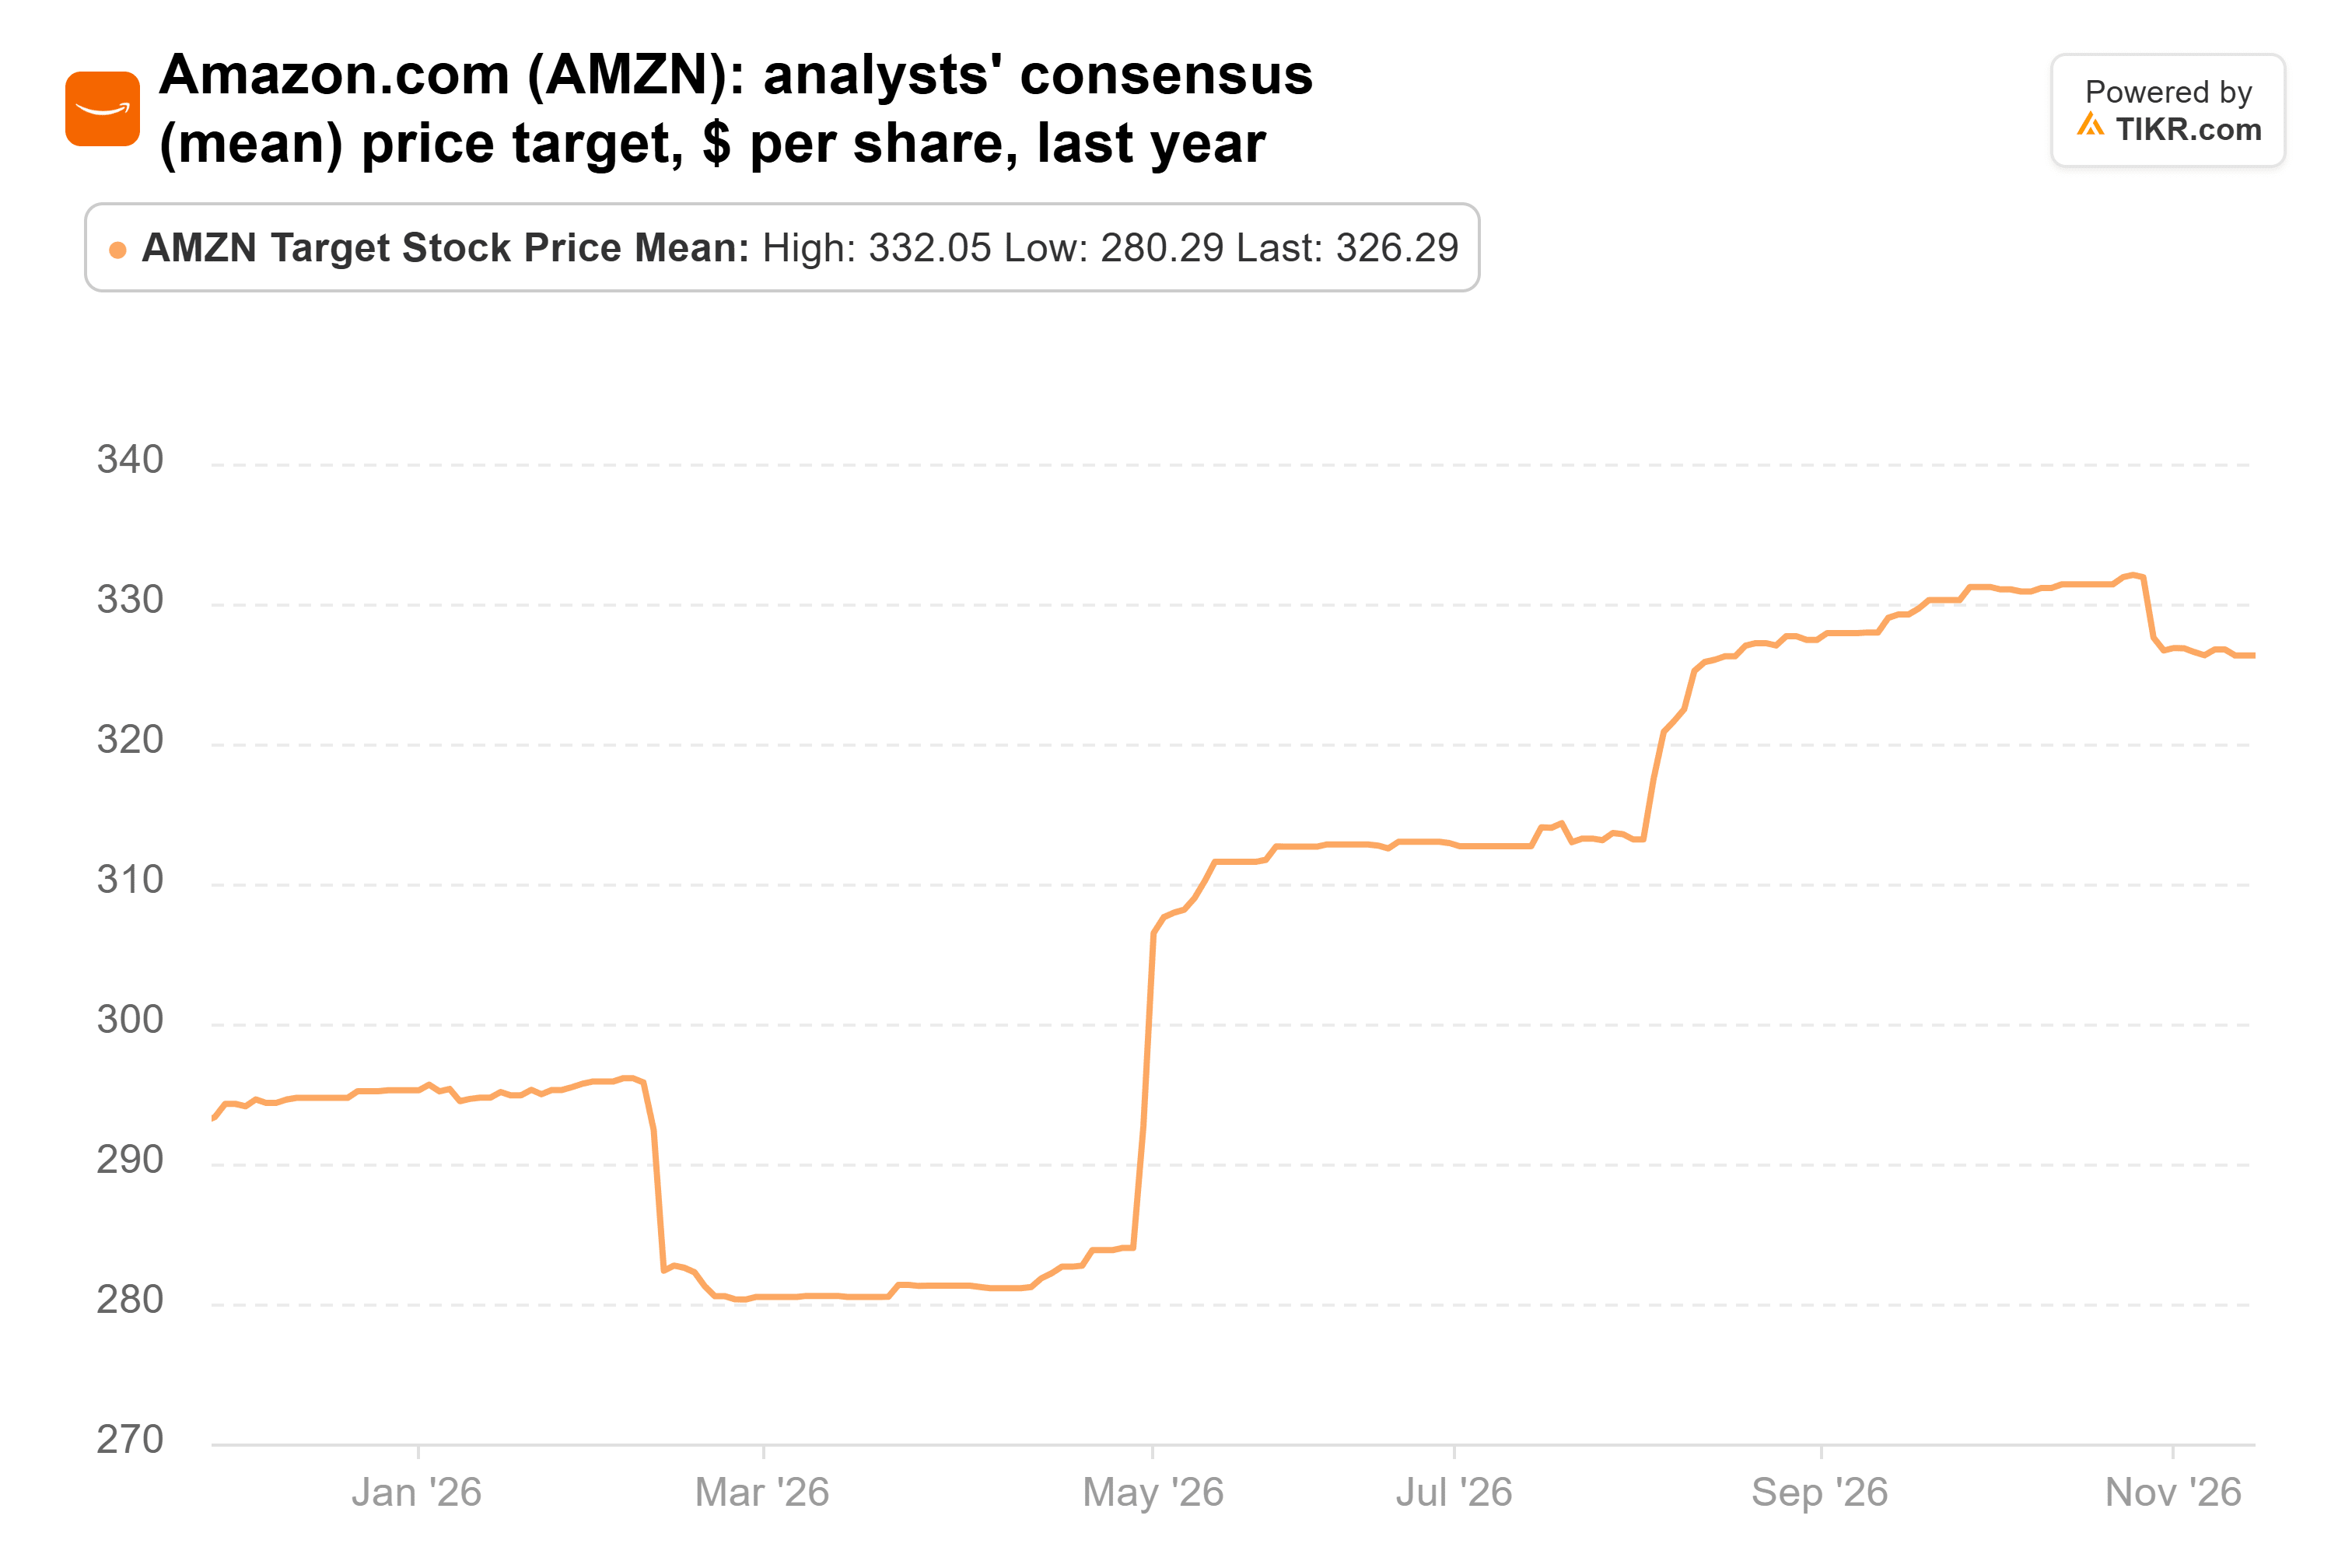
That’s 27% above the last close. At about 26x forward earnings, Amazon trades below its one-year average of 30x and far below its five-year average of 49x. Paying for all that capacity is the risk: Amazon has sold more than $92 billion of bonds this year.
The one I’d buy
If I could only buy one right now, it’d be Taiwan Semiconductor. Whichever company wins the AI chip race, TSMC will most likely make the chips, and analysts kept raising its target through the selloff.
NVIDIA has a strong case at 13x earnings, but I’d want to know who’s running it first. NVIDIA reports this week. It’s widely reported to be TSMC’s biggest customer, so investors in both will be watching its outlook. TSMC gives its 2027 outlook in mid-January, and Soros Fund Management’s next 13F, due in mid-February, will show which of these bets it kept.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



