Key Takeaways
- Evercore ISI reiterated its Buy rating on Snowflake on Nov. 12 and raised its price target to $430, 51% above the current price.
- The stock is 26% below its September high, and Snowflake itself hasn’t reported bad news, while Datadog’s flat fourth-quarter guide is a reminder that usage-based revenue can stall.
- Evercore’s $430 implies 171x forward earnings, close to Snowflake’s three-year average, and analysts have raised their earnings estimates over the past 90 days.
- The numbers back Evercore’s call, but a slipping gross margin is the risk, and Snowflake’s Dec. 2 report is the next test.
Snowflake (SNOW) now sits 26% below its September high. On Nov. 12, Evercore ISI’s Kirk Materne reiterated his Buy rating anyway and raised his price target to $430 from $360, 51% above today’s $285.
No bad news, just worries
Snowflake’s second-quarter report on Sept. 2 sent the stock to that high. Product revenue grew 37% to $1.49 billion, its third straight quarter of acceleration, and management raised its full-year outlook to 36% growth. But the same report cut the year’s product gross margin outlook to 74%, from 75%. CFO Brian Robins said the new outlook “includes a higher revenue mix from fast-growing AI workloads, which carry a lower contribution margin today.”
Snowflake hasn’t reported anything bad since. The fresher scare came from Datadog (DDOG), which also bills on usage. It grew third-quarter revenue 35% to $1.20 billion, then guided the fourth quarter to $1.19 billion to $1.20 billion, about flat, after its largest customer cut usage. My read: investors worry Snowflake’s usage-based revenue could stall the same way.
TIKR tracks 51 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Evercore just caught up with the Street
Materne’s $430 sits right at the $434 consensus target, so this raise takes him to where most of the Street already was. On Snowflake’s September call, he asked how much of the acceleration came from the new AI products and how much from the core. CEO Sridhar Ramaswamy said the AI products “contributed approximately half of the acceleration that we are seeing.” So the core sped up too, which gives a target a sturdier base than one hot product would.
Does $430 add up?
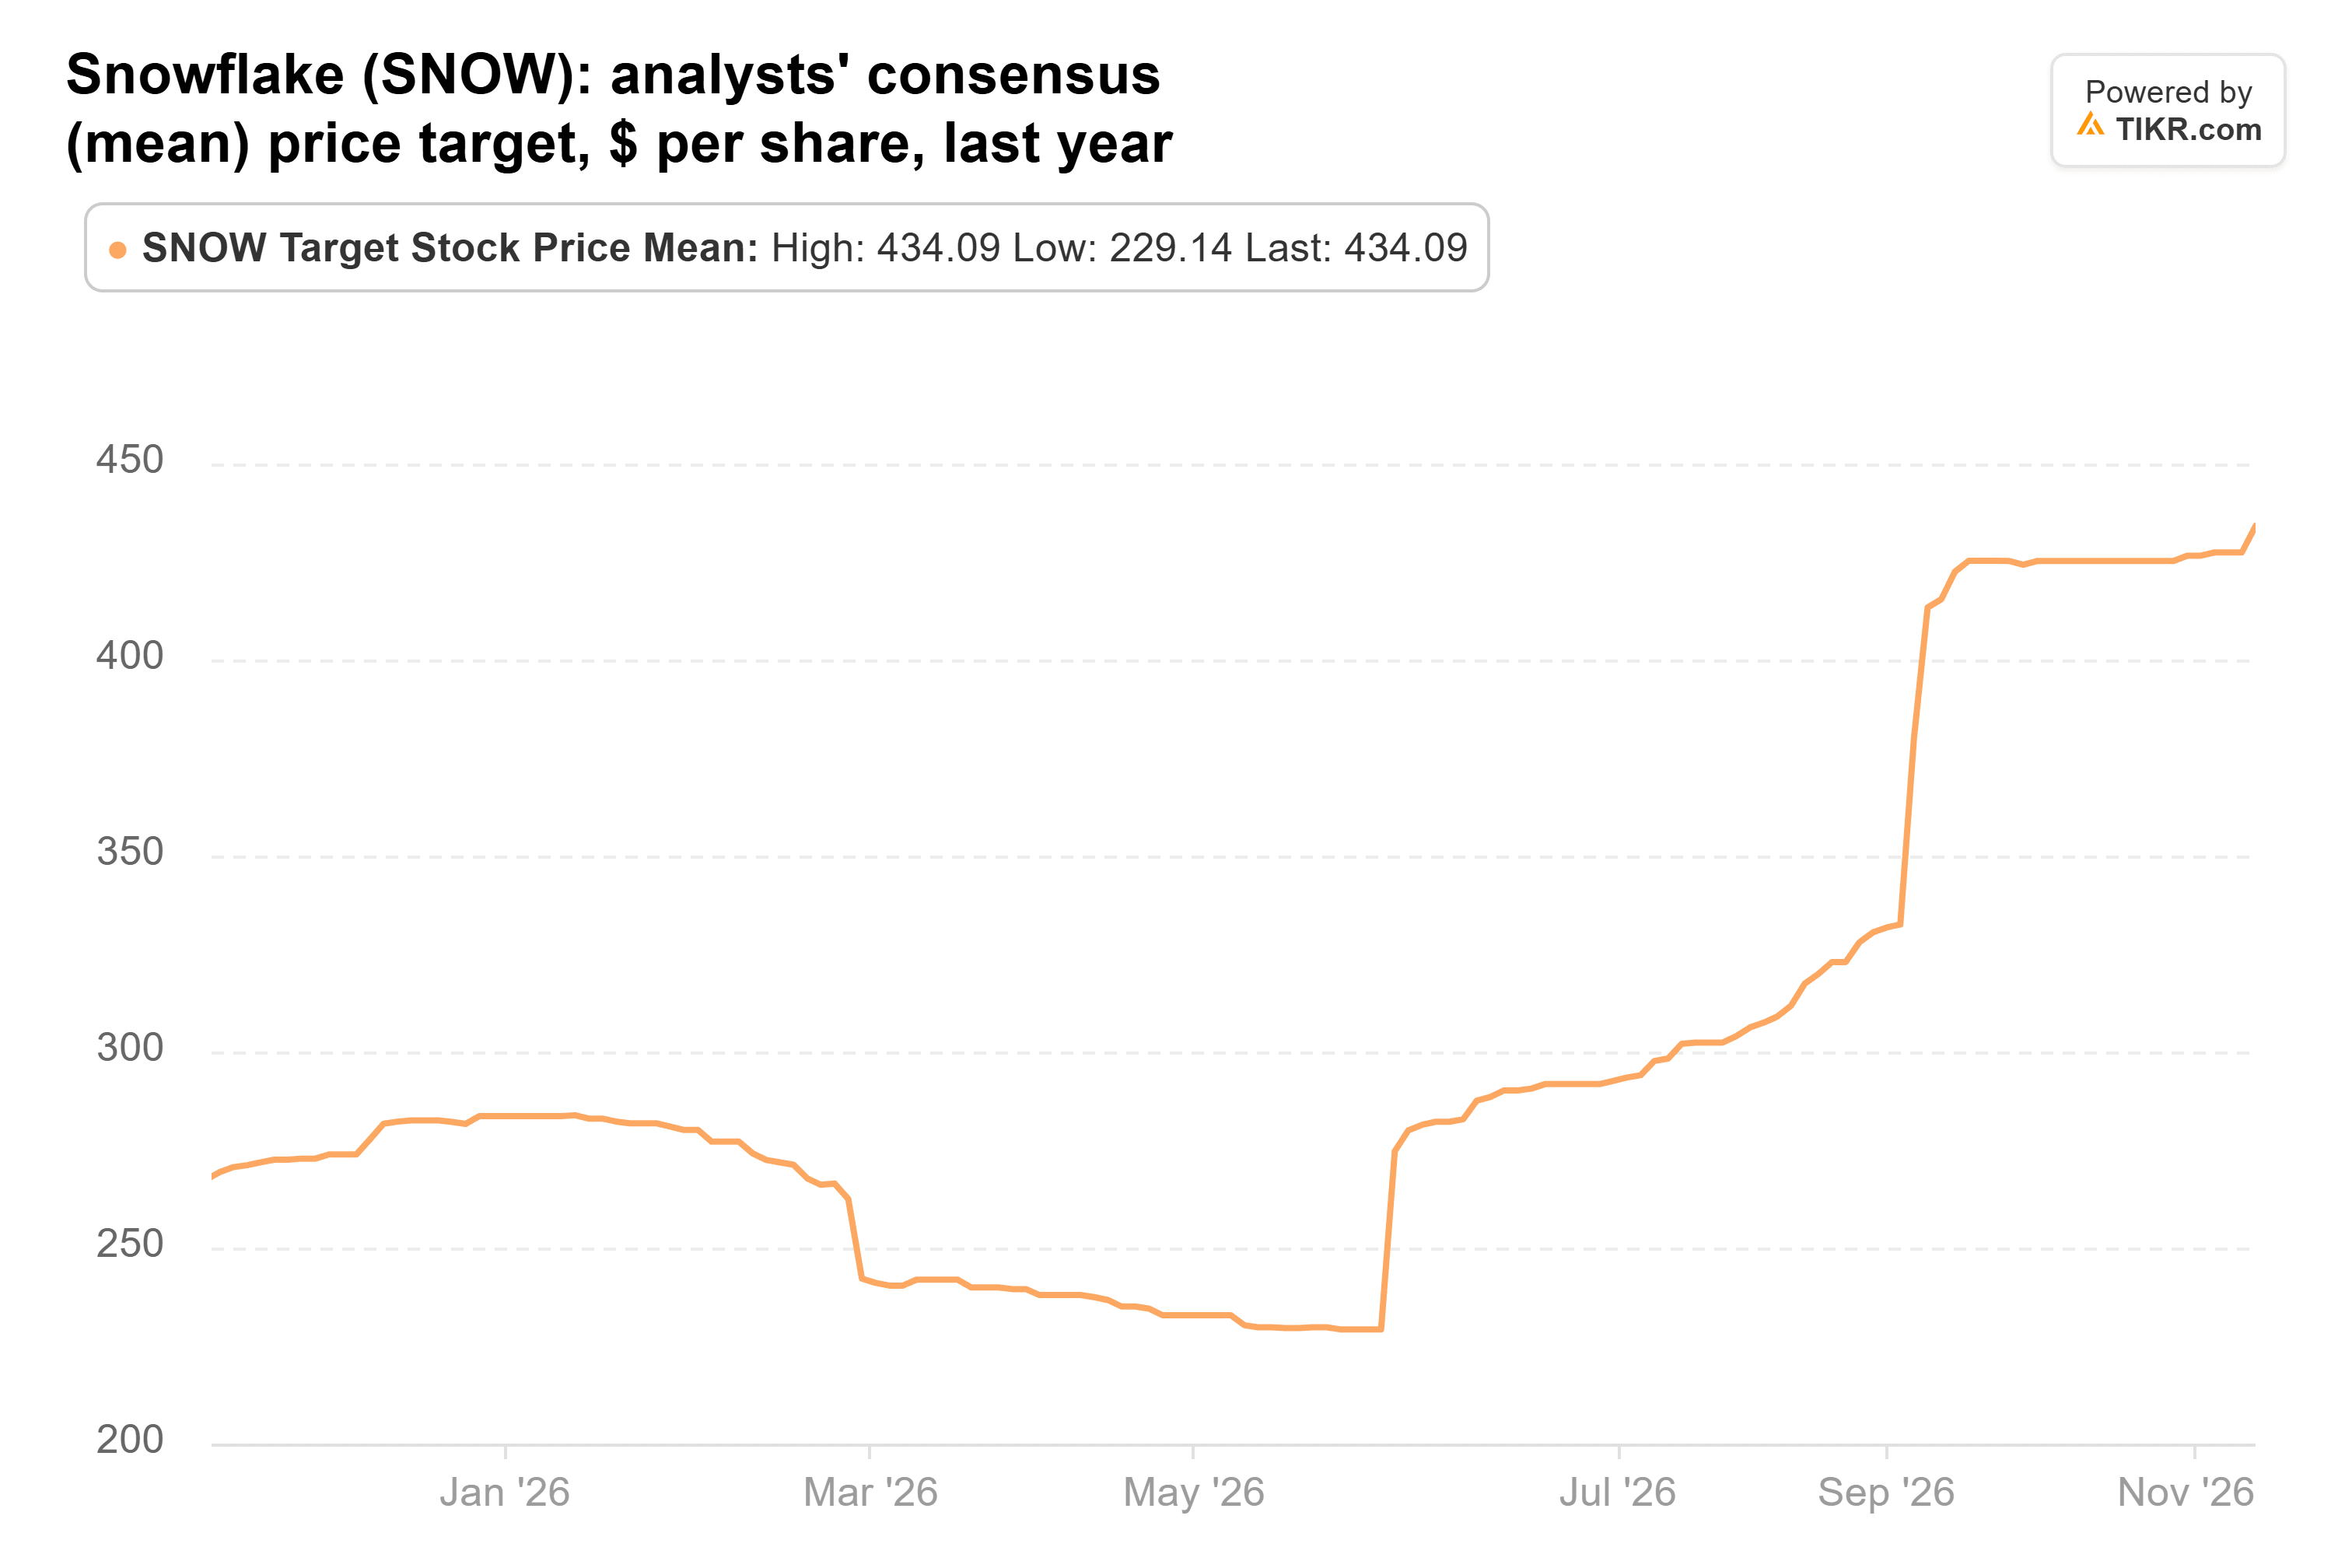
The 53 analysts who cover Snowflake have kept raising their targets through the slide. The consensus has climbed from $269 a year ago to $434 today:
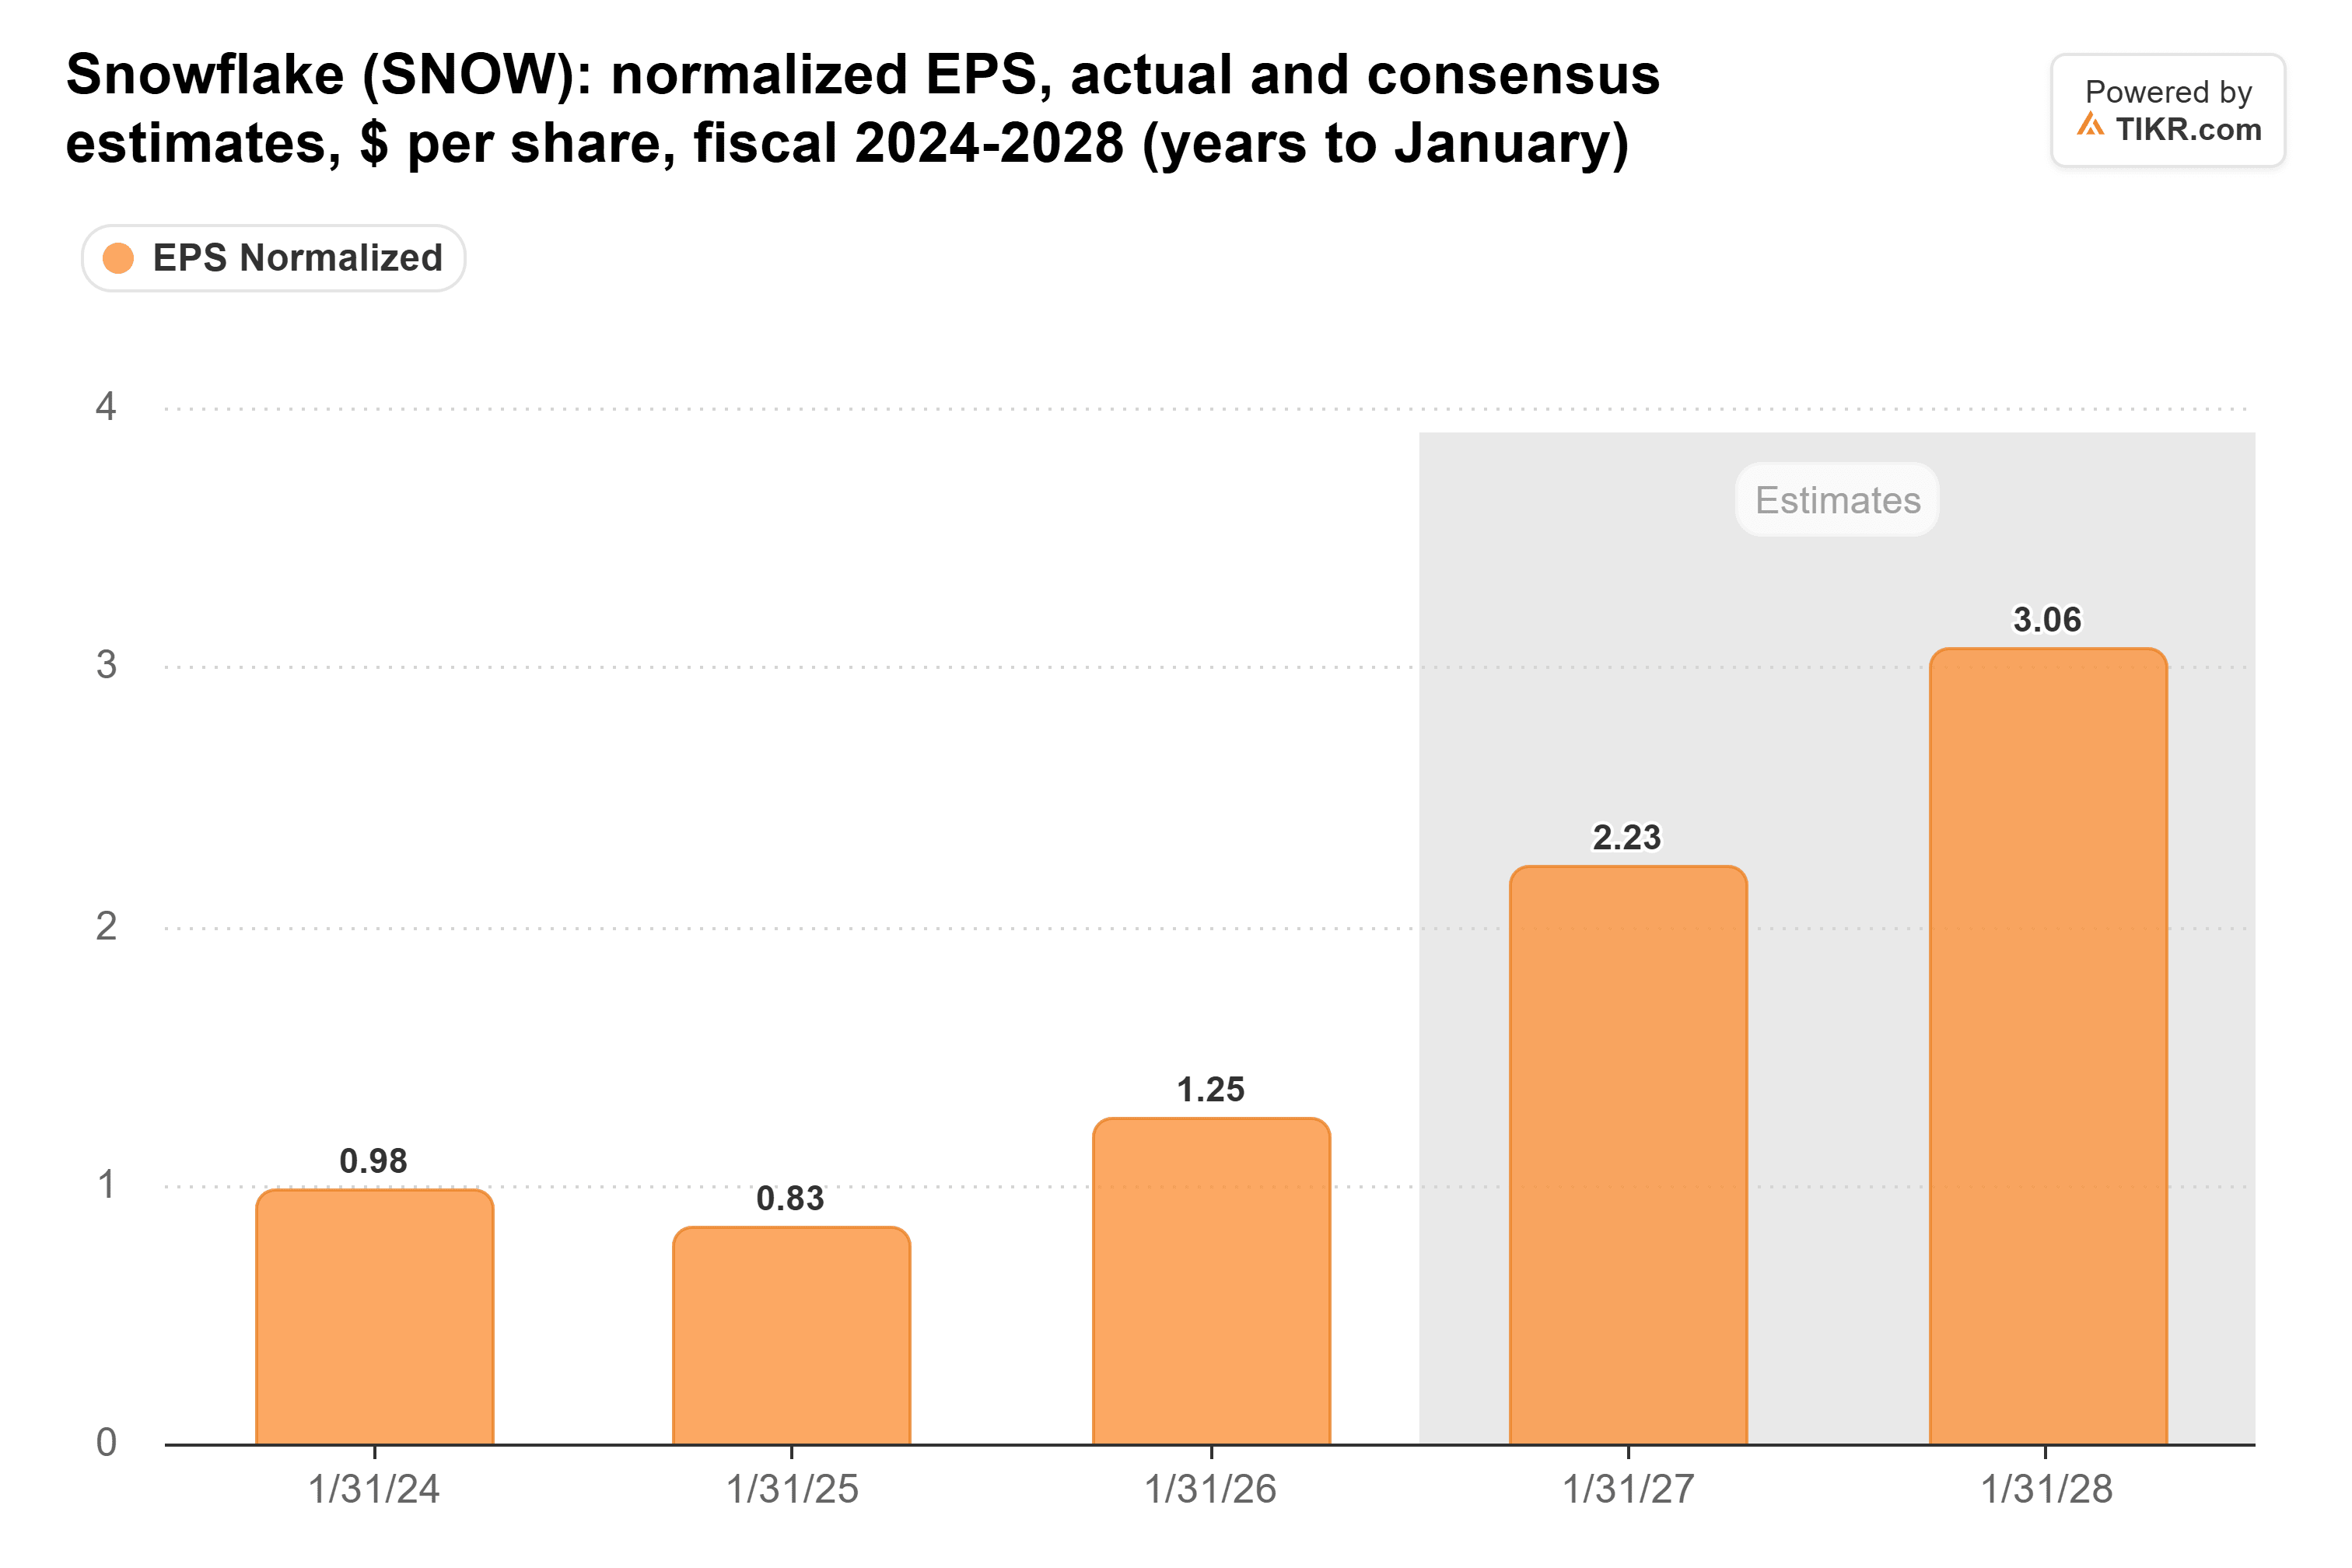
Earnings estimates have moved the same way. Analysts now expect normalized EPS of $2.23 for fiscal 2027 (the year ending January 2027), up from $1.94 90 days ago. For fiscal 2028 they expect $3.06, up from $2.70:
At its last close, Snowflake traded at 115x forward earnings. Evercore’s $430 works out to 171x those same earnings. That’s close to the stock’s three-year average of 165x and above its one-year average of 130x. It’s a lot to pay, but if estimates keep rising, the multiple at $430 comes down as the next year’s earnings roll in.
The margin is the catch
Snowflake earns less gross profit on each AI dollar than on its core business. Its cloud costs rose to 75% of its cost of product revenue in the second quarter, from 70% a year earlier. Still, I’m with Evercore on this one: $430 asks for about Snowflake’s three-year average multiple, and estimates keep going up. The next check comes after the close on Dec. 2, when Snowflake reports its third quarter against a product revenue guide of $1,588 million to $1,593 million and a 74% gross margin outlook for the year. If it shows anything like Datadog’s flat guide, the Street’s targets could be the next thing to fall.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!