Key Takeaways
- D-Wave’s third-quarter revenue rose 21% to $4.5 million, but quarterly bookings fell 19% to $1.9 million.
- Year-to-date bookings reached $37.4 million, up 611%, and management expects to deliver a $20 million Florida Atlantic University system in the fourth quarter.
- GAAP gross margin fell to 52.9% from 71.4%, while the adjusted EBITDA loss widened 83% to $37.7 million.
- IonQ’s $173.8 million quarter shows the scale gap, and D-Wave’s fourth-quarter report, expected in March, must show the backlog converting.
D-Wave Quantum (QBTS) reported third-quarter revenue of $4.5 million on November 10, up 21% from a year earlier. Yet a smaller number drew more attention, because quarterly bookings fell 19% to $1.9 million.
That stings since orders are D-Wave’s best argument. Year-to-date bookings reached $37.4 million, a 611% jump, and remaining performance obligations rose to $38.3 million.
Meanwhile, IonQ (IONQ) reported $173.8 million of third-quarter revenue, up 336%. That single quarter is more than 16 times what D-Wave has recognized all year.
CEO Alan Baratz sounded confident anyway. “Our triple-digit increase in year-to-date bookings and robust pipeline reinforce our confidence in the opportunity ahead,” he said in the earnings release.
Orders arrived early, revenue lags
The quarter’s mix shifted sharply:
- Professional services revenue rose $1.5 million to $2.0 million.
- Quantum computing as a service revenue grew $0.8 million to $2.2 million.
- System sales revenue fell $1.5 million.
Commercial enterprises made up 48% of the more than 100 customers that generated revenue. Because system sales are lumpy, the year-to-date view looks worse. Nine-month revenue was $10.4 million, down 52% from $21.8 million, against a comparison built on bigger system sales.
So the quarterly line stays choppy…
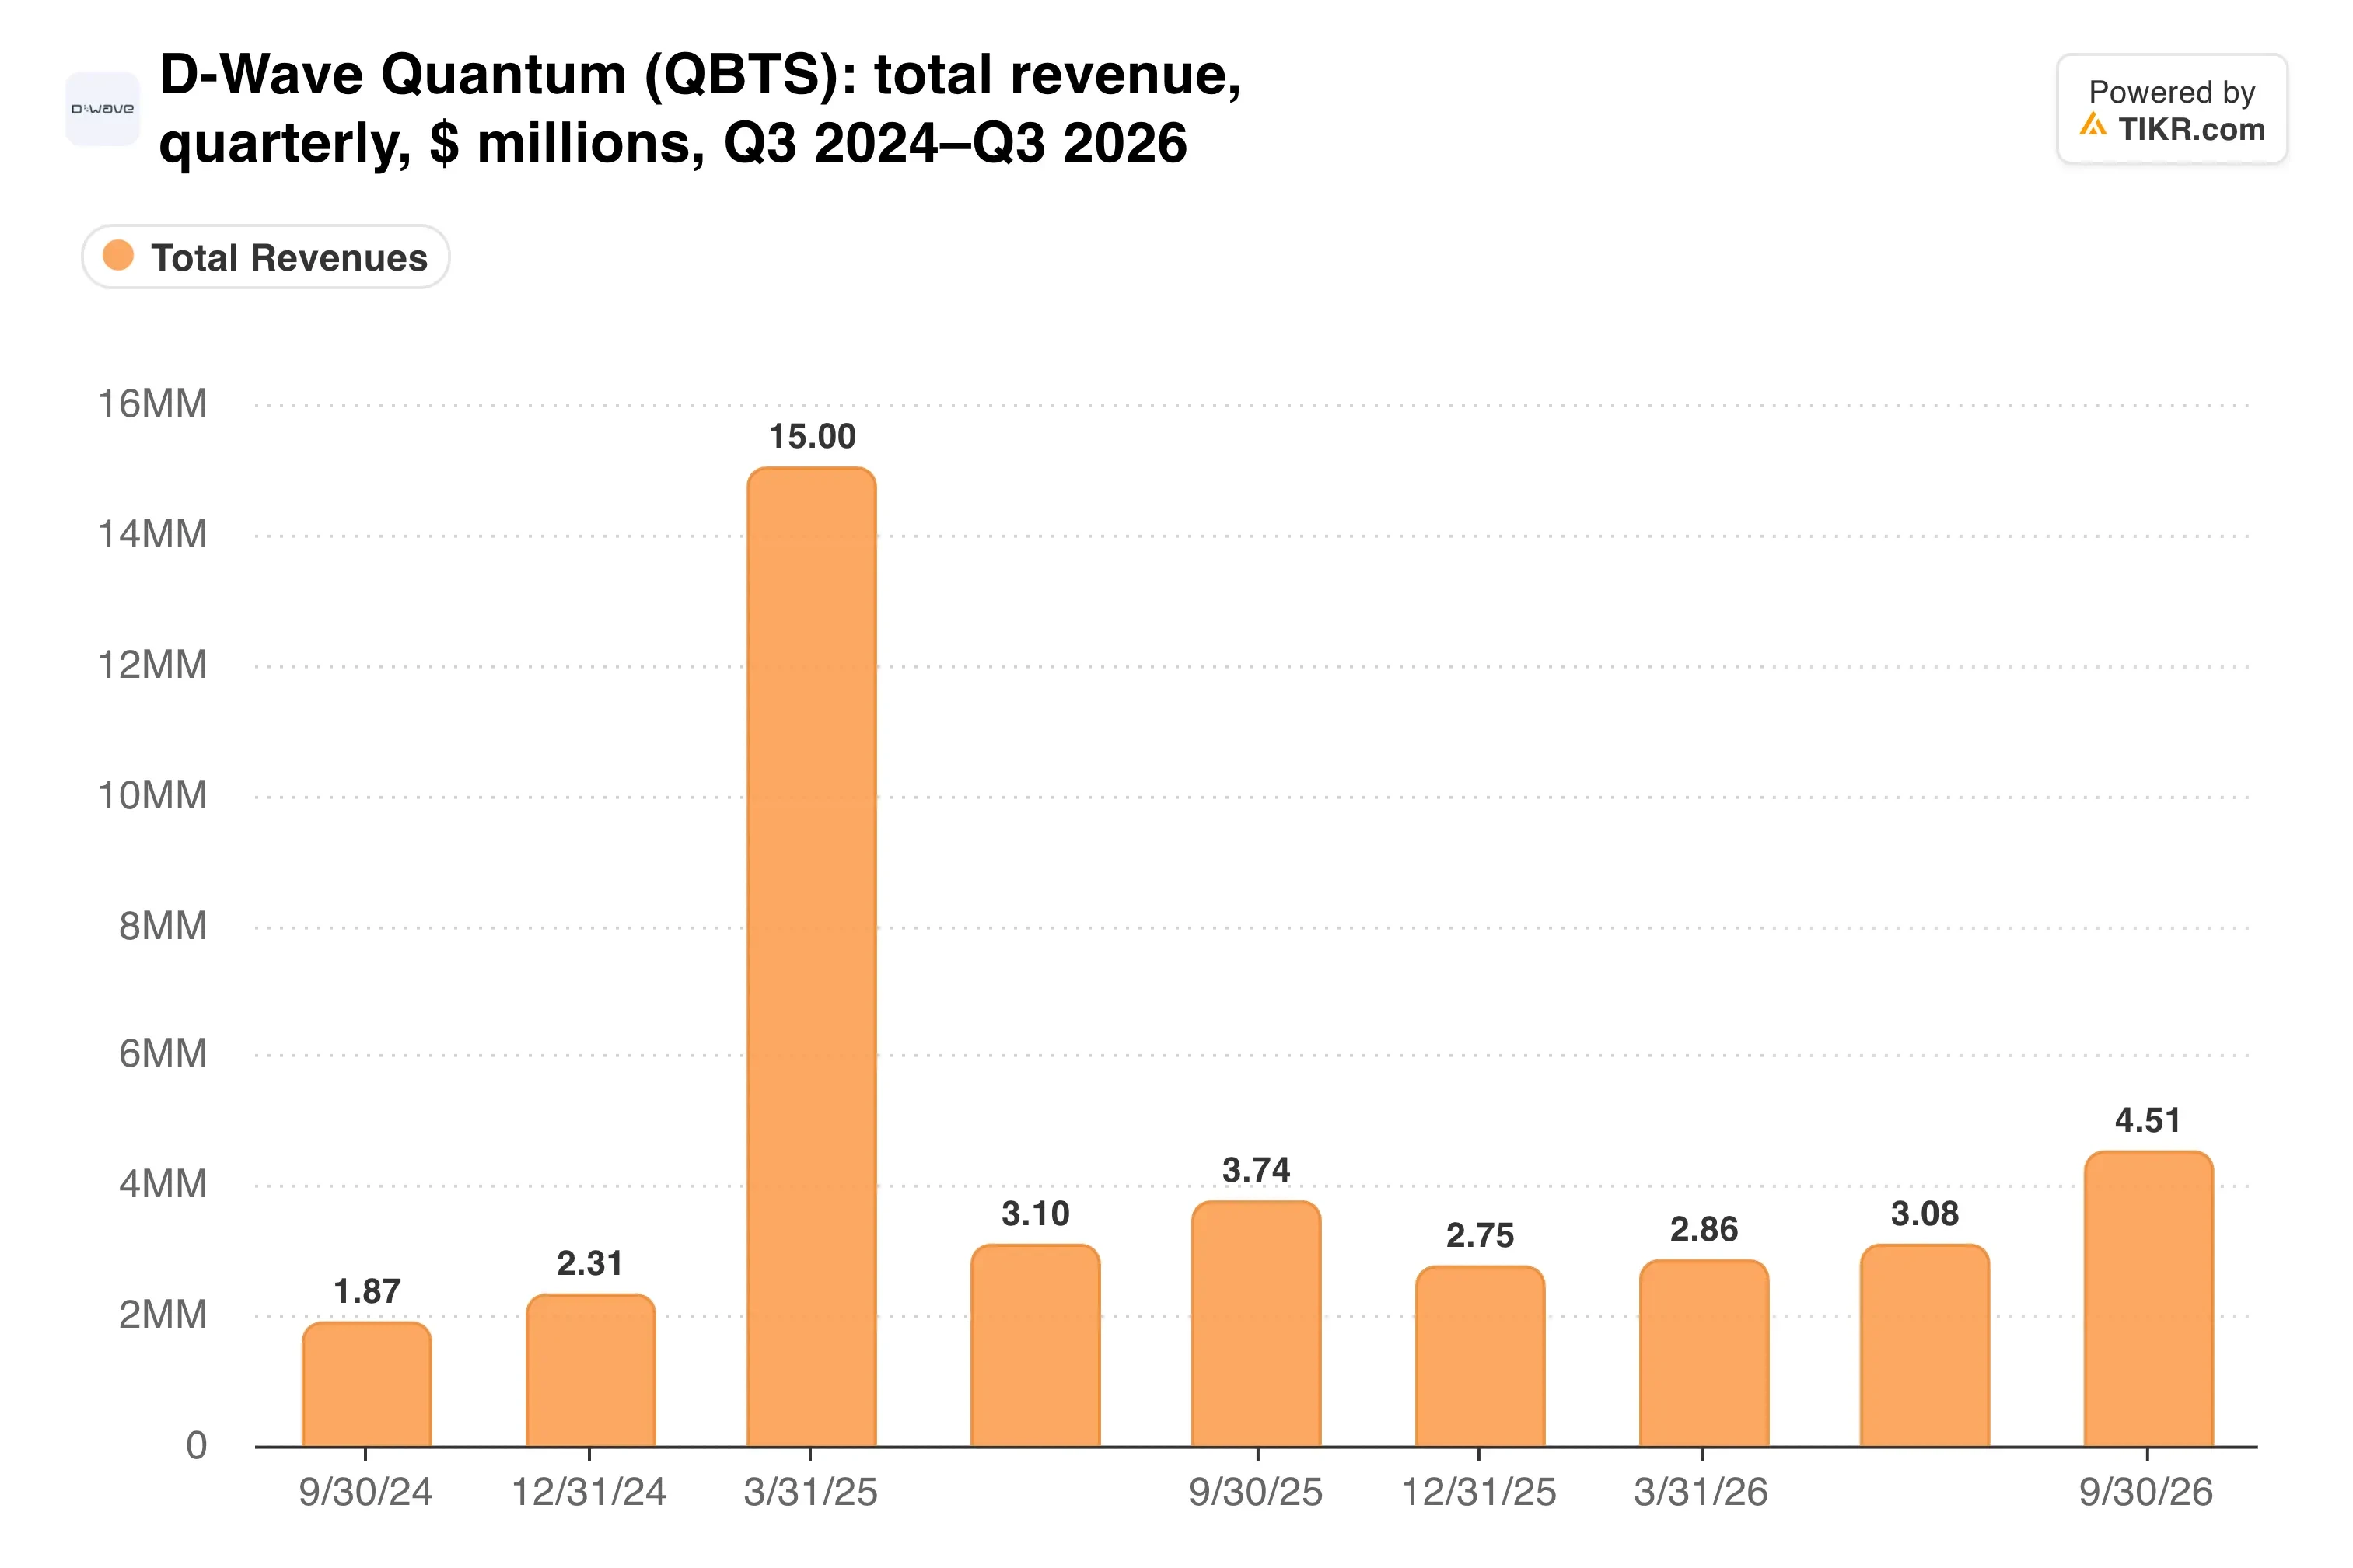
The fourth quarter should look different, though. Management expects to deliver the $20 million Florida Atlantic University system then and recognize a substantial portion of its revenue.
TIKR tracks 17 analysts on D-Wave Quantum. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on D-Wave Quantum, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See D-Wave Quantum’s Analyst Ratings
A foundry partner owned by a rival
The mix shift also dented profitability. GAAP gross margin fell to 52.9% from 71.4%, since lower-margin professional services made up more of revenue.
How much of that reverses?
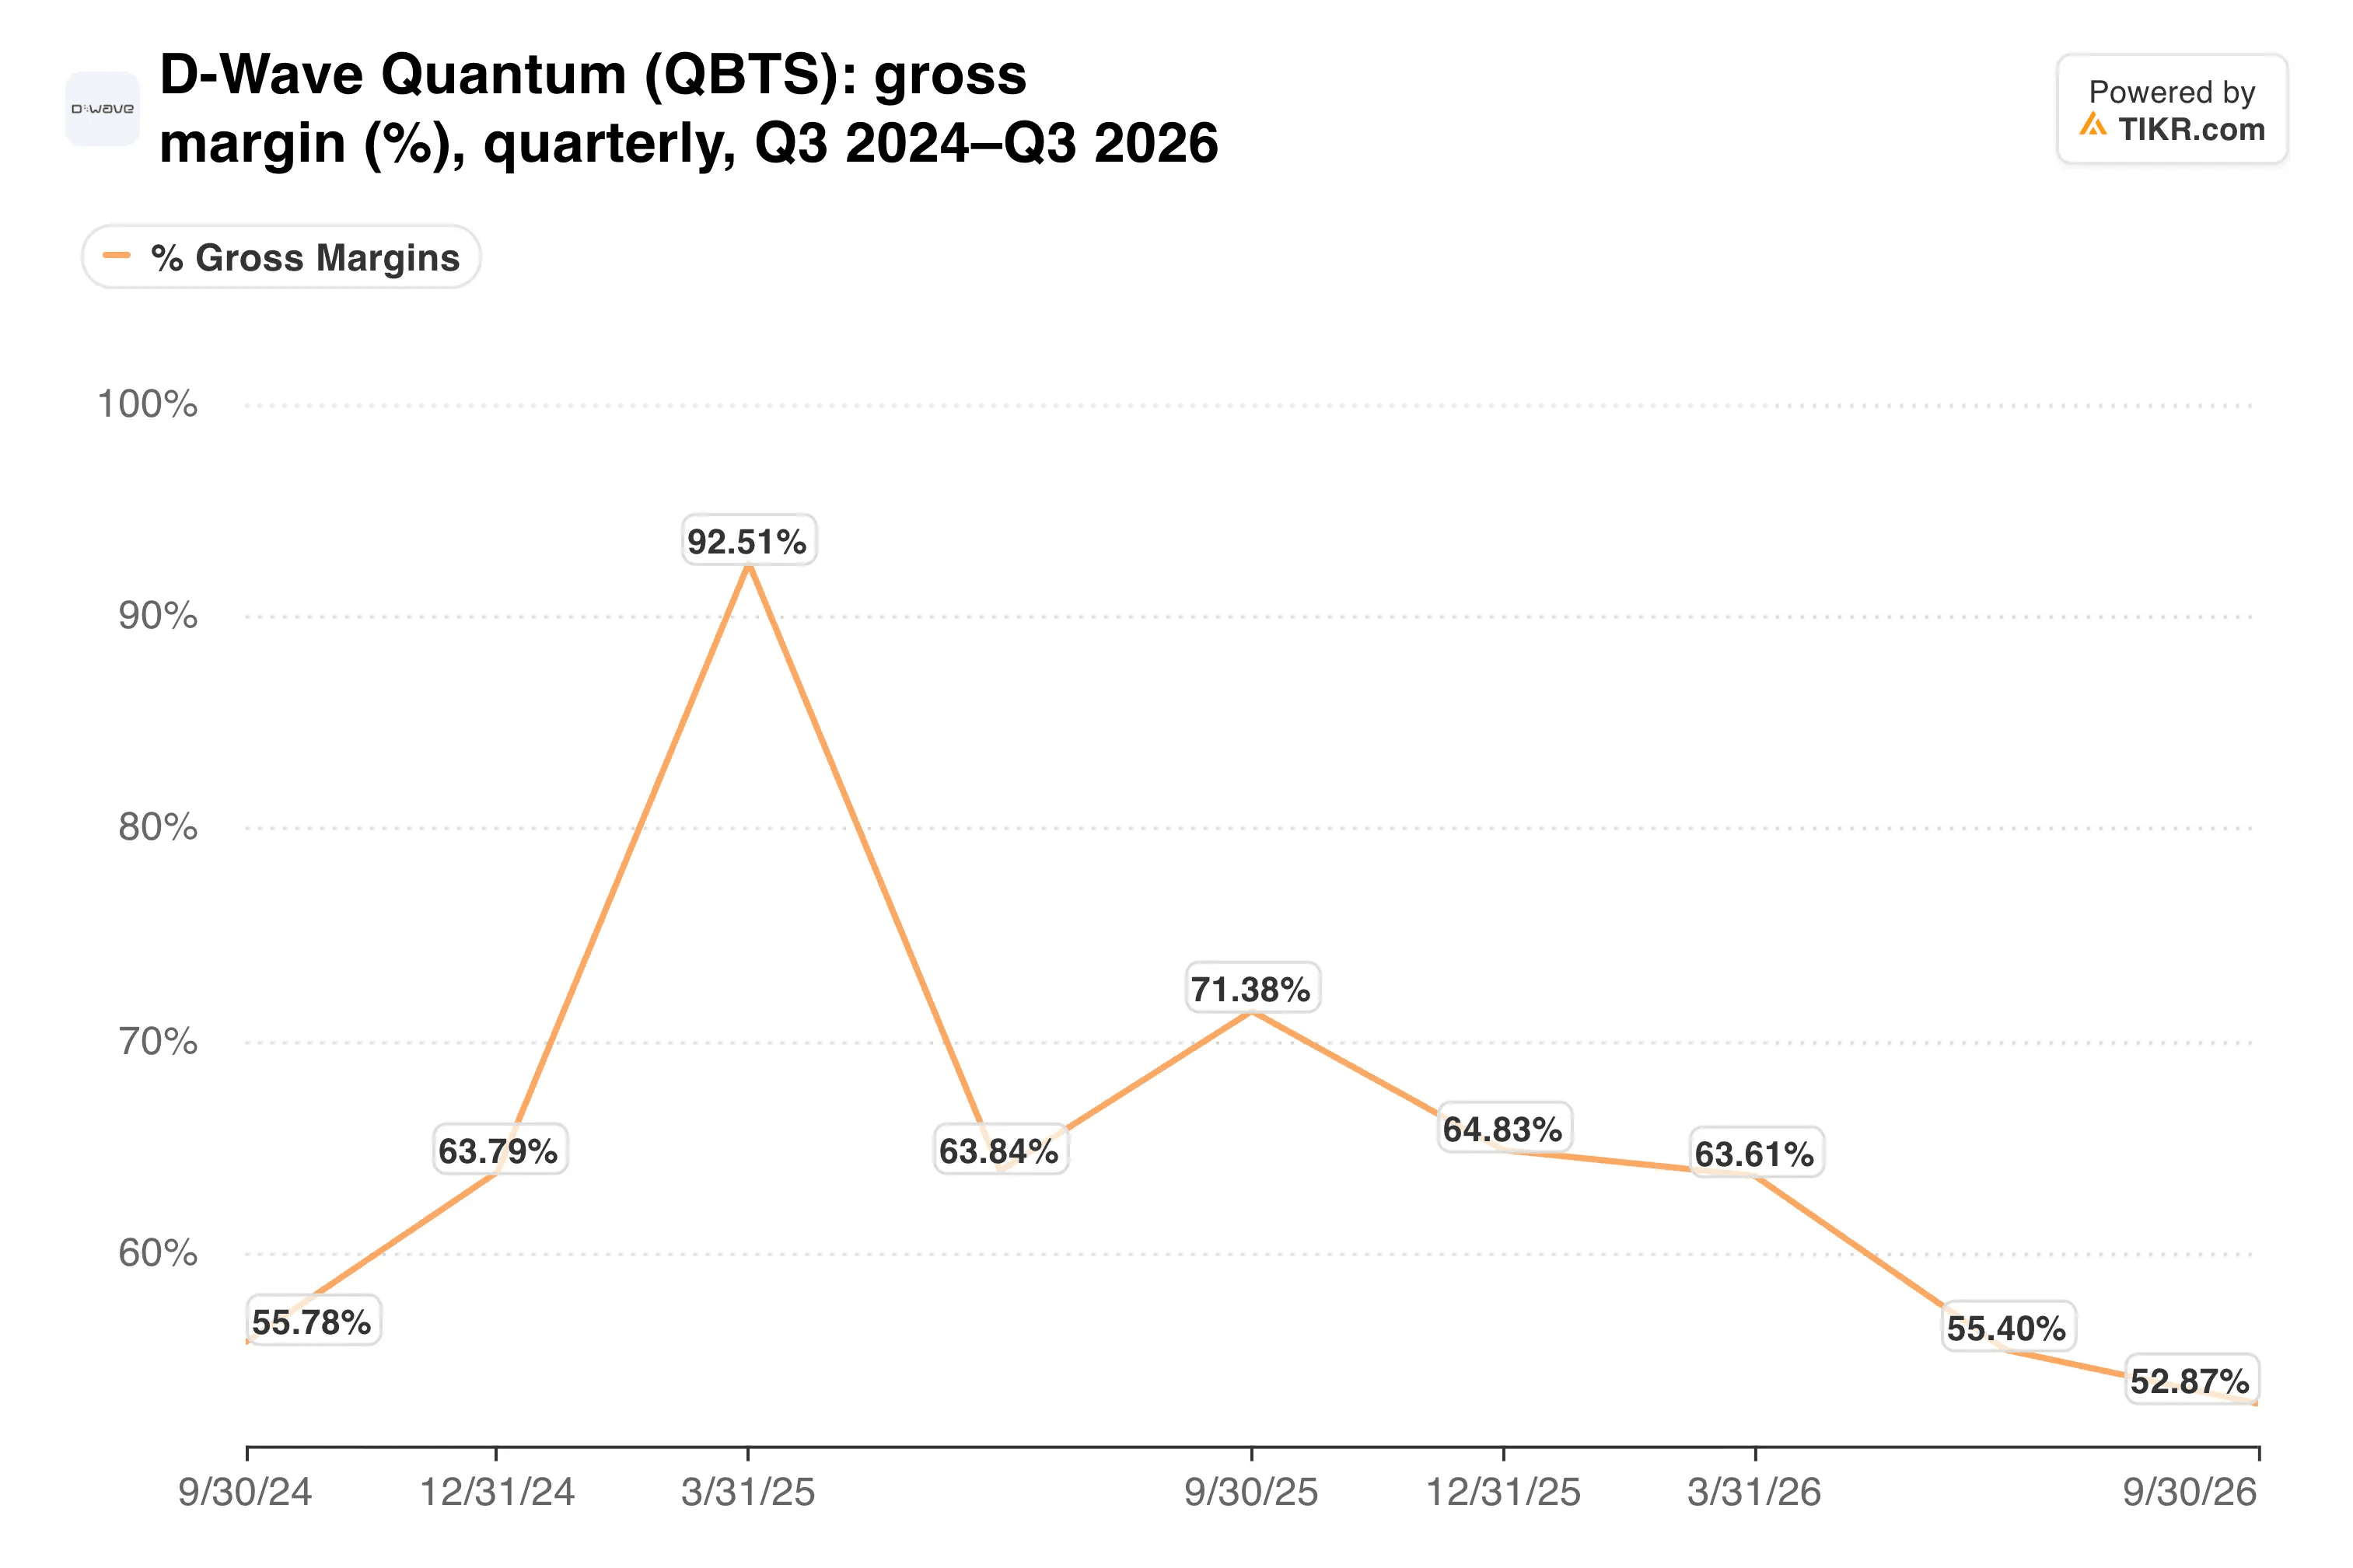
Professional services carry thinner margins, so a quarter heavy on system revenue could lift the figure. Still, one delivery does not make a trend.
Supply is the quieter wrinkle. D-Wave extended its multi-year manufacturing agreement with SkyWater this quarter, but IonQ now owns SkyWater. That foundry business added $83.5 million to IonQ’s third-quarter revenue.
In other words, D-Wave’s chip fabrication runs through a unit its biggest pure-play rival consolidates. Nothing points to friction yet, although it is a dependency worth watching.
The gate-model push continues as well. D-Wave opened a gate-model simulator beta with BBVA and the Jülich Supercomputing Centre among participants, building on its January purchase of Quantum Circuits.
Spending outruns the backlog
Costs are climbing far faster than sales. GAAP operating expenses rose 84% to $55.9 million, and the adjusted EBITDA loss widened 83% to $37.7 million.
Cash and marketable securities fell to $503.4 million from $546.2 million at the end of June. Here is what that burn looks like over two years.
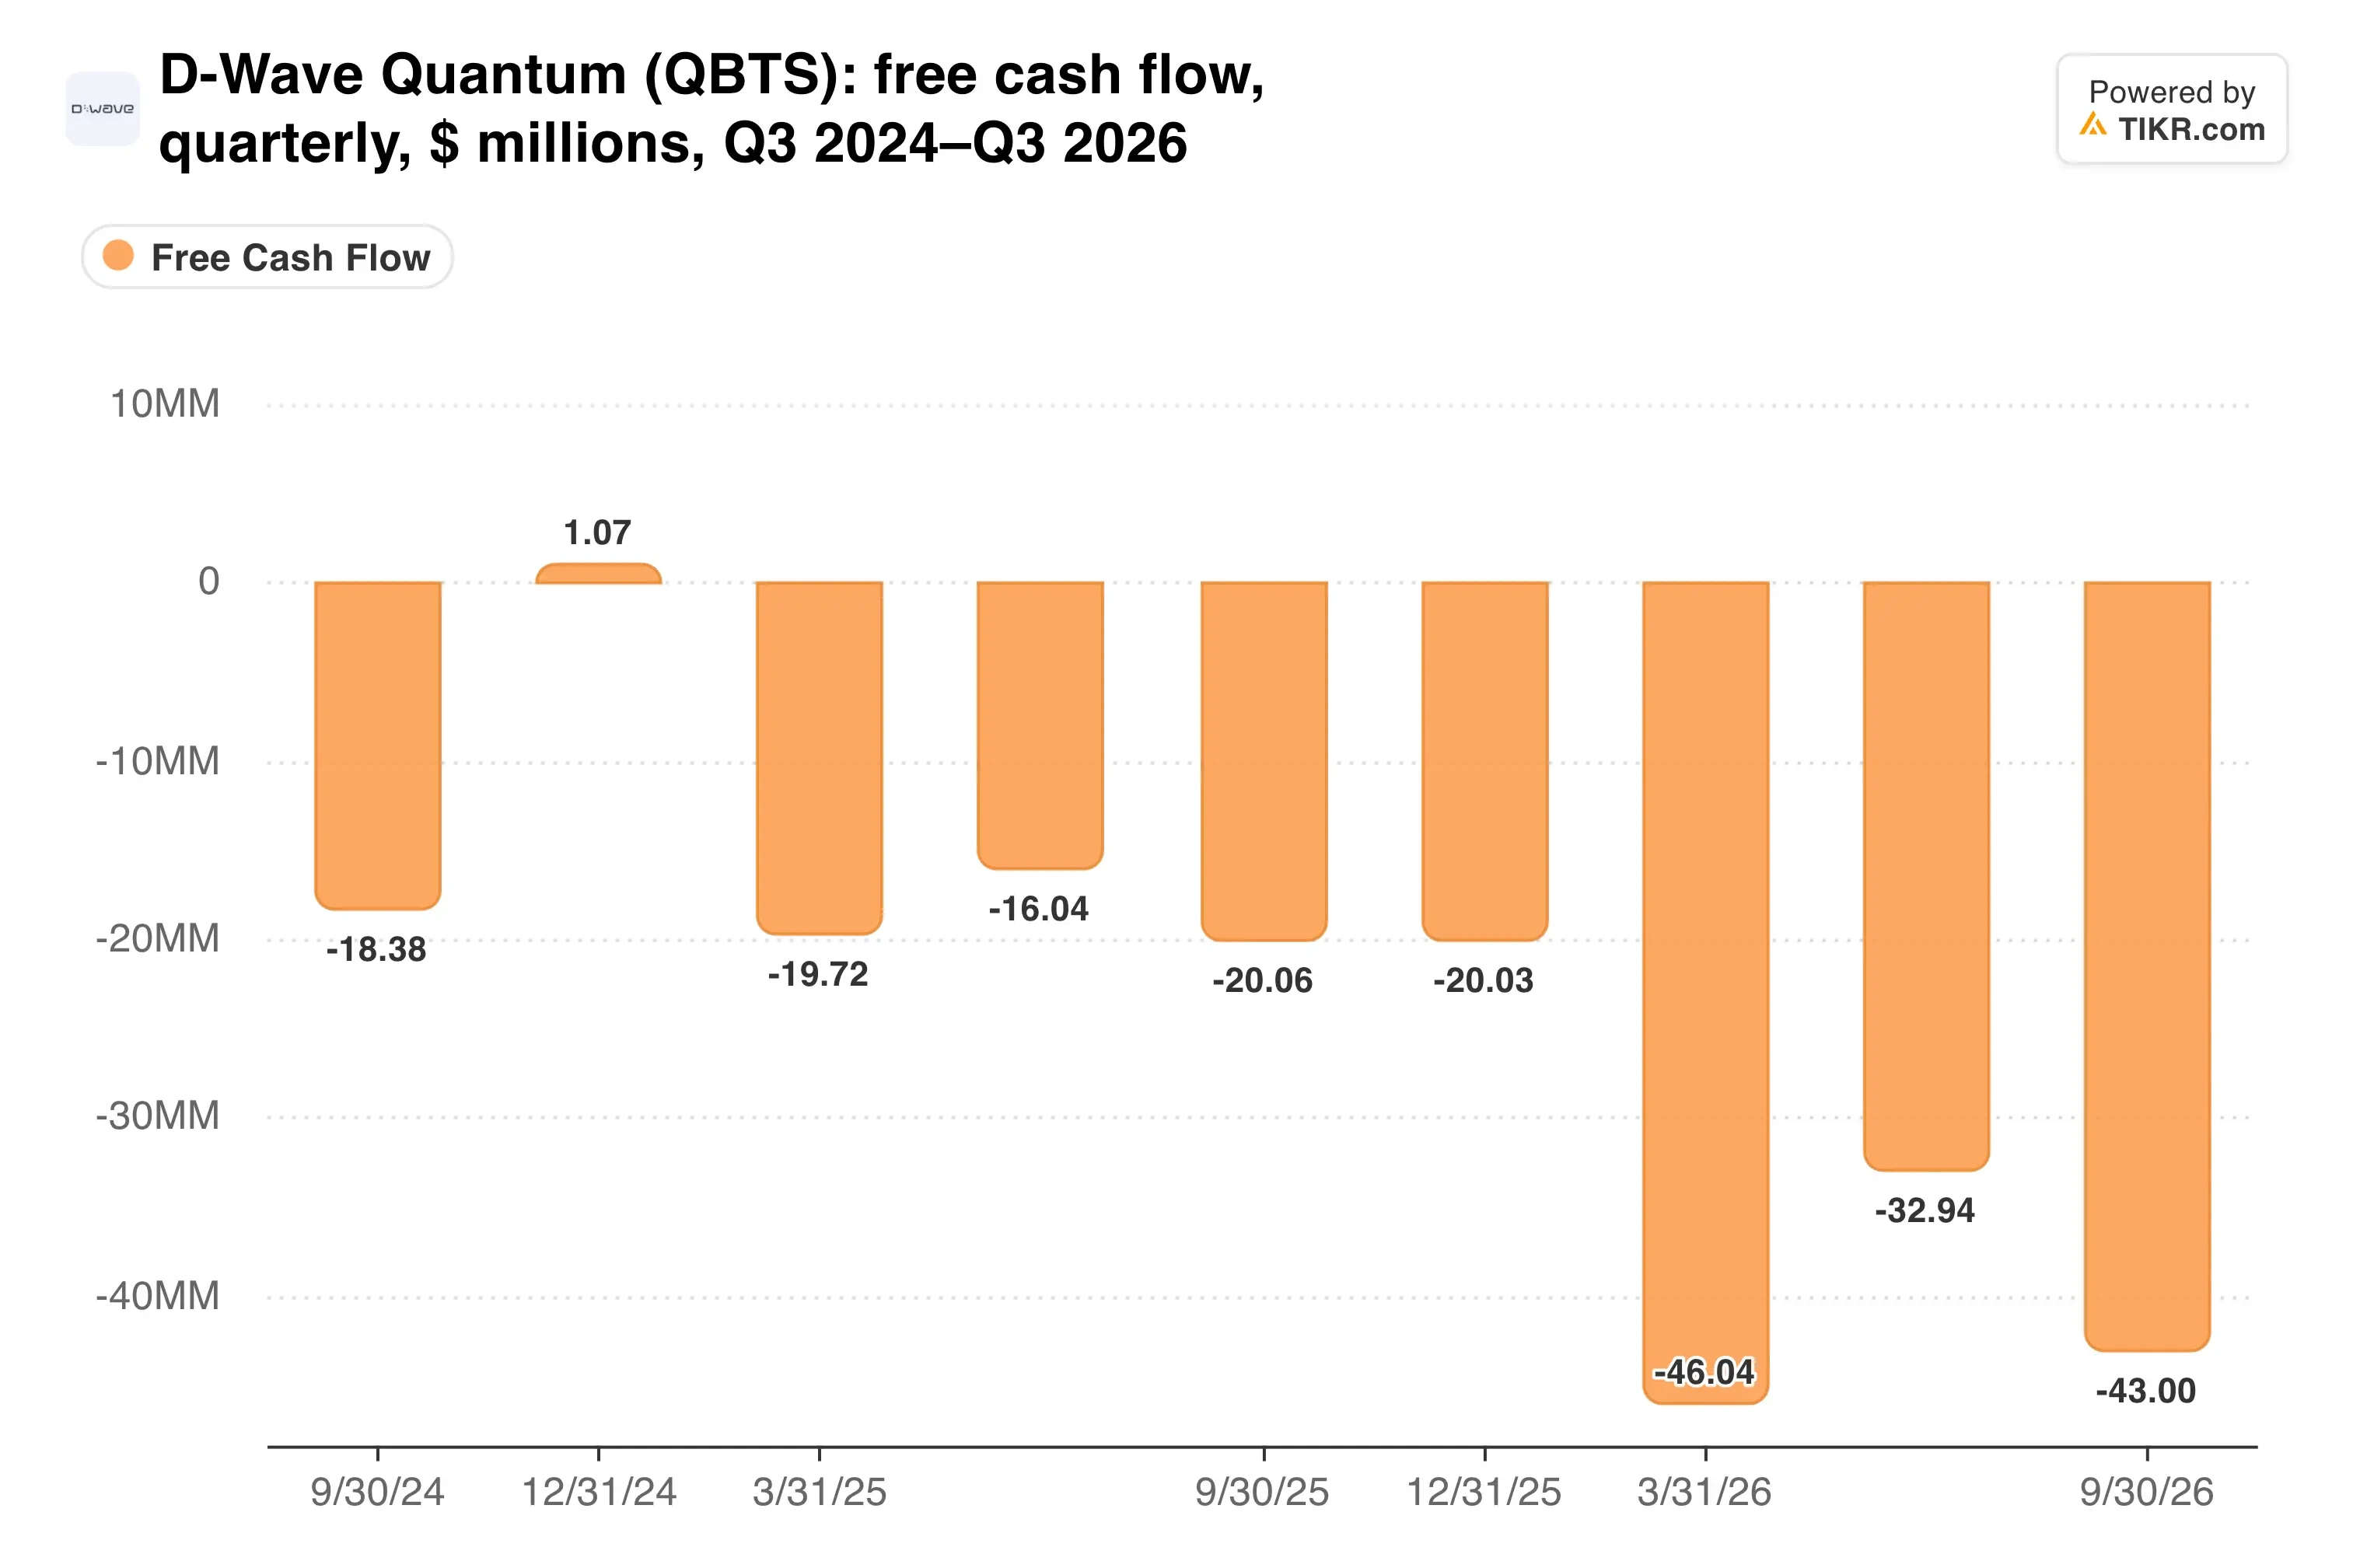
At the third-quarter pace, that cash covers roughly three years. The $100 million CHIPS Act agreement adds a cushion, but the money arrives only as D-Wave hits milestones.
Shares still trade at a steep premium to sales, so investors are paying today for revenue that hasn’t shown up.
My take: The bookings are real, and the balance sheet buys time. However, D-Wave keeps asking investors to judge it on orders while IonQ already reports revenue at scale. I’d want proof that $38.3 million of backlog converts at healthy margins before paying that premium.
The fourth-quarter report, expected in March, will show whether the Florida Atlantic system shipped and how much revenue came with it. With 59% of the backlog due within 12 months, D-Wave has little room for another slip.
So what is D-Wave Quantum stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what D-Wave Quantum could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!