Key Takeaways
- Snowflake shares sit more than 20% below their September 3 high, even as the company keeps shipping new AI agent tools.
- Product revenue rose 37% to $1.49 billion last quarter, and management lifted its full-year target to $6.07 billion.
- Stock-based compensation still ran at 29.5% of revenue, and Datadog’s flat fourth-quarter outlook shows how fast usage-based revenue can stall.
- Snowflake reports on December 2, with guidance calling for product revenue growth of 37% to 38%.
Snowflake (SNOW) has handed back much of its September rally. The stock now sits more than 20% below its September 3 high. That was the day shares jumped nearly 25% after a blowout quarter.
The business itself hasn’t cracked. Last week, Snowflake used its Expedition 2026 event to launch bots that let its CoCo and CoWork agents keep working after users log off. Still, the shares slid alongside the rest of AI software in last Thursday’s tech selloff.
Datadog (DDOG) explains some of the nerves. The monitoring company grew third-quarter revenue 35%, yet it guided fourth-quarter revenue flat after its largest customer cut usage. Both companies bill on consumption, so investors now wonder how sturdy Snowflake’s AI boost really is.
Snowflake gets to answer that on December 2.
Growth sped up again
Snowflake’s fiscal second quarter ended July 31, and it was the company’s strongest in years.
- Product revenue rose 37% to $1.49 billion, marking a third straight quarter of acceleration.
- Net revenue retention reached 126%, while remaining performance obligations grew 30% to $9.0 billion.
- Customers spending over $1 million a year rose 27% to 828.
Management also lifted its full-year product revenue target to $6.07 billion from $5.84 billion. That moves expected growth to 36% from 31%. Wells Fargo responded with a Street-high $525 price target.
CEO Sridhar Ramaswamy credited AI products with about half of the acceleration. So the core data platform sped up too, and that matters more than any single launch.
The quarterly climb has been steady…
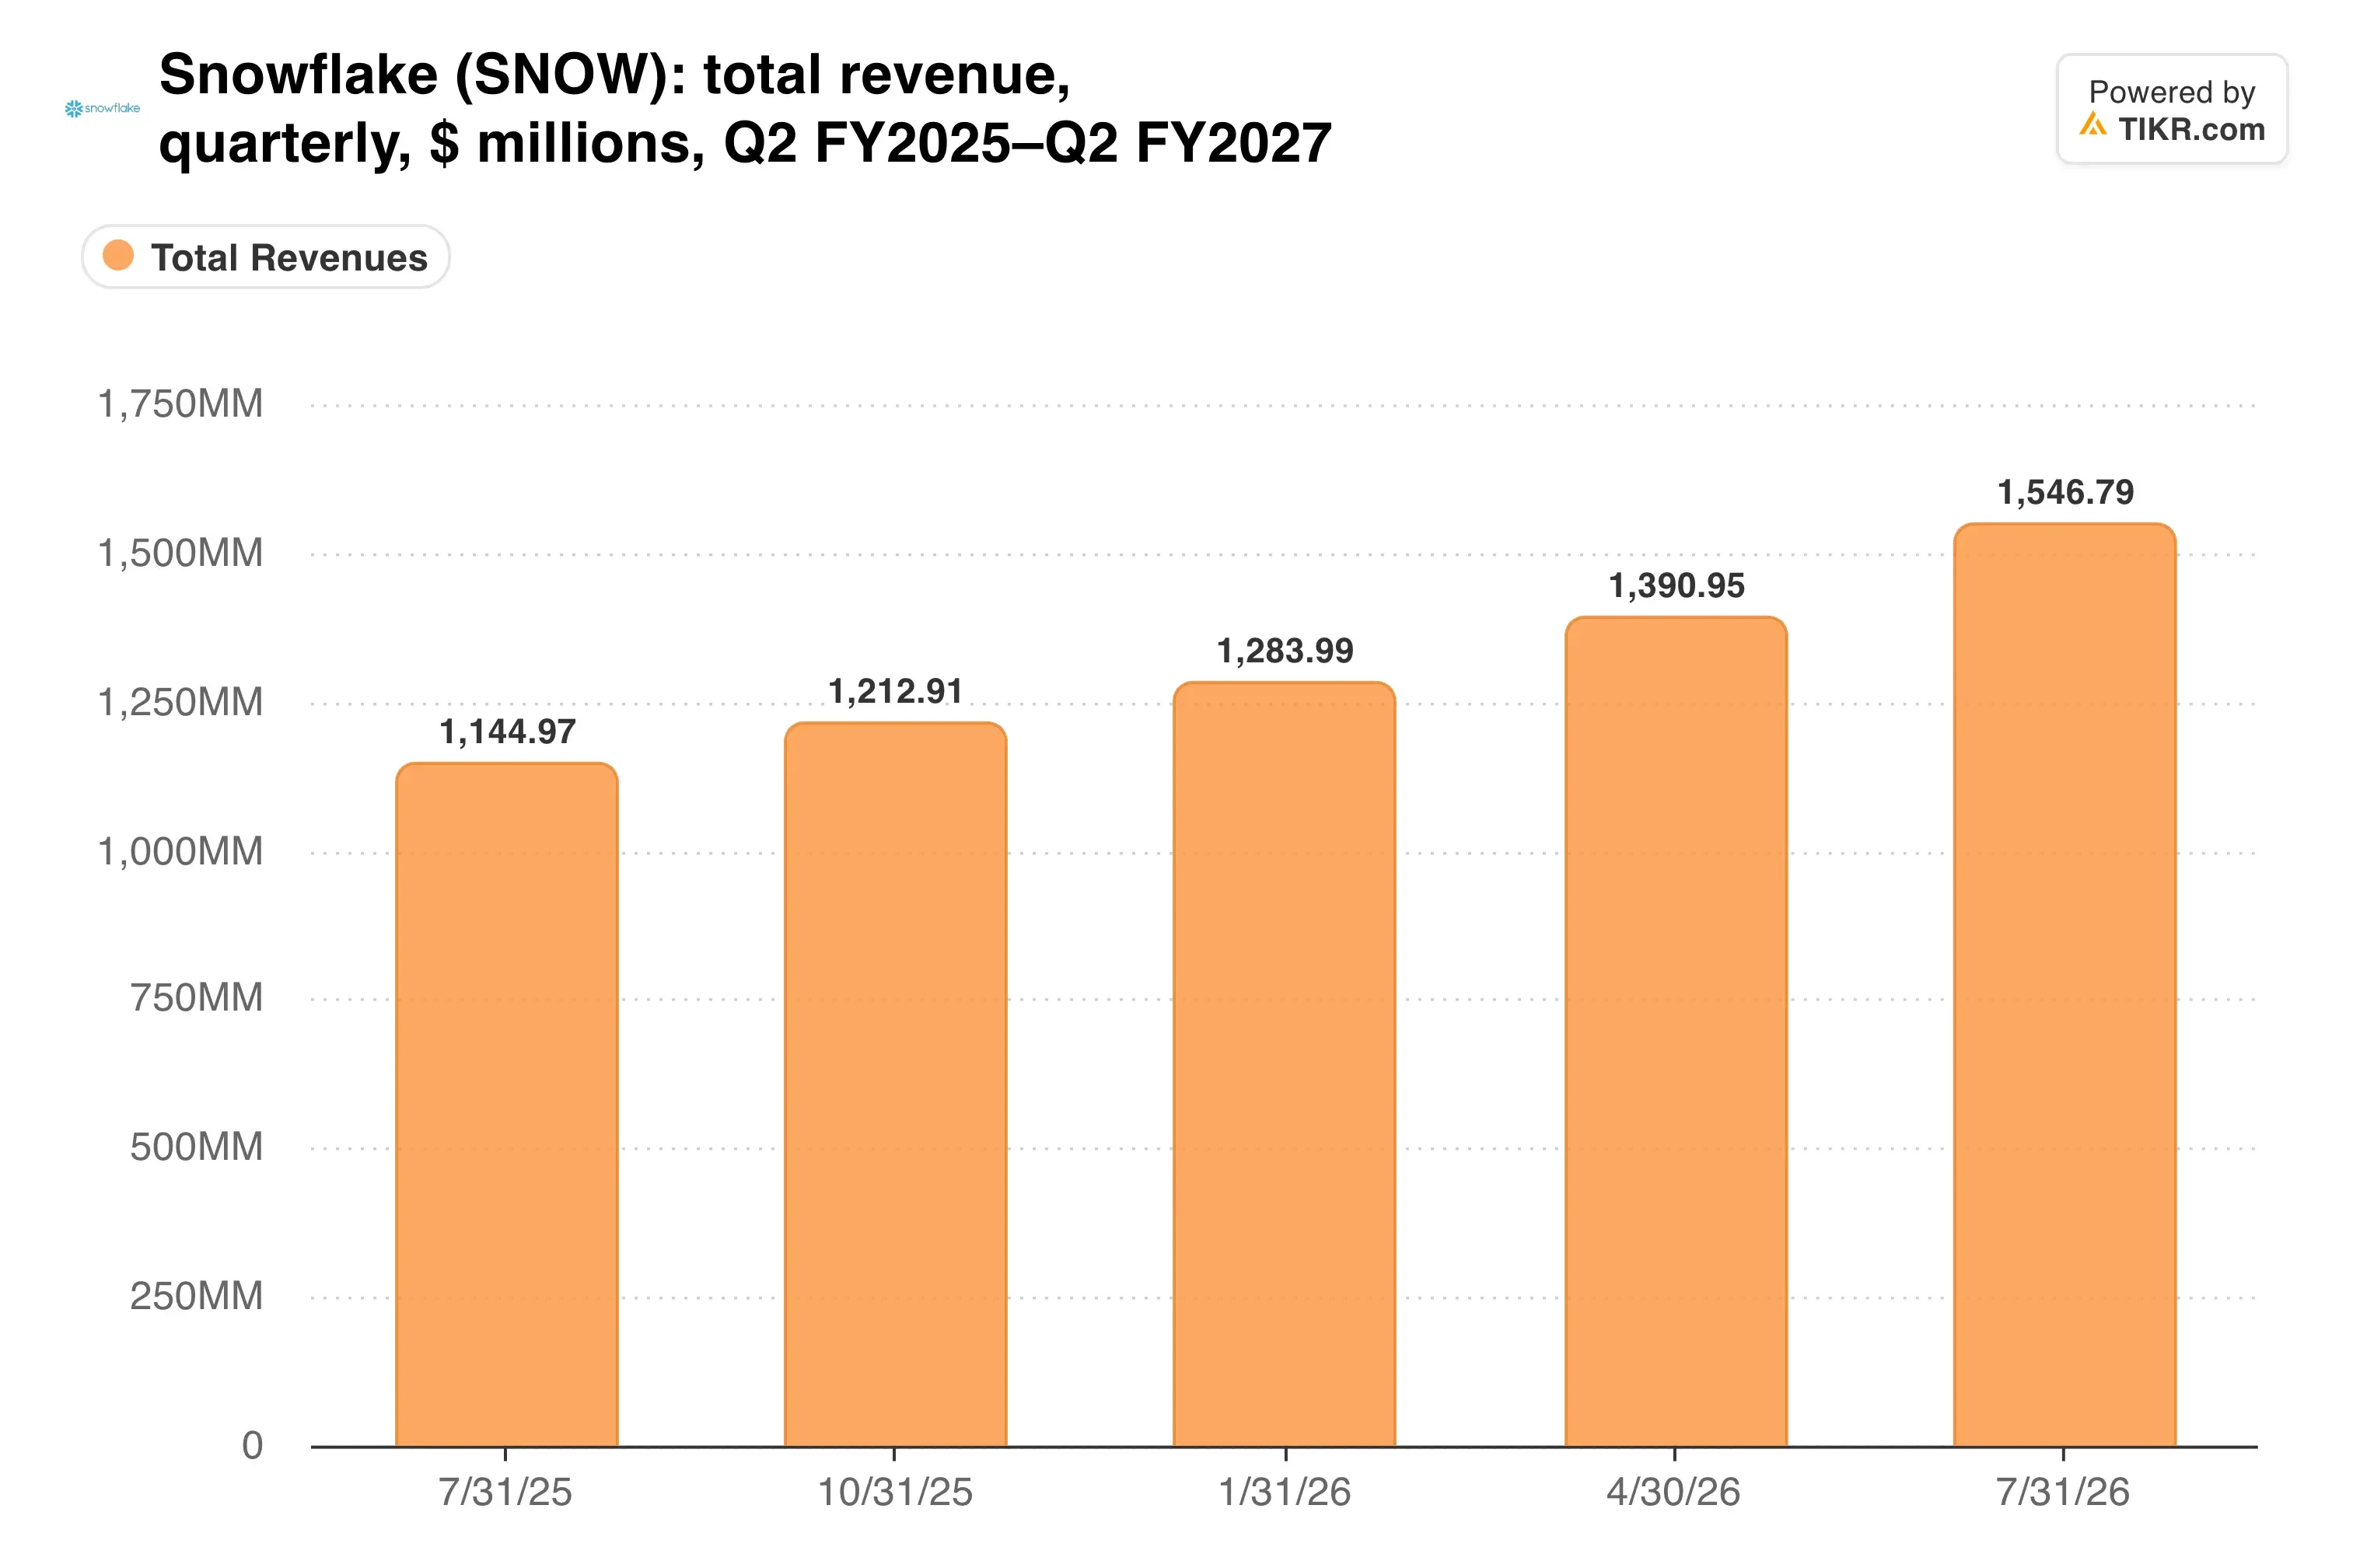
Total revenue hit $1.55 billion, up 35% from a year earlier.
Agents are built to burn compute
Expedition was about turning chat assistants into workers. The new CoCo and CoWork bots run scheduled tasks in the background, and both agents now plug into Slack and spreadsheets.
Adoption was already quick before the event. CoCo topped 9,100 accounts in the second quarter after adding more than 2,000, while CoWork reached 5,800. Every agent query runs on Snowflake compute, so wider use should show up as consumption.
“AI continues to compound our advantages, creating a flywheel effect across the business,” Ramaswamy said in the earnings release.
The catch is that AI work costs more to serve. What has that done to gross margin?
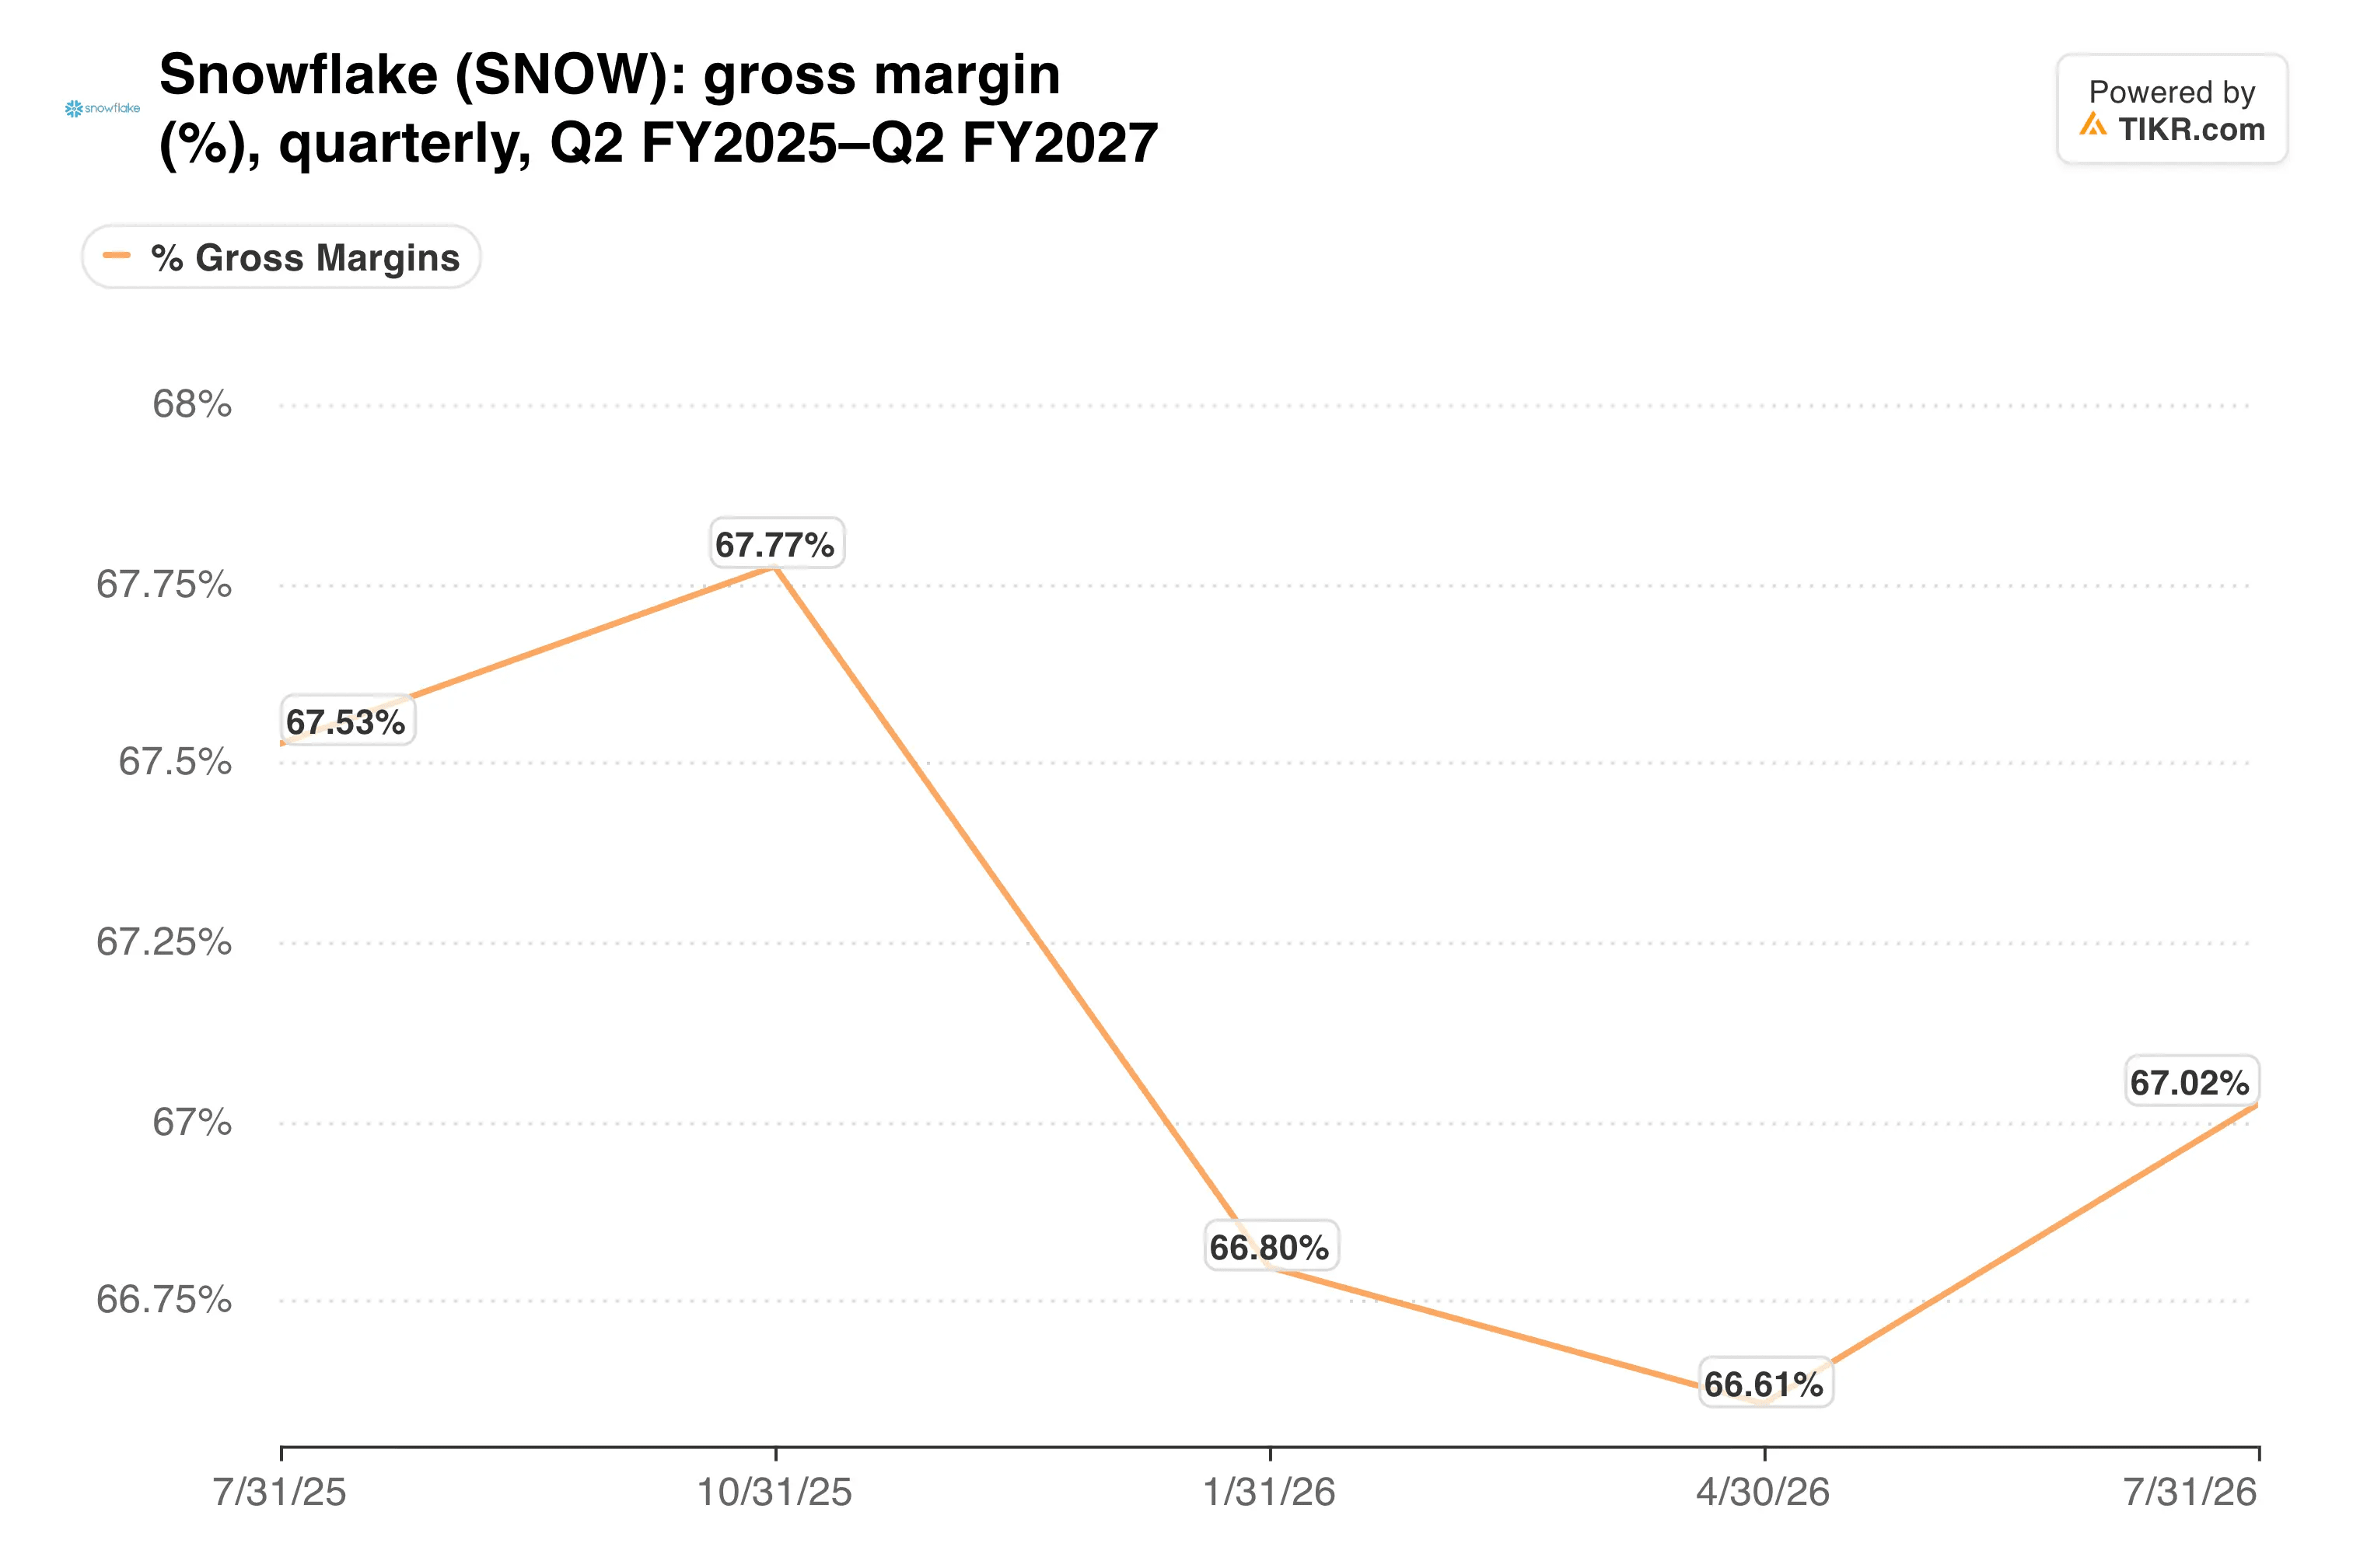
Gross margin edged down to 67.0% from 67.5% a year earlier. That’s a manageable dip, though it bears watching as agent usage scales.
TIKR tracks 53 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Stock comp still clouds profits
Profitability is moving the right way, but slowly. Non-GAAP operating margin rose to 15.3% from 11.1%. Yet Snowflake still posted a $263 million GAAP operating loss.
Stock-based compensation explains most of that gap. Related charges came to $456 million, or 29.5% of revenue, down from 38.1% a year earlier.
Valuation leaves little slack either…
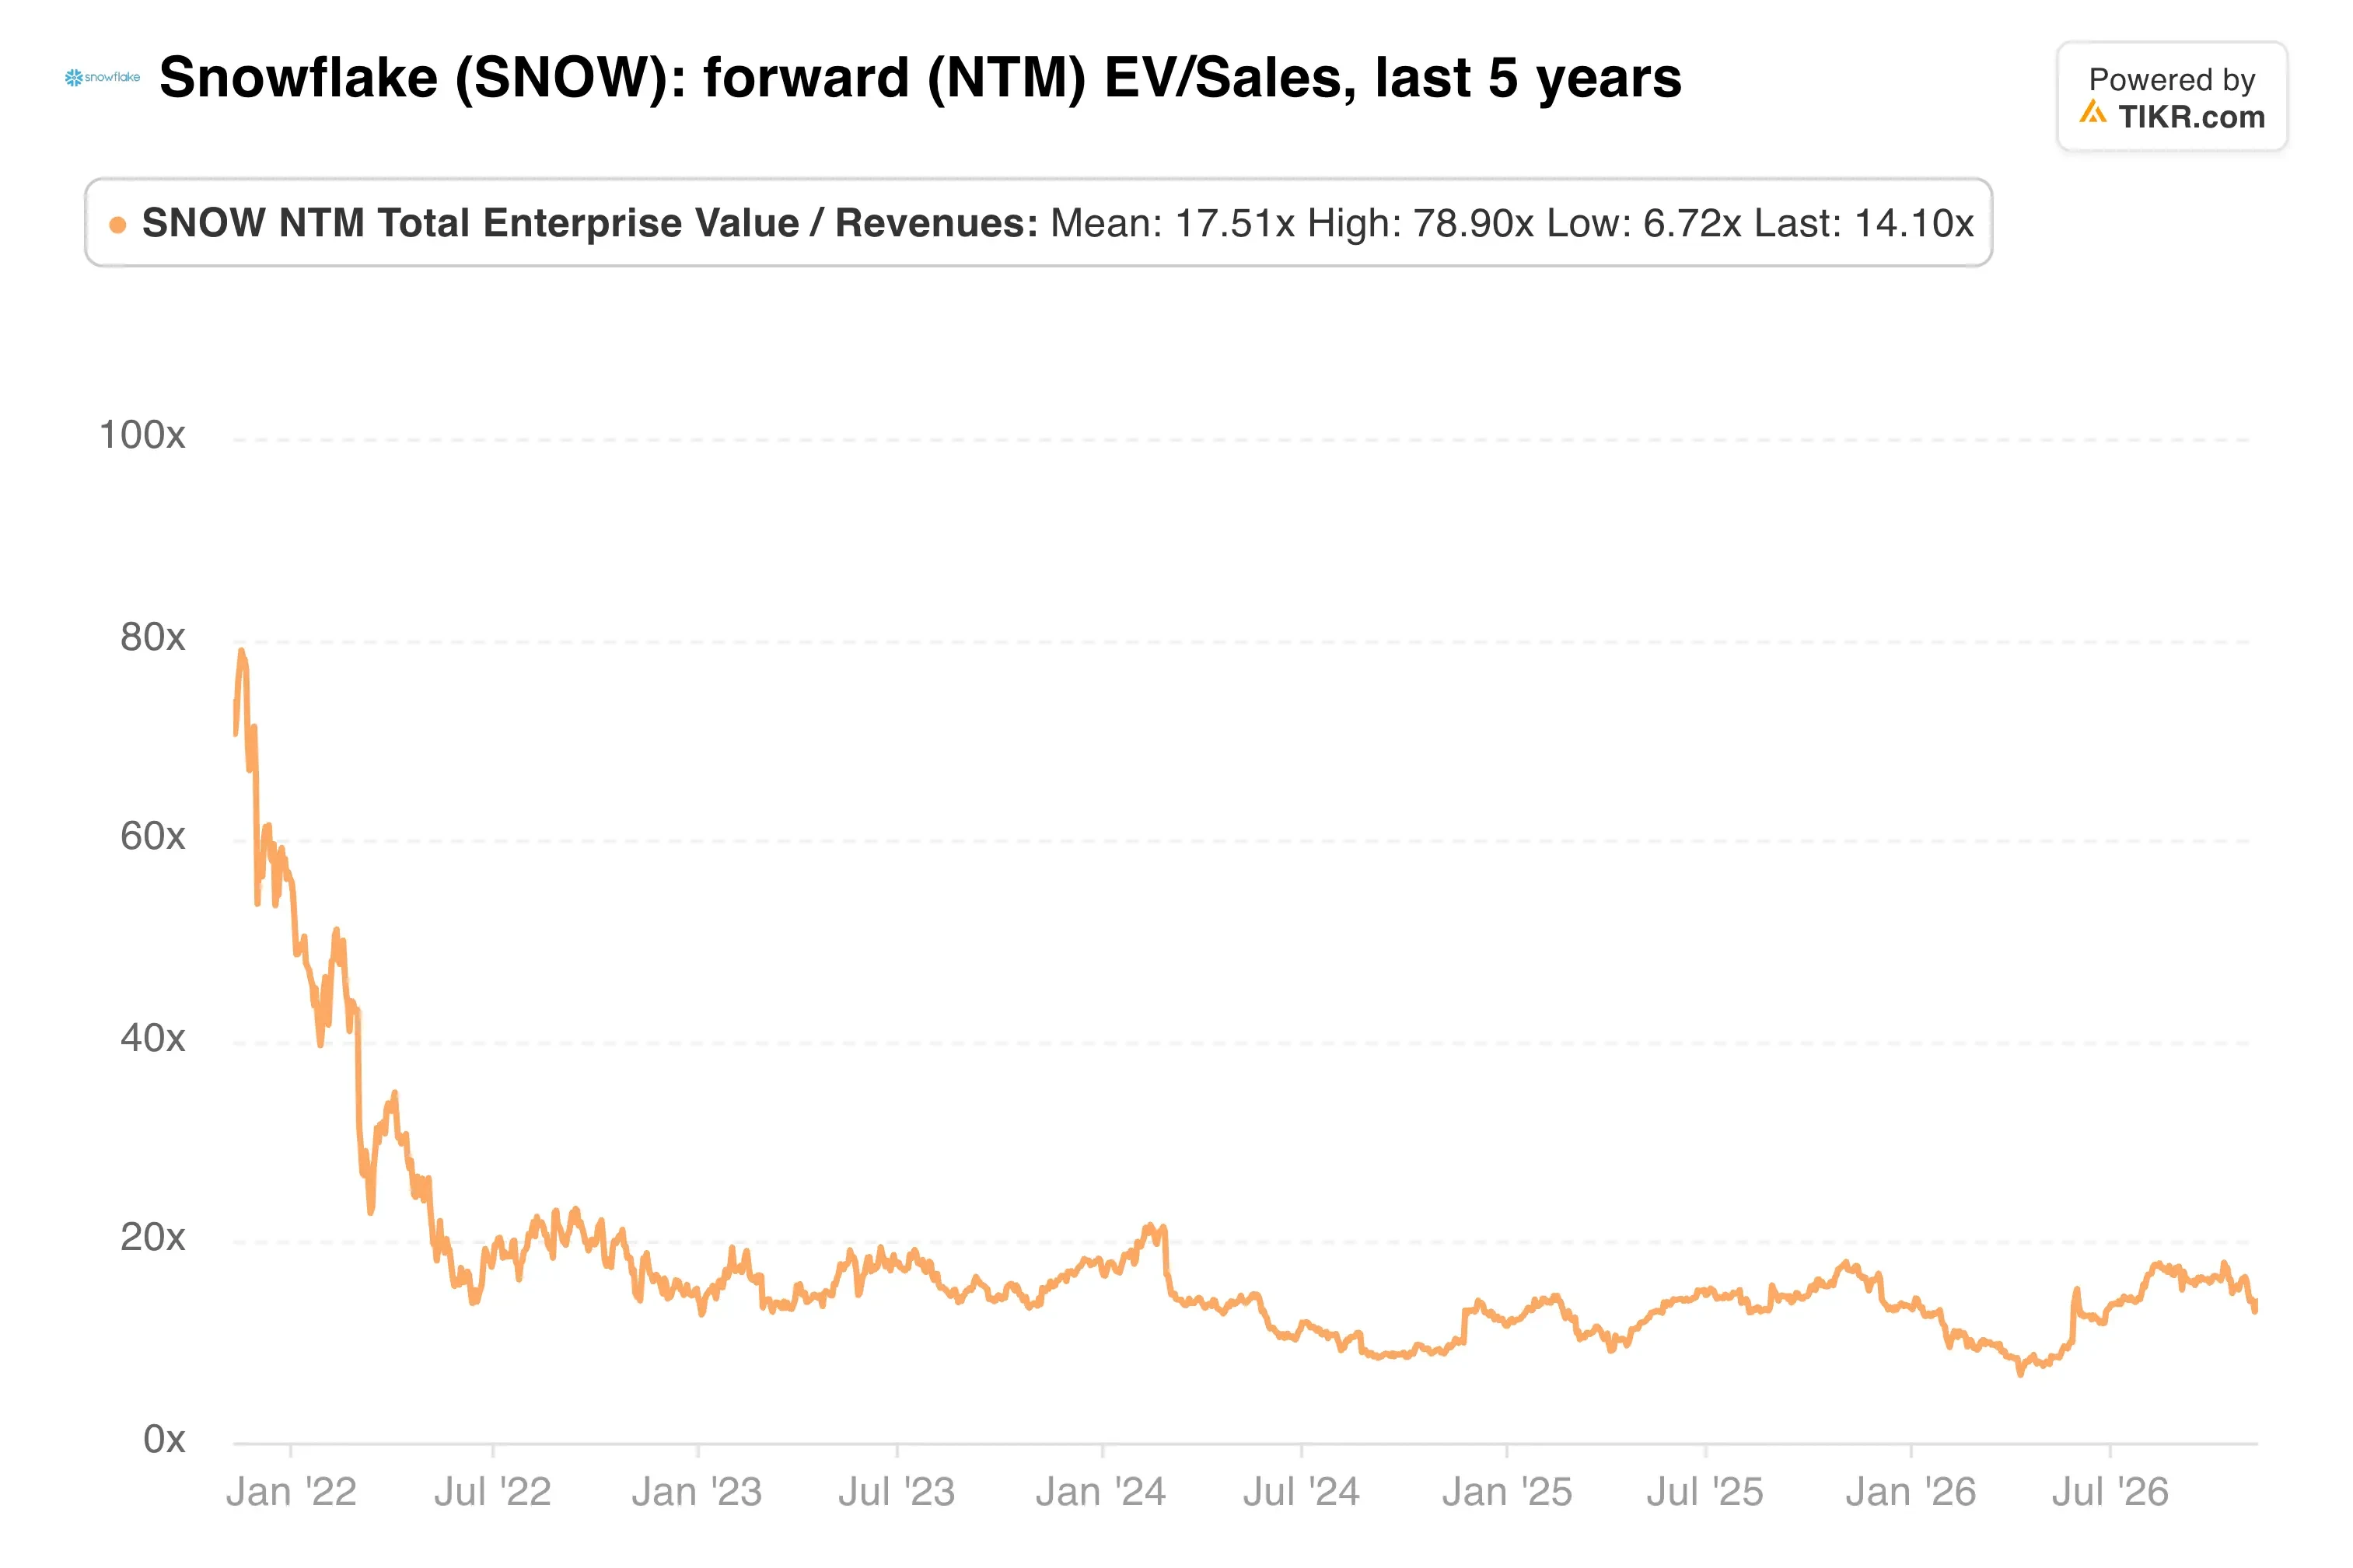
Snowflake trades well below its 2021 peak on forward sales. Still, Reuters noted in September that its multiple ran about twice the broader software group’s.
Datadog’s report shows the risk in that premium. Its third-quarter revenue reached $1.20 billion, and its fourth-quarter outlook of $1.19 billion to $1.20 billion implies no sequential growth. Snowflake, by contrast, guided third-quarter product revenue to $1.588 billion to $1.593 billion, up 37% to 38%.
My take: Snowflake looks like the sturdier consumption story today because its growth is spread across thousands of accounts. However, heavy stock comp and a GAAP loss leave little room for a stumble. I’d want proof that agents add usage without eroding gross margin before calling this pullback a bargain.
The December 2 report is the next checkpoint. It needs product revenue at the top of guidance and an operating margin near the 15.5% target to show the acceleration still has legs.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!