Key Takeaways
- Snowflake launched Business Ontology and a generally available Cortex AI Gateway on November 3 to govern AI agents ahead of its December 2 report.
- Product revenue grew 37% last quarter, and CEO Sridhar Ramaswamy said AI drove “approximately half of the acceleration.”
- Non-GAAP product gross margin slipped to 74.7% from 76.4% as Snowflake absorbs AI costs, and its premium valuation leaves little room to stumble.
- On December 2, product revenue needs to land inside the $1.588 billion to $1.593 billion guide, and the outlook needs to keep growth in the high 30s.
Snowflake (SNOW) reports its fiscal third quarter on December 2, and the bar sits high. Product revenue grew 37% last quarter, and management guided the current quarter to 37% to 38%.
That September report sent the stock up nearly 25% in a day. Shares traded at $377 that session, their highest level since December 2021.
This month, Snowflake used its Expedition 2026 event to show where the next leg of growth could come from. Its answer is governed AI agents that customers will pay to run.
The timing matters because consumption peers are wobbling. Datadog (DDOG) grew revenue 35% last quarter, yet it guided its fourth quarter roughly flat with the third.
Agents get a control panel
On November 3, Snowflake added three pieces to its Horizon Catalog:
- Business Ontology stores approved definitions of business terms and serves only those to agents.
- Cortex AI Gateway, now generally available, applies one set of access policies to every agent and model call.
- Cost governance assigns AI spending to users or teams and enforces hard budget limits.
Glean and Kargo already run the gateway, while dentsu is an early Business Ontology adopter.
“The enterprises that win won’t be the ones with the most agents,” EVP of Product Christian Kleinerman said in the launch release. His pitch is control, and that is what large buyers ask for before they scale.
Snowflake needs that pitch to land, because growth has been climbing for three straight quarters…
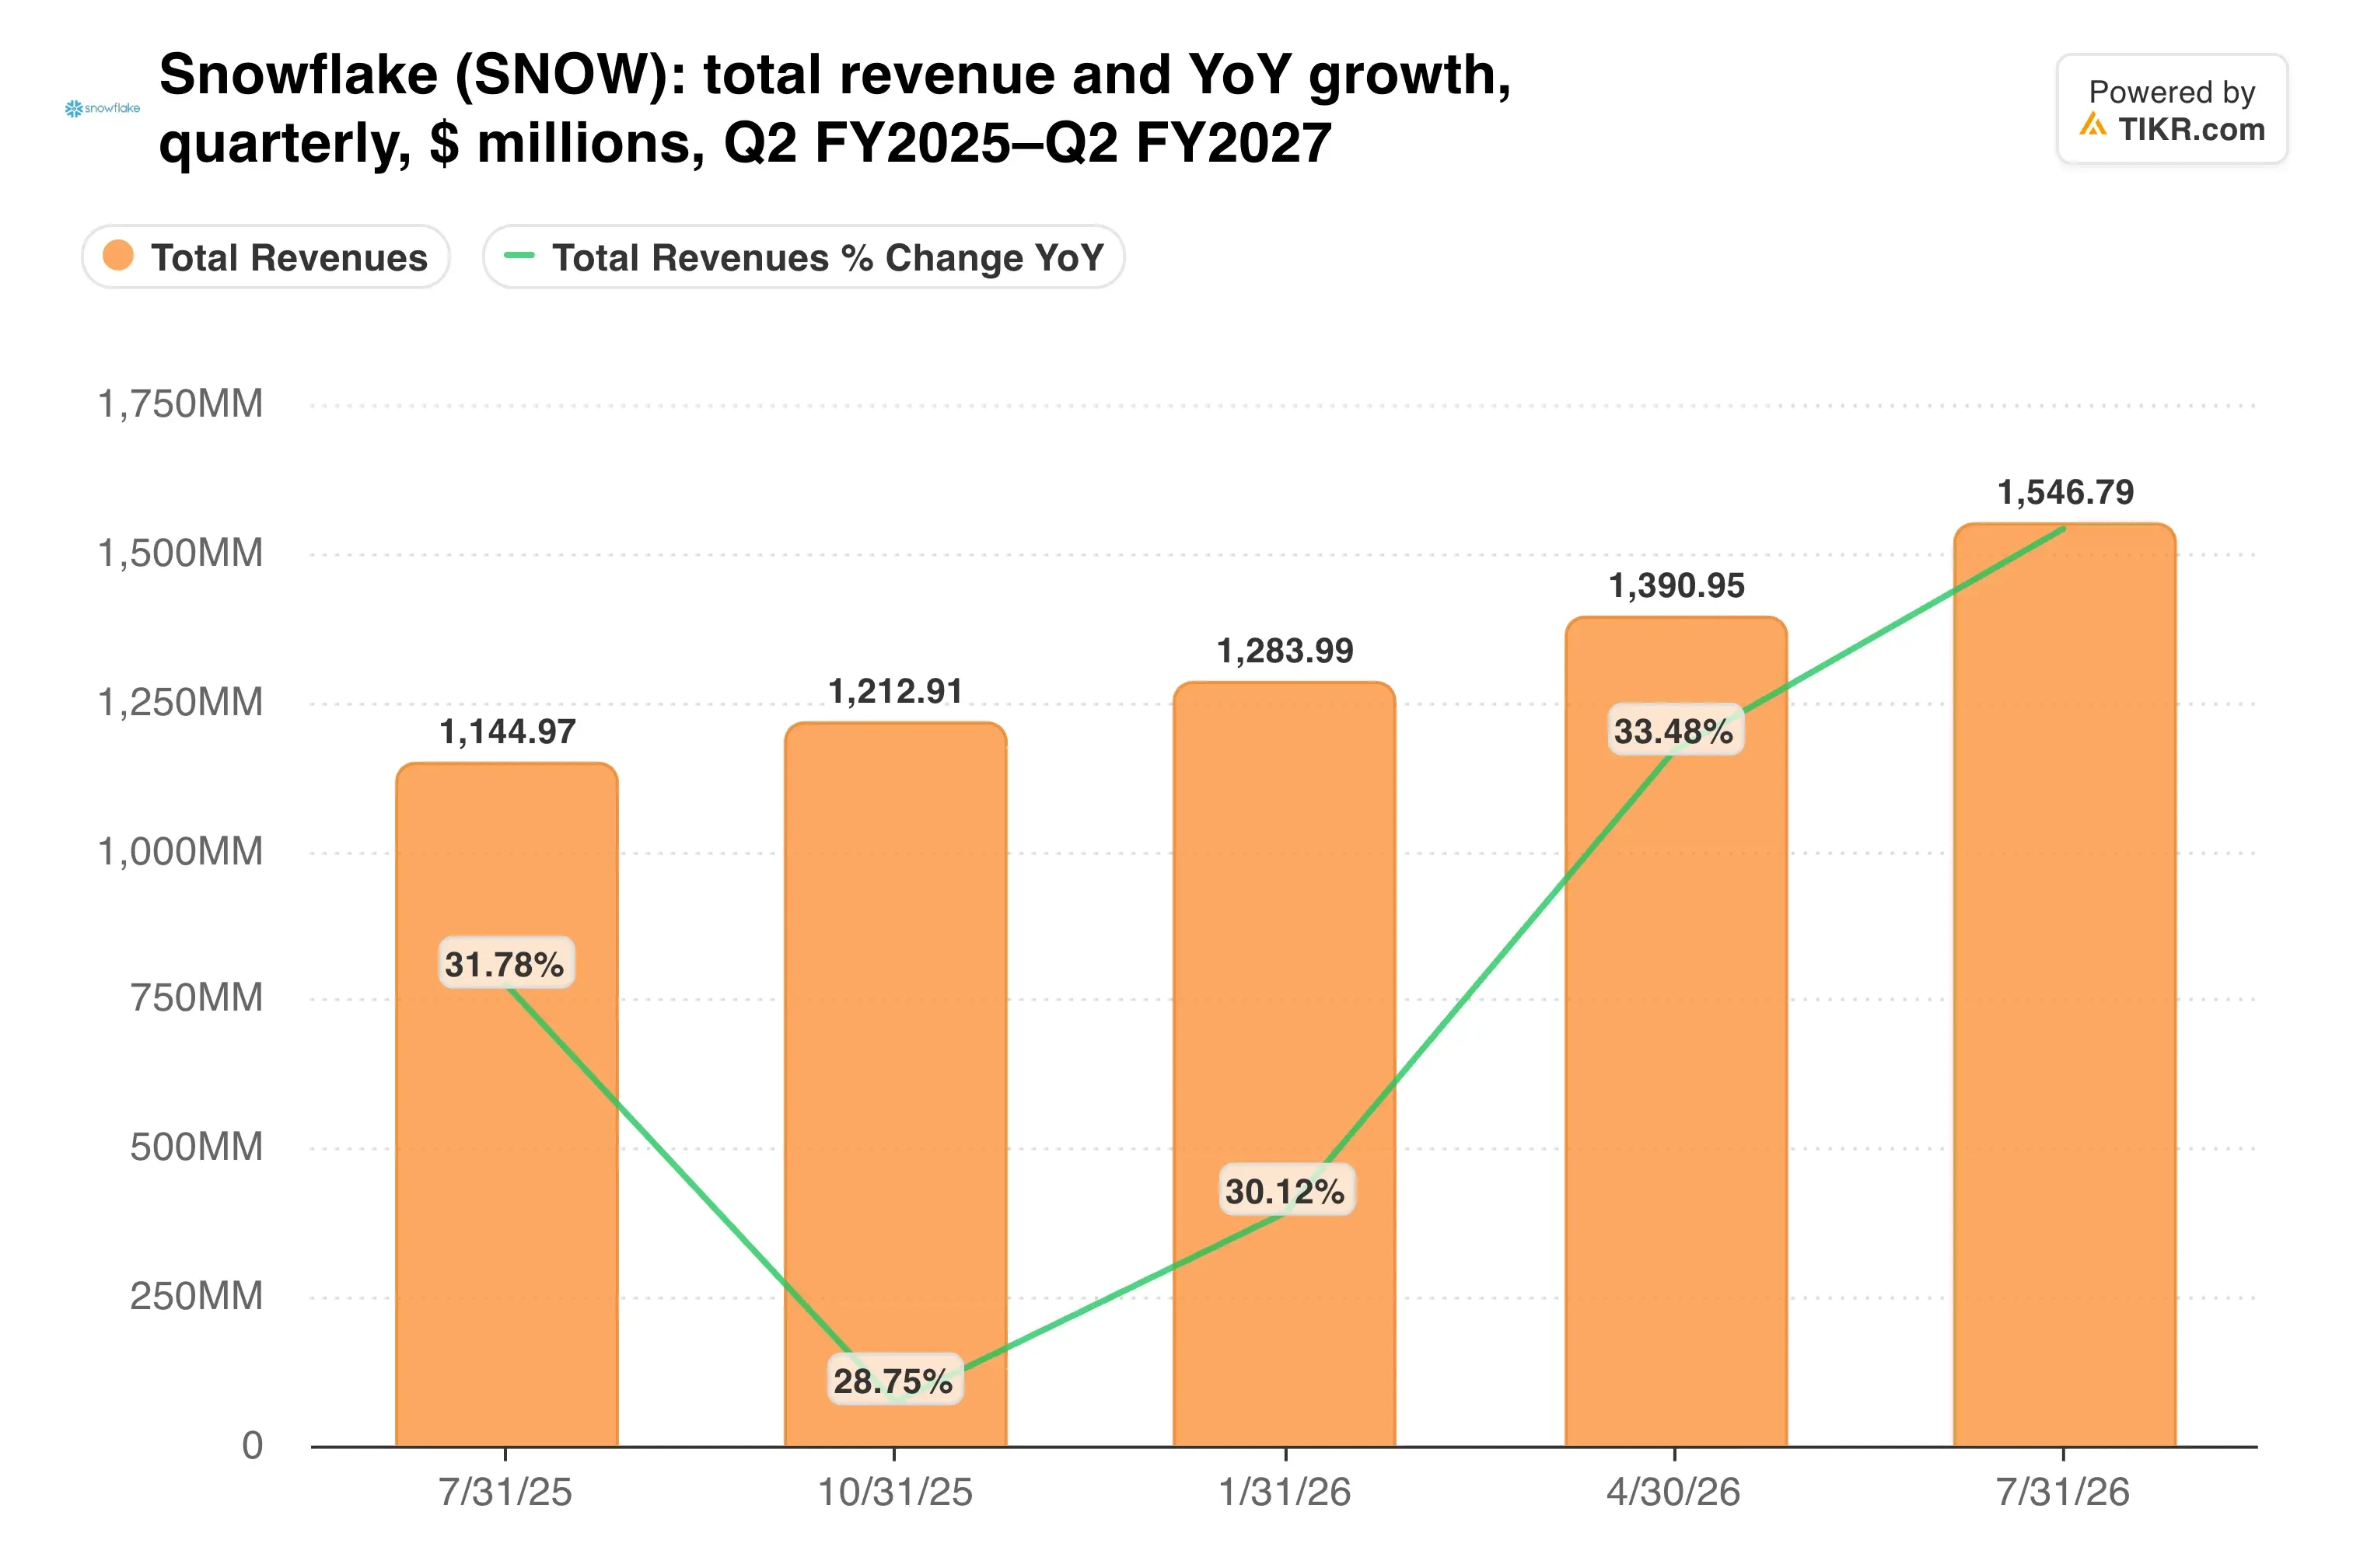
Total revenue reached $1.55 billion in the July quarter, up 35% from a year earlier.
AI is lifting the core platform
CEO Sridhar Ramaswamy told investors that AI drove “approximately half of the acceleration” in growth. The core data platform supplied the rest.
Other metrics back that up. Remaining performance obligations rose 30% to $9 billion, and net revenue retention held at 126%. CoCo, the coding agent, topped 9,100 accounts after adding more than 2,000 in the quarter. CoWork reached 5,800.
So management raised full-year product revenue guidance to $6.07 billion from $5.84 billion, which implies 36% growth.
How does that stack up against the other big consumption name in software?
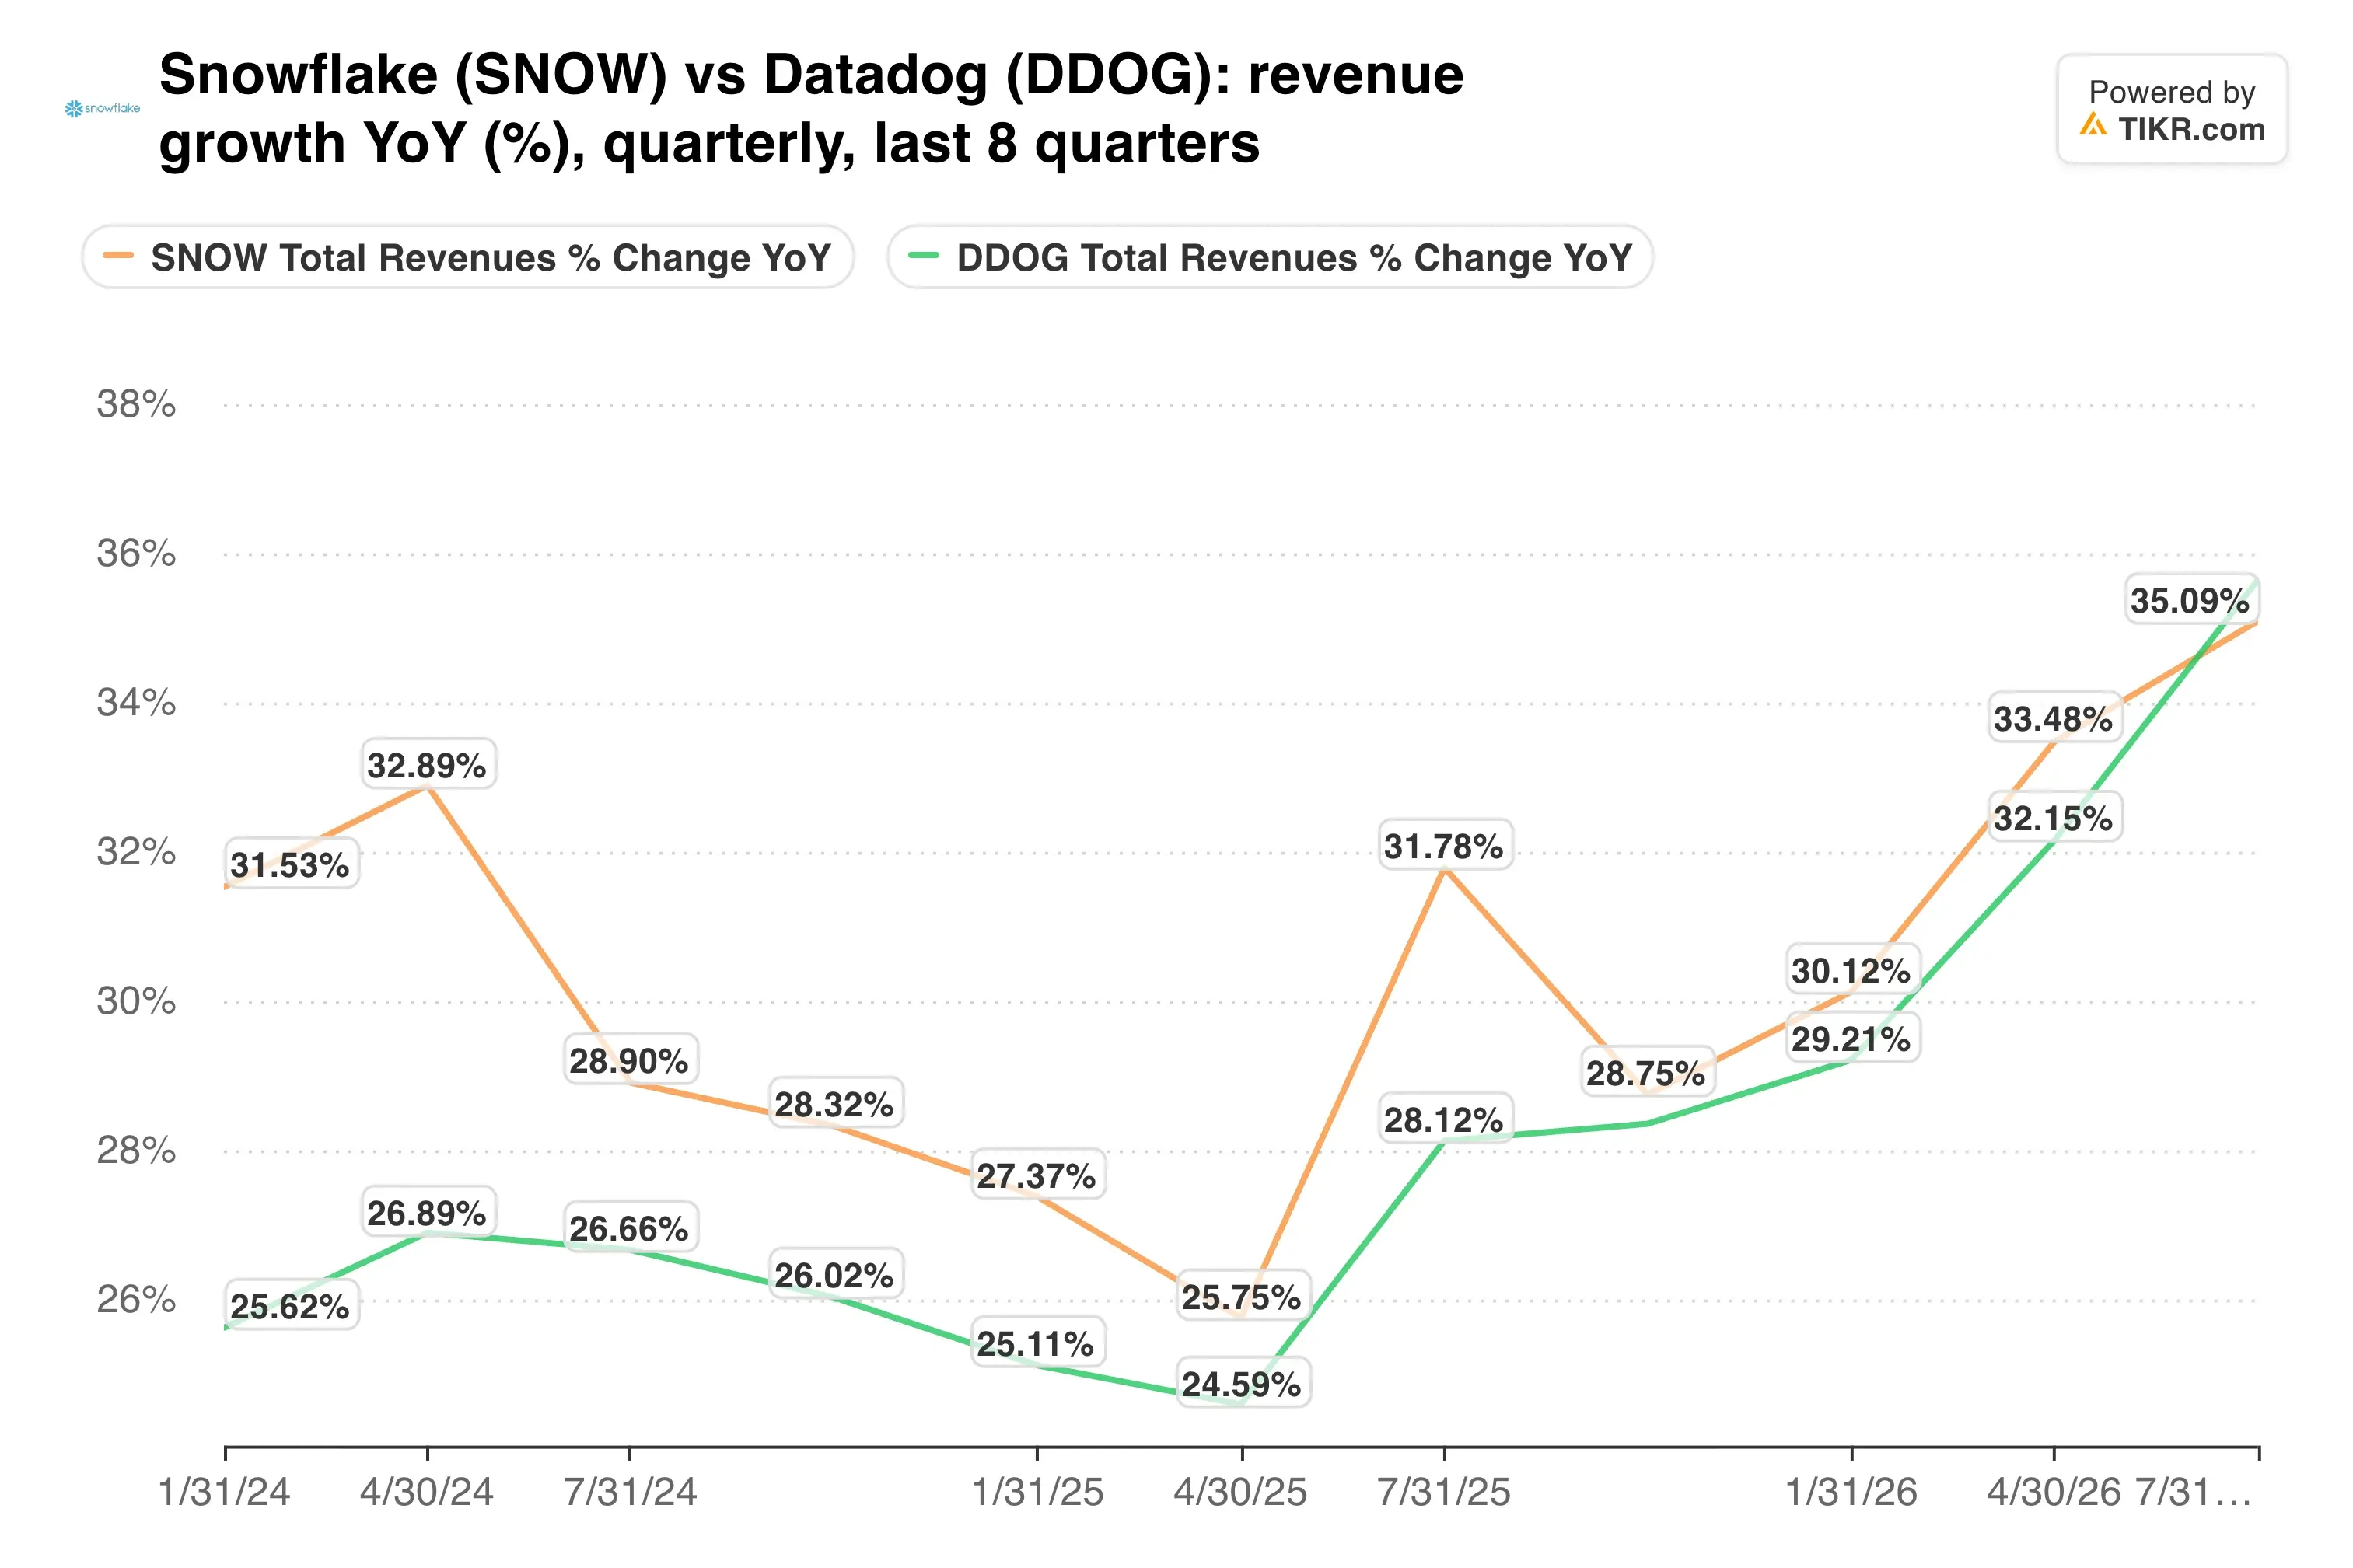
Both companies grew 35% last quarter. However, Datadog’s fourth quarter guide of $1.19 billion to $1.20 billion implies no sequential growth. Snowflake’s third quarter product revenue guide implies about 6.6%.
TIKR tracks 53 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Margins fund the AI push
The cost of that growth shows up first in gross margin.
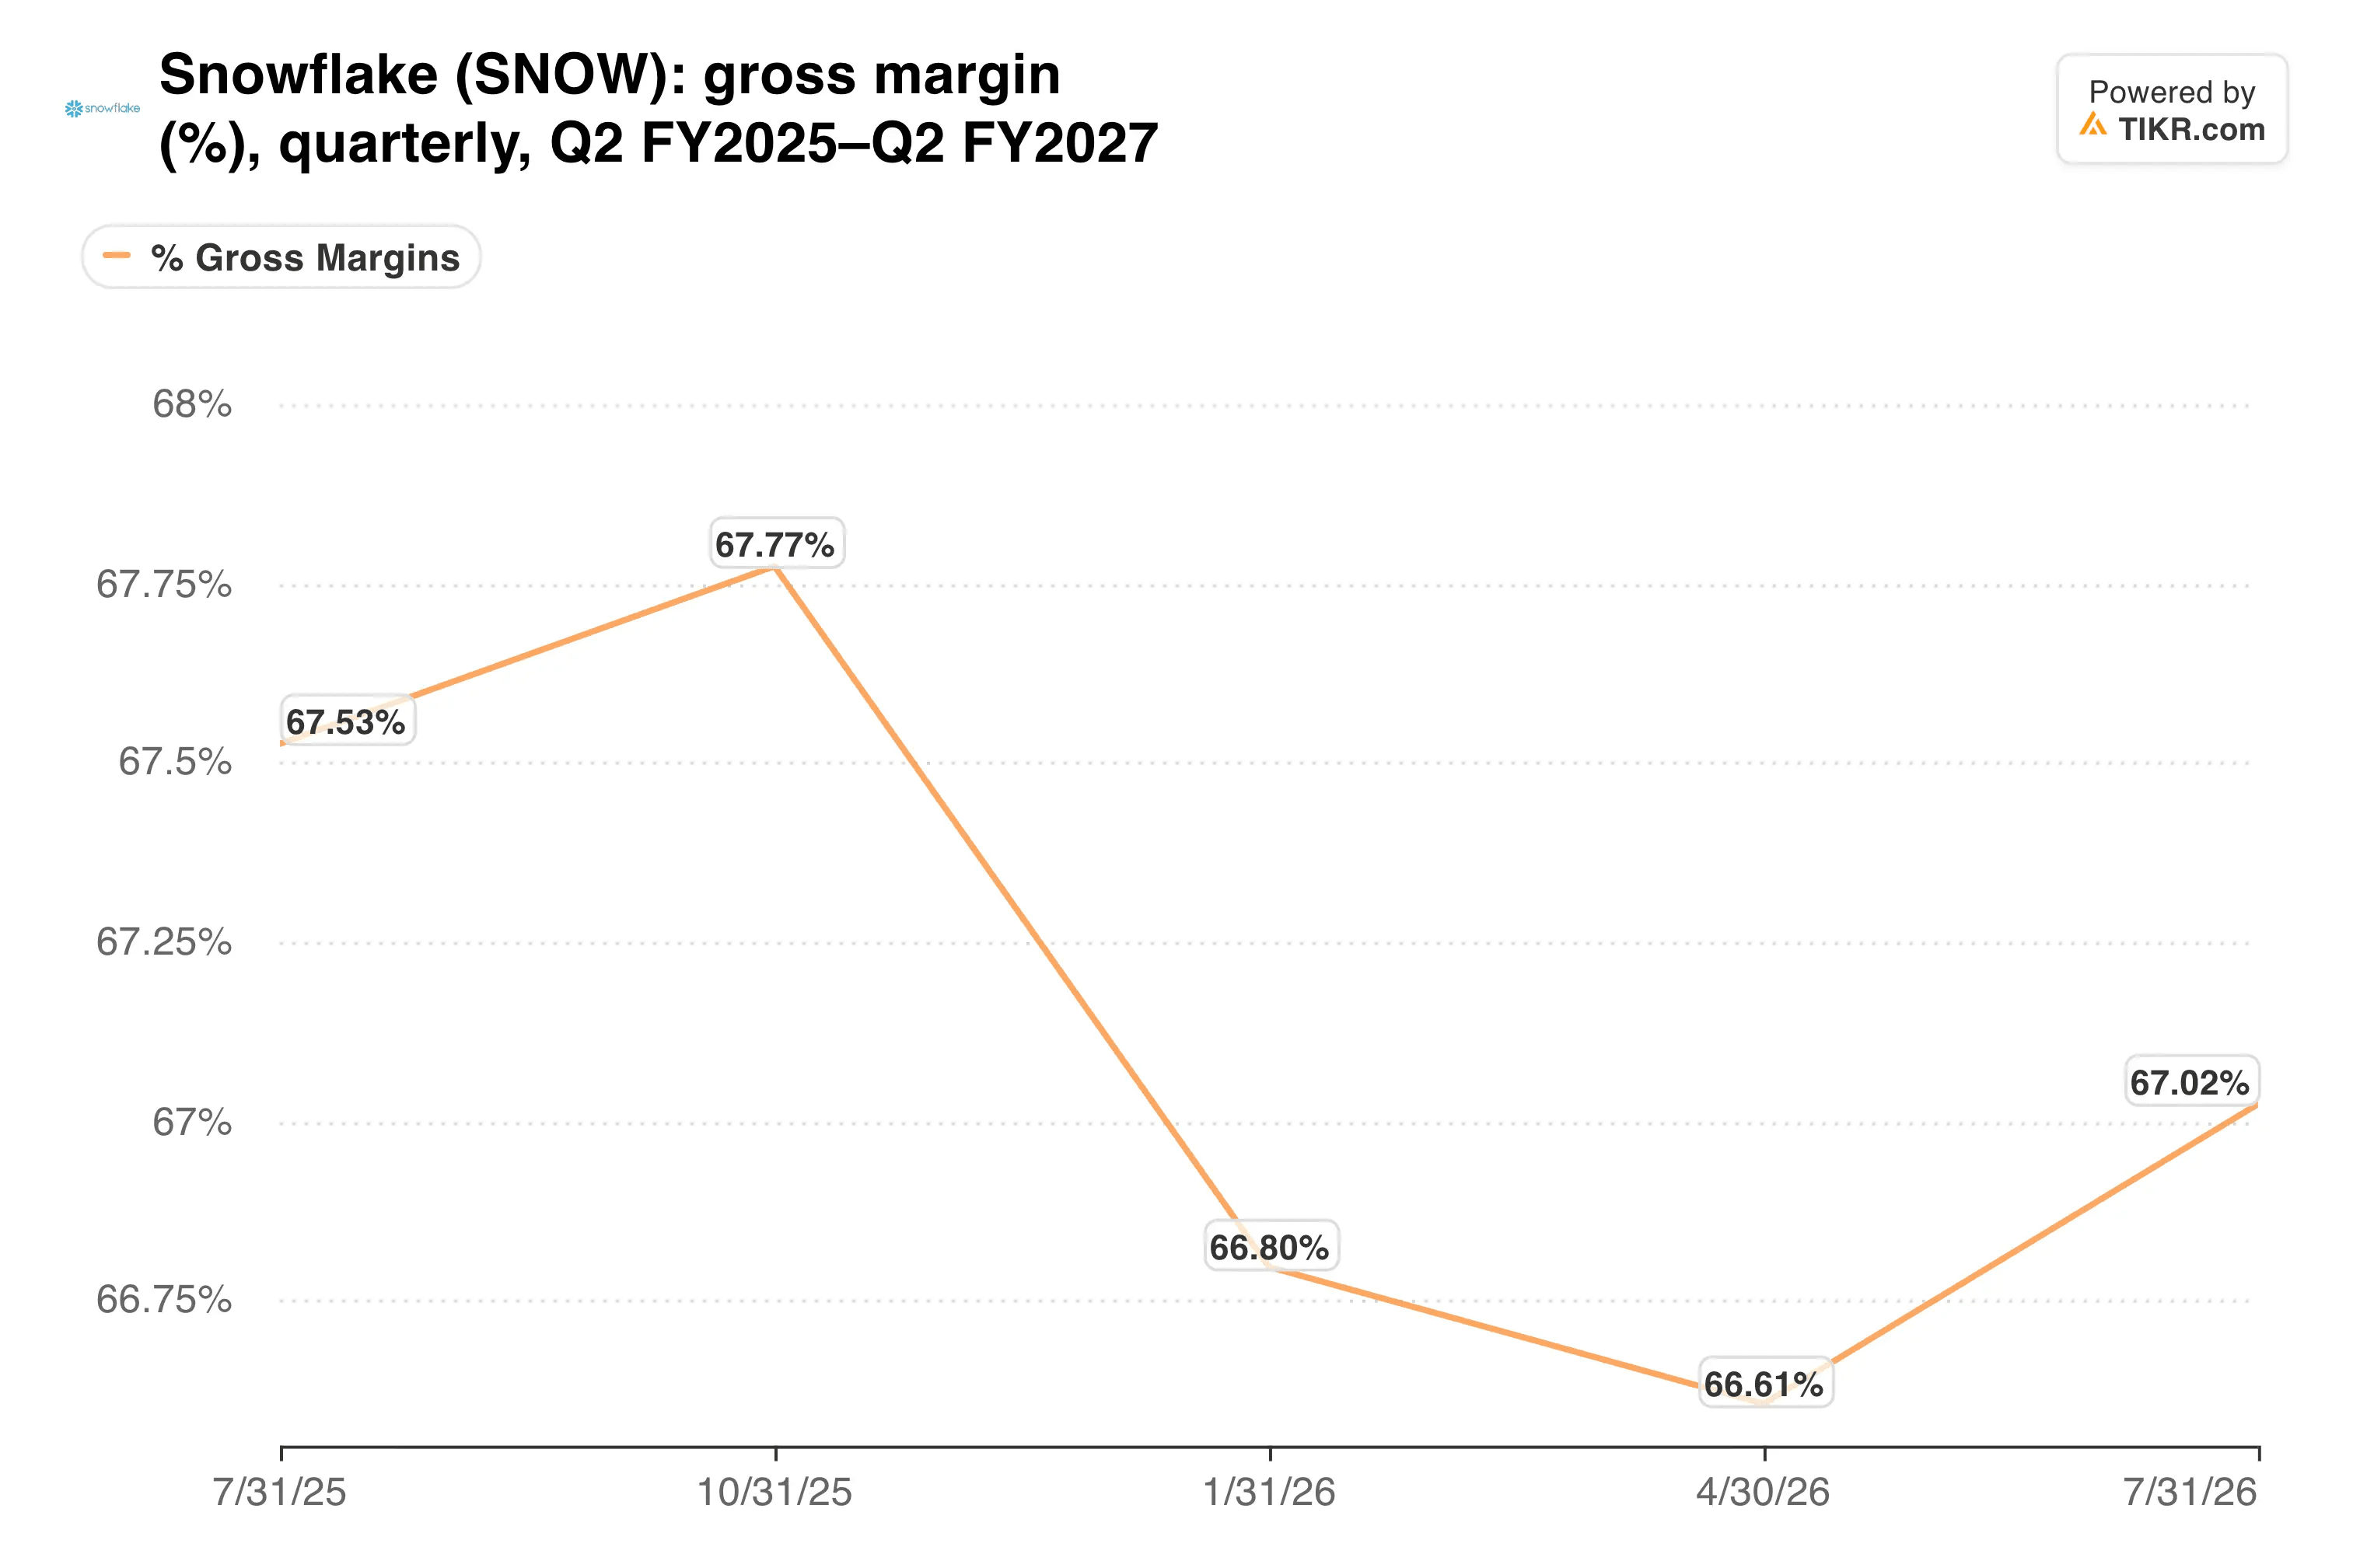
Non-GAAP product gross margin slipped to 74.7% from 76.4% a year earlier. The full-year guide calls for 74%, so management expects that pressure to stay.
Operating leverage has more than offset it so far. Non-GAAP operating margin rose to 15.3% from 11.1%, while stock-based compensation charges fell to 29% of revenue from 39%. Still, the GAAP operating loss was $263 million.
Valuation leaves little room for a stumble. At the September high, Snowflake traded at roughly twice the forward sales multiple of the broader software group.
My take: The Expedition launches are smart, since budget caps and audit trails are what CIOs need before agents reach production. But they won’t move this quarter’s numbers. I’d hold rather than chase here, because the stock needs both growth near 38% and gross margin near 74% to justify its premium.
Snowflake reports after the close on December 2. The key tests are product revenue against the $1.588 billion to $1.593 billion guide, gross margin against 74%, and whether the January quarter guide keeps growth in the high 30s.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!