Key Takeaways
- ServiceNow launched AI Workflow Factory globally on October 6, bundling process mining, agent building, and AI governance into one system.
- Q2 subscription revenue rose 24.5% to $3.88 billion, and AI annual contract value crossed $1 billion.
- Shares trade at 33.0x forward earnings after a 42.8% three-month run, leaving about 3% upside to the average target.
- The October 28 Q3 report will show whether AI deals keep cRPO growth near the 19.5% to 20% guide.
ServiceNow (NOW) has a simple pitch for the AI era: agents need a manager.
On October 20, it published a study finding that 90% of organizations had an agentic AI security incident in the past year. That stat happens to support its own product, AI Workflow Factory, which launched globally on October 6.
Shares rose 2.9% to $150 that day and have returned 42.8% over three months. Q3 results arrive October 28.
One governed loop for agents
AI Workflow Factory bundles tools ServiceNow already sells into one system. Process Mining finds slow workflows, Build Agent and App Engine create fixes, and AI Control Tower governs what the agents do.
A new Autonomous Engineer, which plans, builds, and tests code on its own, is in early access. ServiceNow did not disclose pricing for either product.
The subscription base underneath keeps compounding…

Q2 subscription revenue rose 24.5% to $3.88 billion, topping the high end of guidance by 1.5 percentage points. Total revenue grew 24% to $3.99 billion.
AI deals passed $1 billion
AI annual contract value, the yearly value of signed AI deals, crossed $1 billion in Q2. Current remaining performance obligations, or contracted revenue due within 12 months, rose 21% to $13.2 billion.
Management raised full-year subscription guidance to between $15.76 billion and $15.78 billion, about 20.5% growth.
It also shut down deal chatter. ServiceNow said it has “no interest or intention” of buying AI startup Decagon, and President Amit Zavery reiterated that it is an organic-growth-first company.
Analysts see that growth carrying into profits…
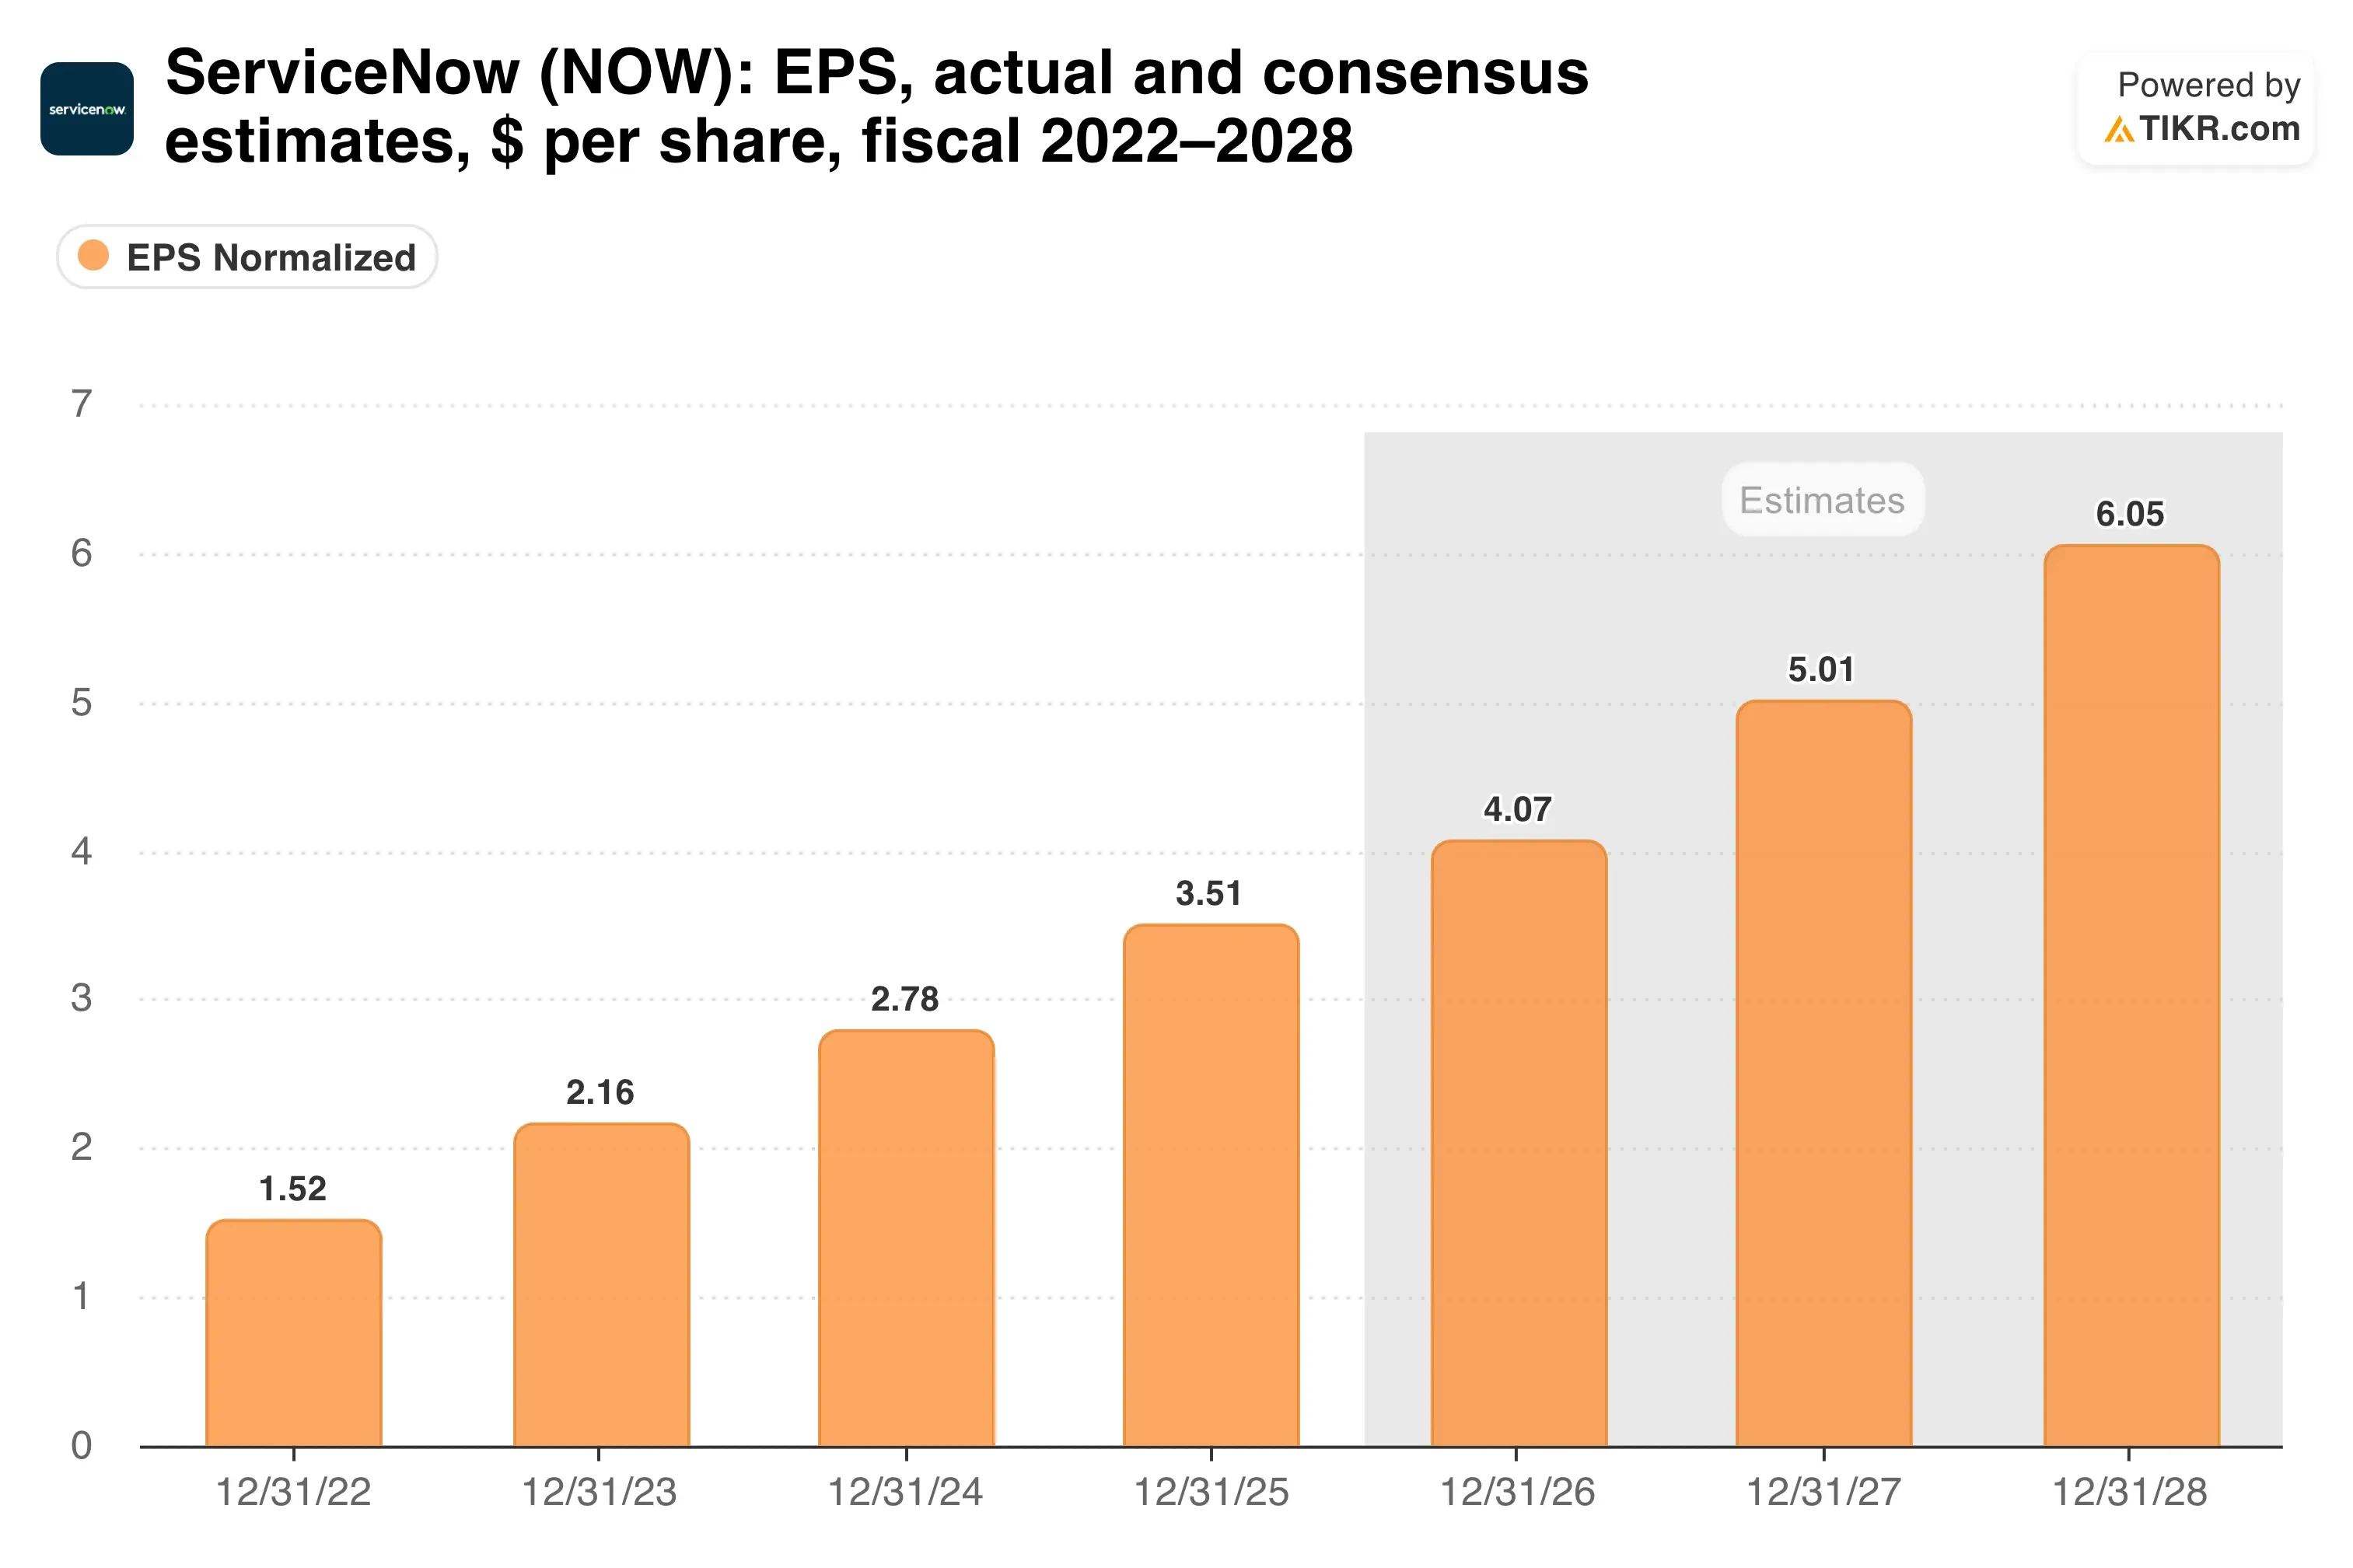
Consensus expects EPS to grow about 19.4% a year over the next two years, roughly in step with revenue.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
The multiple is catching up
The stock has run much faster than earnings, and the forward P/E shows it…
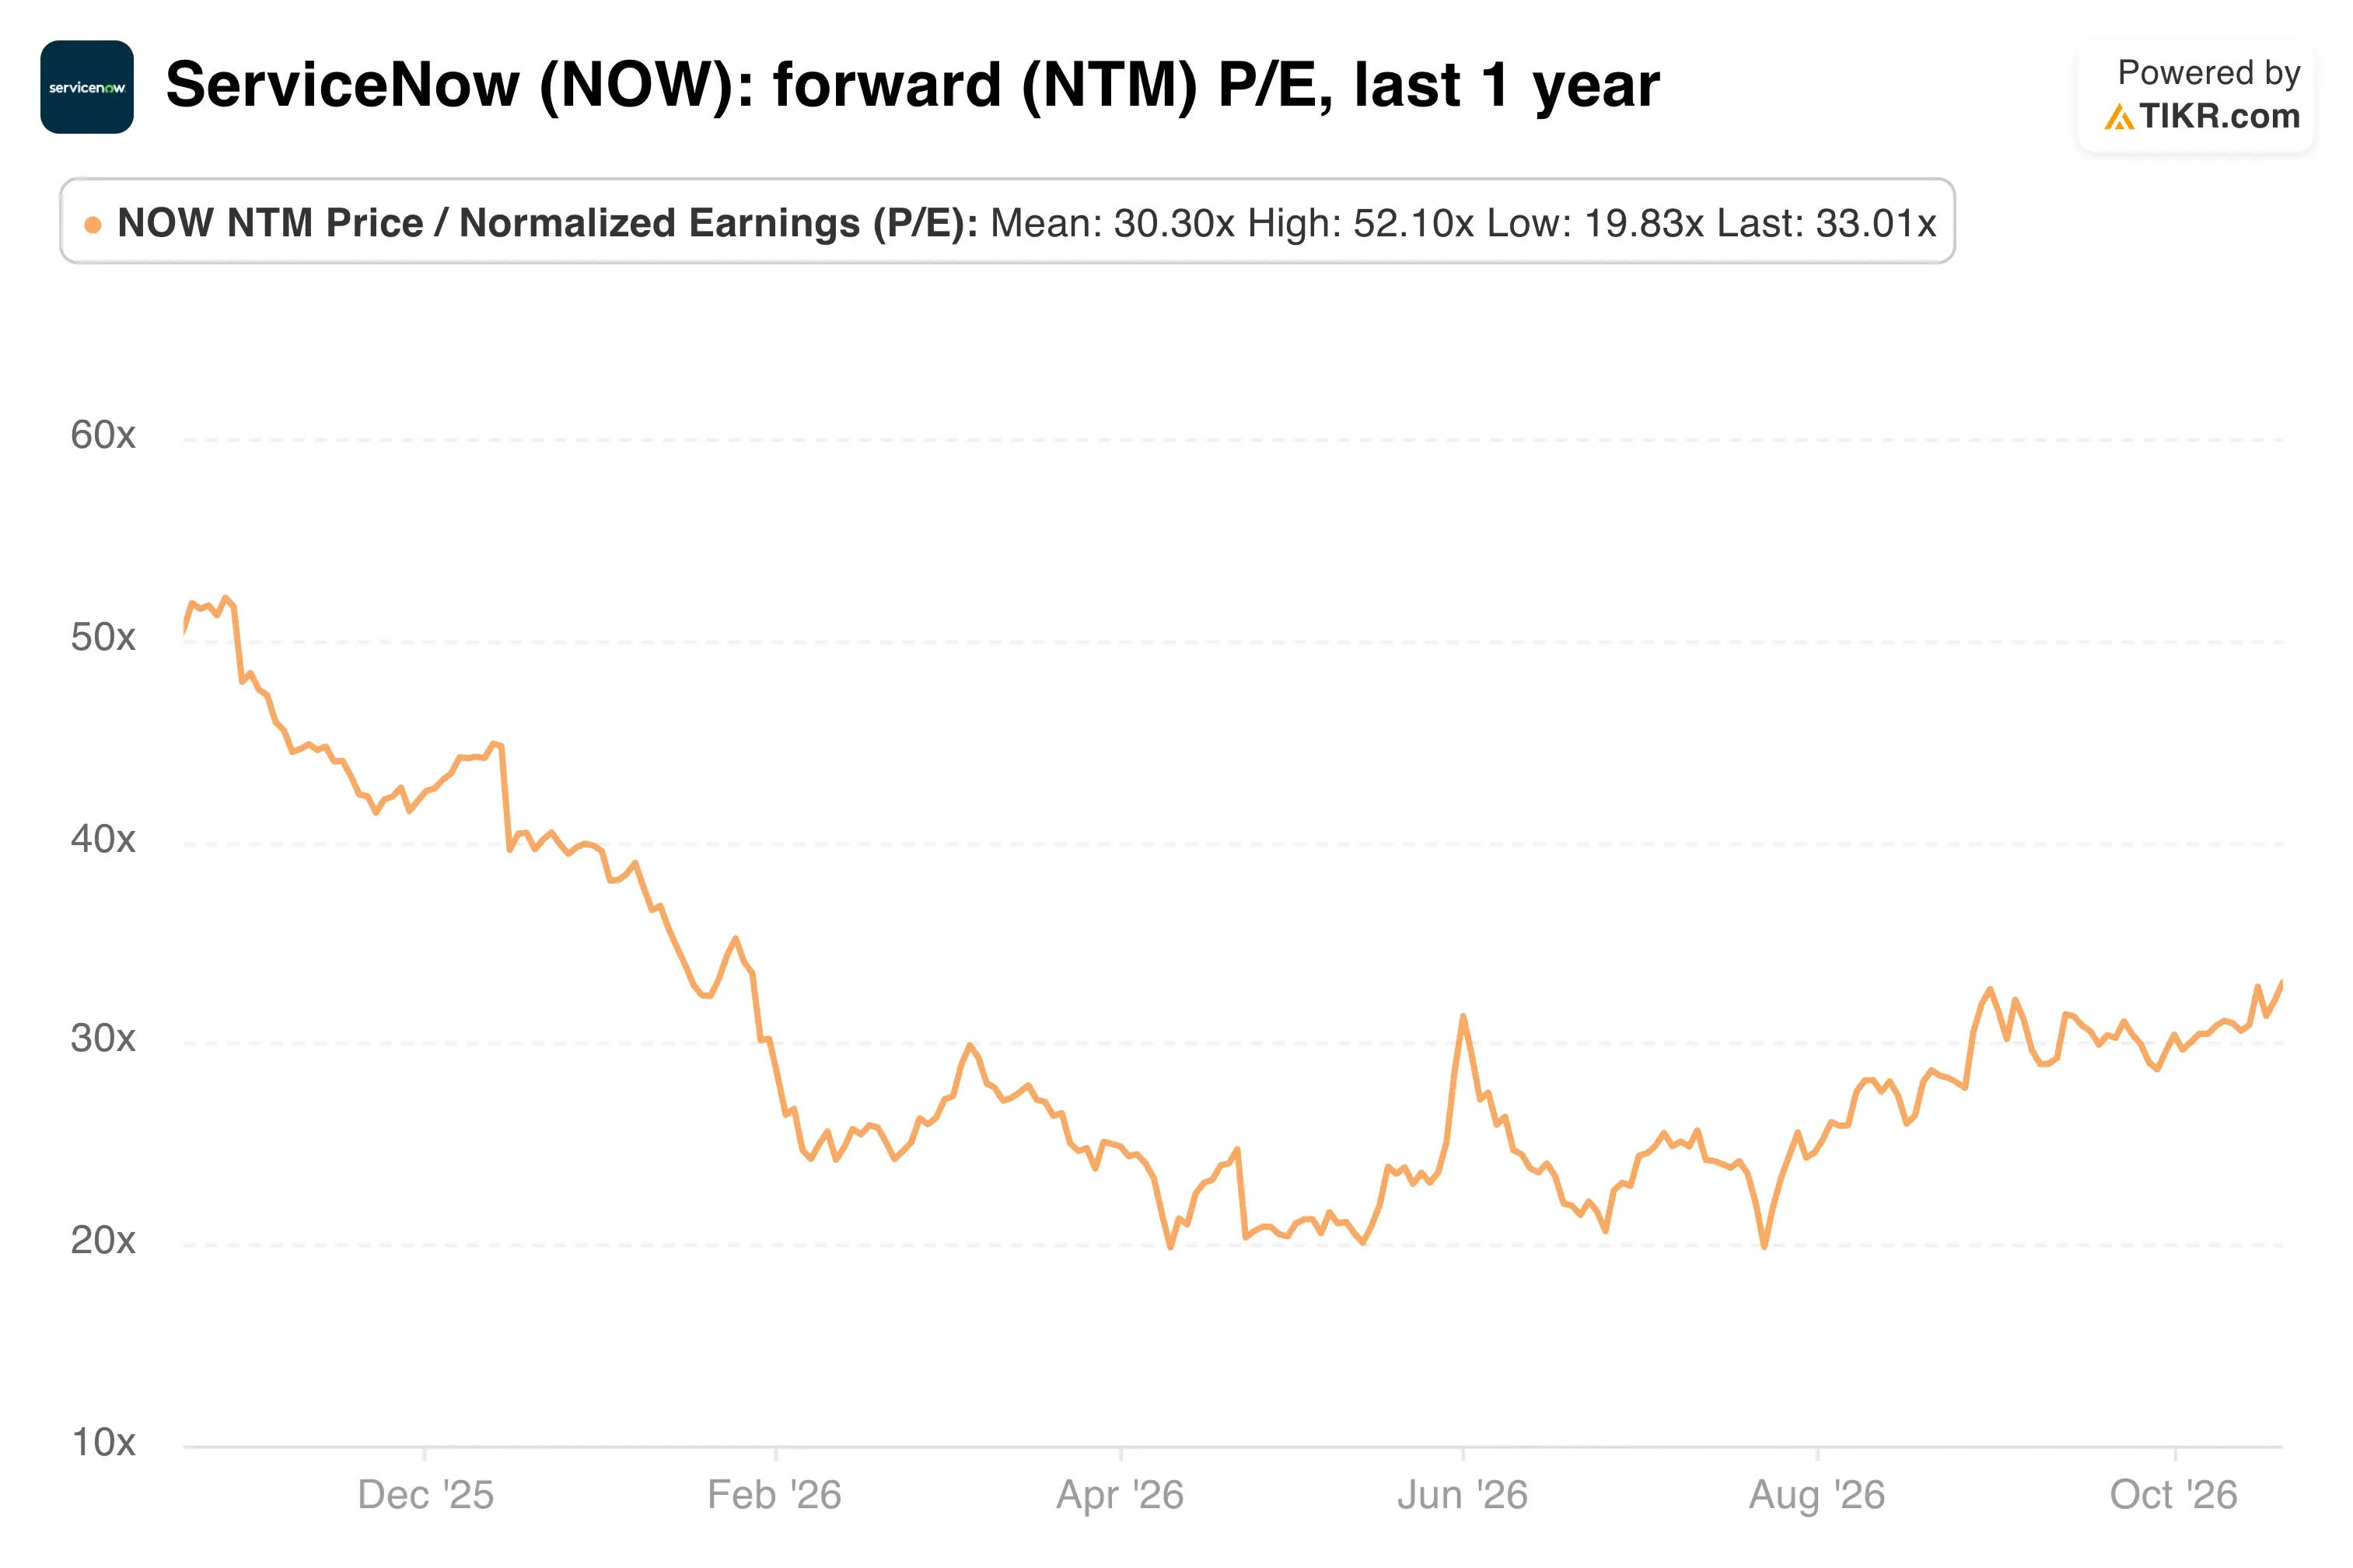
Shares trade at 33.0x forward earnings, up from about 23x at the end of June, while forward EPS barely moved. The average analyst target of $154 implies only about 3% upside.
My take: Governance is what nervous CIOs actually want, so ServiceNow is selling the right thing. But at 33x, Q3 has to prove AI deals add net new contract value rather than relabel old ones.
October 28 is the test. Watch cRPO growth against the 19.5% to 20% guide and any fresh update on AI contract value.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!