Key Takeaways
- Qualcomm shares rose 5% today on Alphabet’s nearly $548 million stake.
- The stake backs Qualcomm’s data center push, still targeting $5 billion of revenue in fiscal 2027.
- Arm and Intel have a lot riding on that push too.
- Qualcomm trades above its five-year average forward P/E as earnings shrink, so data center revenue has to show up.
Qualcomm (QCOM) jumped 5% today after Alphabet (GOOGL) disclosed a stake of nearly $548 million, a vote for its push into data centers. That’s a day after it sank 12% on a 26% drop in handset chip revenue.
Two chipmakers have a lot riding on that push: Arm Holdings (ARM), which licenses the designs Qualcomm’s CPUs run on, and Intel (INTC), whose server chips Qualcomm wants to compete with.
A second hyperscaler buys in
Alphabet’s 13F shows roughly 3 million Qualcomm shares at the end of September.
On Wednesday, CEO Cristiano Amon kept the $5 billion fiscal 2027 data center target, mostly from two hyperscalers, one of them Amazon. Amazon already holds a warrant for up to 25 million Qualcomm shares. Now another cloud giant owns the stock.
Short on everything
Asked by Yahoo Finance today about the AI sell-off, Amon pointed to an industry “short on wafers.” He thinks “there may be a disconnect in what the market probably expects the rates of build out and the actual rate of build out.”
Intel, up 7% today, has the same problem. Its data center and AI revenue jumped 78% in the September quarter, and CEO Lip-Bu Tan’s priority is unlocking supply “to meet extraordinary demand for our Xeon family.” That’s an opening for Qualcomm.
If Qualcomm wins that business, Arm, up 3%, gets a cut. Its data center royalties more than doubled year over year in each of the four quarters through June. But phones were still about 43% of its royalties in the year to March 2026, so Qualcomm’s handset slump hurts Arm, too.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
The numbers still have to catch up
Going into Wednesday’s report, analysts expected Qualcomm’s earnings to dip again in fiscal 2027:
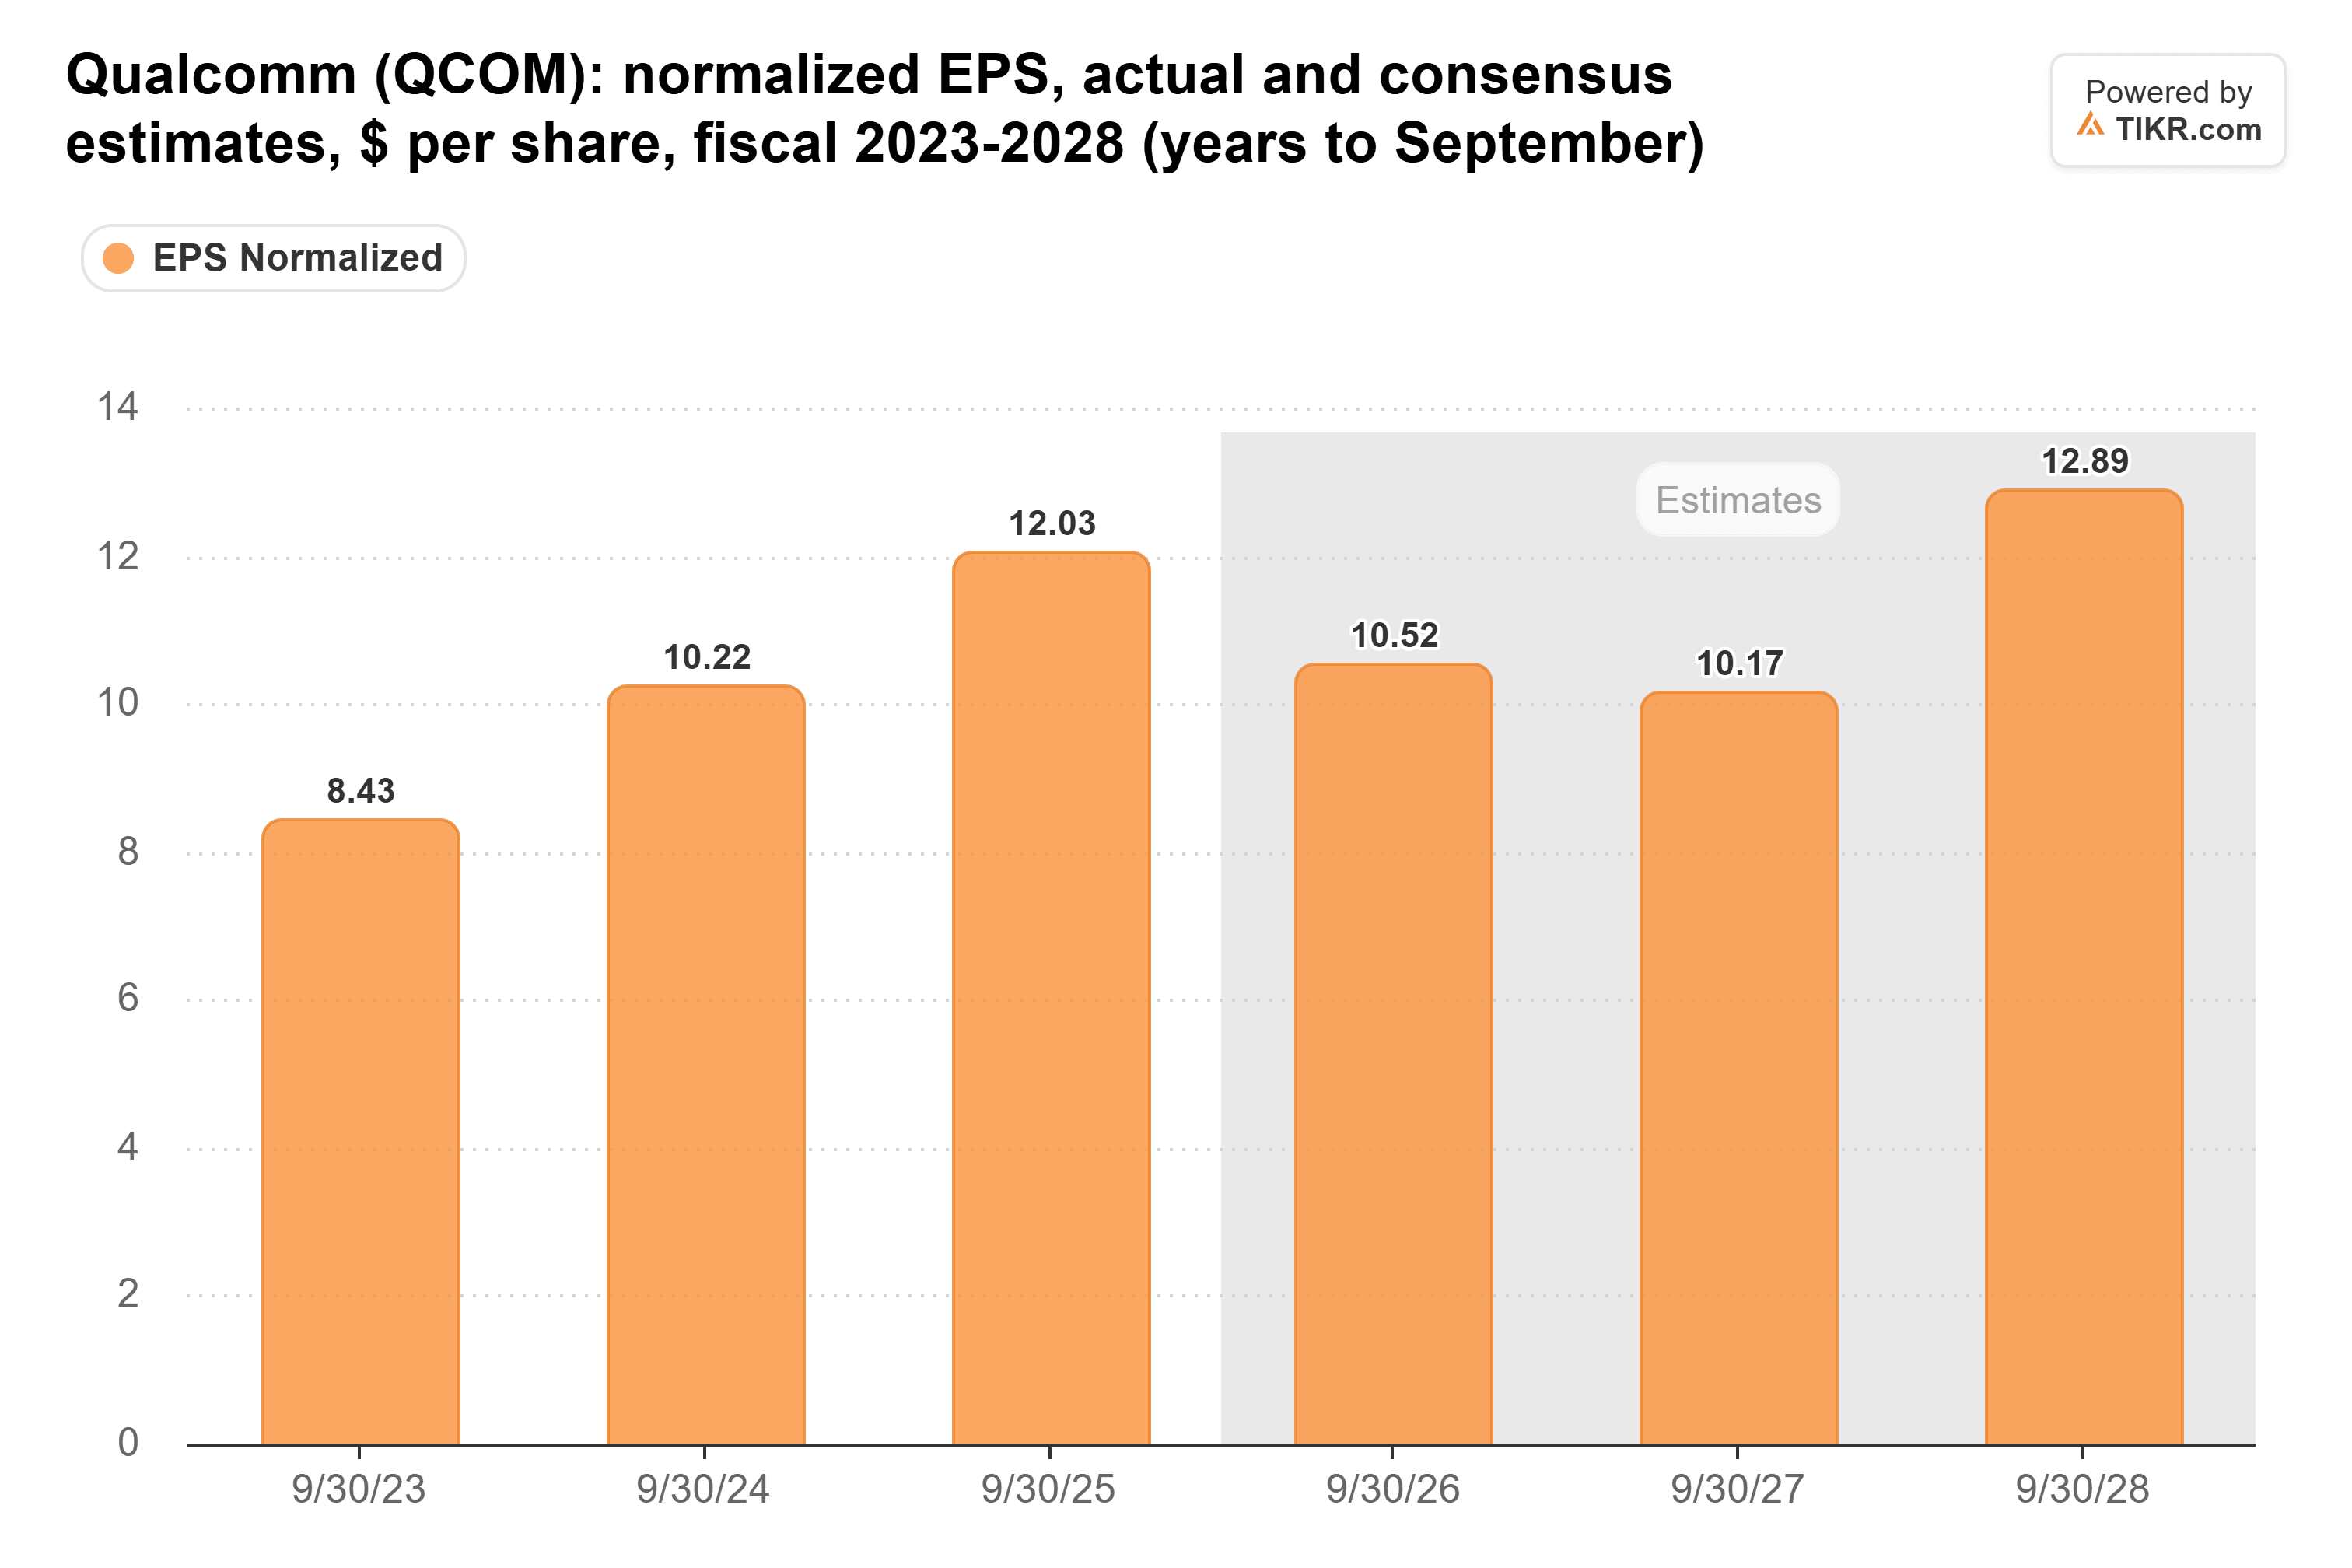
And the stock isn’t cheap against its own history:

At the last close, it traded at about 18x forward earnings, above its five-year average of 14x, and today’s jump takes it higher.
Alphabet’s vote is welcome. But at that multiple, with earnings shrinking, I’d want to see data center revenue before buying this bounce.
We’ll know more early next year, when Qualcomm reports its first quarter of revenue from custom chips for two hyperscalers.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!