


Key Takeaways
- Amazon validates Qualcomm’s data-center strategy, but it did not hand the company $60 billion of booked revenue. The purchase opportunity runs up to $60 billion over 10 years and is tied to warrant vesting and actual product purchases.
- The new growth engine matters because the core business is still uneven. Revenue fell to $9.95 billion in the June 2026 quarter, down from $10.37 billion a year earlier and $12.25 billion in December 2025.
- QCOM is already priced for a successful pivot. Its 19.63x forward P/E is about 29% above its 15.26x historical mean, while normalized EPS estimates do not inflect materially until FY2028.
Amazon gives Qualcomm an opening in AI data centers, but the earnings ramp will decide the stock. See QCOM’s revenue, EPS, and valuation outlook on TIKR for free →
Qualcomm’s Amazon agreement gives investors the clearest public proof yet that its data-center ambitions are becoming commercial rather than theoretical. The company is supplying custom AI-inference silicon and optical connectivity that can extend to 1.6 terabits per second, pushing Qualcomm further beyond its traditional smartphone base.
The question is no longer whether Qualcomm has a credible AI story. It is whether the Amazon relationship can convert into enough revenue to justify a stock already trading at 19.63x next-twelve-month normalized earnings.
Amazon Gives Qualcomm a Customer, Not $60 Billion of Guaranteed Revenue
The headline number is large, but investors should read it carefully.
Amazon can purchase up to $60 billion of Qualcomm server-chip products, technology, systems, and manufacturing services over 10 years. Qualcomm issued Amazon warrants for up to 25 million shares at an exercise price of $161.26, with vesting tied to commercial arrangements, binding purchase orders, and actual purchases. 3.75 million shares vested at issuance based on initial commitments. Qualcomm’s September 8-K
That makes this a meaningful commercial endorsement, but not a conventional backlog figure. Qualcomm has effectively offered Amazon potential equity participation in exchange for long-term demand. The value of the agreement will depend on how quickly Amazon converts its commitments into orders and how much of the opportunity Qualcomm can fulfill profitably.
Management said it is already in production and expects revenue to begin in the December quarter. It also called its approximately $5 billion fiscal 2027 data-center revenue target “very high confidence,” with a goal of more than $15 billion by fiscal 2029. That would turn data centers into a genuine third growth engine beside handsets and auto/IoT, not merely an AI narrative.
The $60 billion headline matters only if it becomes recurring revenue. Explore Qualcomm’s forward estimates on TIKR →
The Core Business Still Needs to Stabilize
The timing explains why the Amazon deal matters so much.
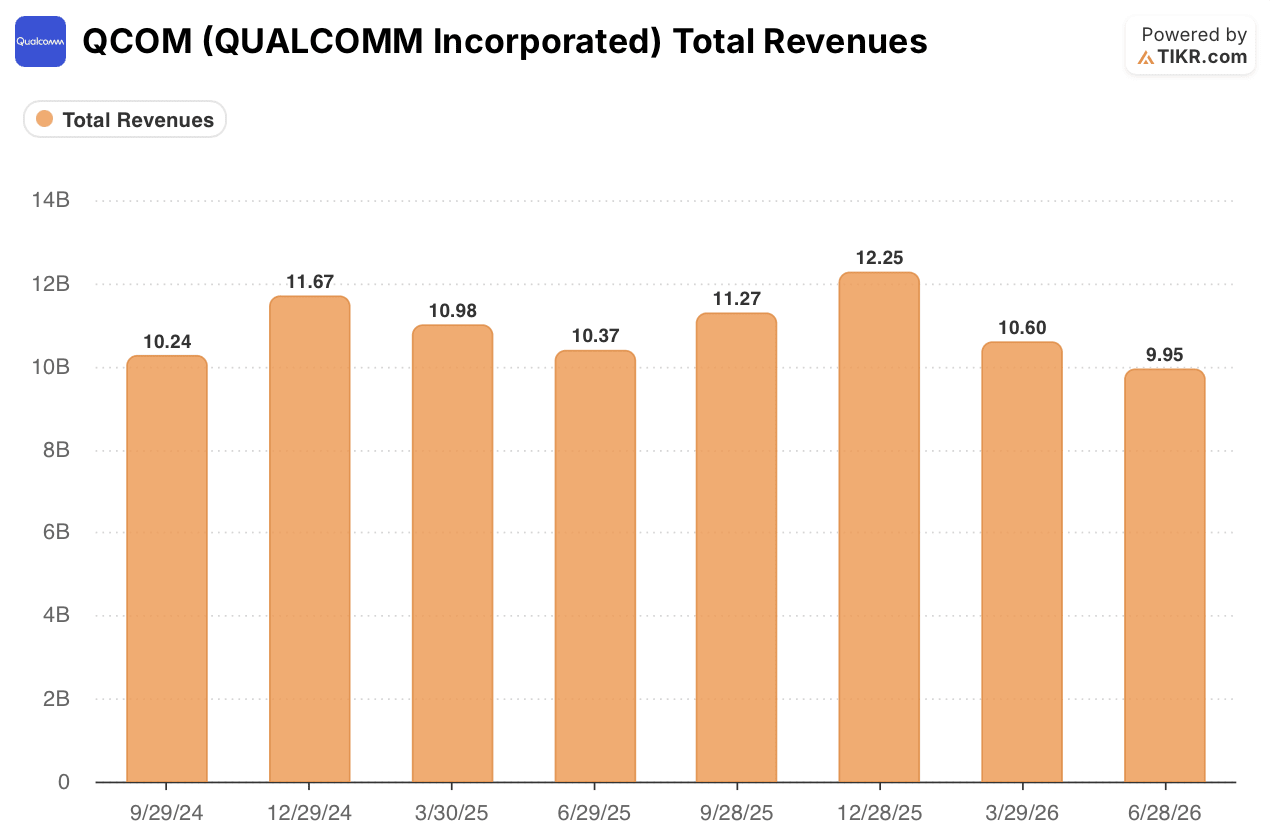
Qualcomm’s total revenue reached $9.95 billion in the June 2026 quarter, down roughly 4% from $10.37 billion a year earlier and nearly 19% below the $12.25 billion reported in December 2025. That does not mean the company’s existing businesses are broken, but it does show that investors cannot rely on a smooth handset-led recovery to carry the earnings story.
The data-center push is intended to reduce that dependence. Qualcomm expects non-handset businesses to exceed half of QCT revenue in fiscal 2027 and rise toward two-thirds by fiscal 2029. Amazon strengthens that plan because it supplies a named hyperscale customer and a real revenue starting point.
Still, investors should watch the conversion rate, not just the targets. December-quarter revenue, customer volume, and the pace of the optical-connectivity rollout will matter more than the $60 billion headline.
QCOM’s Valuation Is Already a Bet on the FY2028-FY2029 Ramp
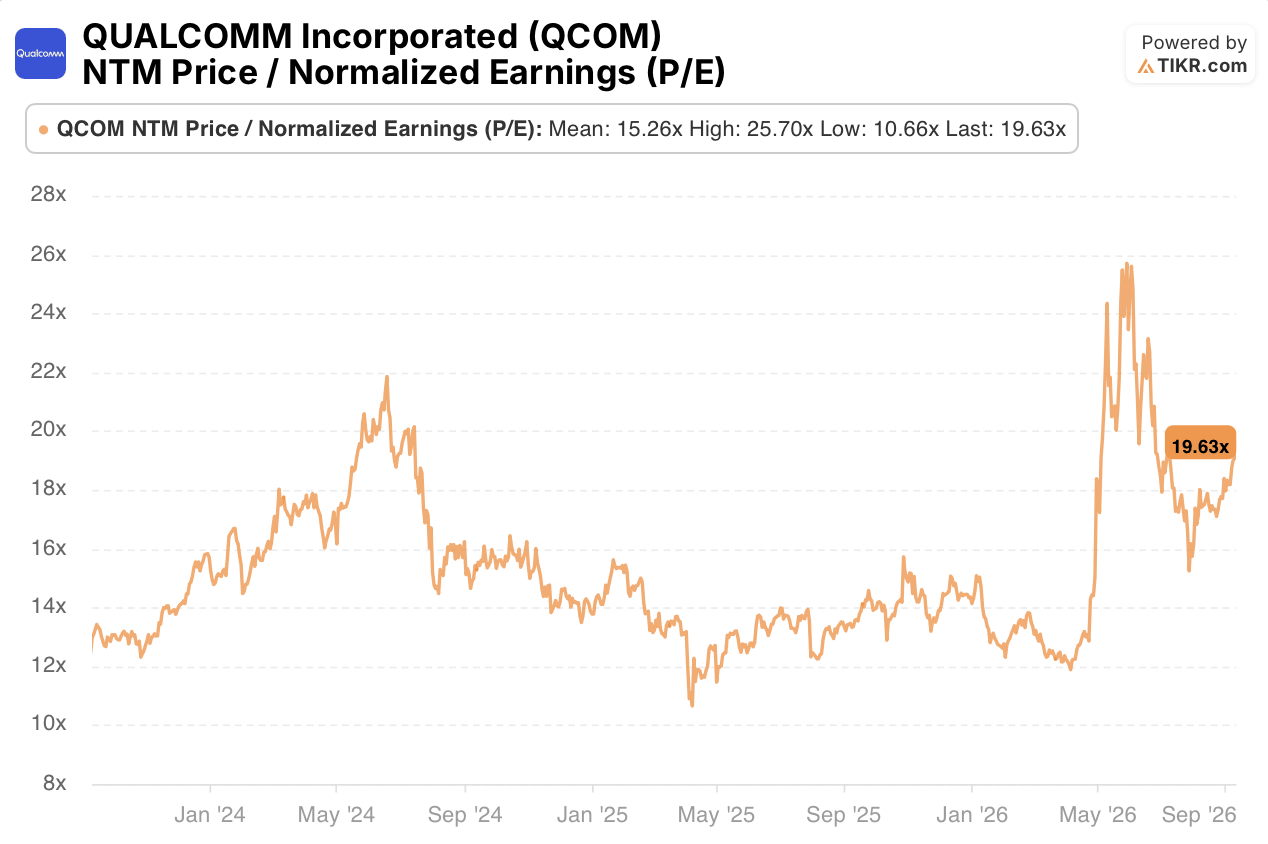
At 19.63x forward normalized earnings, Qualcomm trades above its 15.26x historical mean, though below its 25.70x high. The market is already assigning some value to Qualcomm becoming more than a cyclical handset-chip company.

The earnings path explains why execution matters. Normalized EPS is estimated to decline from $12.03 in fiscal 2025 to $10.48 in fiscal 2026 and $10.22 in fiscal 2027. It is then expected to rise to $12.97 in fiscal 2028 and $17.66 in fiscal 2029, a roughly 73% increase from the FY2027 estimate.
That forecast leaves little room for a weak rollout. Qualcomm does not need Amazon to deliver all $60 billion for the thesis to work. It needs the partnership to prove that its custom silicon and optical products can scale into durable, high-value data-center revenue while its established businesses stabilize.
For investors, QCOM is now less a pure smartphone-cycle story and more an execution story. Amazon has made the upside more believable. The next results must make it measurable.
Before buying into Qualcomm’s data-center pivot, compare its 19.6x forward P/E with its own history and other chip stocks. Start your free TIKR account →
Should You Invest in QUALCOMM Incorporated?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up QCOM stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track QCOM alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze QCOM stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


