Key Takeaways
- Pinterest has finished the roughly $2 billion of buybacks it announced in March, and it had $1.95 billion left on its authorization going into third-quarter results after the close on Thursday, Oct. 29.
- The rest of the buyback has to come from free cash flow, because Elliott’s $1 billion and Pinterest’s own cash already paid for the first round.
- Years of buybacks only held the diluted share count flat because stock pay took much of the cash, and unvested stock units have risen to 69.1 million.
- At 9.4x forward earnings, each buyback dollar retires far more stock than it did at the five-year average of 24x, and Thursday’s free cash flow, stock pay and share count show whether the buyback can keep going.
Pinterest (PINS) has bought back more than $2 billion of its own stock this year, and it still has nearly $2 billion left to spend. Thursday’s third-quarter report, due after the close on Oct. 29, is the first look at whether its own cash flow can pay for the rest.
The first $2 billion is done
On March 3, Pinterest announced:
- A new $3.5 billion share repurchase program.
- About $2 billion of buybacks in the first half of 2026, including a $1 billion accelerated repurchase.
- A $1 billion investment from Elliott Investment Management to pay for that accelerated repurchase.
It delivered. Pinterest bought back more than $2 billion of stock at an average of $18.17. Shares outstanding fell 15% in six months, from 664.5 million at the end of 2025 to 565.5 million on June 30.
That left $1.95 billion on the authorization. But Elliott’s money came as convertible notes due 2031, and cash and securities fell from $2.47 billion to $1.27 billion over those six months. So the rest has to come from free cash flow.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Cash flow can cover it, eventually
Free cash flow nearly tripled from 2022 to 2025.
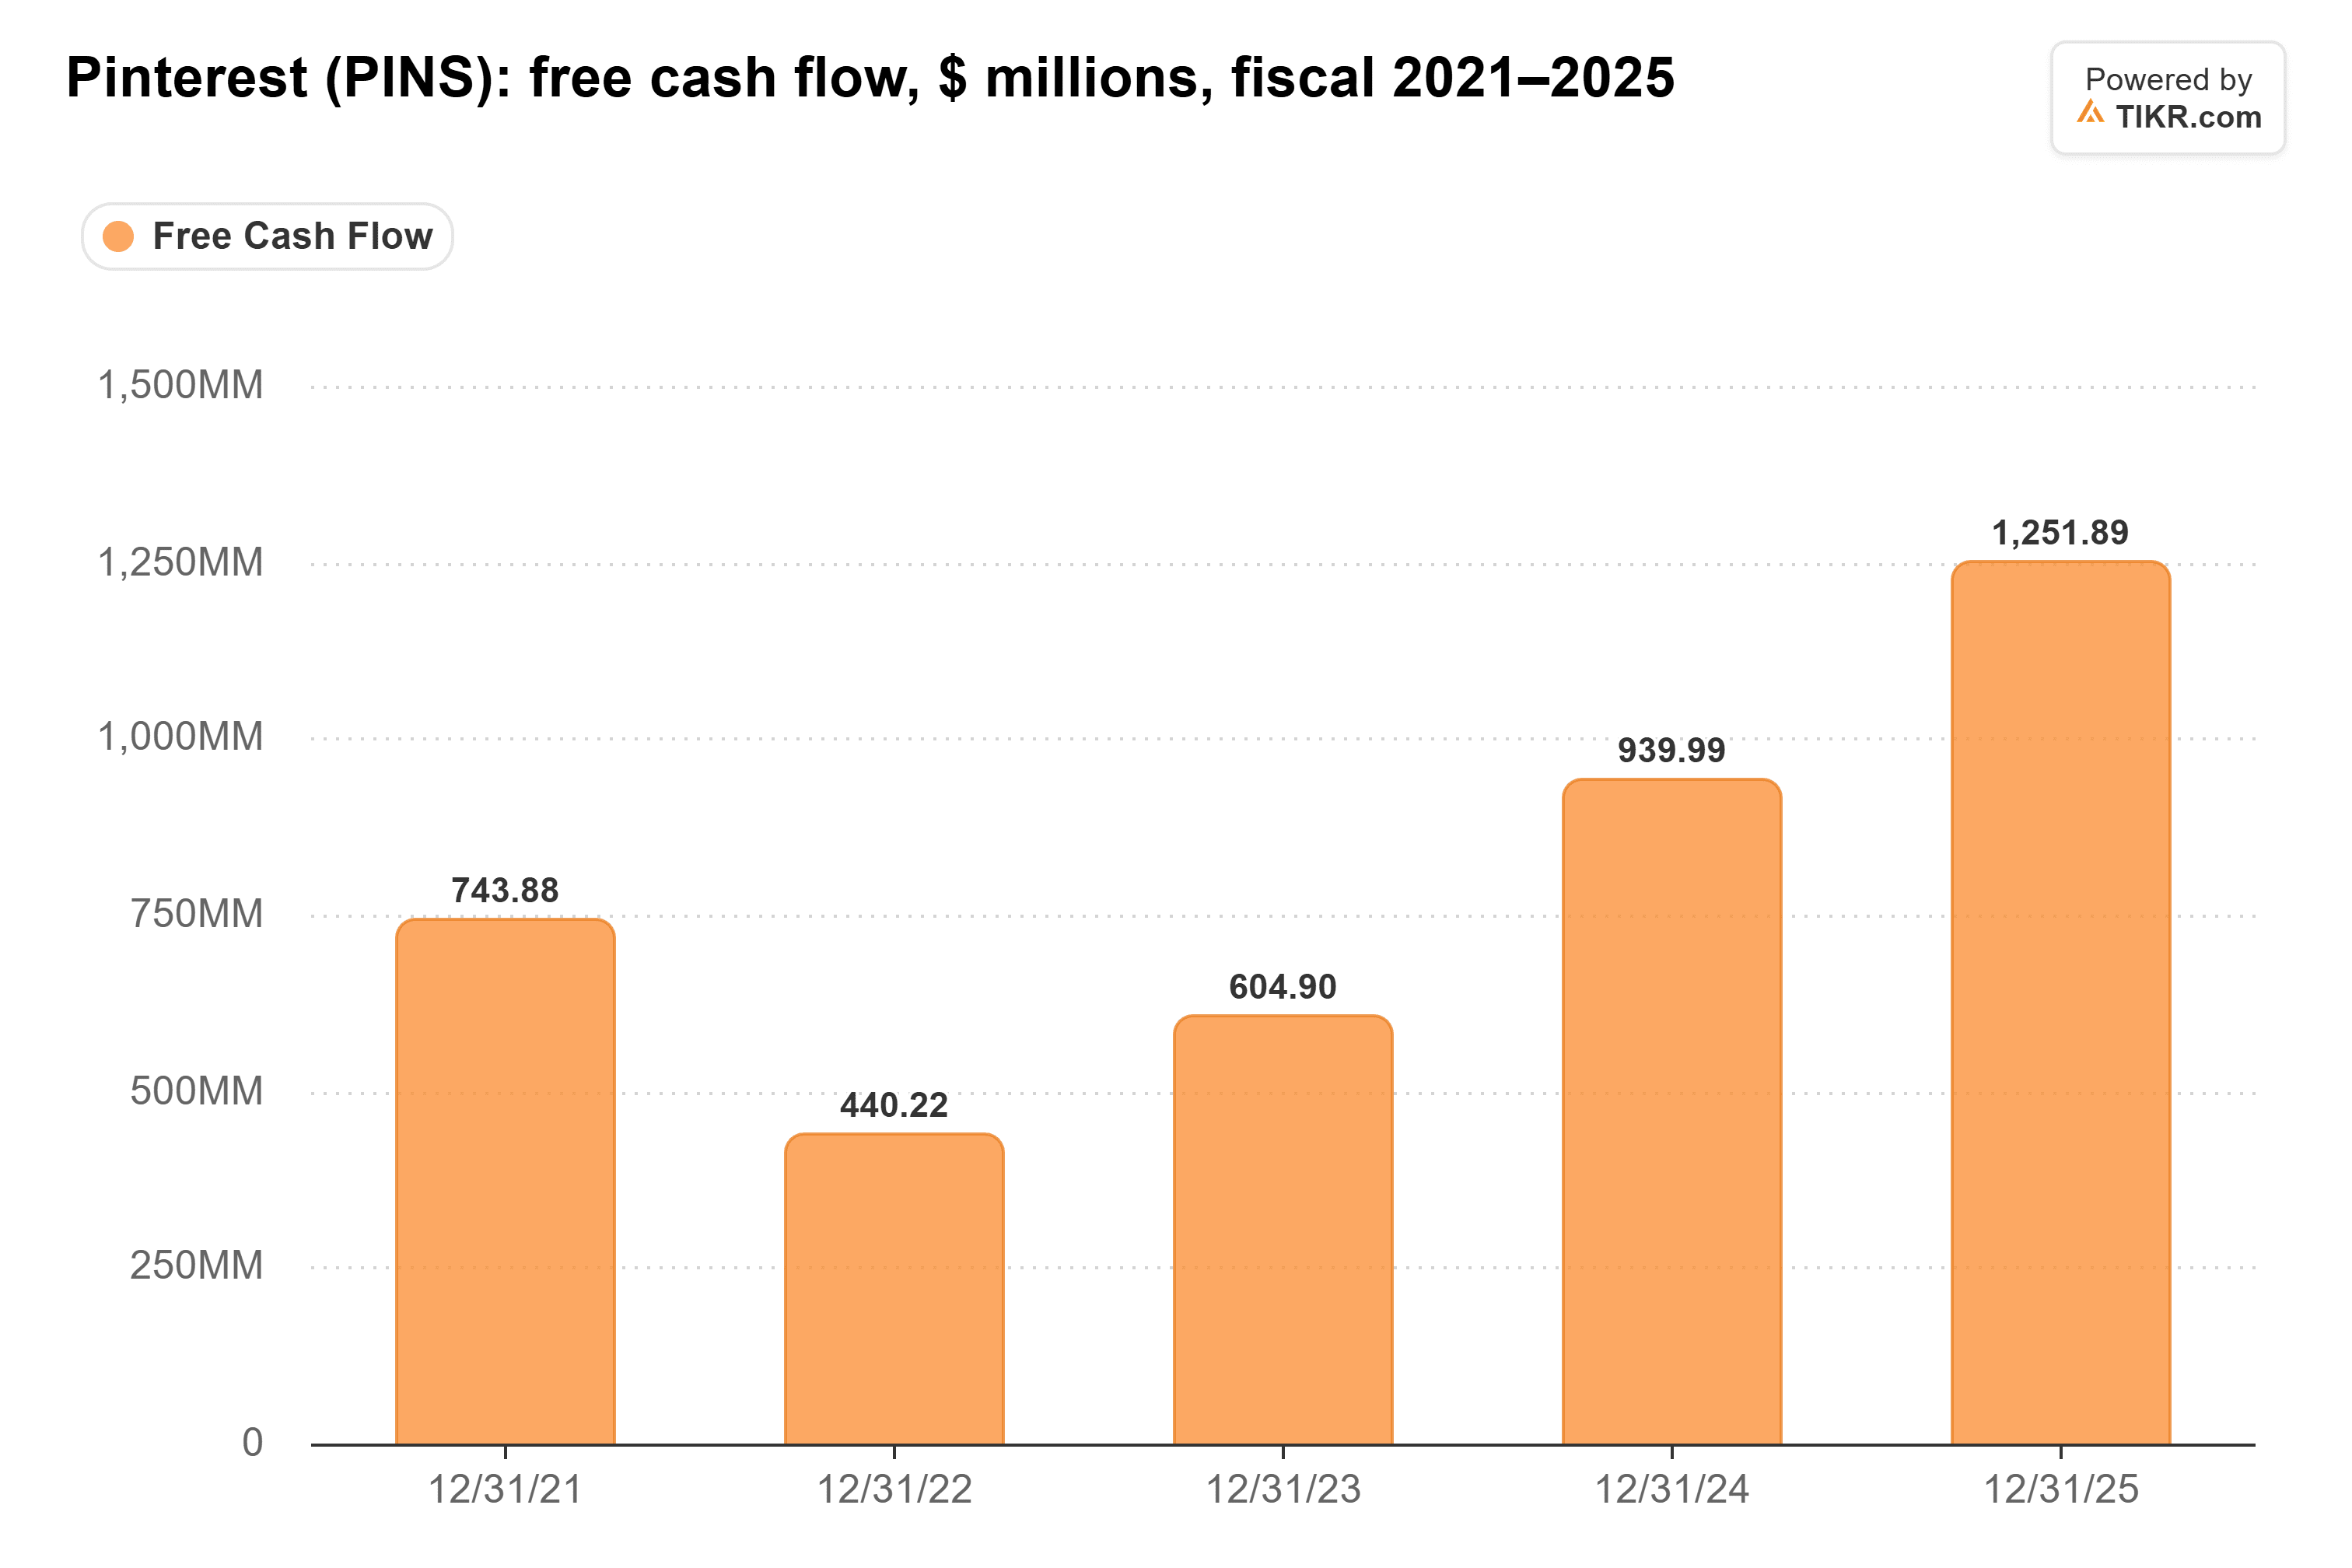
Analysts expect $1.27 billion this year. Not all of it can go to buybacks, though: Pinterest spent $399 million last year covering employees’ taxes on vesting shares. Set that much aside, and analysts’ 2026 figure pays for the remaining $1.95 billion in a bit over two years (roughly, since withholding moves with vesting and the stock price).
Stock pay keeps eating the cash
That withholding is the catch. Pinterest has bought back stock for years, and its diluted share count barely moved.
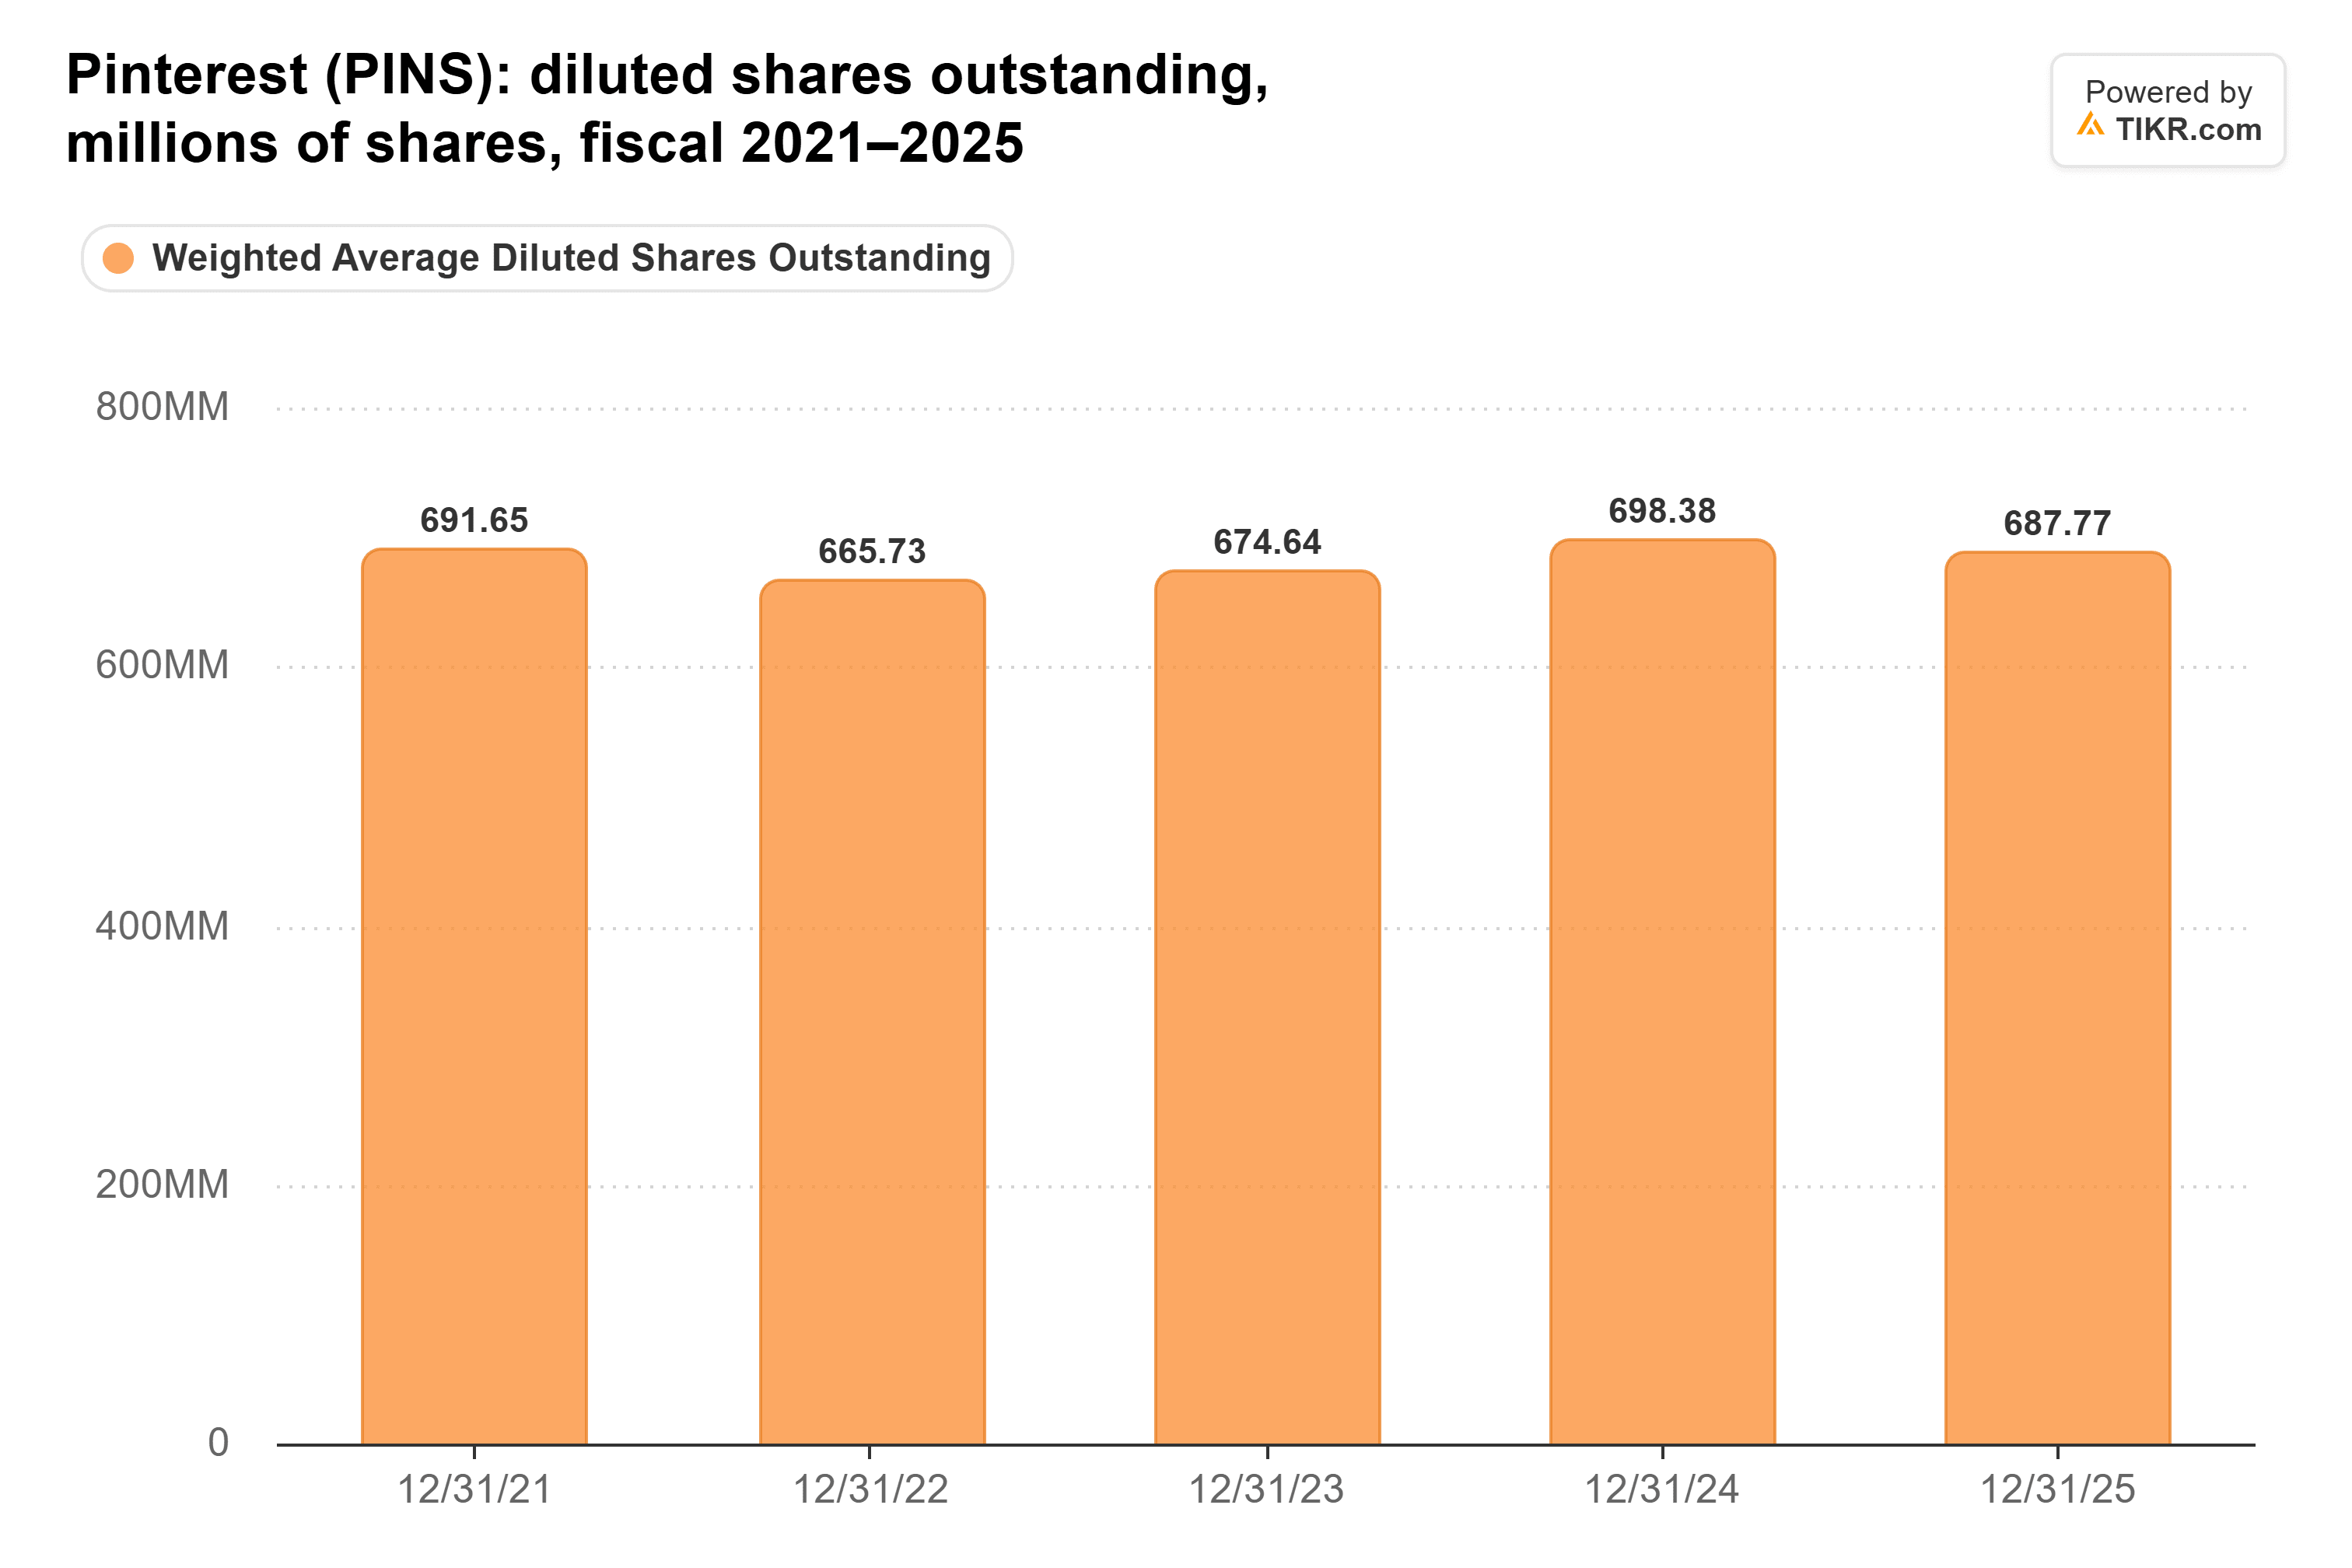
From 2021 to 2025, buybacks and tax withholding took $3.3 billion, 83% of free cash flow, while diluted shares went from 692 million to 688 million. And unvested stock units jumped from 39.1 million to 69.1 million in the first half of 2026, as stock compensation hit $324.5 million in the second quarter, up from $227.2 million a year earlier. Management expects it to come down starting in the third quarter.
Cheap shares go further
The stock is much cheaper now. Pinterest trades at 9.4x forward earnings, near the bottom of its five-year range.
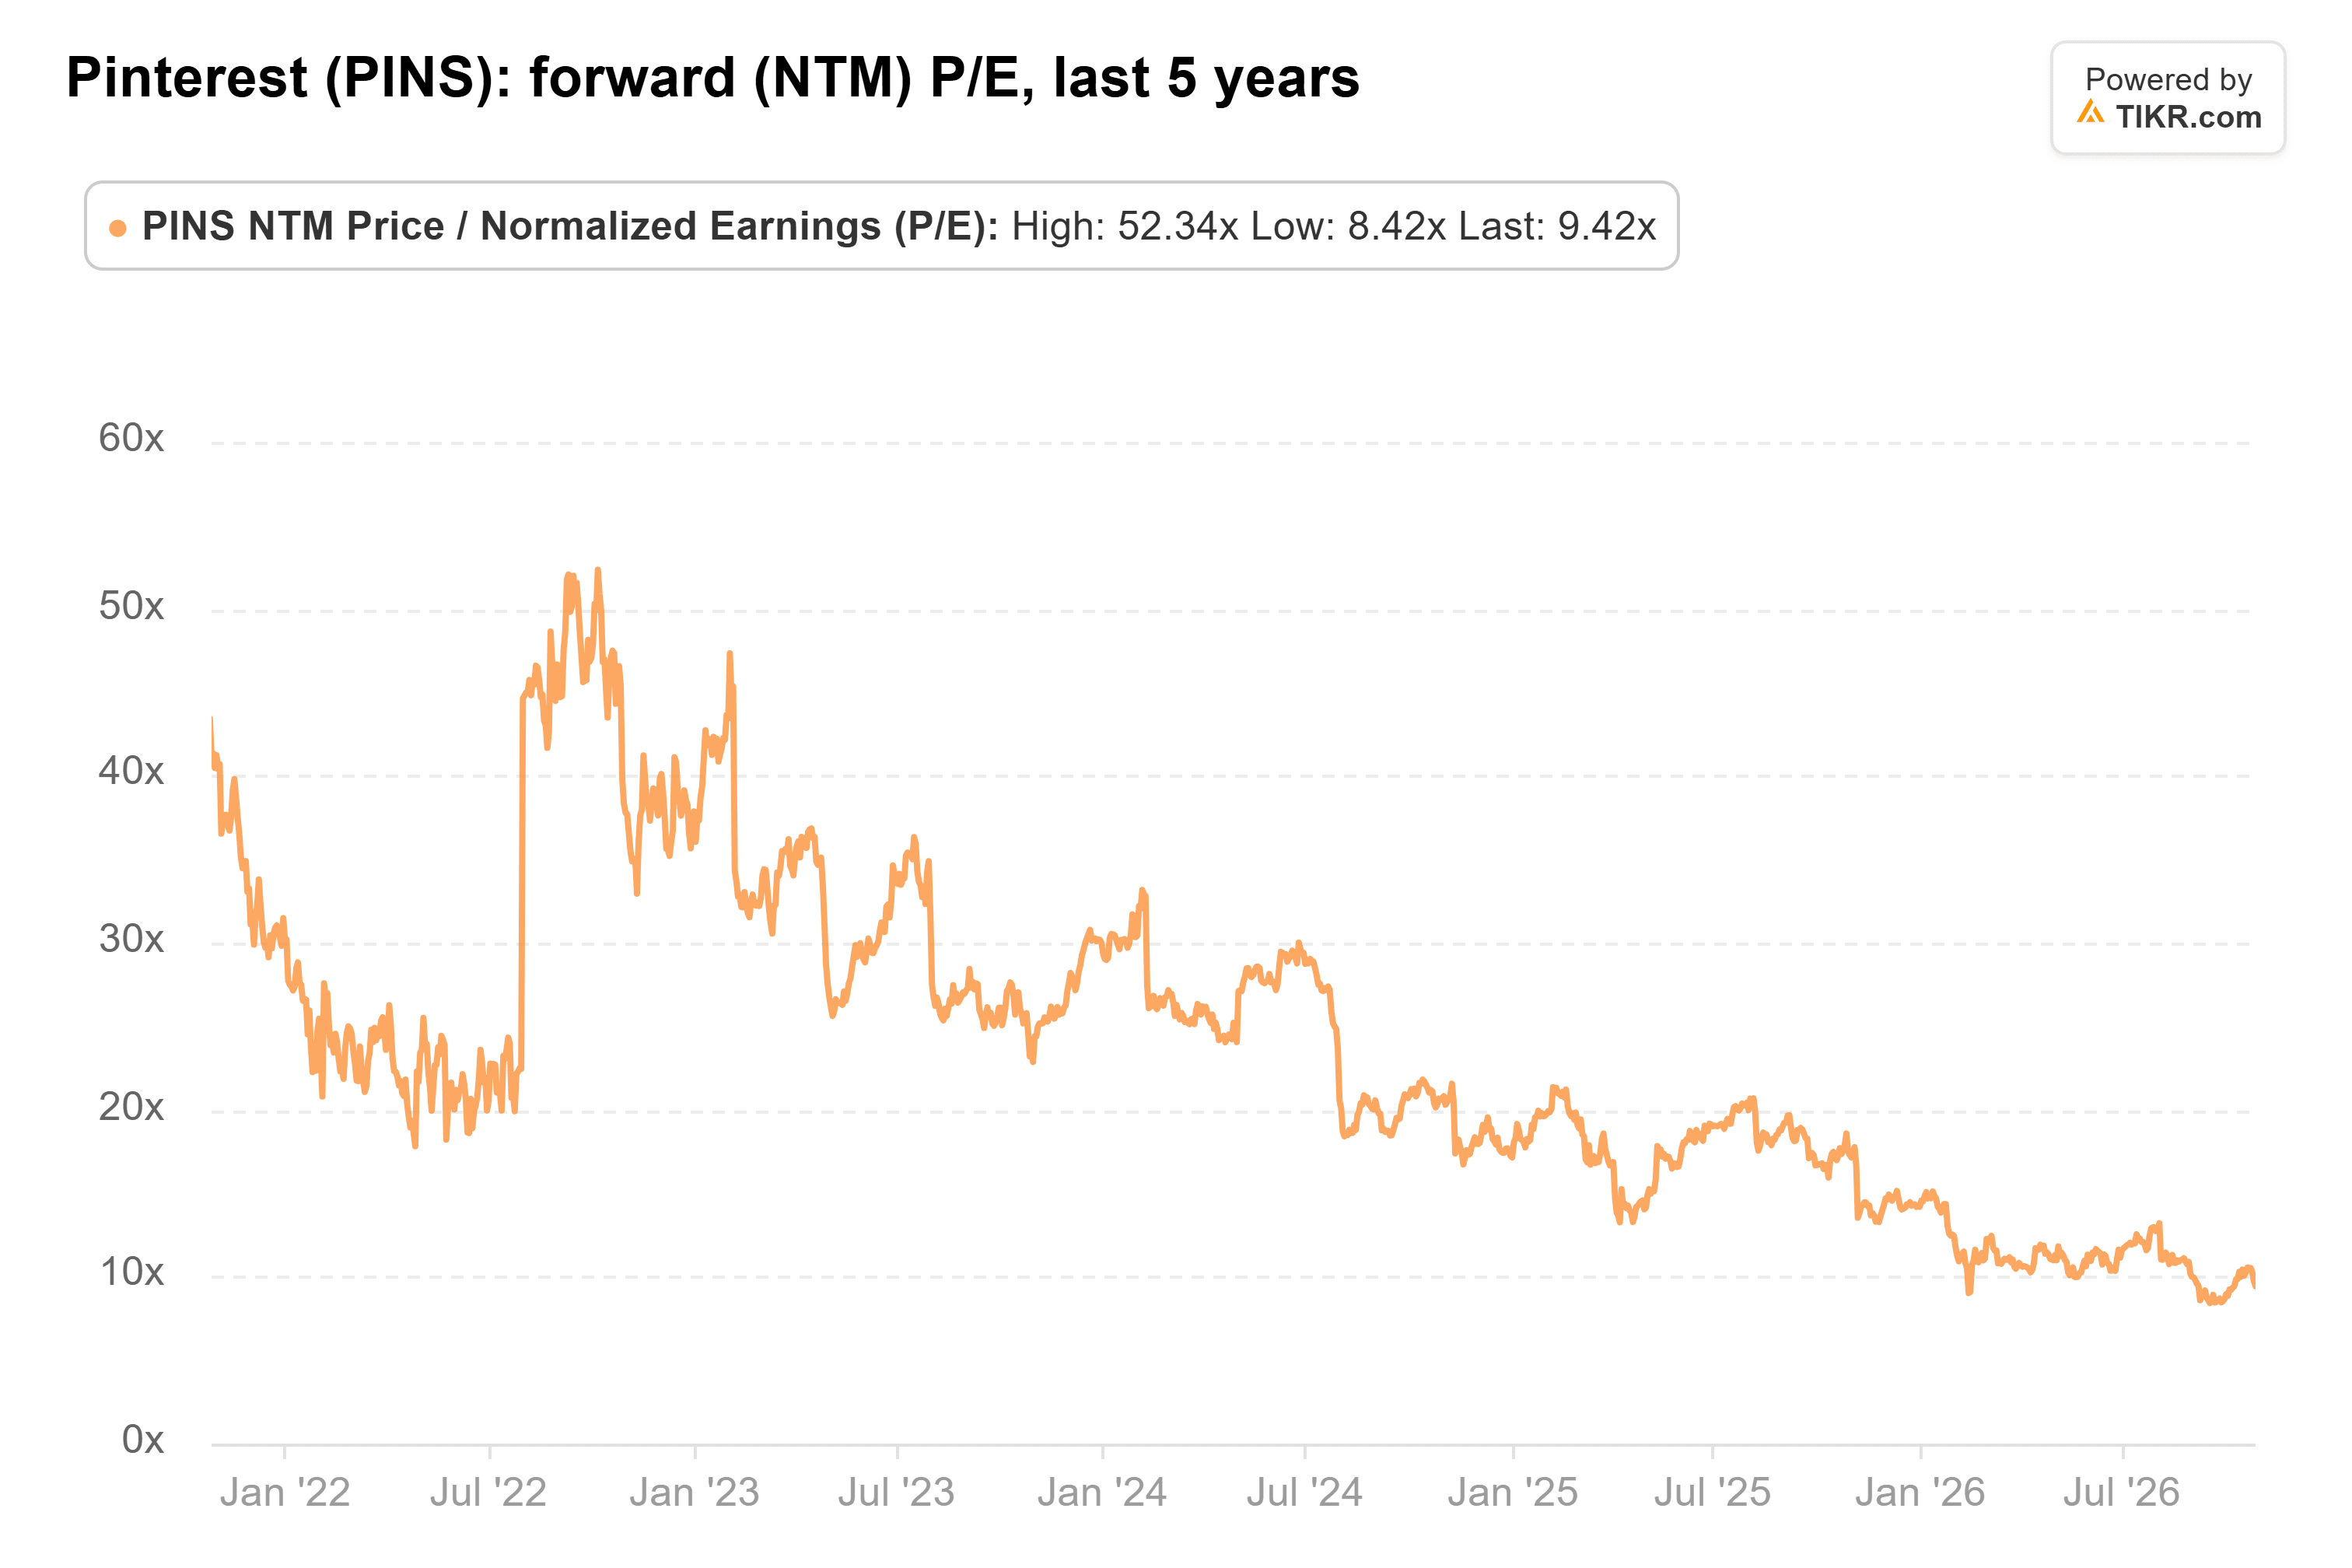
That compares with a five-year average of 24x. Pinterest paid an average of $30.79 a share for its 2025 buybacks. At around $21, the $1.95 billion left would retire more than 90 million shares. That’s roughly 16% of the shares outstanding at the end of June, and more than the 69.1 million unvested units waiting to vest.
The estimates count on it: analysts expect normalized EPS to grow about 19% a year through 2028 on net income growth of about 13%.
What Thursday has to show
Pinterest handed its finances to an Amazon Ads veteran on Monday, so Thursday is James Dibbo’s first call as CFO. Three numbers matter for the buyback:
- Free cash flow above the $318 million of a year earlier.
- Stock compensation clearly below the second quarter’s $324.5 million.
- Diluted shares below the second quarter’s 562.9 million, plus how much of the $1.95 billion went to work in the quarter.
Strong cash flow won’t save the stock from a weak fourth-quarter guide. Pinterest has fallen after four of its last five reports, and the biggest drops, 22% in November and 17% in February, came on revenue guides below consensus.
My take: at under 10x earnings, buying back stock is the best thing Pinterest can do with its cash, and its free cash flow can fund the rest of the program in a couple of years. But the buyback only shrinks the share count if stock pay falls. If Thursday’s stock comp stays near $324.5 million, much of what’s left just soaks up new grants.
Of course, one quarter won’t settle it: the 2027 outlook with fourth-quarter results in early February is the bigger test.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!