PepsiCo (PEP) beat Wall Street’s third-quarter estimates on Thursday, October 8, then cut its full-year profit outlook. Core EPS came in at $2.34 against the $2.30 analysts expected, and revenue of $25.27 billion topped the $24.97 billion consensus.
The stock went into the report near a 12-month low, trading at about $124, and rose more than 1% in premarket trading. The analyst call starts at 8:15 a.m. ET.
The Beat Came With a Lower Bar
PepsiCo now expects core constant-currency EPS to grow 1% to 2% this year, down from the low end of its prior 4% to 6% range. Including currency, core EPS growth guidance fell to 2.5% to 3.5%.
The pressure point is North American snacks. PepsiCo cut prices by up to 15% on brands including Lay’s and Doritos in February. Savory snack volume and share improved in Q3, but lower pricing left PepsiCo Foods North America (PFNA) revenue flat and its core operating profit down 12%.
Even the headline profit growth needed help. Core operating profit rose 3%, and tariff refunds contributed 4 points of that.
CEO Ramon Laguarta said the company is “acting with urgency to sustainably improve our performance in North America,” and flagged more structural cost cuts in the coming months.
PepsiCo’s Snack Margin Was Shrinking Before February
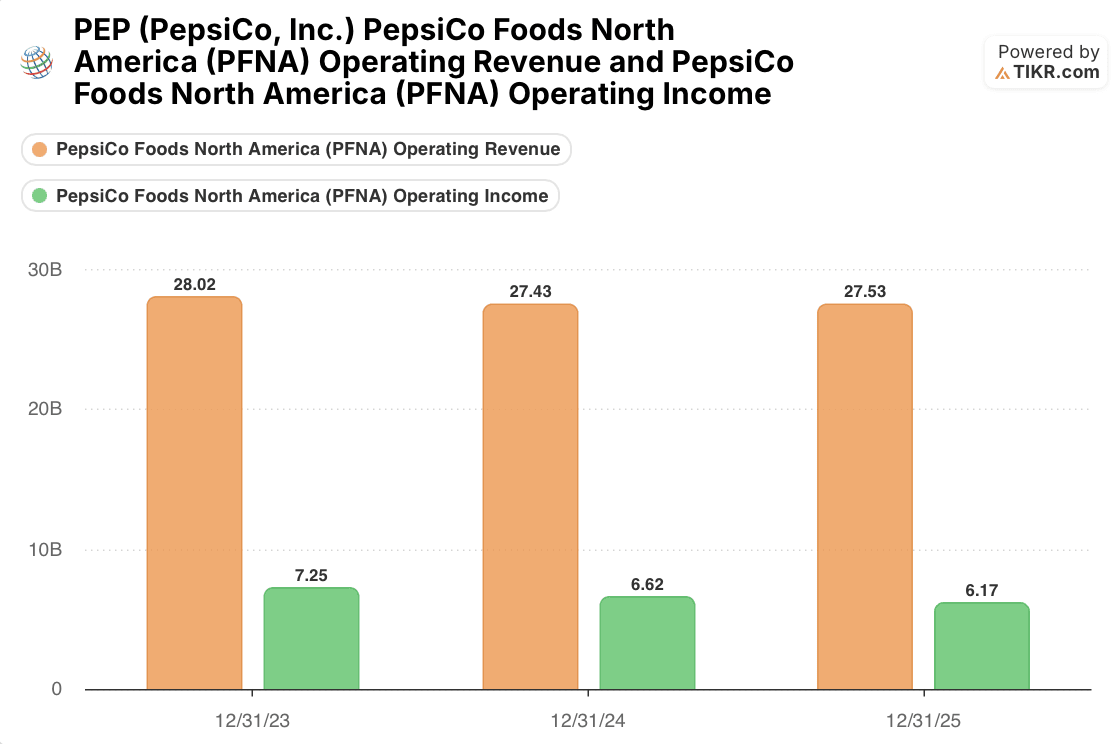
The Q3 drop extends a longer slide. PFNA’s operating income fell from $7.25 billion in 2023 to $6.17 billion in 2025, down about 15%, while revenue barely moved ($28.02 billion to $27.53 billion). Its operating margin went from 25.9% to 22.4% in two years.

That’s why the guidance cut lands hard. Analysts expected 2026 EPS of $8.55, about 5% growth on 2025’s $8.14. The new 2.5% to 3.5% range implies roughly $8.34 to $8.42, or about 1.5% to 2.5% below consensus. Expect those estimates to come down this week.
Isn’t This Already in the Price?

Mostly, yes. PepsiCo trades at 14.28x forward earnings, the lowest reading in five years and about 32% below its five-year average of 21.01x.
The 14.28x multiple uses next-12-month earnings estimates. At about $124, PepsiCo trades at roughly 14.8x the $8.38 implied by the midpoint of its revised 2026 guidance.
What’s new is the repair work. PepsiCo plans to raise some chip prices by a low- to mid-single-digit percentage, while keeping them below pre-cut levels, as we covered last month. The increases were reported to take effect in late 2026 or early 2027. International is carrying the rest: core constant-currency operating profit rose 9% to 19% across all four international segments.
The Question PepsiCo Still Has to Answer
The open question is whether the snack volume PepsiCo bought in February survives those price increases. If shoppers stay, PFNA margins can rebuild from 22.4% with pricing and the new cost cuts. If volume slips back, PepsiCo will have given up margin for share it couldn’t keep, and the 2027 estimate of $8.91 looks too high.
My view: the guidance cut resets expectations to a level PepsiCo can clear, and at about 14x earnings the stock already prices in a weak year. Snack rivals such as Mondelez (MDLZ) face the same choice between shelf share and margin. The fourth-quarter report gives the first read, but the real test is PFNA volume once the higher chip prices are on shelves in 2027.
So what is PepsiCo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PEP stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!