Key Takeaways
- PDD Holdings stock jumped 9% after third-quarter adjusted earnings beat estimates, though revenue missed.
- PDD’s ad revenue grew 12%, while Alibaba’s merchant fees fell 5% and JD.com cut its marketing spend.
- Transaction services, which include Temu, fell 12% under Europe’s new parcel duty.
- At about 7x forward earnings, PDD needs no higher multiple to reach analyst targets of $93 or more.
PDD Holdings (PDD) stock is up 9% today after the Temu owner’s third-quarter earnings beat forecasts. Non-GAAP earnings per ADS were RMB21.04, against the RMB18.54 analysts expected. Alibaba (BABA) reported the same morning, and JD.com (JD) two days earlier, so we can see who’s winning merchants.
Revenue was flat at RMB108.3 billion, short of the RMB115.2 billion analysts wanted. Blame transaction services, which include Temu’s fulfillment fees: they fell 12% to RMB48.5 billion in the first full quarter of the EU’s €3 duty on low-value parcels.
The ads are back
Online marketing, PDD’s ad revenue, grew 12% to RMB59.8 billion, after 3% in the second quarter. Sales and marketing expenses fell to RMB25.3 billion from RMB30.3 billion, lifting GAAP operating profit about 24% to RMB31.2 billion.
Alibaba can’t say the same. Its customer management revenue, what it earns from Taobao and Tmall merchants, fell 5% in the September quarter, and grew just 1% on a like-for-like basis. On ad budgets, PDD is winning this round.
JD.com cut back too: CEO Sandy Xu cited “a notable year-on-year reduction in marketing expenses.” But its 1.7% operating margin, against roughly 29% at PDD, shows how much more PDD keeps from each yuan of sales.
TIKR tracks 35 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
Still cheap at about 7x
Analysts expected earnings to grow again from 2027:
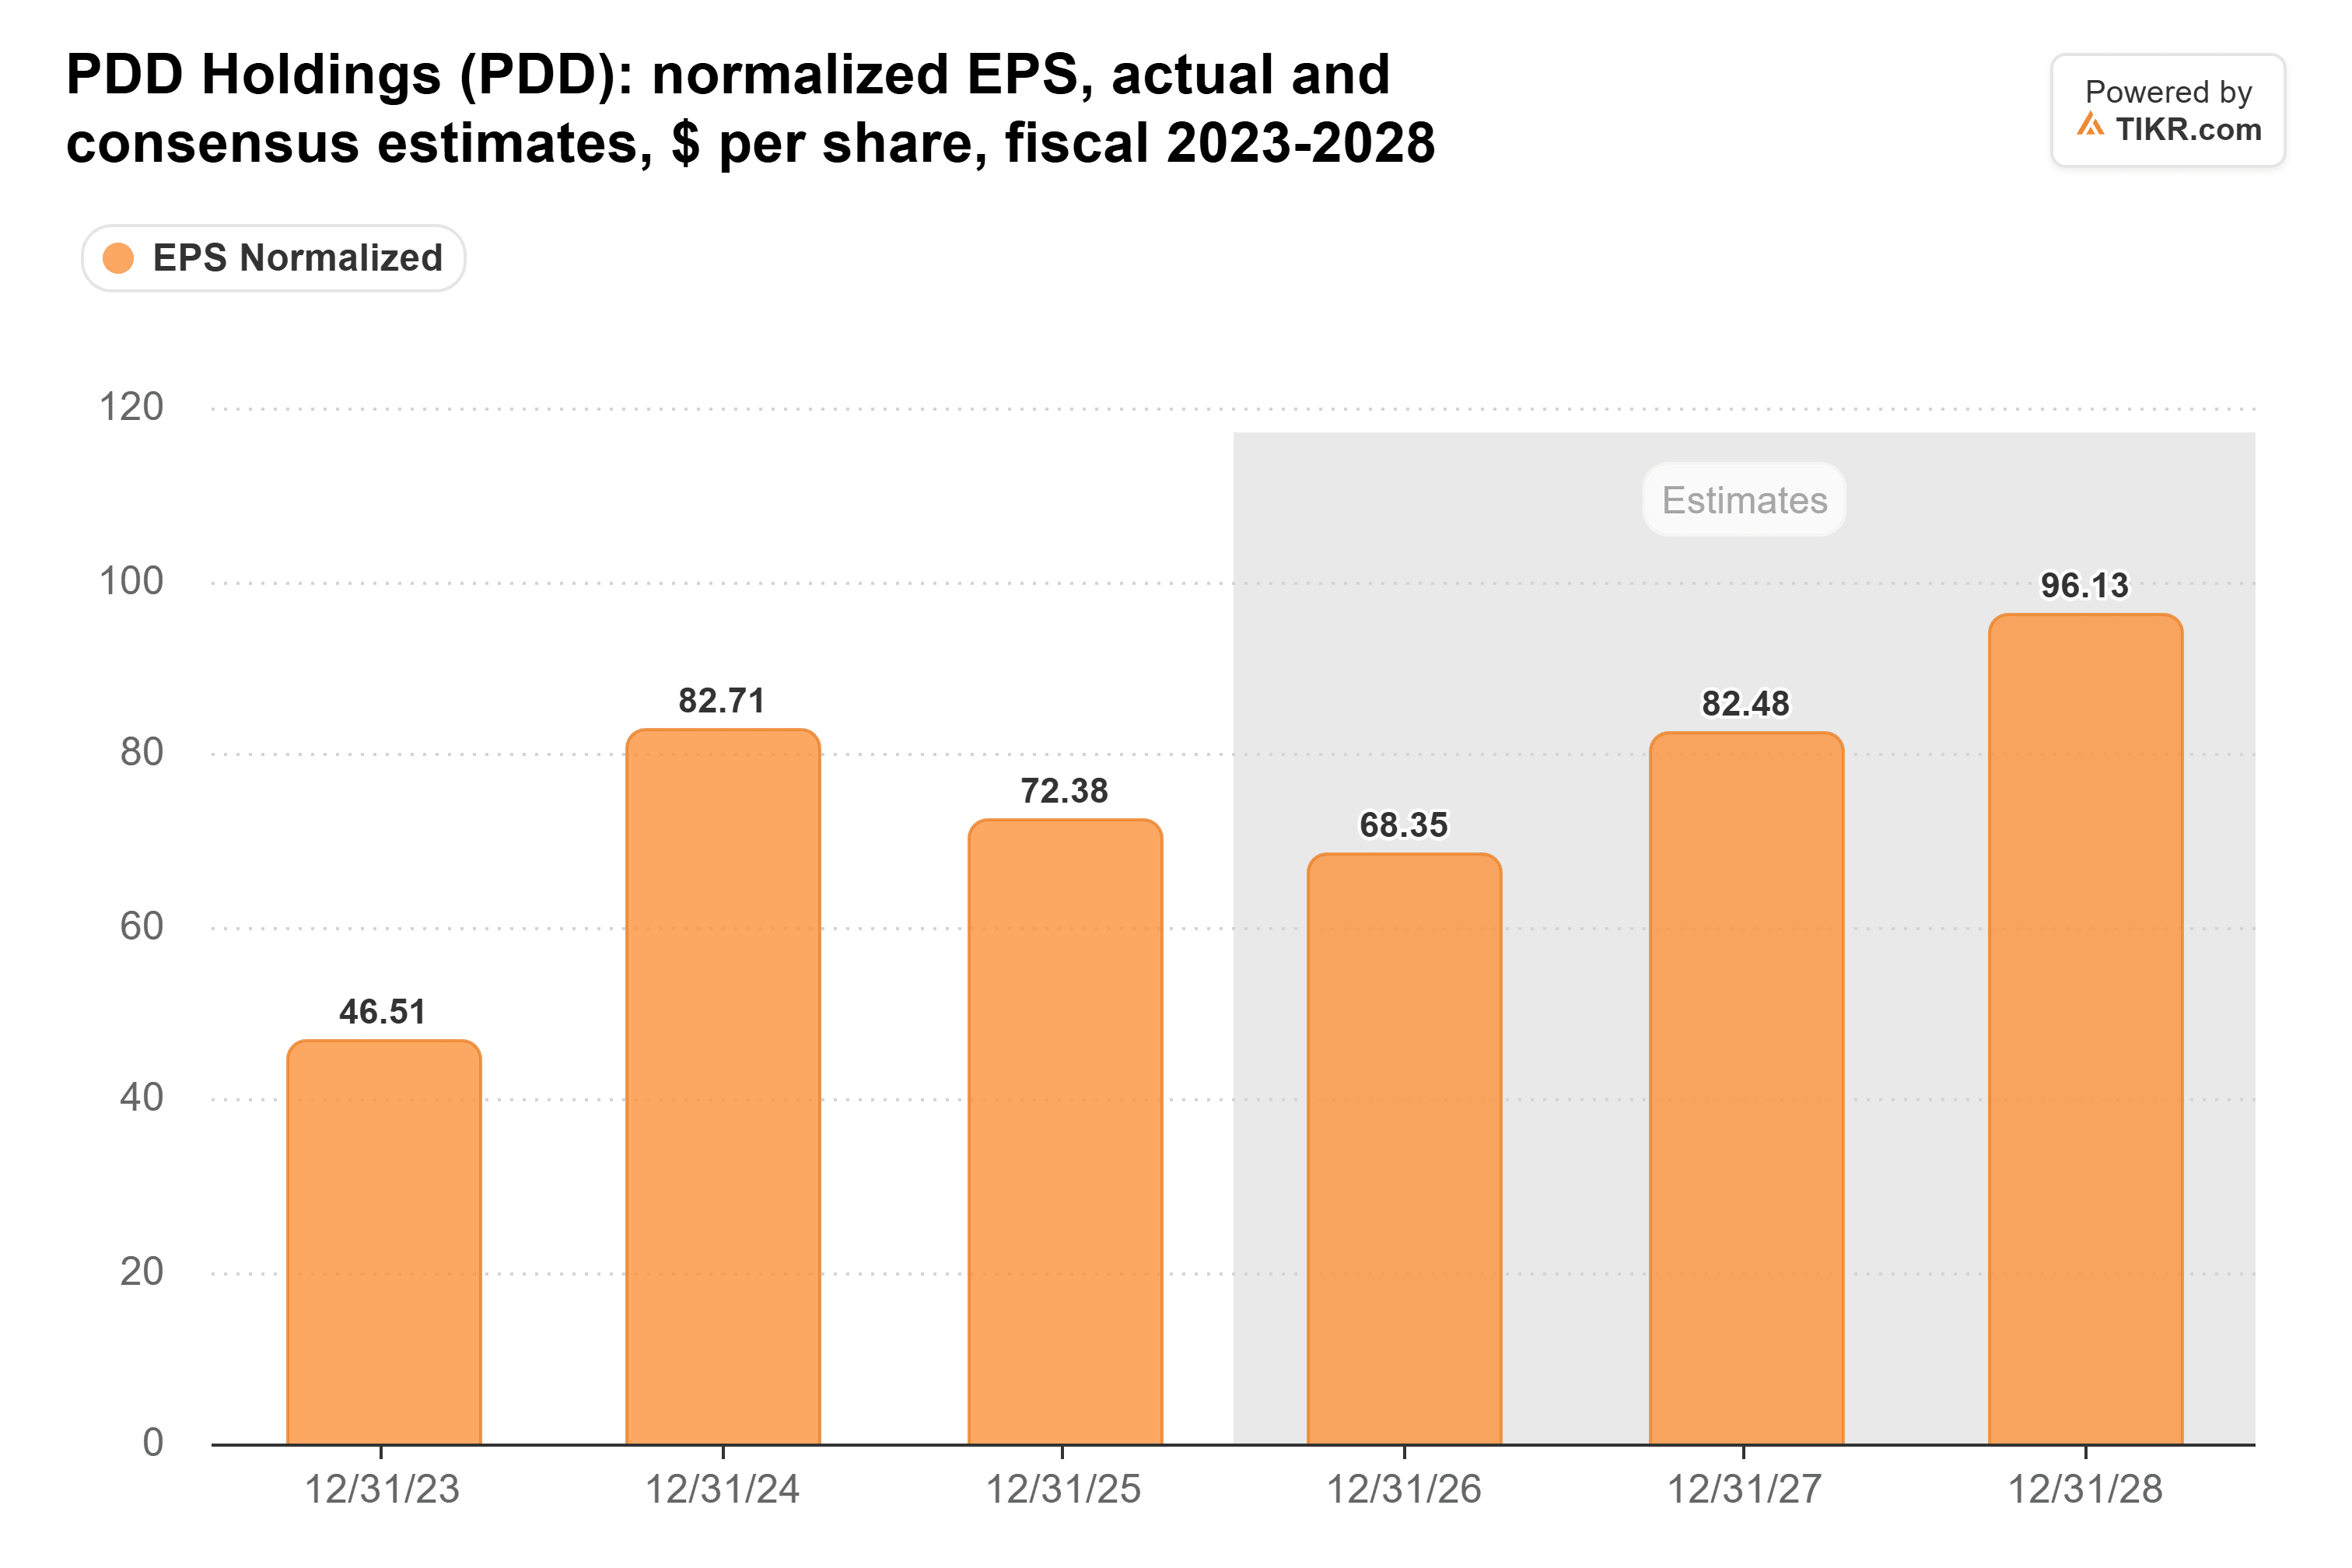
After three quarters, PDD has earned RMB49.86 of non-GAAP EPS per ADS. To hit the RMB68.35 consensus for 2026, it needs only about RMB18.5 from the fourth quarter, a bit above last year’s RMB17.69, and today’s beat should push that estimate up.
Yet the stock traded at 6.8x forward earnings at the last close, just above its five-year low of 6.6x, and today’s jump only takes it to about 7x:
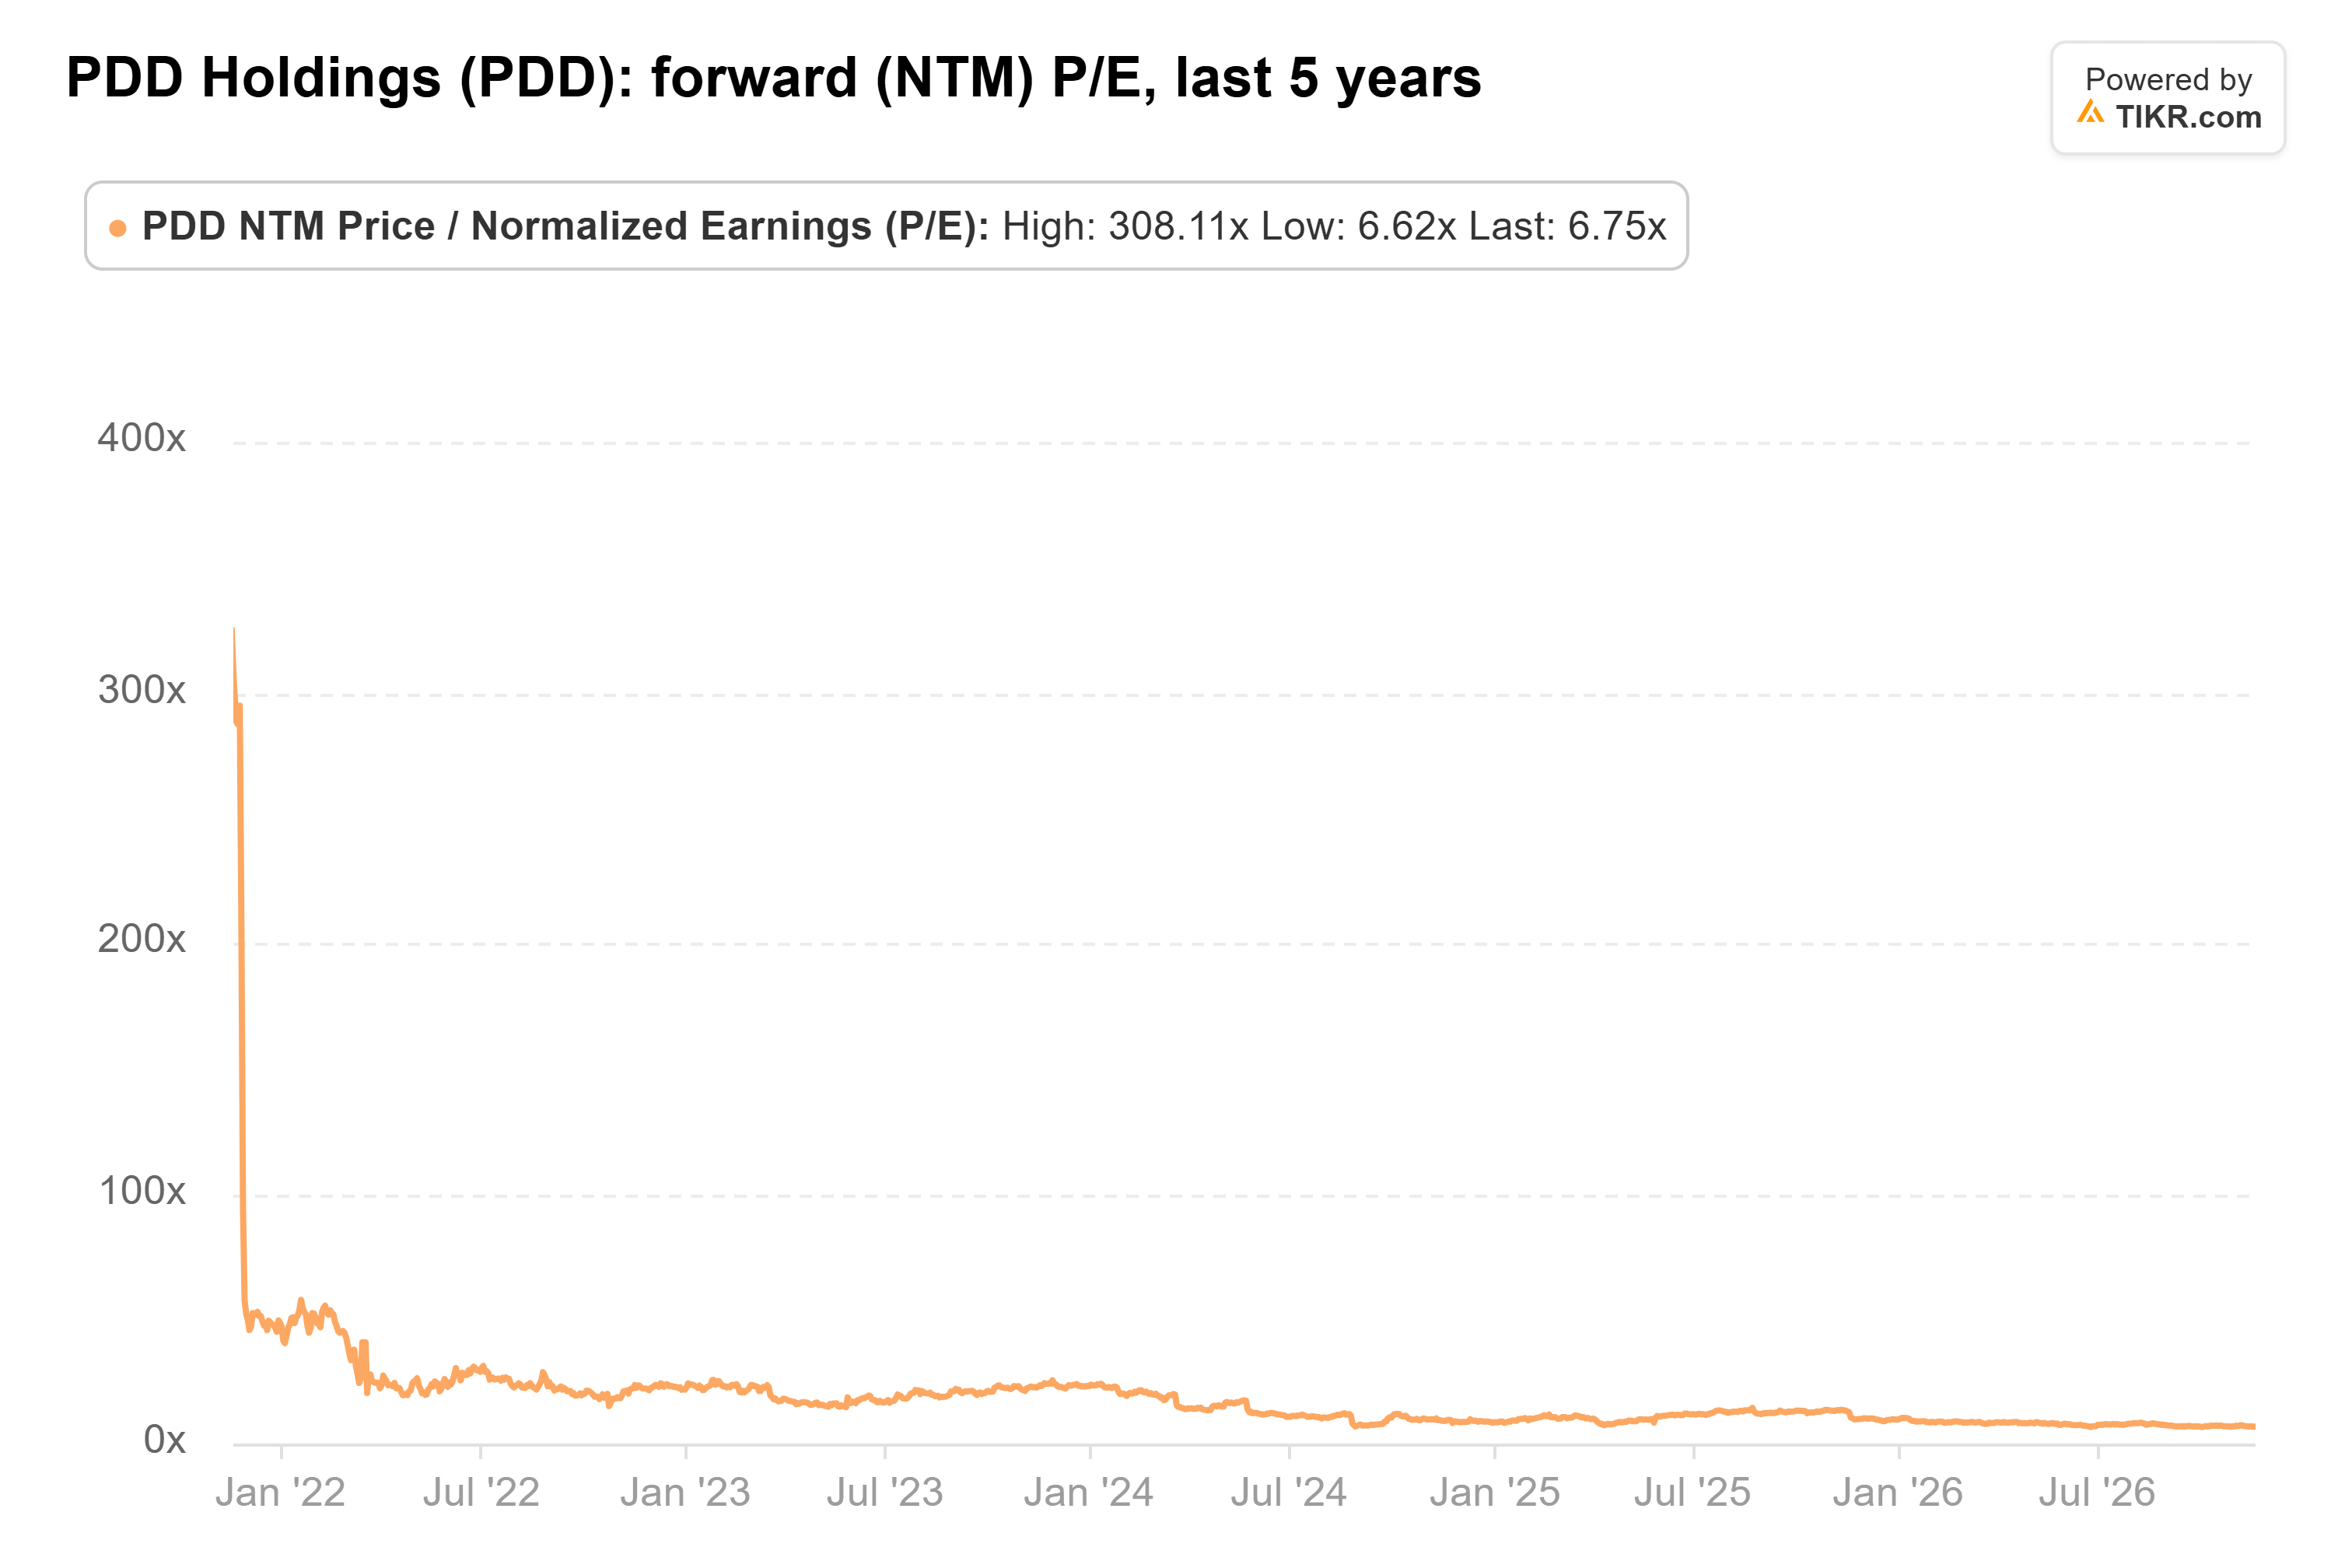
The latest analyst targets all sit at $93 or higher, 20% above the last close. On my math, $93 is about 6.5x 2028 estimates, so it needs no re-rating, just for the estimates to hold.
The way I see it, those targets look conservative, as long as Temu’s slide doesn’t drag estimates down. The fourth-quarter report, likely in March, needs non-GAAP EPS above that RMB18.5 bar and transaction services to stop shrinking.
So what is PDD Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!