

Key Takeaways
- Palo Alto Networks shares jumped 6% after revenue grew 39% and the company raised its full-year outlook.
- CrowdStrike, Cloudflare, Fortinet and Okta rose with it.
- Adjusted EPS grew just 13% as the share count rose 18% after stock-funded deals.
- Demand looks strong, but per-share profit now has to catch up with revenue.
Palo Alto Networks (PANW) is up 6% today after a record fiscal first quarter, a higher outlook and a $4.5 billion all-stock deal for AI startup Applied Compute.
The rest of cybersecurity came along: CrowdStrike (CRWD) is up 6% and Cloudflare (NET) is up 5%, and Fortinet (FTNT) and Okta (OKTA) rose too.
A big beat
Revenue rose 39% to $3.44 billion in the quarter to Oct. 31, beating the $3.31 billion consensus. CEO Nikesh Arora said customers “turn to us to protect them against an unprecedented threat environment.”
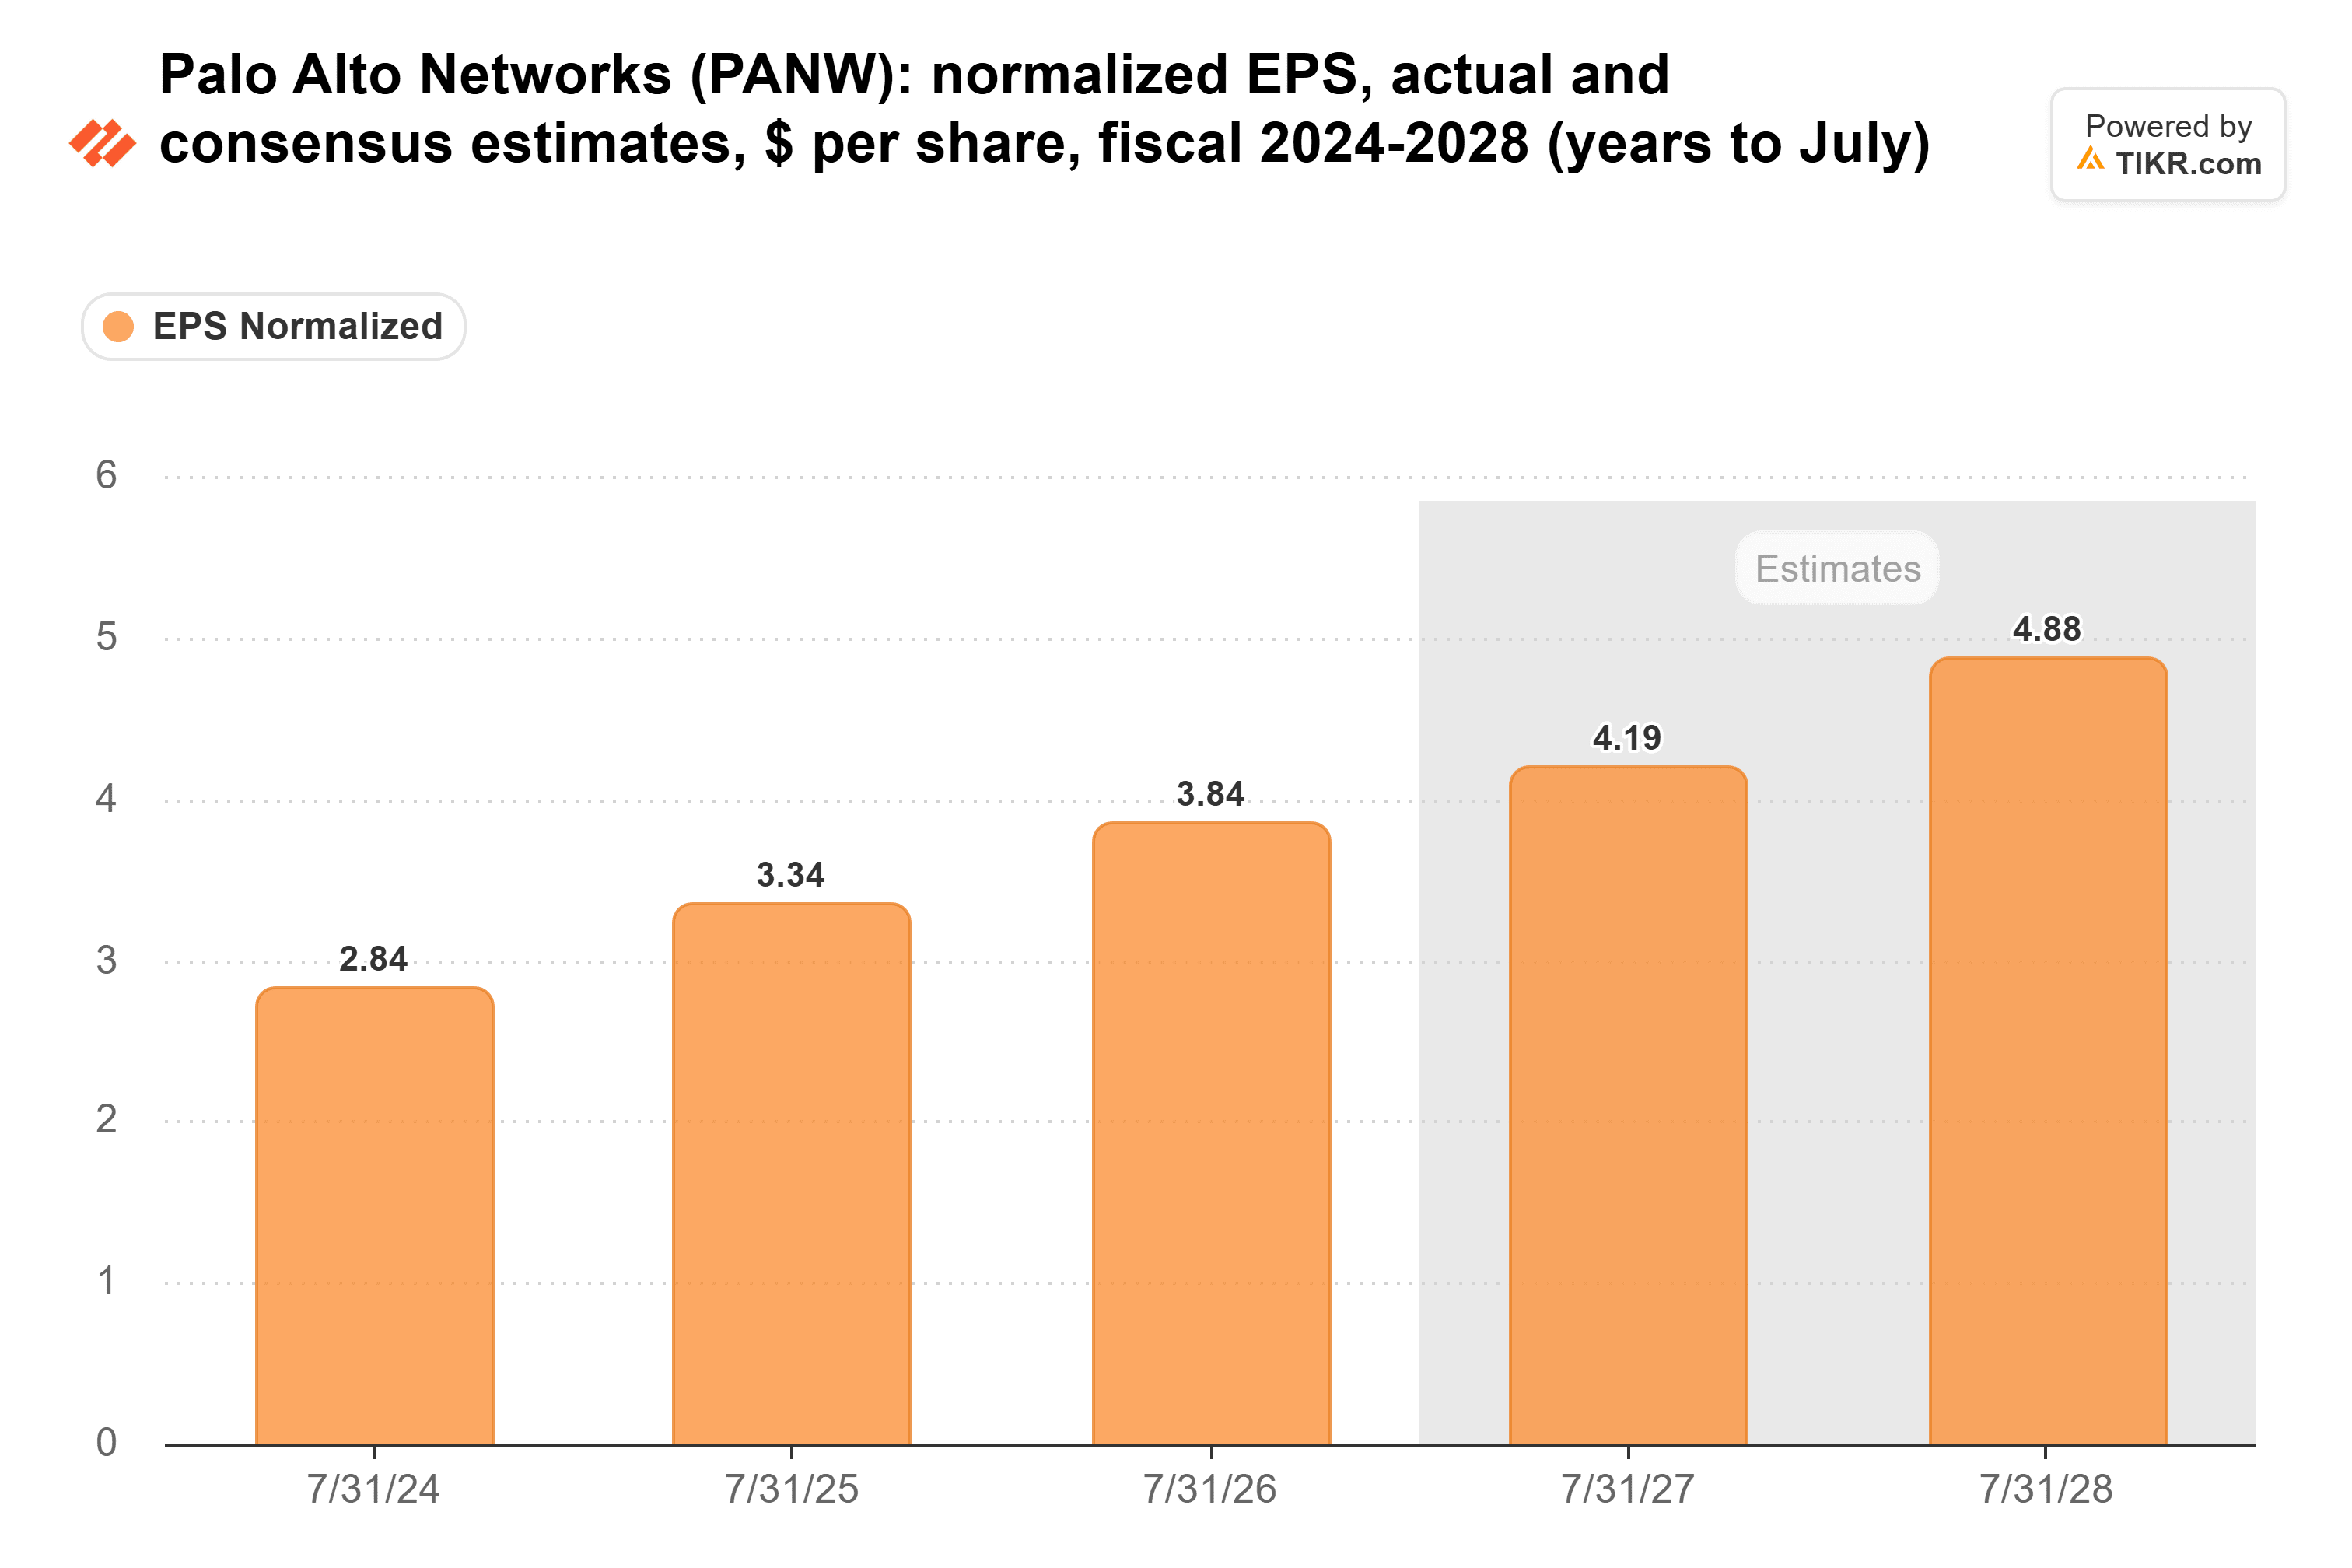
Management raised its fiscal 2027 adjusted EPS guidance to $4.26-$4.30 from $4.16-$4.19, above the $4.19 analysts expected going in:
Rivals get a lift
Fortinet, up 4%, gives the clearest read on firewalls. Its product revenue grew 37% in the quarter to Sept. 30, down from 52% the quarter before, and Palo Alto’s product revenue also grew 37%, to $595 million. To me, that looks like spending lifting the whole group.
Okta, up 7%, is the test for identity, where Palo Alto now competes through CyberArk. Okta reports in early December, and current RPO growth above its 11%-12% guide would show that threat environment reaching identity too.
CrowdStrike and Cloudflare have no news of their own, so their moves are a bet that Palo Alto’s demand is the group’s.
TIKR tracks 55 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
The catch is the share count
The 39% includes CyberArk and Chronosphere, deals Palo Alto paid for mostly in stock. Diluted shares rose 18% from a year ago to 837 million, so adjusted net income grew 33% while adjusted EPS grew 13%. Applied Compute adds more stock, though it’s less than 2% of Palo Alto’s market value.
After a nearly 30% slide from its highs, Palo Alto traded at 81x forward earnings at the last close. That’s down from 101x in August but well above its five-year average of 57x:
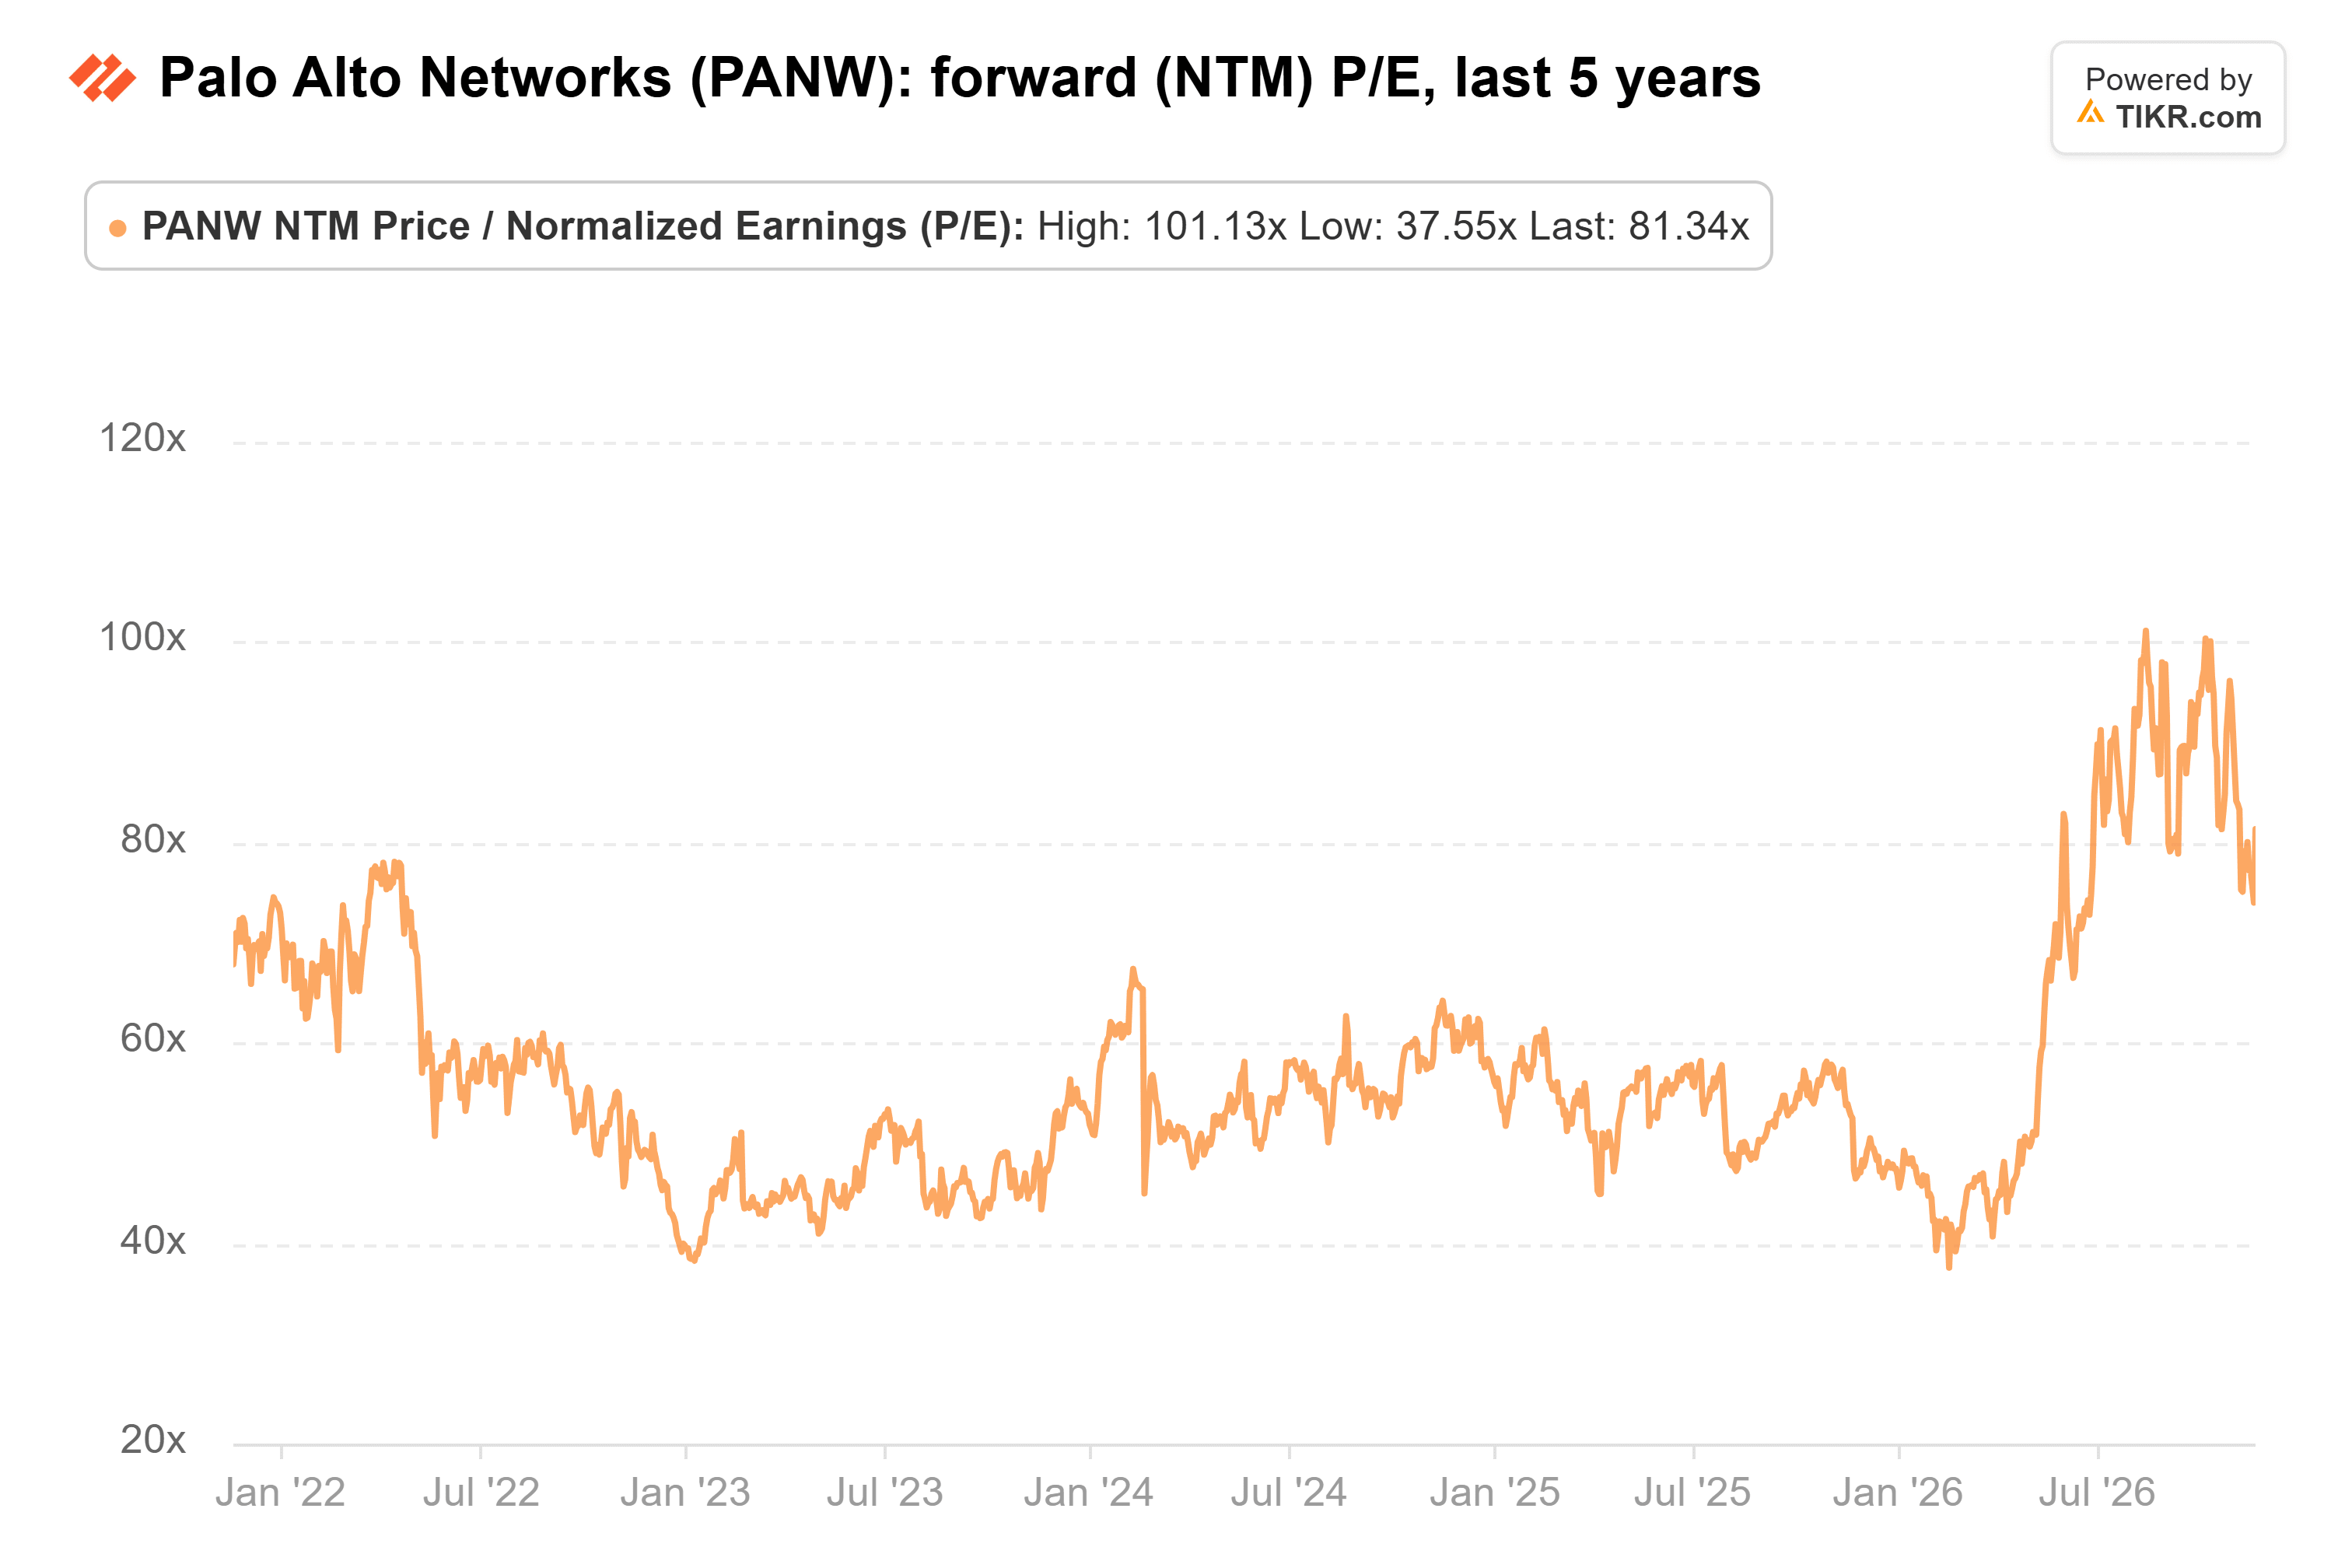
(At today’s price, it’s even higher.)
The way I see it, a beat this size settles the demand question, but the stock needs per-share profit to grow much faster than 13%. The next test comes with fiscal second-quarter results, likely in mid-February. Management guides to revenue of $3.53-$3.55 billion, above the $3.42 billion analysts expected, on 837-842 million shares.
So what is Palo Alto Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Palo Alto Networks for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


