Key Takeaways
- UnitedHealth Group (UNH) fell 14% in a week after CMS proposed a rule to widen Medicare Advantage audits.
- Humana (HUM), far more exposed to Medicare Advantage, and CVS Health (CVS) sold off on the same rule.
- CMS estimates the audits would recover about $9 billion per payment year industry-wide.
- The drop looks bigger than the rule’s likely cost to UnitedHealth, and the 2027 outlook due before year-end is the next test.
UnitedHealth Group stock is down 14% in the past week, mostly on a proposed Medicare rule.
On Nov. 16, the Centers for Medicare & Medicaid Services proposed CRUSH, an anti-fraud rule aimed largely at Medicare Advantage.
UnitedHealth is the program’s largest insurer, so it led the selling, and Humana and CVS Health went down with it.
The audit rule has teeth
CMS would extrapolate coding errors from a sample of charts across a whole contract, back to payment year 2018. It estimates that would recover about $9 billion per payment year industry-wide.
UnitedHealth hasn’t sized its share. Insurers have beaten this before: a Texas judge vacated CMS’s 2023 version in September 2025 after Humana sued.
This one is a proposal, open for comment until Jan. 19, 2027.
Humana has more at stake. Medicare Advantage brought in $31.4 billion of the $38.7 billion of premiums its insurance business collected in Q3, while premiums from CMS were more than 44% of UnitedHealth’s 2025 revenue.
On Wednesday, Sen. Elizabeth Warren renewed her call to break up CVS, UnitedHealth and Cigna.
CVS’s Aetna-run Health Care Benefits segment had nearly tripled Q3 adjusted operating income to $912 million.
TIKR tracks 26 analysts on UnitedHealth. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on UnitedHealth, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See UnitedHealth’s Analyst Ratings.
Priced for more damage than CMS has spelled out
The business was healing before this. In Q3, UnitedHealth’s medical care ratio fell to 88.4% from 89.9%.
Management raised its 2026 adjusted EPS outlook to at least $20.50 from $19.50-$20.00. Consensus has normalized EPS rising from $16.35 in 2025 to $23.33 in 2027:
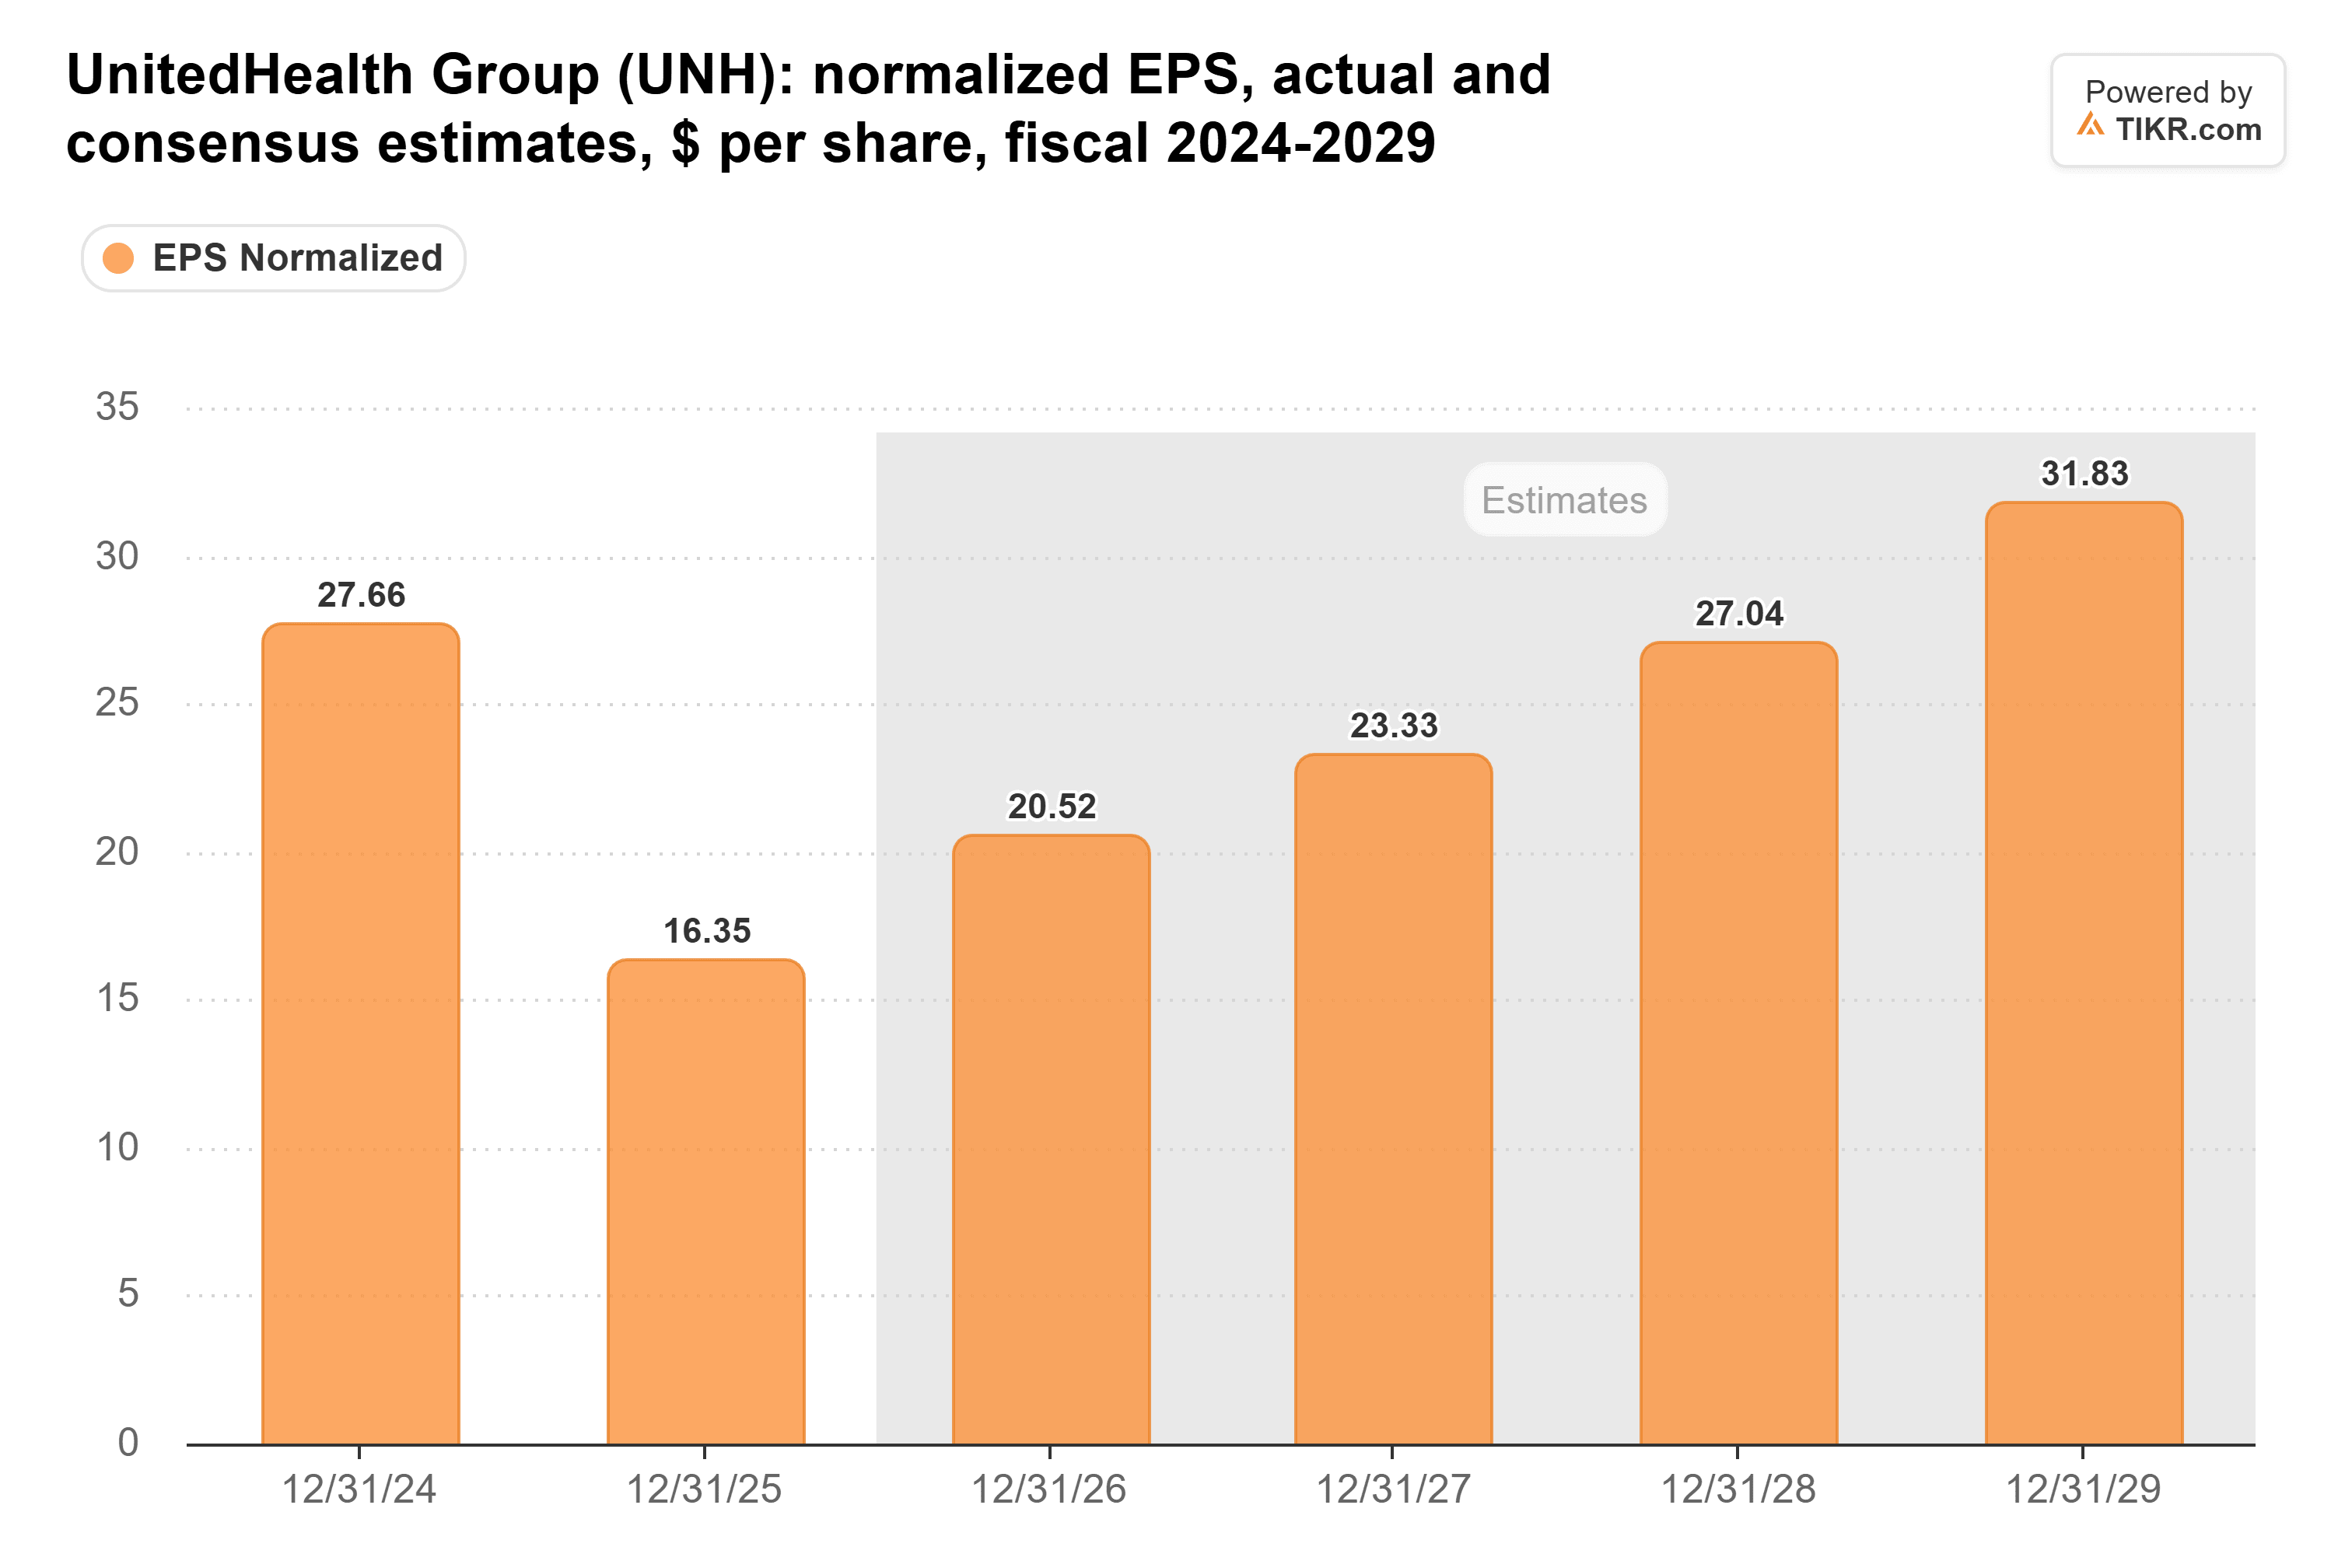
Those estimates came before the proposal. The stock traded at 17x forward earnings before Wednesday’s drop, below its five-year average of 19x:
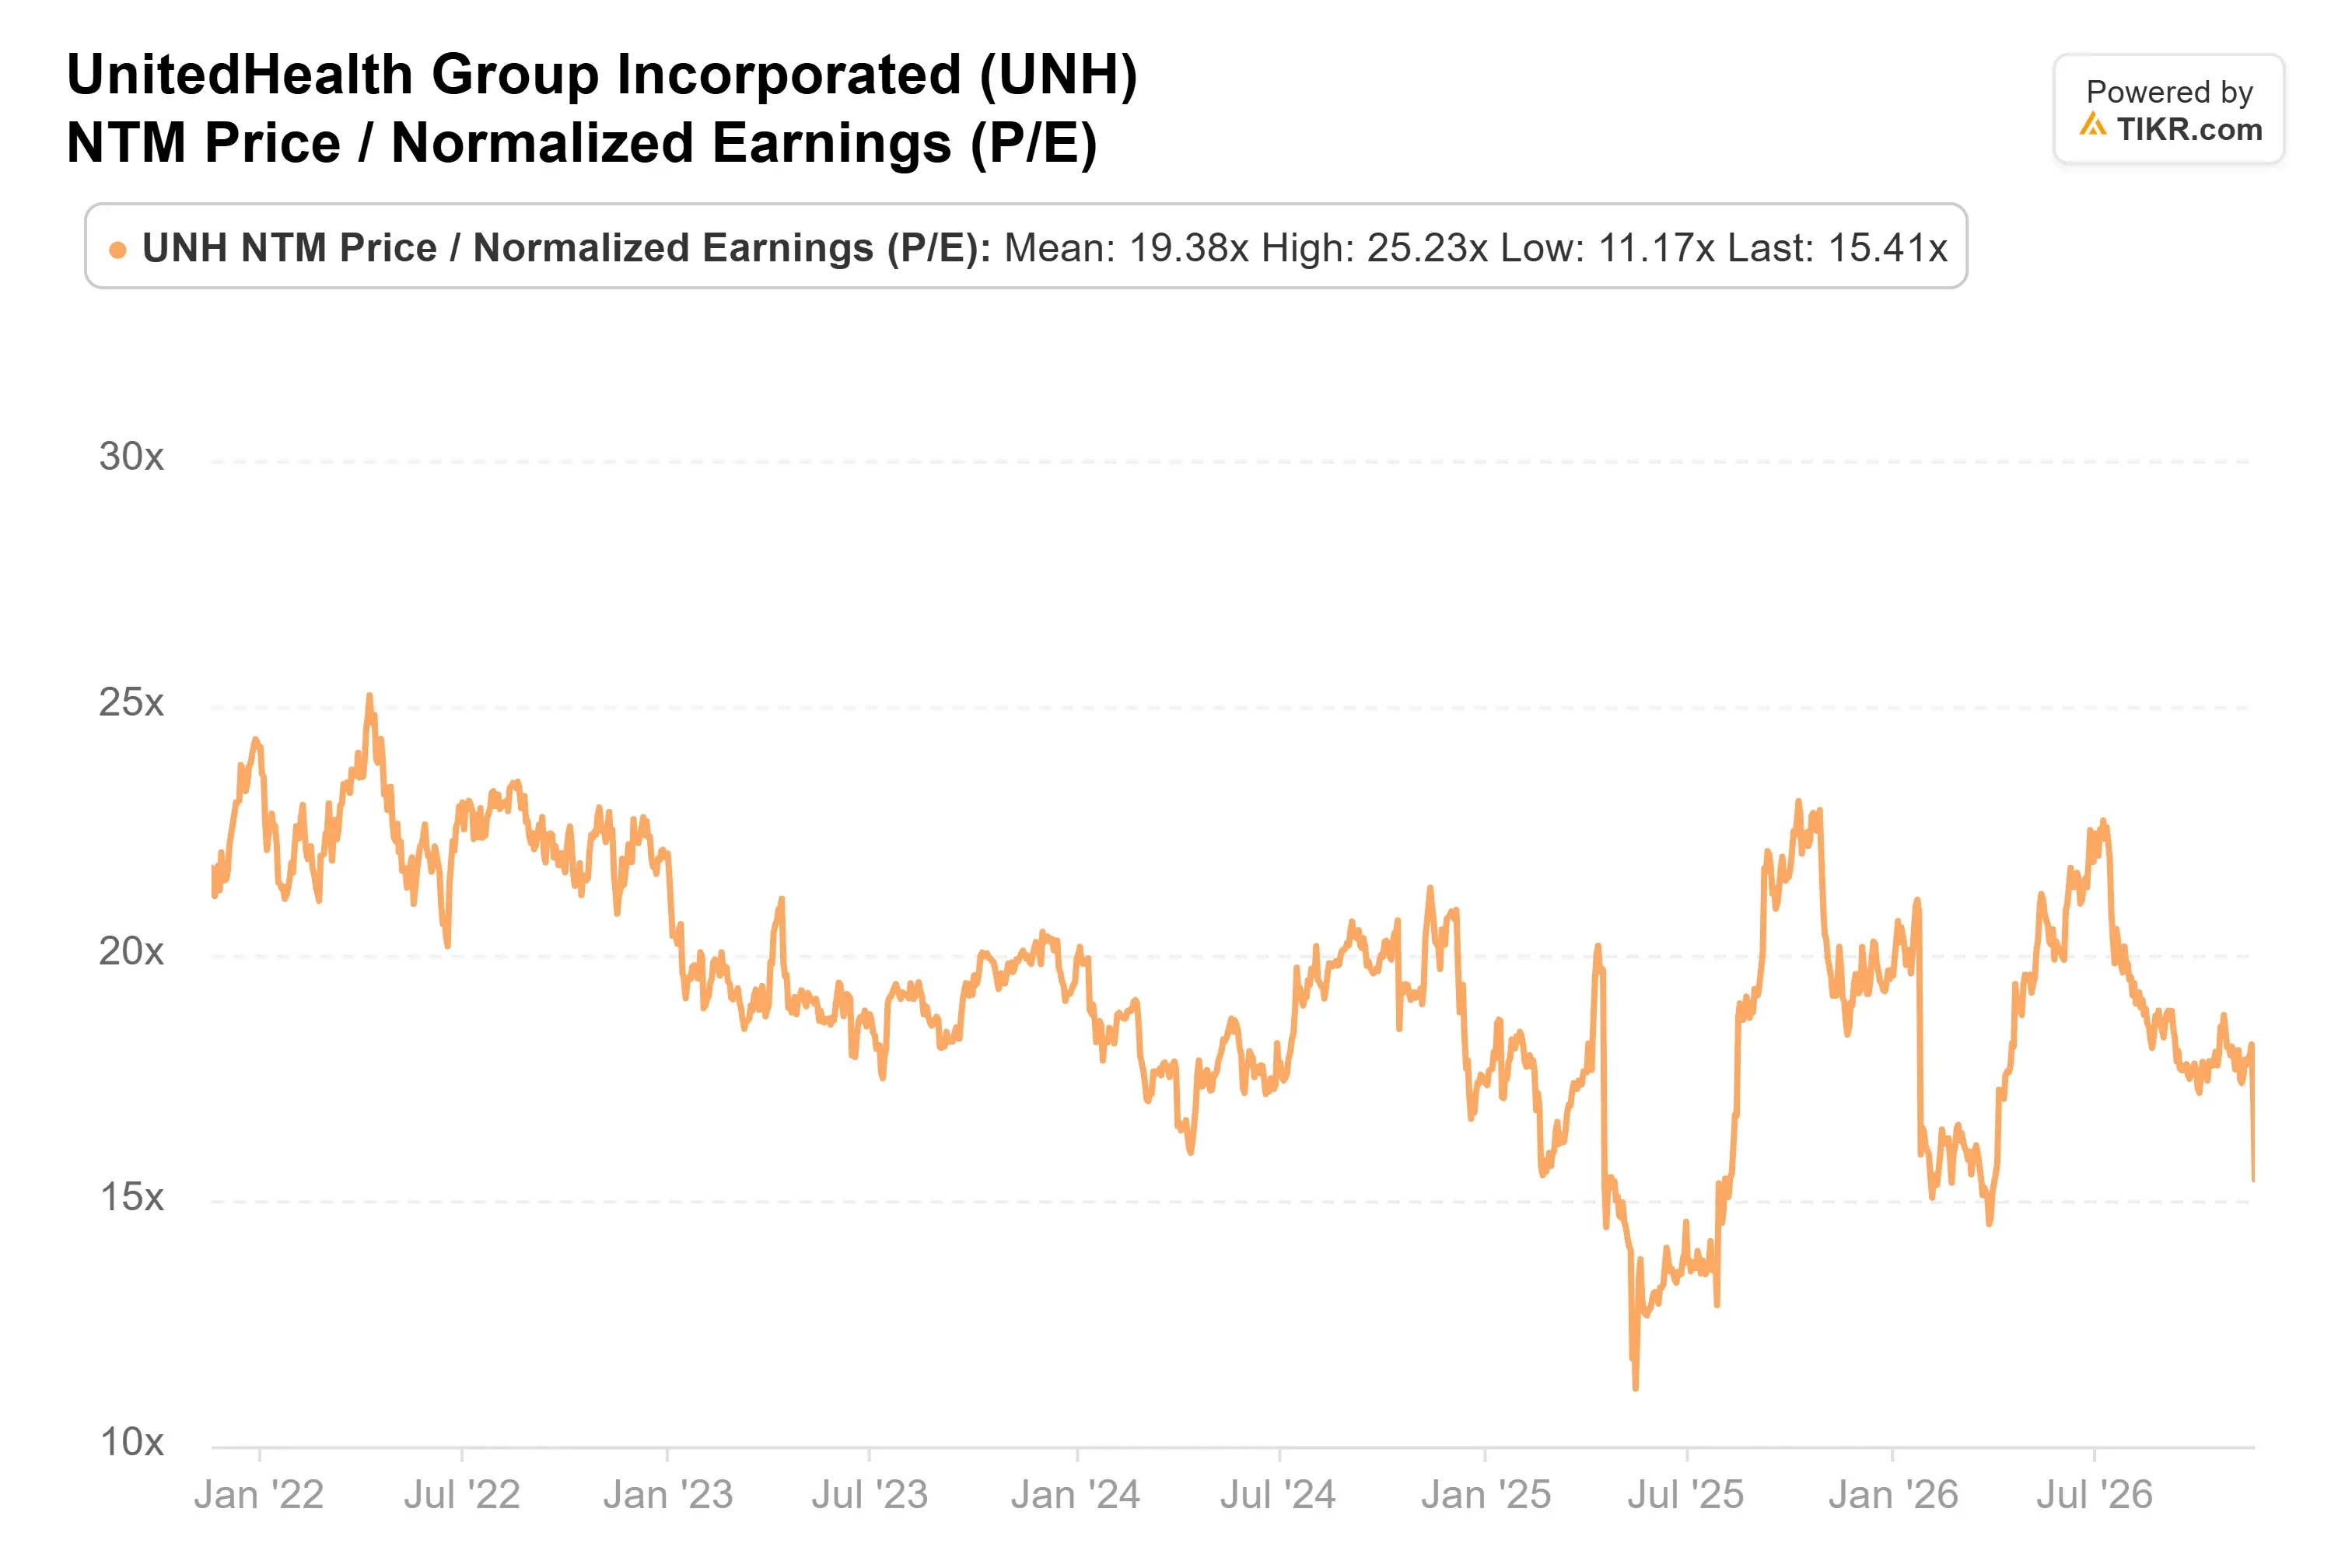
After Wednesday, it’s closer to 15x. UnitedHealth lost about $50 billion of market value in the week, and CMS’s yearly estimate covers every Medicare Advantage insurer.
Bottom line: I’d lean toward loading up, but I’d keep the position small in case the clawback is bigger than I expect. The test is the 2027 outlook management has promised before year-end.
If management guides to at least $23.17 (13% growth on $20.50) and puts a manageable number on CRUSH, the recovery looks intact.
So what is UnitedHealth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what UnitedHealth could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!