Key Takeaways
- PDD Holdings reports third-quarter results on November 19 after second-quarter revenue rose 8% while net income fell 12% to RMB27.2 billion.
- Transaction services grew 13%, but online marketing revenue rose just 3.5%, so the domestic ad engine has nearly stalled.
- Operating expenses rose 13% as PDD stepped up merchant support, and Temu faces a new €3 EU parcel duty plus ongoing regulatory scrutiny.
- Thursday’s report will show whether Temu absorbed its first full quarter of the duty and how far net income lands from last year’s RMB29.3 billion.
PDD Holdings (PDD) reports third-quarter results before the US market opens on Thursday, November 19. The setup looks familiar: solid profit, slowing growth and rising costs.
In August, revenue rose 8% to RMB112.4 billion, but net income fell 12% to RMB27.2 billion. Heavier spending on merchants and on compliance did most of the damage.
JD.com (JD) goes first, on November 17. That gives investors a fresh read on Chinese shoppers, although the two companies look nothing alike on profit. JD’s second-quarter net margin was 2.1%, while PDD’s was 24.2%.
Marketing growth nearly stalled
PDD’s last report showed strong profit and soft growth. Three numbers stood out:
- Transaction services revenue rose 13% to RMB54.7 billion.
- Online marketing services and other revenue grew just 3.5% to RMB57.6 billion.
- Non-GAAP earnings per ADS fell to RMB19.33 ($2.85) from RMB22.07.
A RMB7.4 billion non-operating loss also weighed on net income. One year earlier, that line showed a small gain.
The mix matters because the slower piece is the bigger one. Marketing still made up just over half of second-quarter revenue, so its slow growth drags on the total…
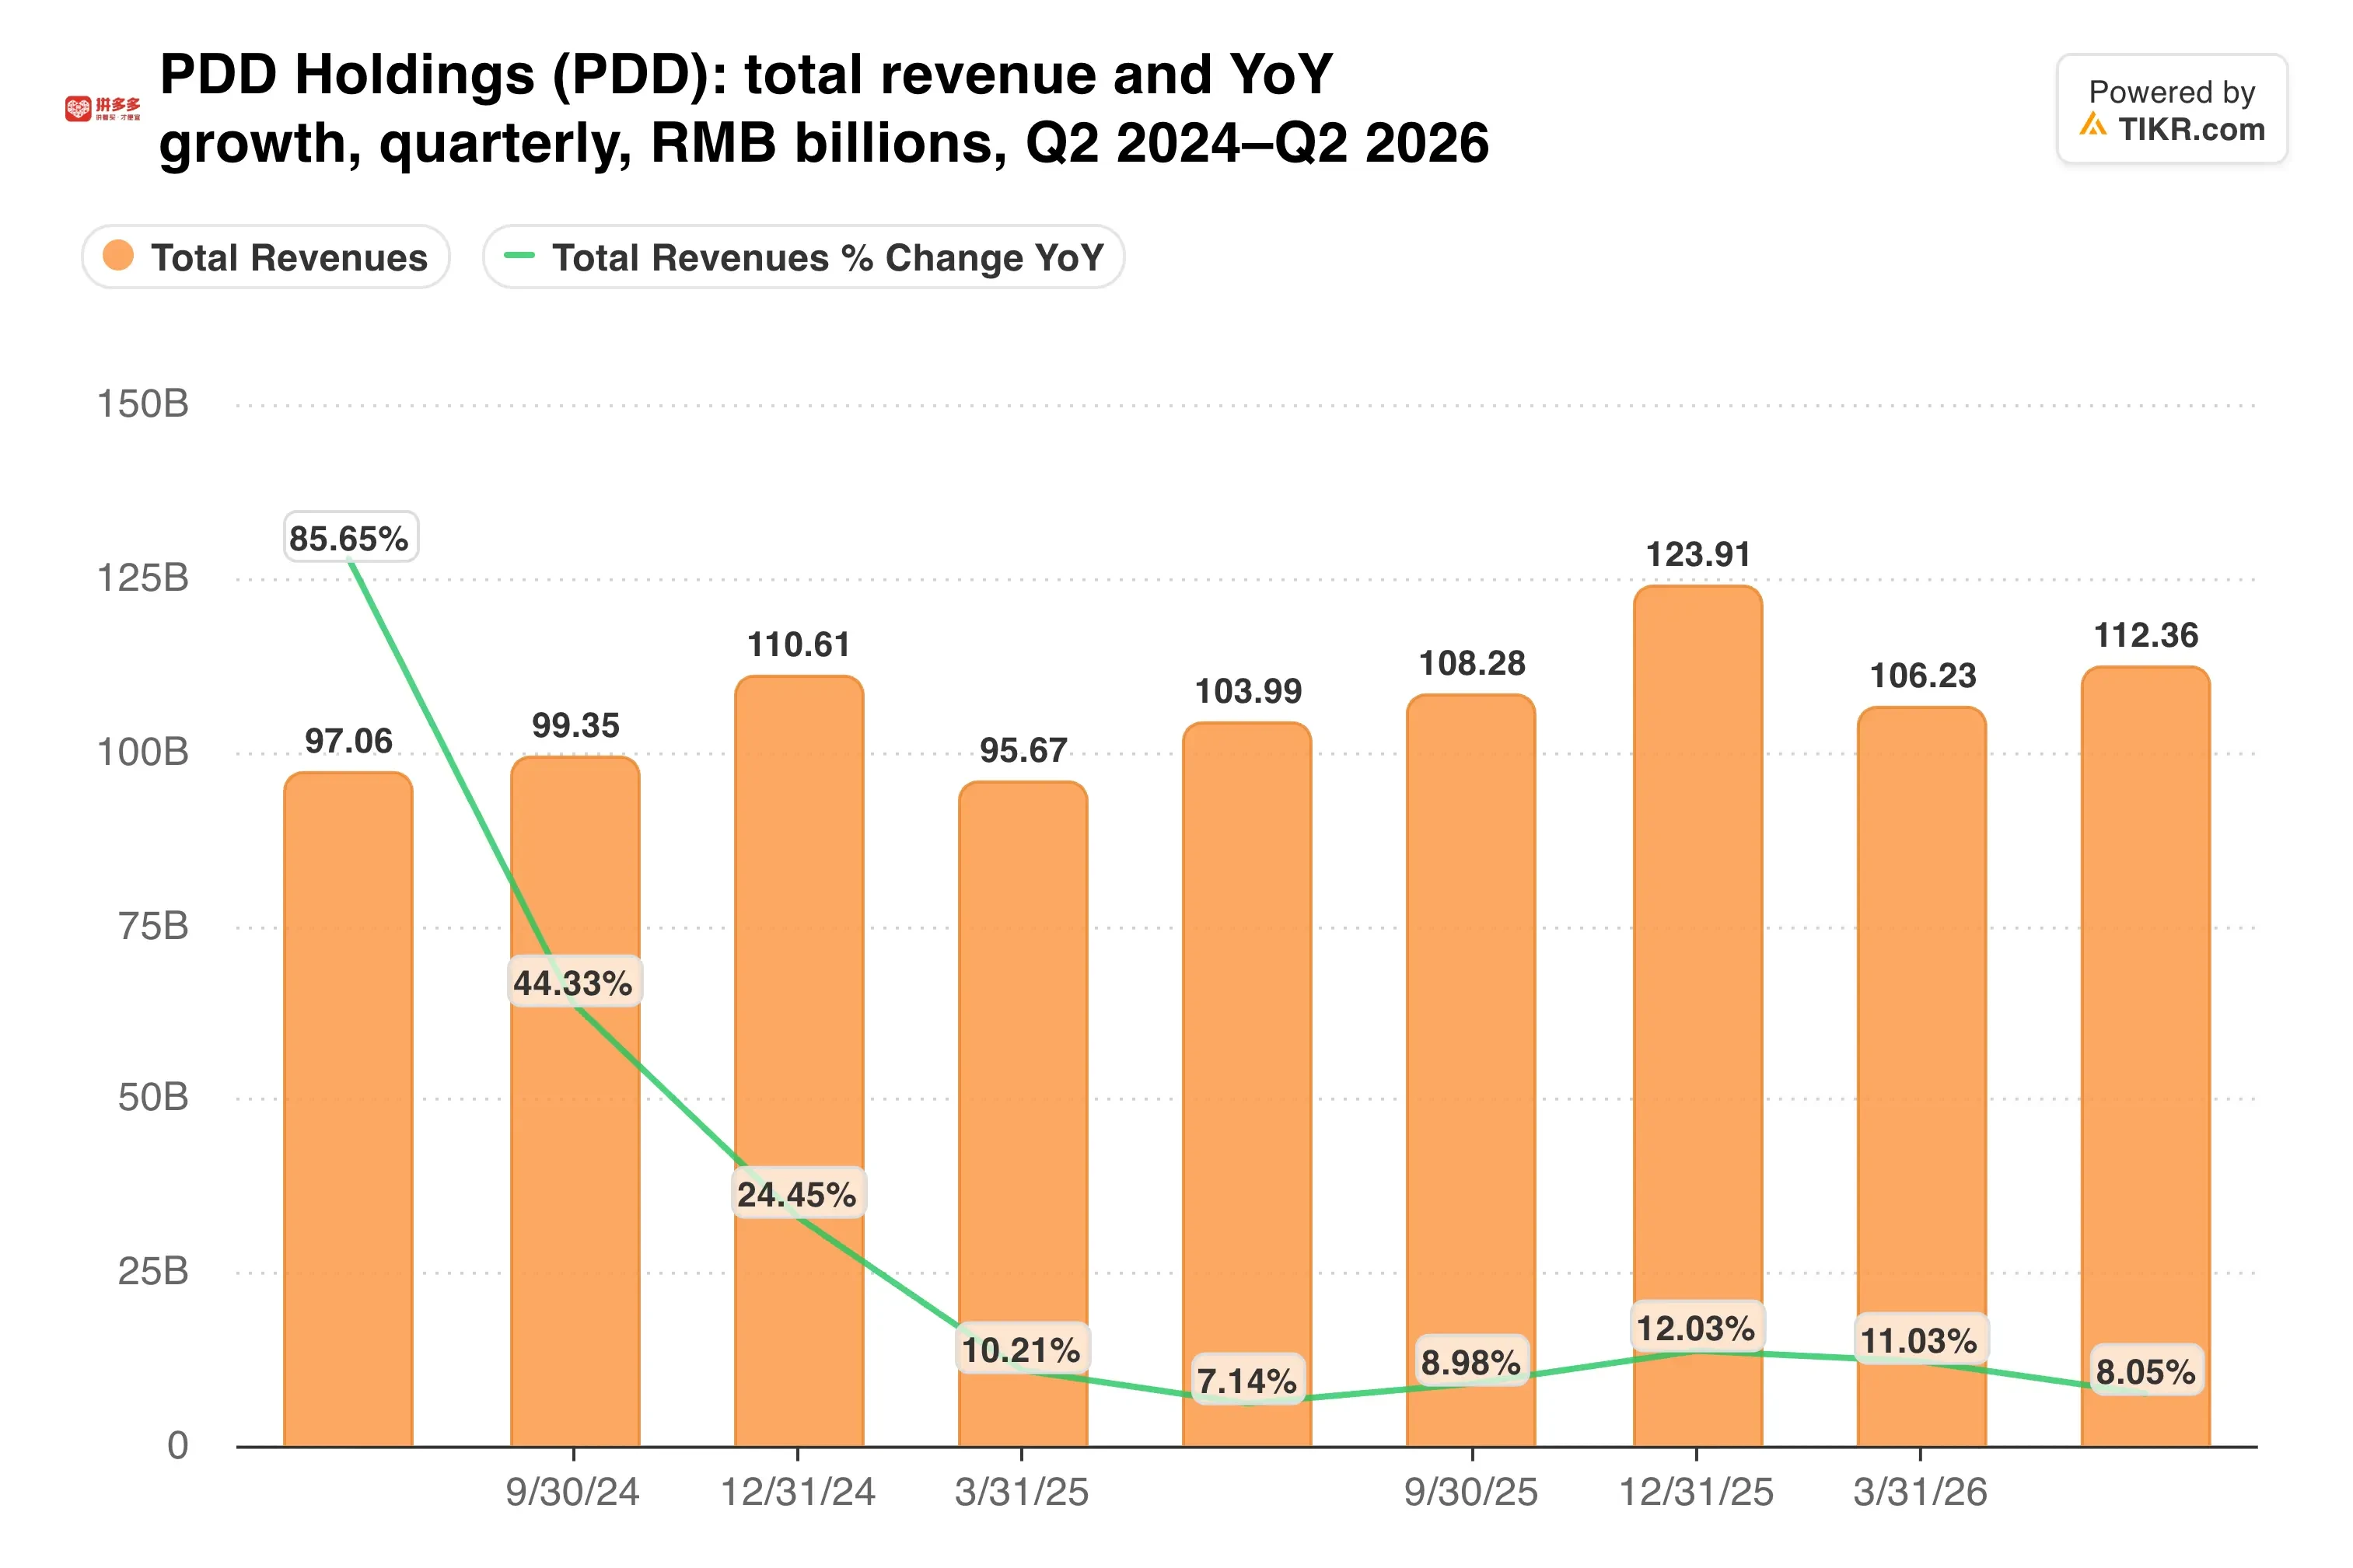
Top-line growth was 9% in the third quarter of 2025 and 8% in the second quarter of 2026. Marketing revenue mostly reflects what Pinduoduo’s merchants spend on ads at home, so the domestic engine needs a lift.
Spending is the swing factor
Total operating expenses rose 13% to RMB36.6 billion, faster than revenue. General and administrative costs jumped 53%, and research and development rose 27%.
Management says the spending is deliberate. “At this stage, our priority is helping merchants thrive and strengthening the broader industry ecosystem,” VP of Finance Jun Liu said in the August release.
Temu adds its own bill. The European Commission fined it €200 million in May for failing to assess the risk of illegal products. Temu called the fine disproportionate, yet the Commission accepted its fix plan on October 26. Next, Temu owes regulators an interim risk assessment covering the six months through November 30.
Europe also began charging a €3 duty per item on parcels under €150 in July. So the third quarter is the first full quarter carrying that cost. In October, Temu also agreed to a $3 million data and product safety settlement with Texas.
Even so, PDD still keeps far more of each yuan than its rival does.
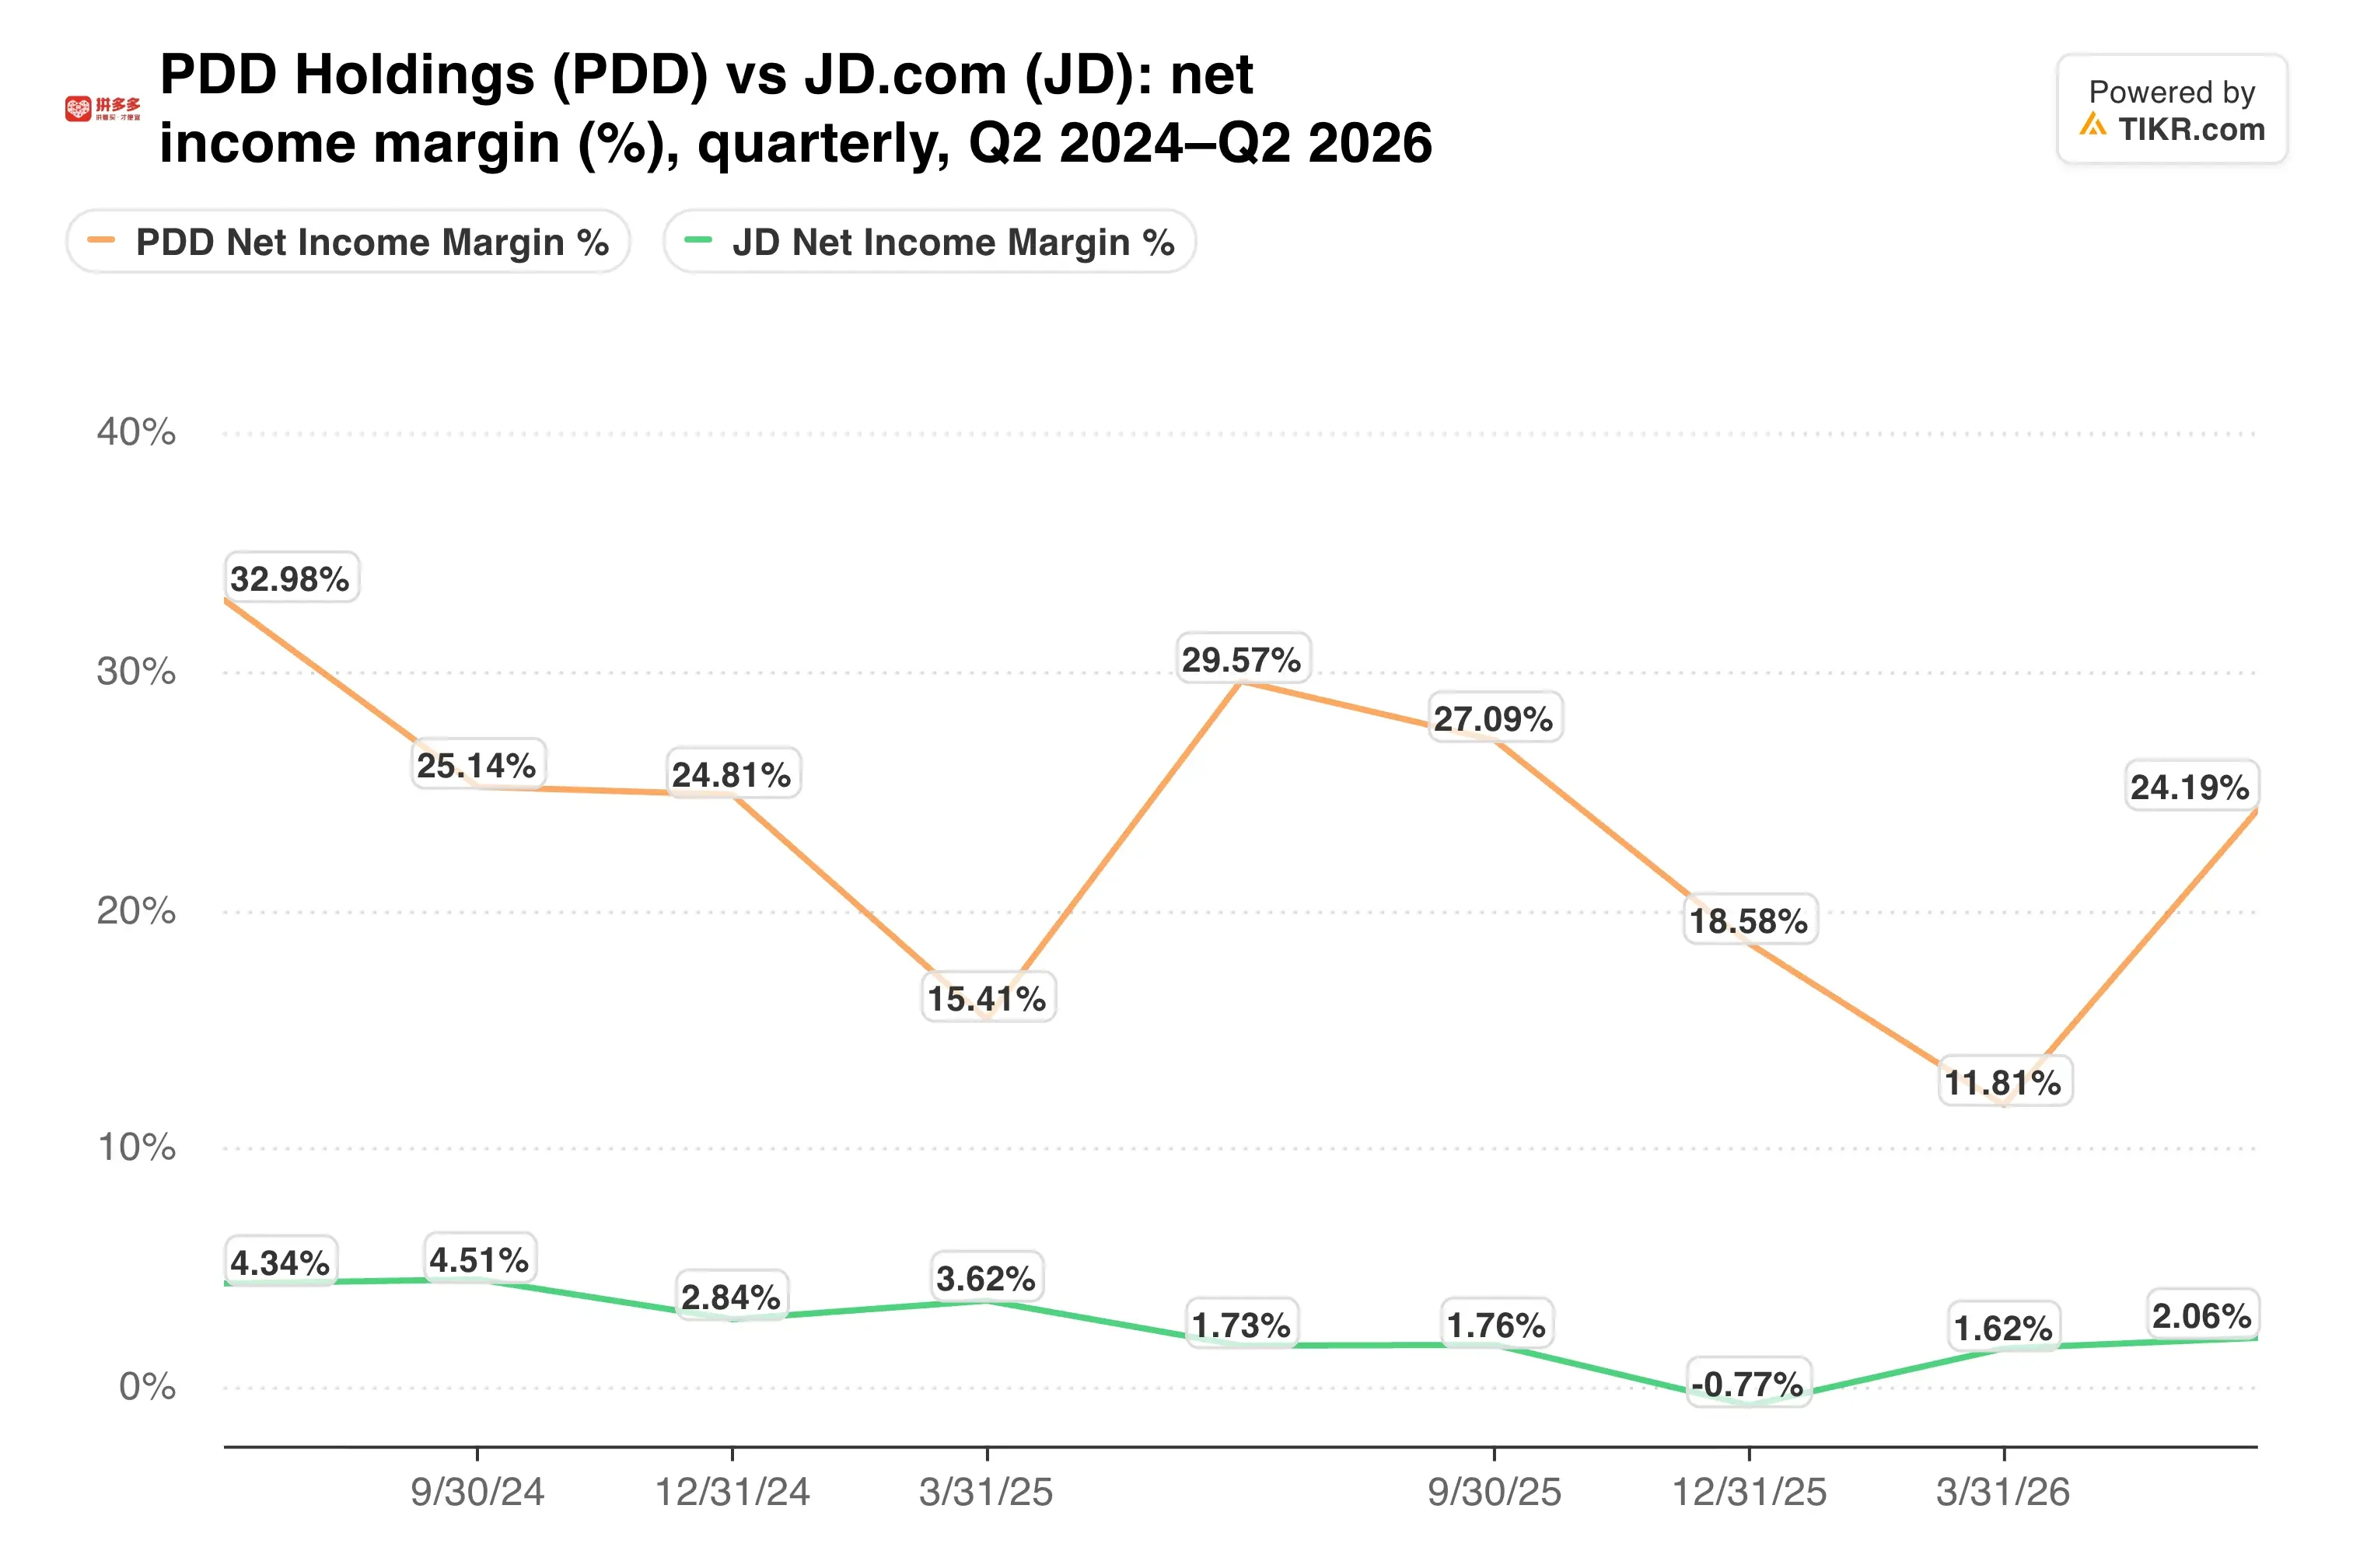
That gap gives PDD room to absorb new costs. However, the cushion is shrinking quarter by quarter.
TIKR tracks 37 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
A cash pile cushions the comparison
PDD ended June with RMB456.4 billion ($67.3 billion) in cash, cash equivalents and short-term investments. That was up from RMB422.3 billion at the end of 2025, and the balance keeps climbing:
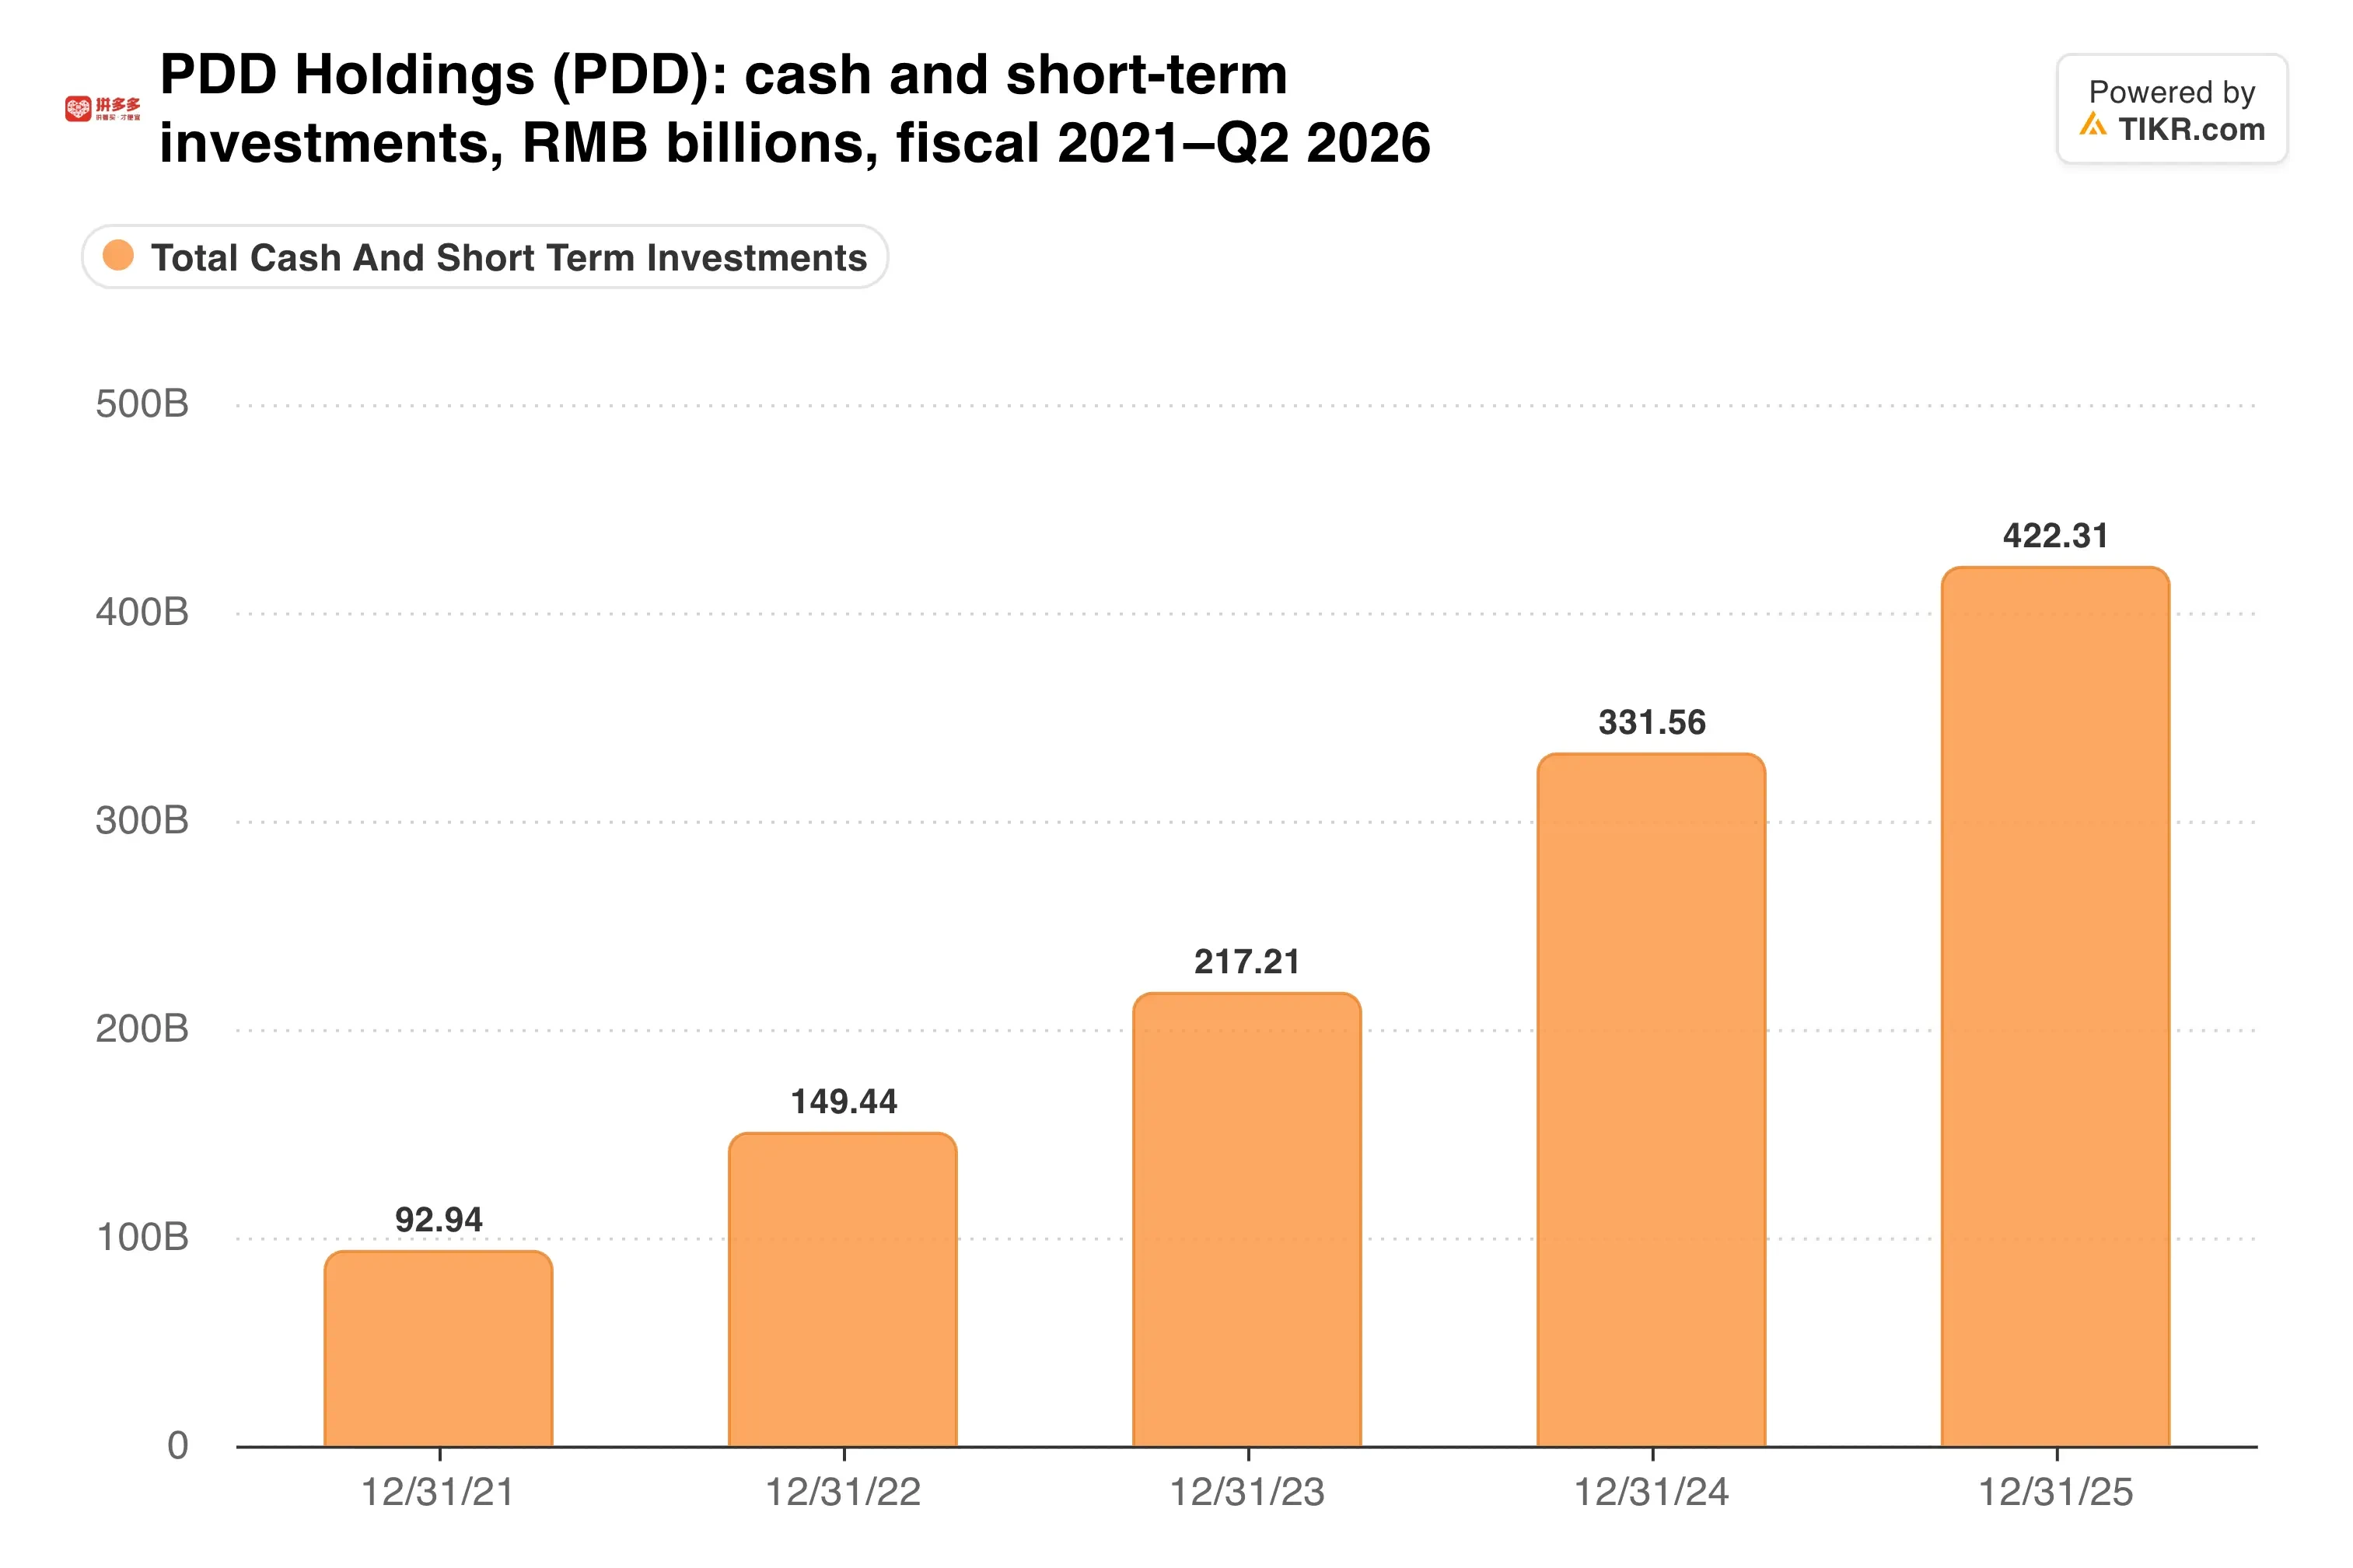
All that cash is a big reason the stock can look cheap while earnings shrink. Its valuation sits near the low end of its five-year range.
The third-quarter comparison is tougher than the second. A year ago, PDD posted RMB29.3 billion of net income and non-GAAP earnings per ADS of RMB21.08. Operating cash flow reached RMB45.7 billion in that quarter.
My take: PDD remains hugely profitable, and its cash lets management keep spending without strain. Still, I’d want two signs before calling a bottom. First, marketing revenue growth should move back above 3.5%. Second, operating expenses should grow slower than sales. Until then, a cheap multiple can stay cheap.
Thursday’s report will show whether Temu absorbed the first full quarter of the €3 duty while transaction services kept growing near 13%. It will also show how far net income lands from last year’s RMB29.3 billion. JD’s Tuesday numbers will offer an early look at Chinese demand.
So what is PDD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!