Key Takeaways
- ONEOK closed a Permian acquisition worth about $4.4 billion on Oct. 6, Kimberly-Clark closed its Kenvue acquisition on Nov. 2, and the two stocks yield 4.9% and 4.8%.
- ONEOK’s distributable cash flow covered its fiscal 2025 dividend 2.3x. Kimberly-Clark’s dividend took 87% of its free cash flow over the twelve months to Sept. 30, 2026.
- Kimberly-Clark has raised its dividend for 54 years in a row but took on new debt to buy Kenvue, while ONEOK paid off nearly $5.5 billion of debt principal in September.
- At each dividend’s pace now, $10,000 in ONEOK pays about $14,650 over 20 years against about $13,270 for Kimberly-Clark. At their 5-year rates, Kimberly-Clark comes out ahead.
ONEOK (OKE) closed a roughly $4.4 billion purchase of Brazos Midstream’s Permian assets on Oct. 6. Four weeks later, Kimberly-Clark (KMB) closed its acquisition of Kenvue.
Both stocks yield close to 5%. Each board’s first dividend declaration after its deal came at the current rate: $1.07 a quarter at ONEOK on Oct. 14, and $1.28 at Kimberly-Clark on Nov. 11. If you could hold only one of them for the next 20 years, which would it be?
| Metric | ONEOK (OKE) | Kimberly-Clark (KMB) |
|---|---|---|
| Dividend yield | 4.9% | 4.8% |
| Annual dividend | $4.28 | $5.12 |
| Dividend growth, fiscal 2020-2025 | 2.0% a year | 3.3% a year |
| Coverage, on its own measure | 2.3x distributable cash flow coverage (fiscal 2025) | 87% cash dividend payout ratio (TTM to Sept. 30, 2026) |
| Net debt/EBITDA (LTM) | 3.7x | 1.2x (before Kenvue) |
| Interest coverage (LTM) | 3.5x | 13x (before Kenvue) |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
ONEOK’s cash has outgrown its dividend
ONEOK’s business is growing. Its third-quarter adjusted EBITDA rose 6% from a year before to $2.24 billion on record Permian volumes. On Oct. 27, it raised its 2026 adjusted EBITDA guidance to $8.5-$8.6 billion, its third raise of the year.
Its distributable cash flow rose from $3.20 a share in fiscal 2016 to $9.25 in fiscal 2025. Over the same years, the dividend went from $2.46 to $4.12:
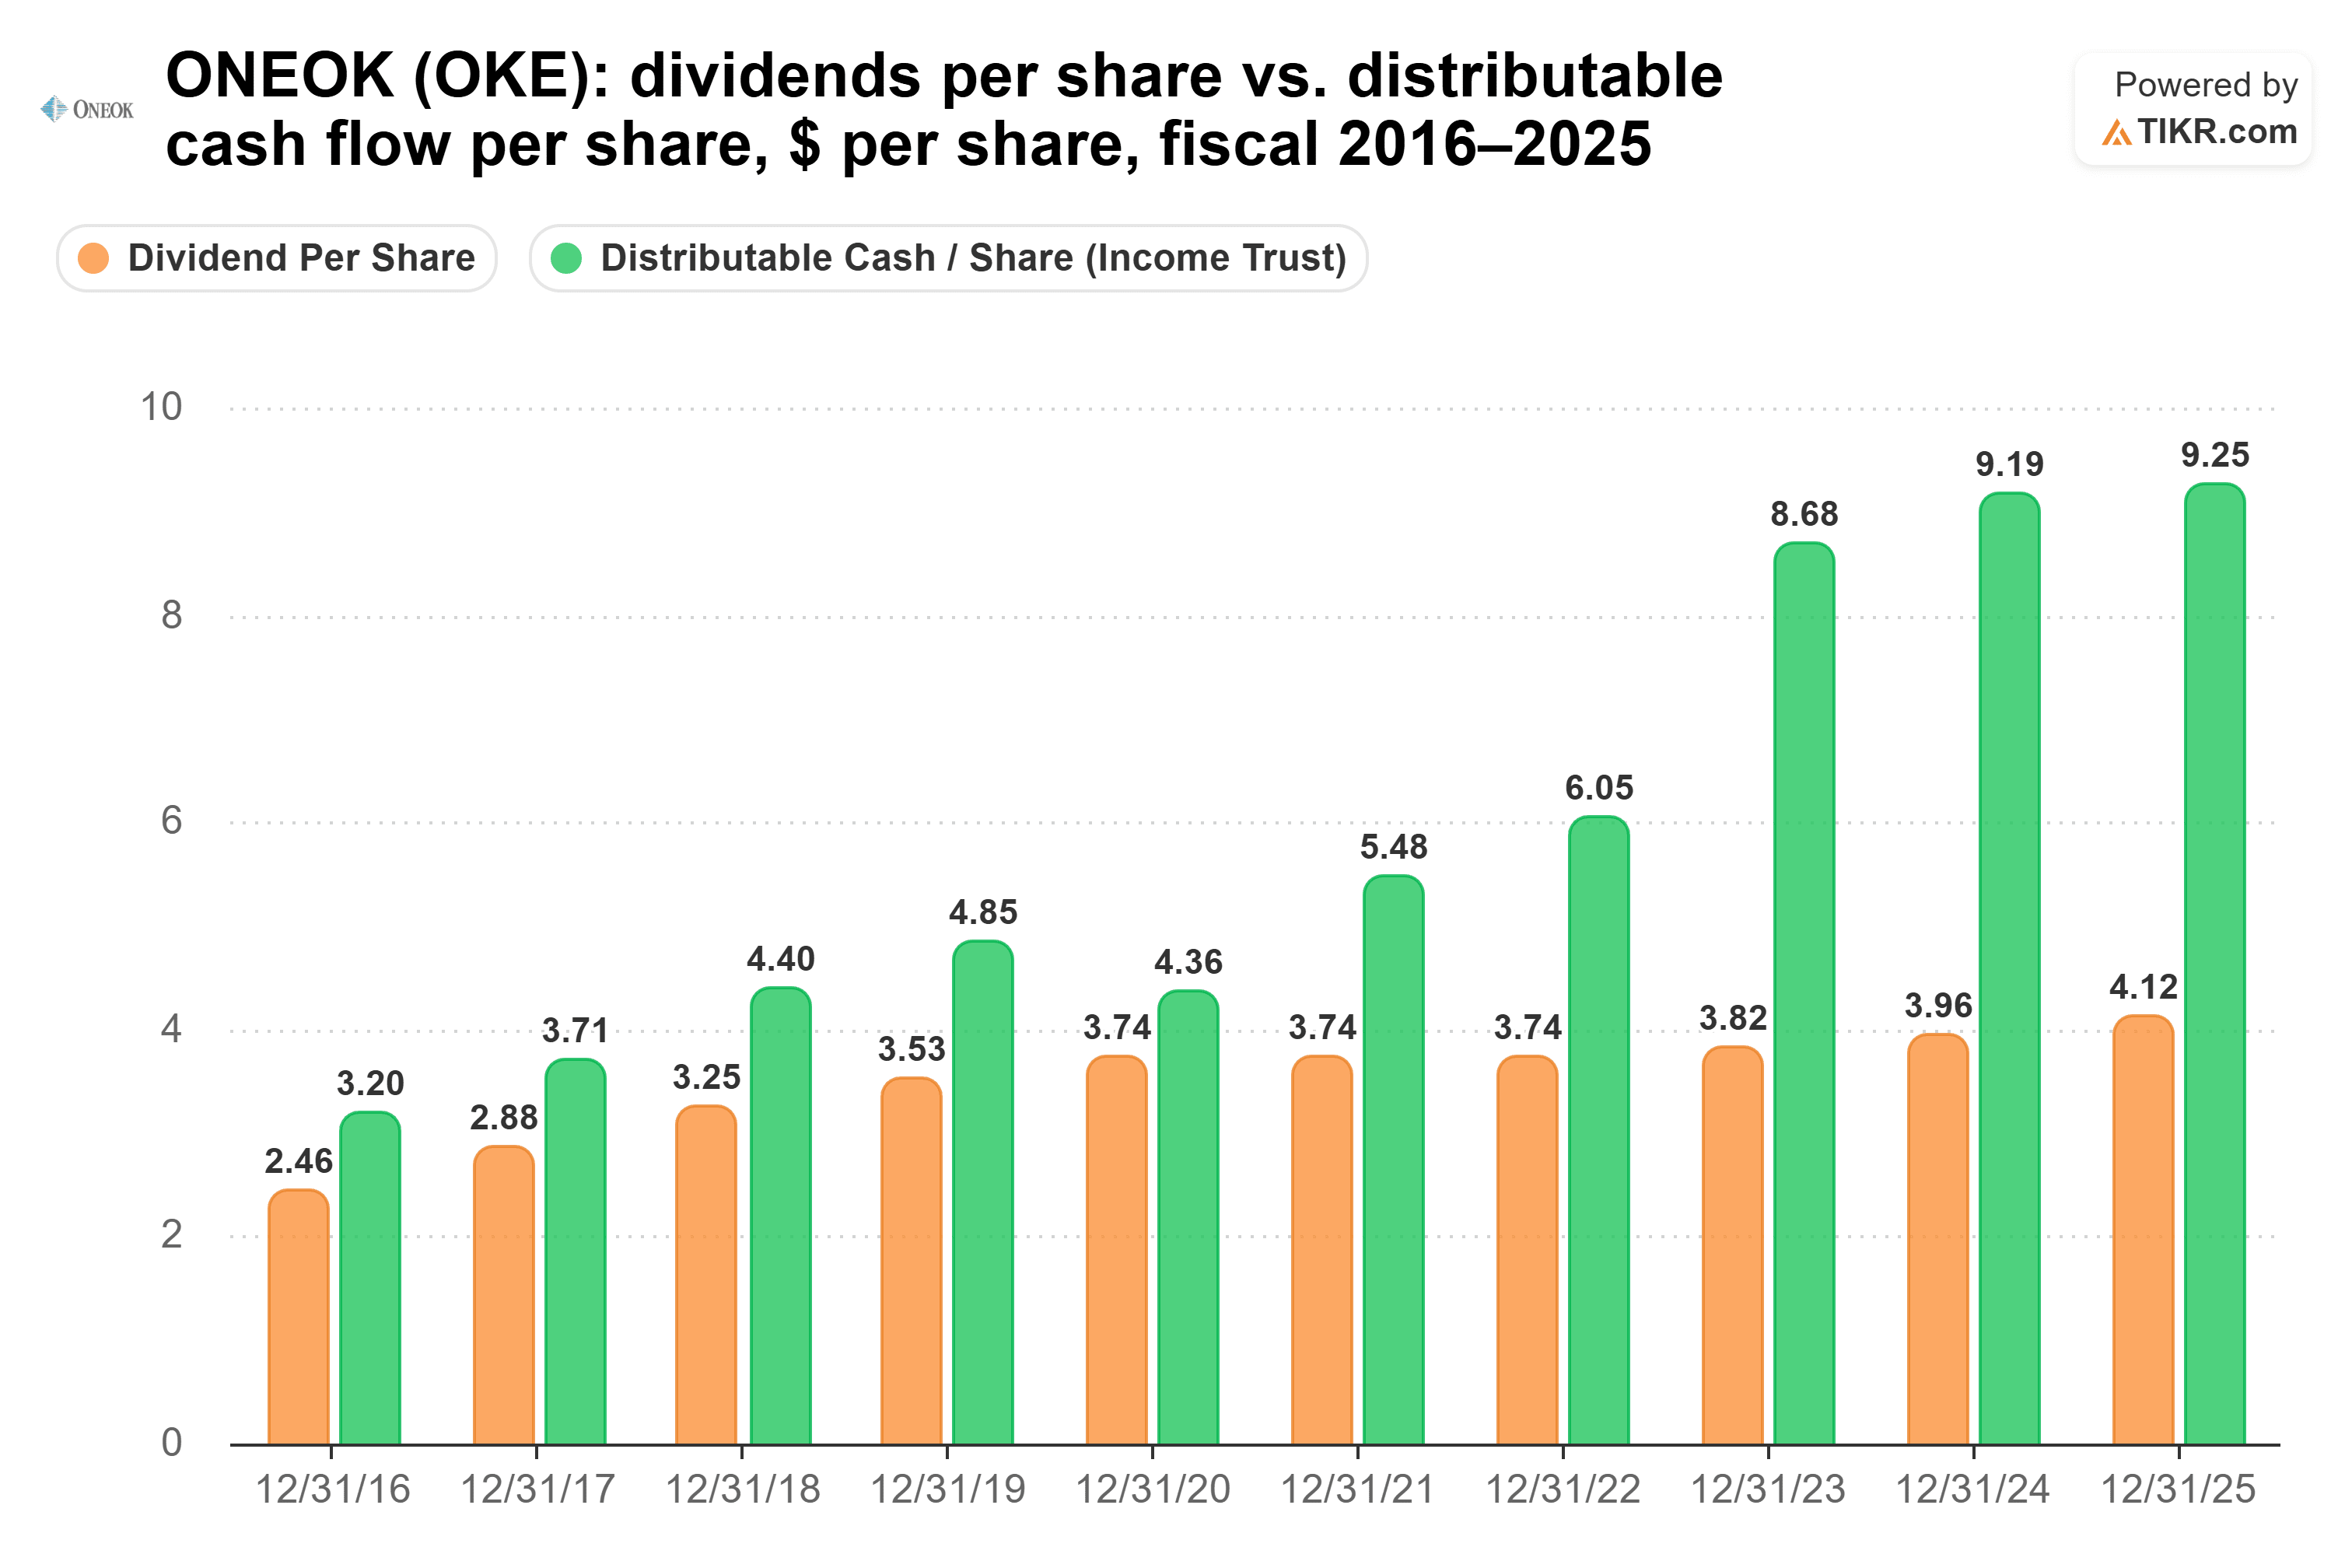
That’s 2.3x coverage in fiscal 2025, up from 1.3x in fiscal 2016. The dividend grew 2.0% a year from fiscal 2020 to fiscal 2025. It stayed at $3.74 a share from fiscal 2020 to fiscal 2022, then rose 4.0% in fiscal 2025.
ONEOK expects capex of about $3.5 billion this year and around $3 billion in 2027. ONEOK CFO Walter Hulse said on the third-quarter call that this still leaves “quite a bit of free cash flow to return capital to shareholders.”
Debt is the catch. ONEOK’s net debt is 3.7x EBITDA over the last twelve months. Hulse said on the same call: “We now view 3.5x as the upper end of our targeted leverage range.”
Kimberly-Clark has the record, but less room
Kimberly-Clark has the longer record. The company says it has raised its dividend for 54 consecutive years and paid one for 92. But its free cash flow fell from $2.46 billion in fiscal 2016 to $1.64 billion in fiscal 2025. Meanwhile, the dividends it paid rose every year, from $1.31 billion to $1.66 billion:
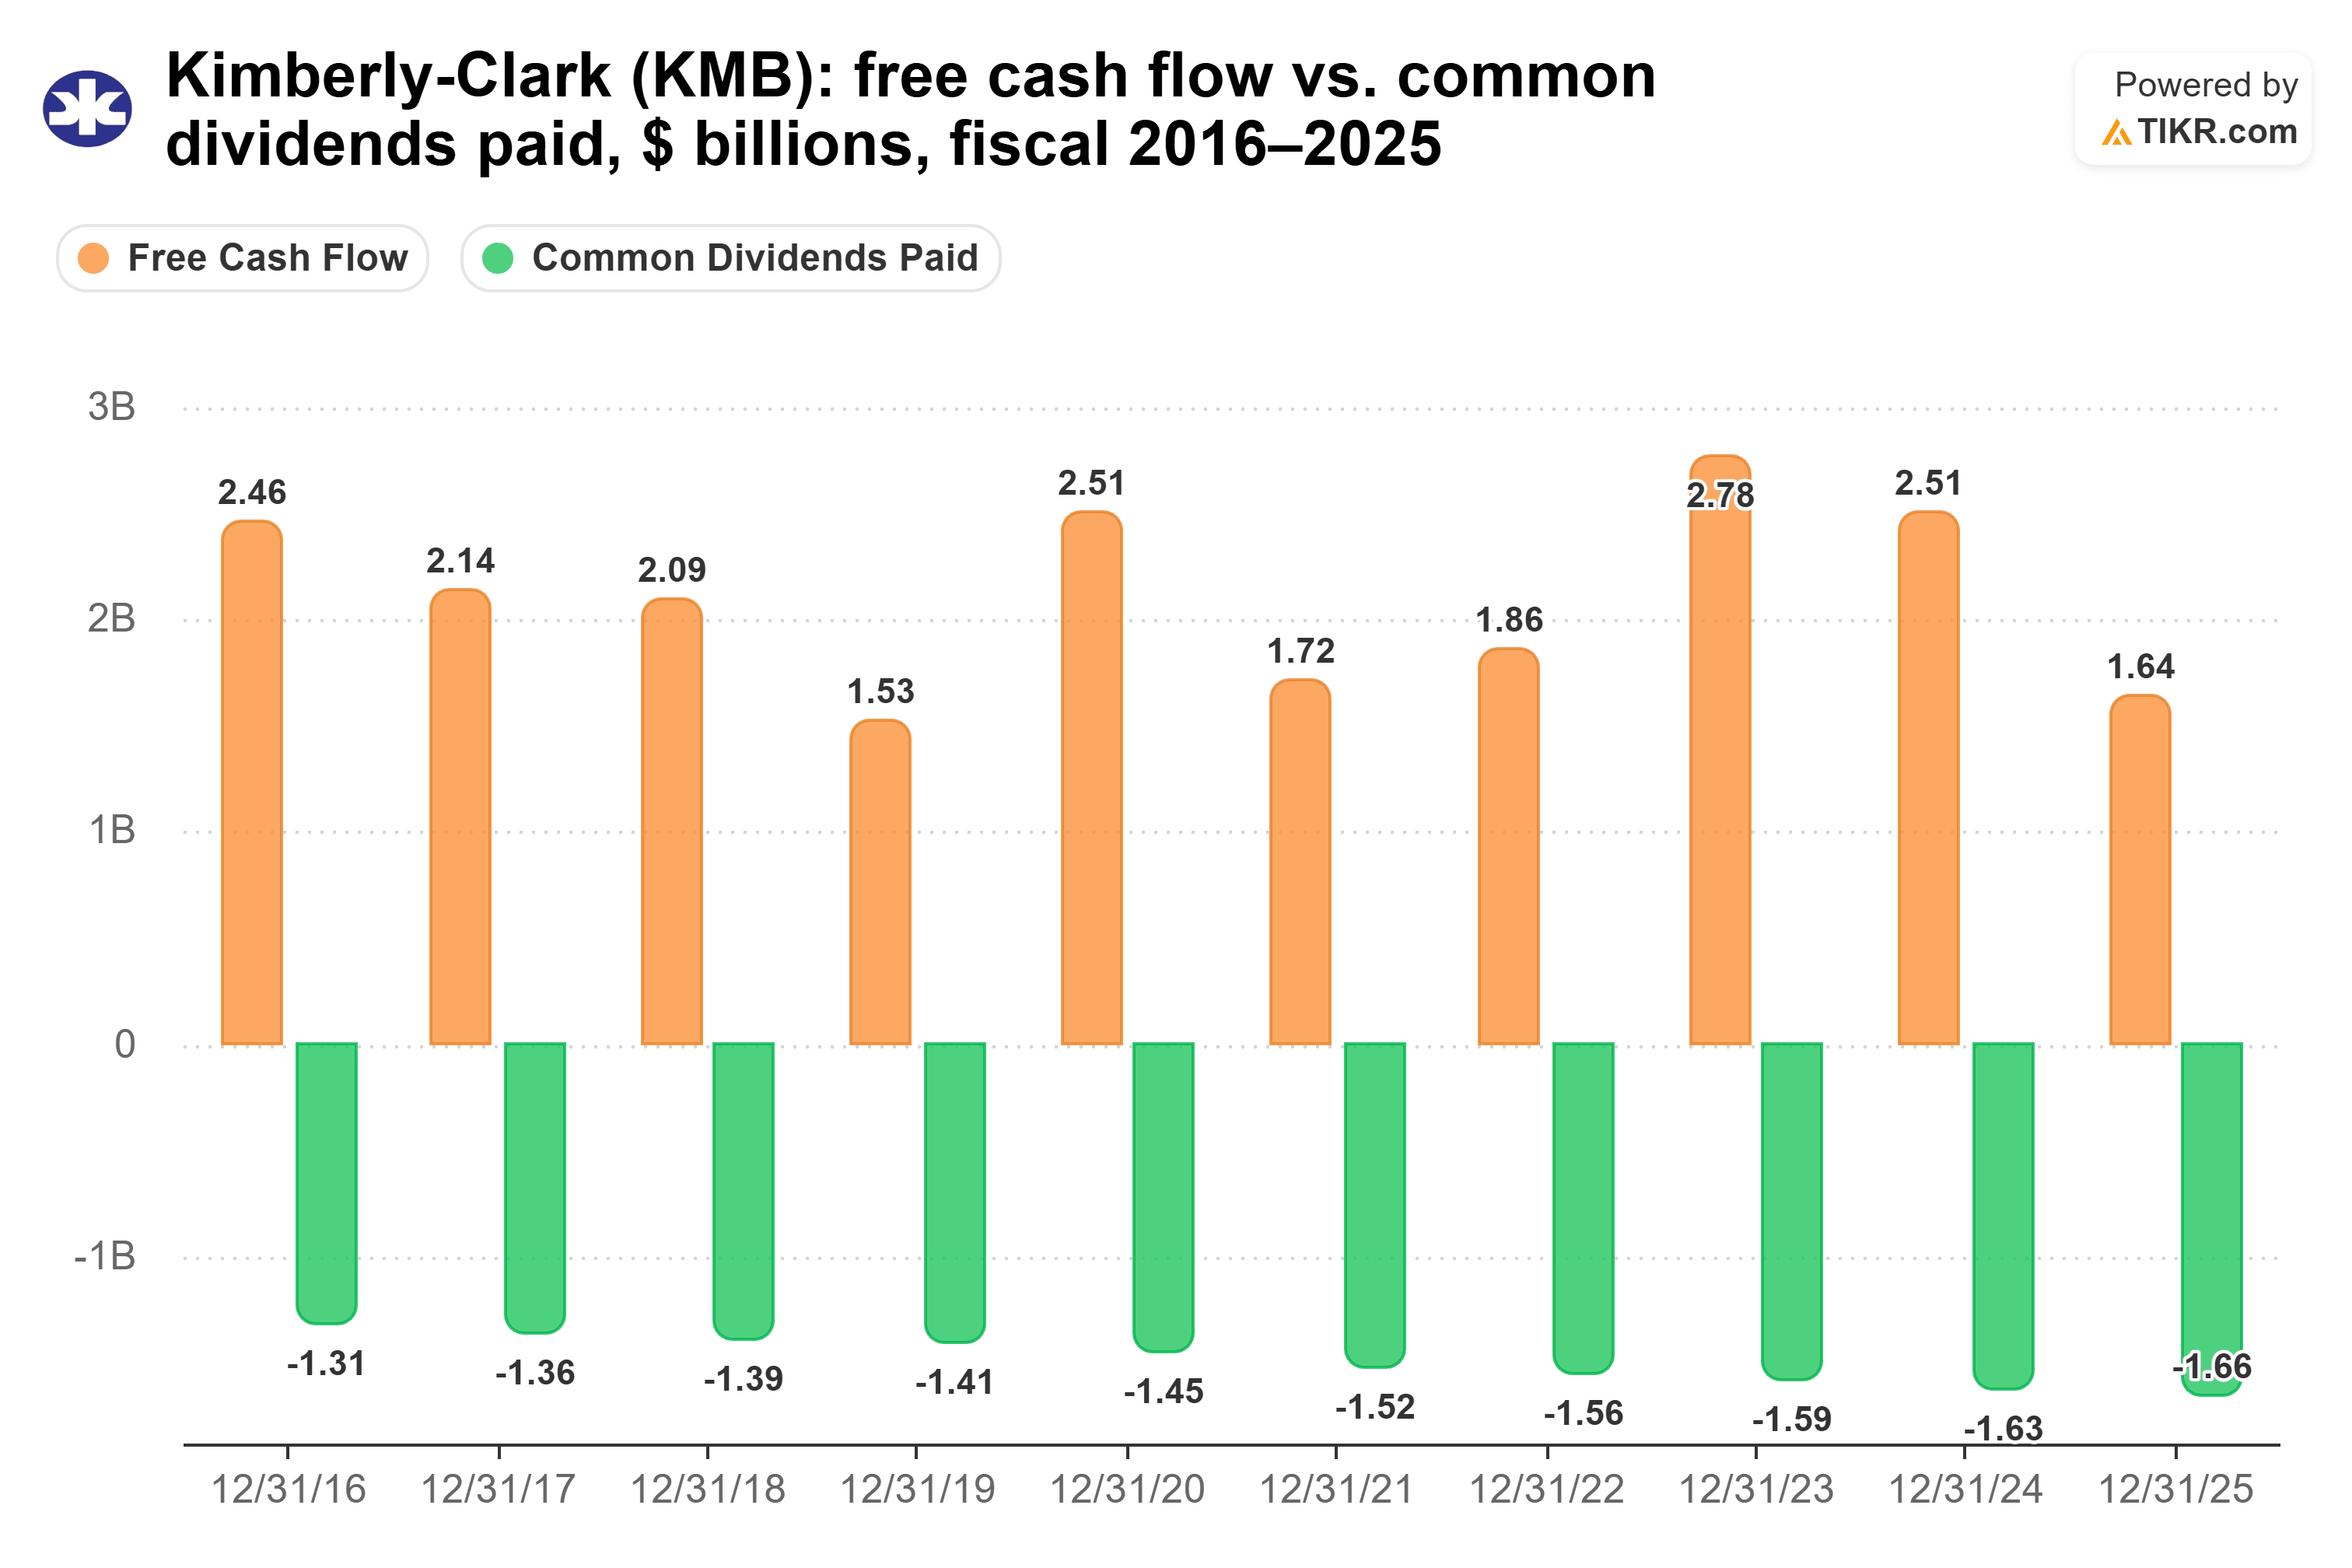
Dividends took 101% of free cash flow in fiscal 2025, and 87% over the twelve months to Sept. 30, 2026. That’s a thin cushion.
The base business is soft, too. Third-quarter organic sales fell 1.3% from a year before. A social media disruption around its diapers in China cost about 270 basis points. Kimberly-Clark still reaffirmed its 2026 outlook with those results on Nov. 5.
Kenvue brings Tylenol, Listerine and Neutrogena, and it brings debt. Kimberly-Clark sold $4.9 billion of new notes on Oct. 29. On Nov. 3, it swapped about $6.4 billion of Kenvue’s bonds for its own. Before the deal, it carried $6.5 billion of debt at Sept. 30. It expects Kenvue to cut its 2027 earnings per share by a mid-single-digit percentage, compared with Kimberly-Clark on its own.
So which dividend wins?
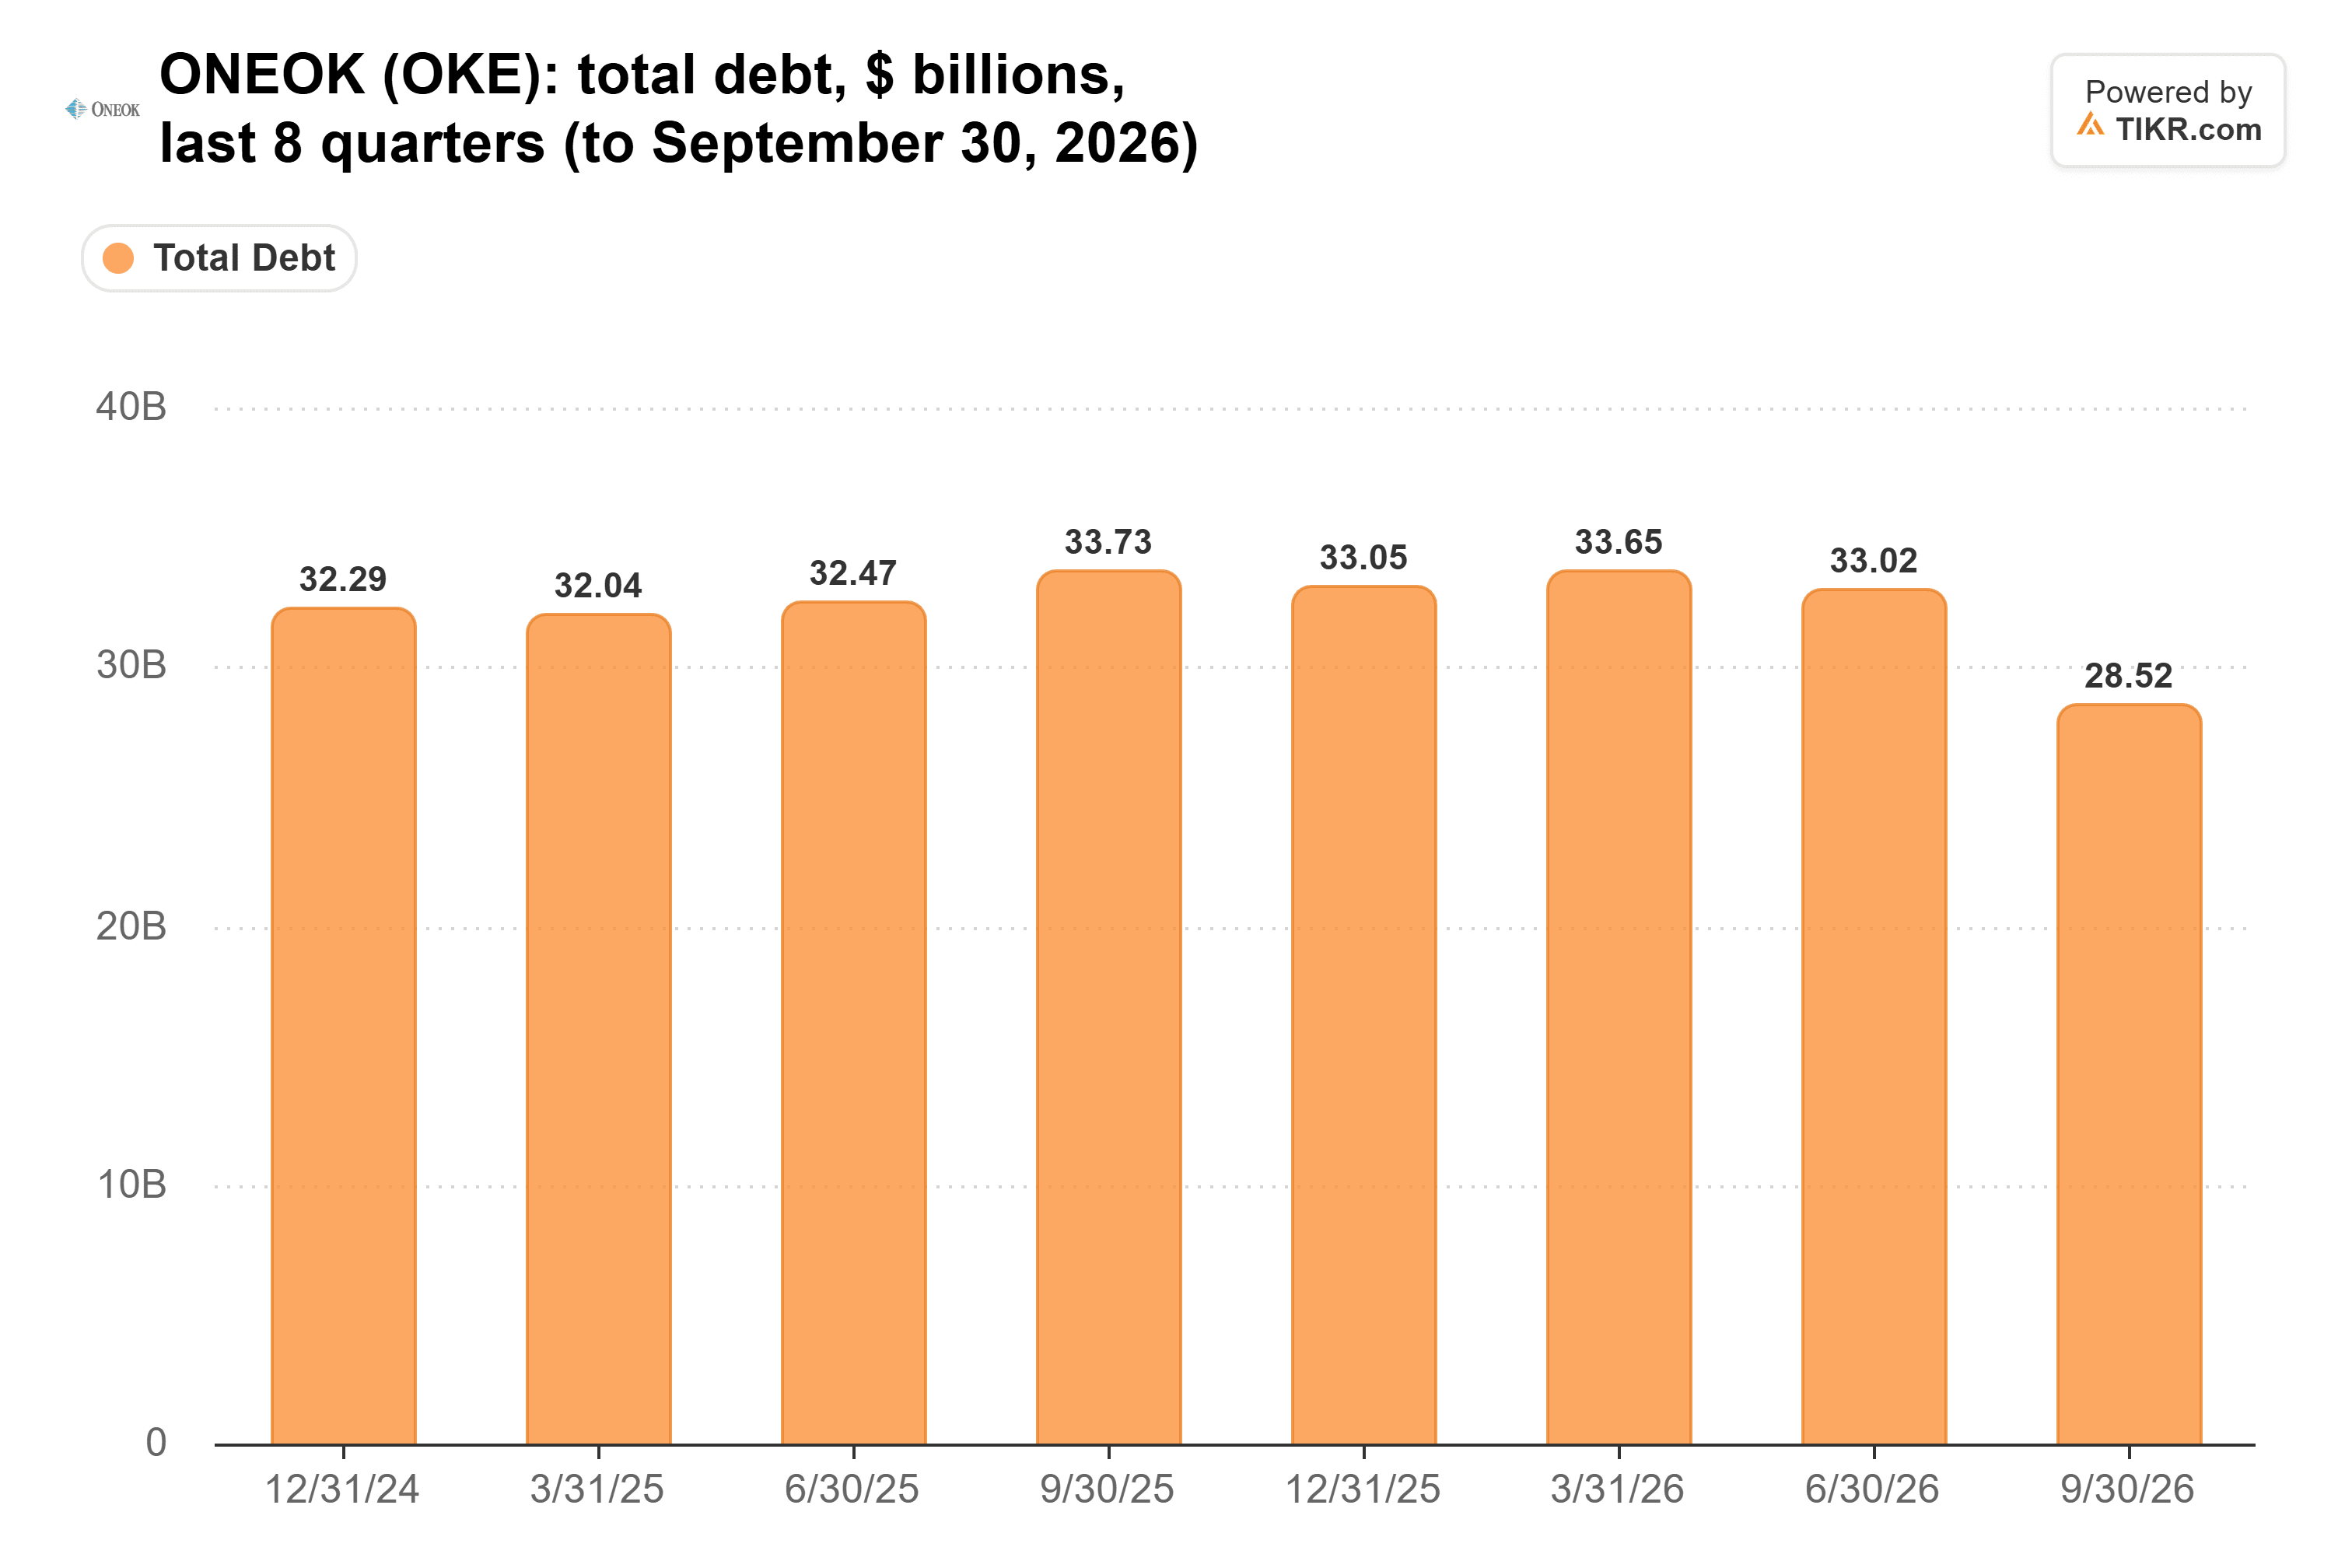
If I can only hold one dividend stock for the next 20 years, it’s ONEOK. Over that long, the cash behind the check matters most. ONEOK’s distributable cash flow covers its dividend more than twice over, and the company is paying its debt down. Its total debt fell from $33.0 billion at June 30 to $28.5 billion at Sept. 30, 2026, after it paid off nearly $5.5 billion of principal in September:
S&P and Fitch raised ONEOK’s credit ratings to BBB+ from BBB on Oct. 19.
ONEOK should pay you more over those 20 years, too. At each dividend’s 5-year rate, $10,000 in Kimberly-Clark pays about $1,480 more. But ONEOK’s 5-year rate includes those three years at $3.74. At each dividend’s pace now, $10,000 in ONEOK pays about $14,650 over 20 years, and Kimberly-Clark about $13,270.
This isn’t to say Kimberly-Clark’s dividend is in danger. Its 54-year streak is one management will work very hard to keep, and Kenvue’s brands could make it a stronger business. It’s just that, for 20 years, I’d rather own the dividend with the wider cushion and the shrinking debt.
Of course, Kimberly-Clark is aiming for about 2x leverage by the end of the deal’s second year and $1.9 billion of cost synergies. If it gets there, that 87% could come down a lot.
Forget ONEOK: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And ONEOK isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!