Key Takeaways
- Oppenheimer has kept its Outperform rating and $425 price target on Marvell Technology, 248% above the stock’s Nov. 20 close.
- Marvell fell 11.7% on Nov. 20 and is 61% below its June closing high, after investors balked at its all-stock deal for Lumentum.
- Analysts expect $12.76 of normalized EPS in fiscal 2029, and $425 is about 33x that.
- Today the stock trades at about 17x the year ending January 2028, so the target needs the multiple to roughly double and the estimates to hold.
Marvell Technology (MRVL) fell 11.7% on Nov. 20, to $122.28, after Stifel cut its price target during a broad chip selloff. It’s now 61% below its June 4 closing high.
Oppenheimer isn’t moving. It has kept its Outperform rating and the $425 target it set on Oct. 7, now 248% above Friday’s close. Investors have punished the stock since Marvell agreed to buy Lumentum (LITE) in a $115 billion all-stock deal, even though Lumentum’s quarterly revenue more than doubled to $1.26 billion.
Investors Balked at Marvell’s Price for Lumentum
On Nov. 2, Marvell announced a deal to pay 4.5 of its shares for each Lumentum share, worth about $1,132 at Oct. 28 prices, the last close before reports of the talks. At Friday’s close, those shares are worth about $550. When the deal closes, which Marvell expects in the first half of 2028, Lumentum holders will own about a third of the combined company.
The business didn’t give investors a reason to sell. Alongside the deal, Marvell said third-quarter revenue would land within 2% of the $3.15 billion midpoint it guided to in August.
Oppenheimer Isn’t Budging on Marvell
Oppenheimer’s Rick Schafer has held his target while others cut theirs. Stifel lowered its target to $280 from $370 on Nov. 20, and RBC cut to $250 from $425 on Nov. 3.
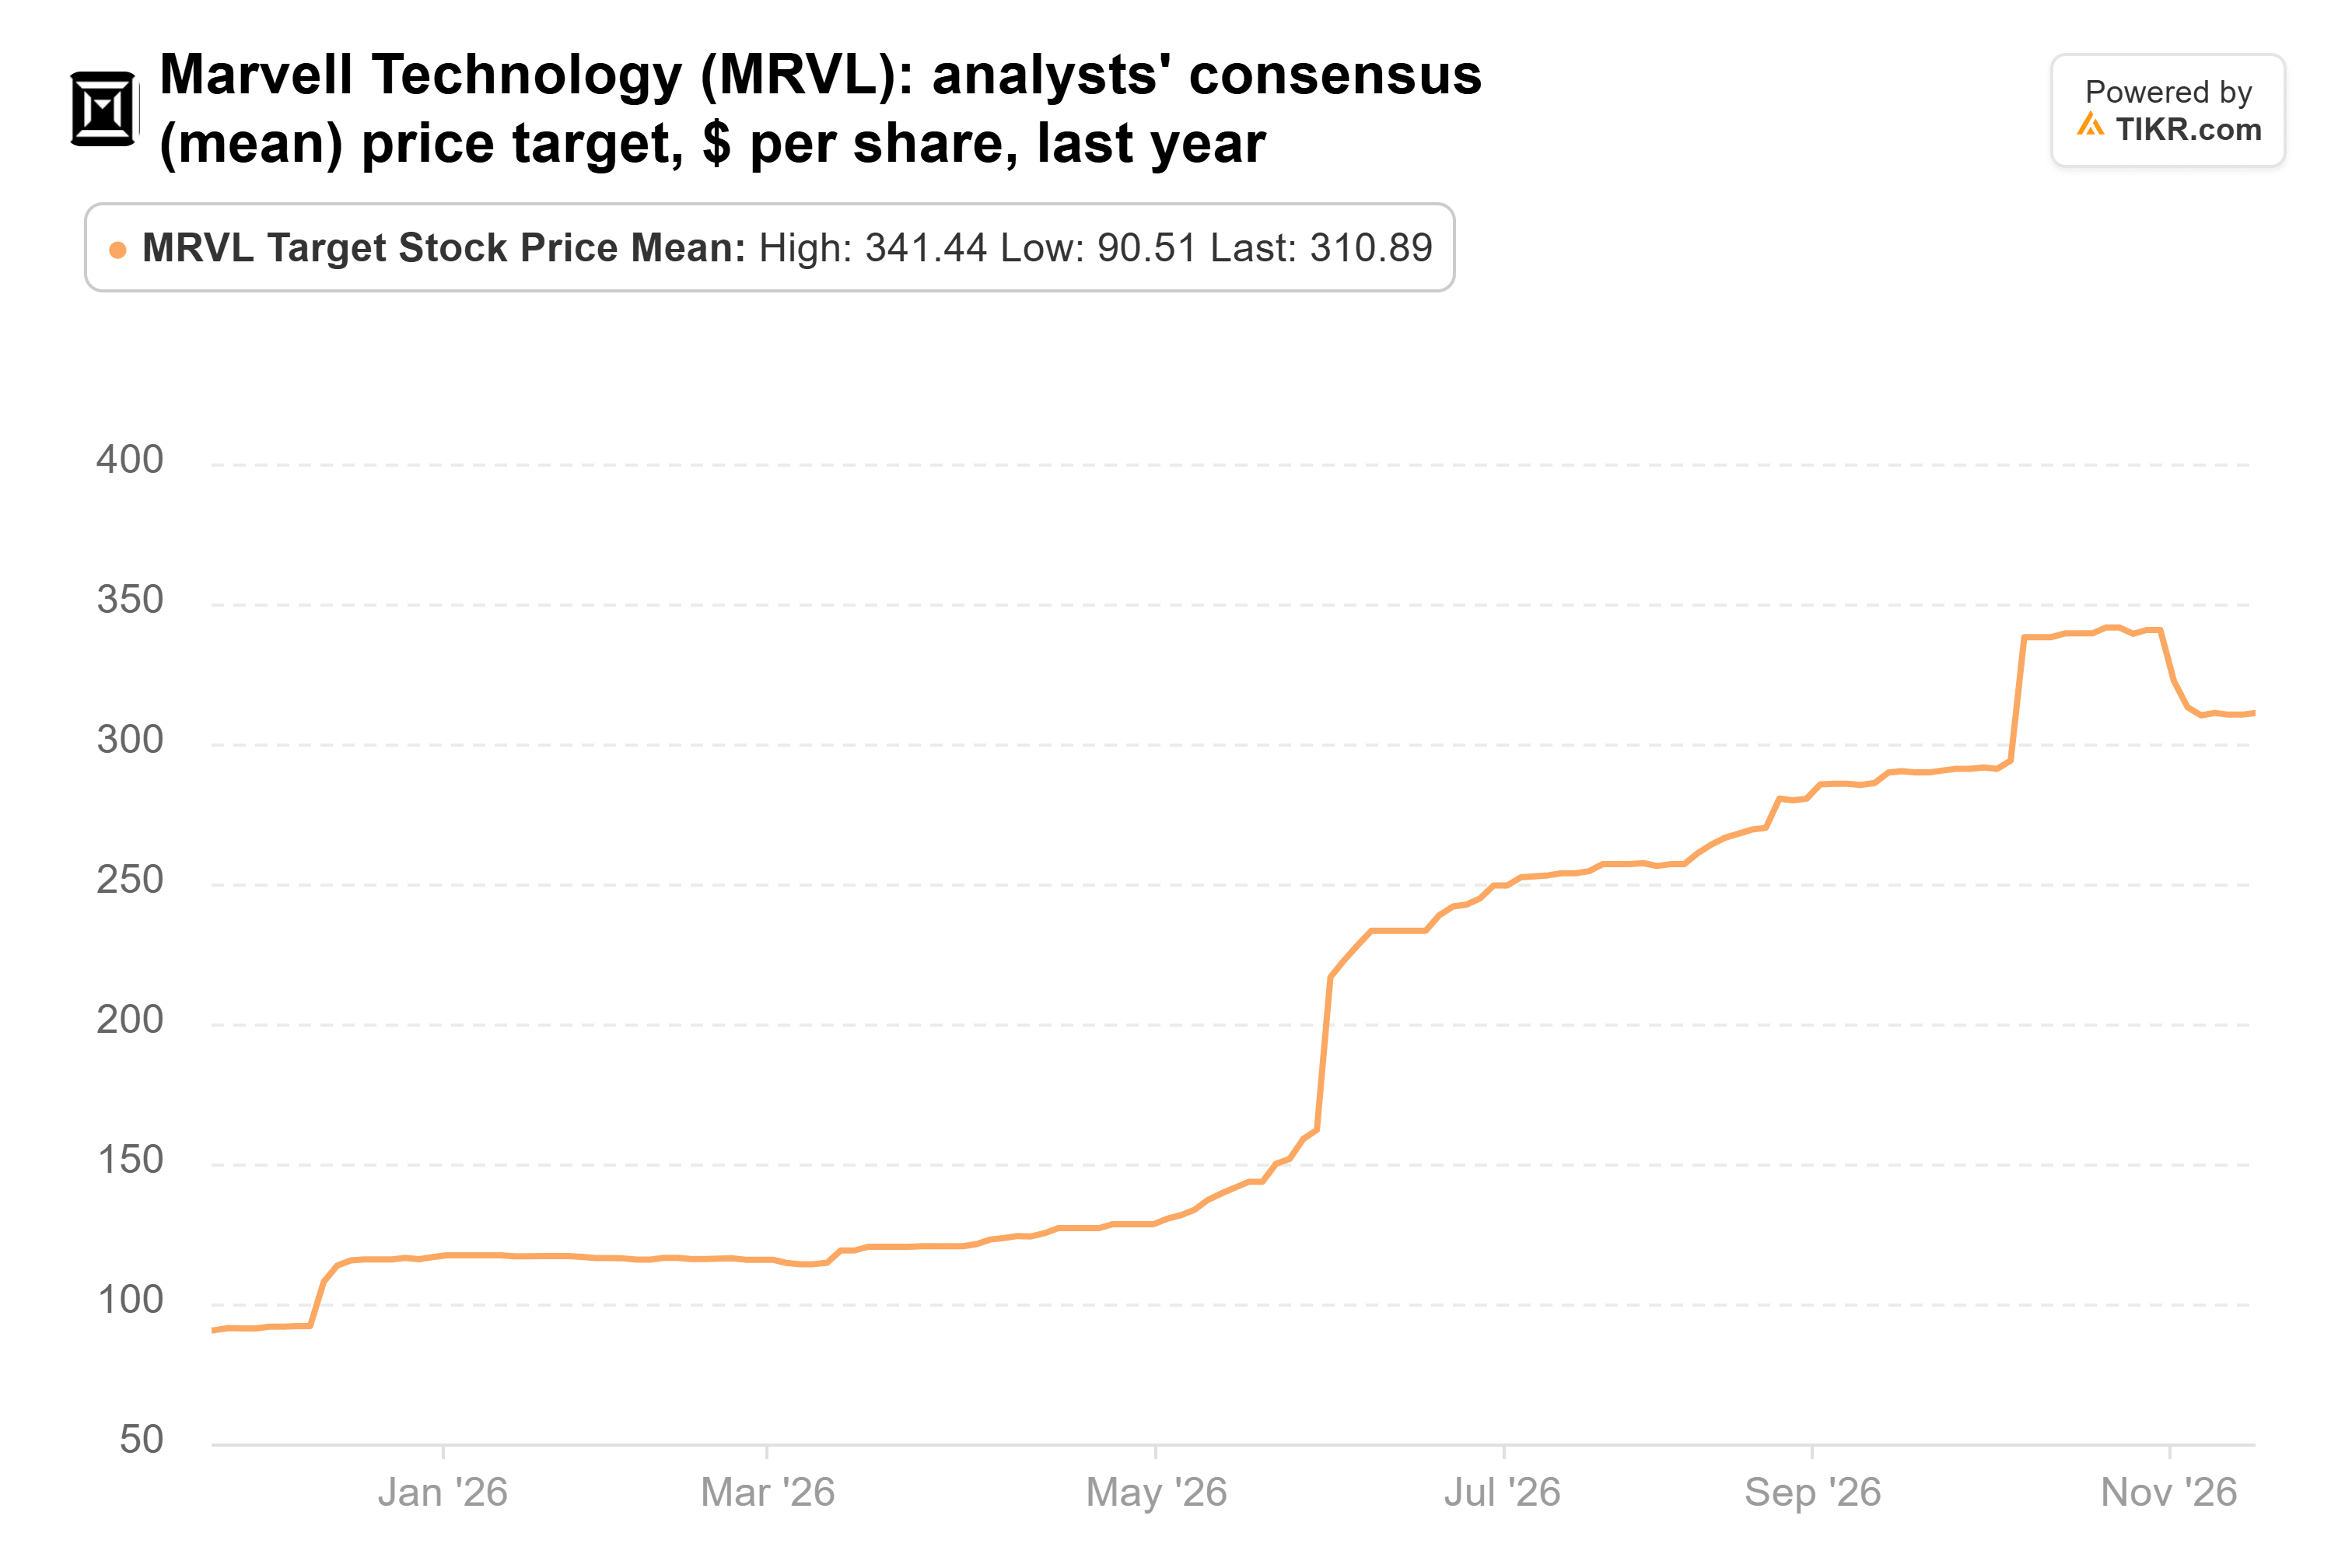
That leaves Oppenheimer 37% above the $311 consensus target. The consensus has eased from $341 in late October, but it’s still more than triple where it stood a year ago:
What $425 Asks For
Analysts expect Marvell’s normalized EPS to climb from $4.22 in fiscal 2027 (the year ending January 2027) to $7.37 in fiscal 2028 and $12.76 in fiscal 2029:
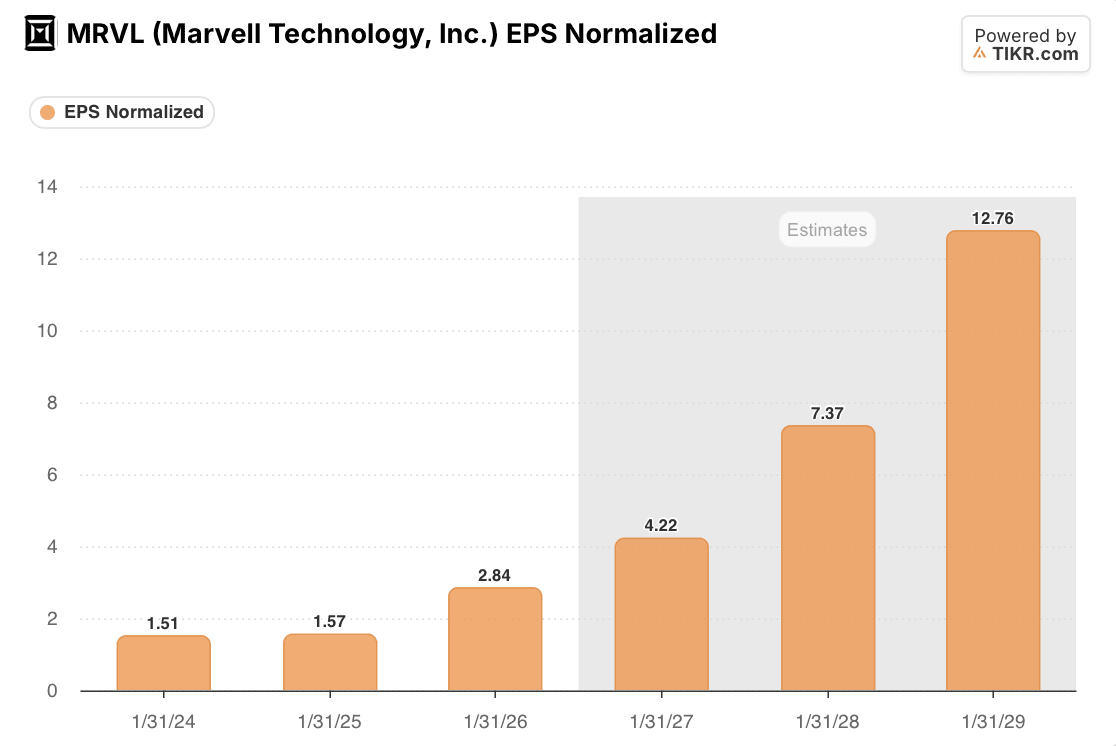
They’ve raised those numbers through the selloff: three months ago, the fiscal 2028 estimate was $6.29.
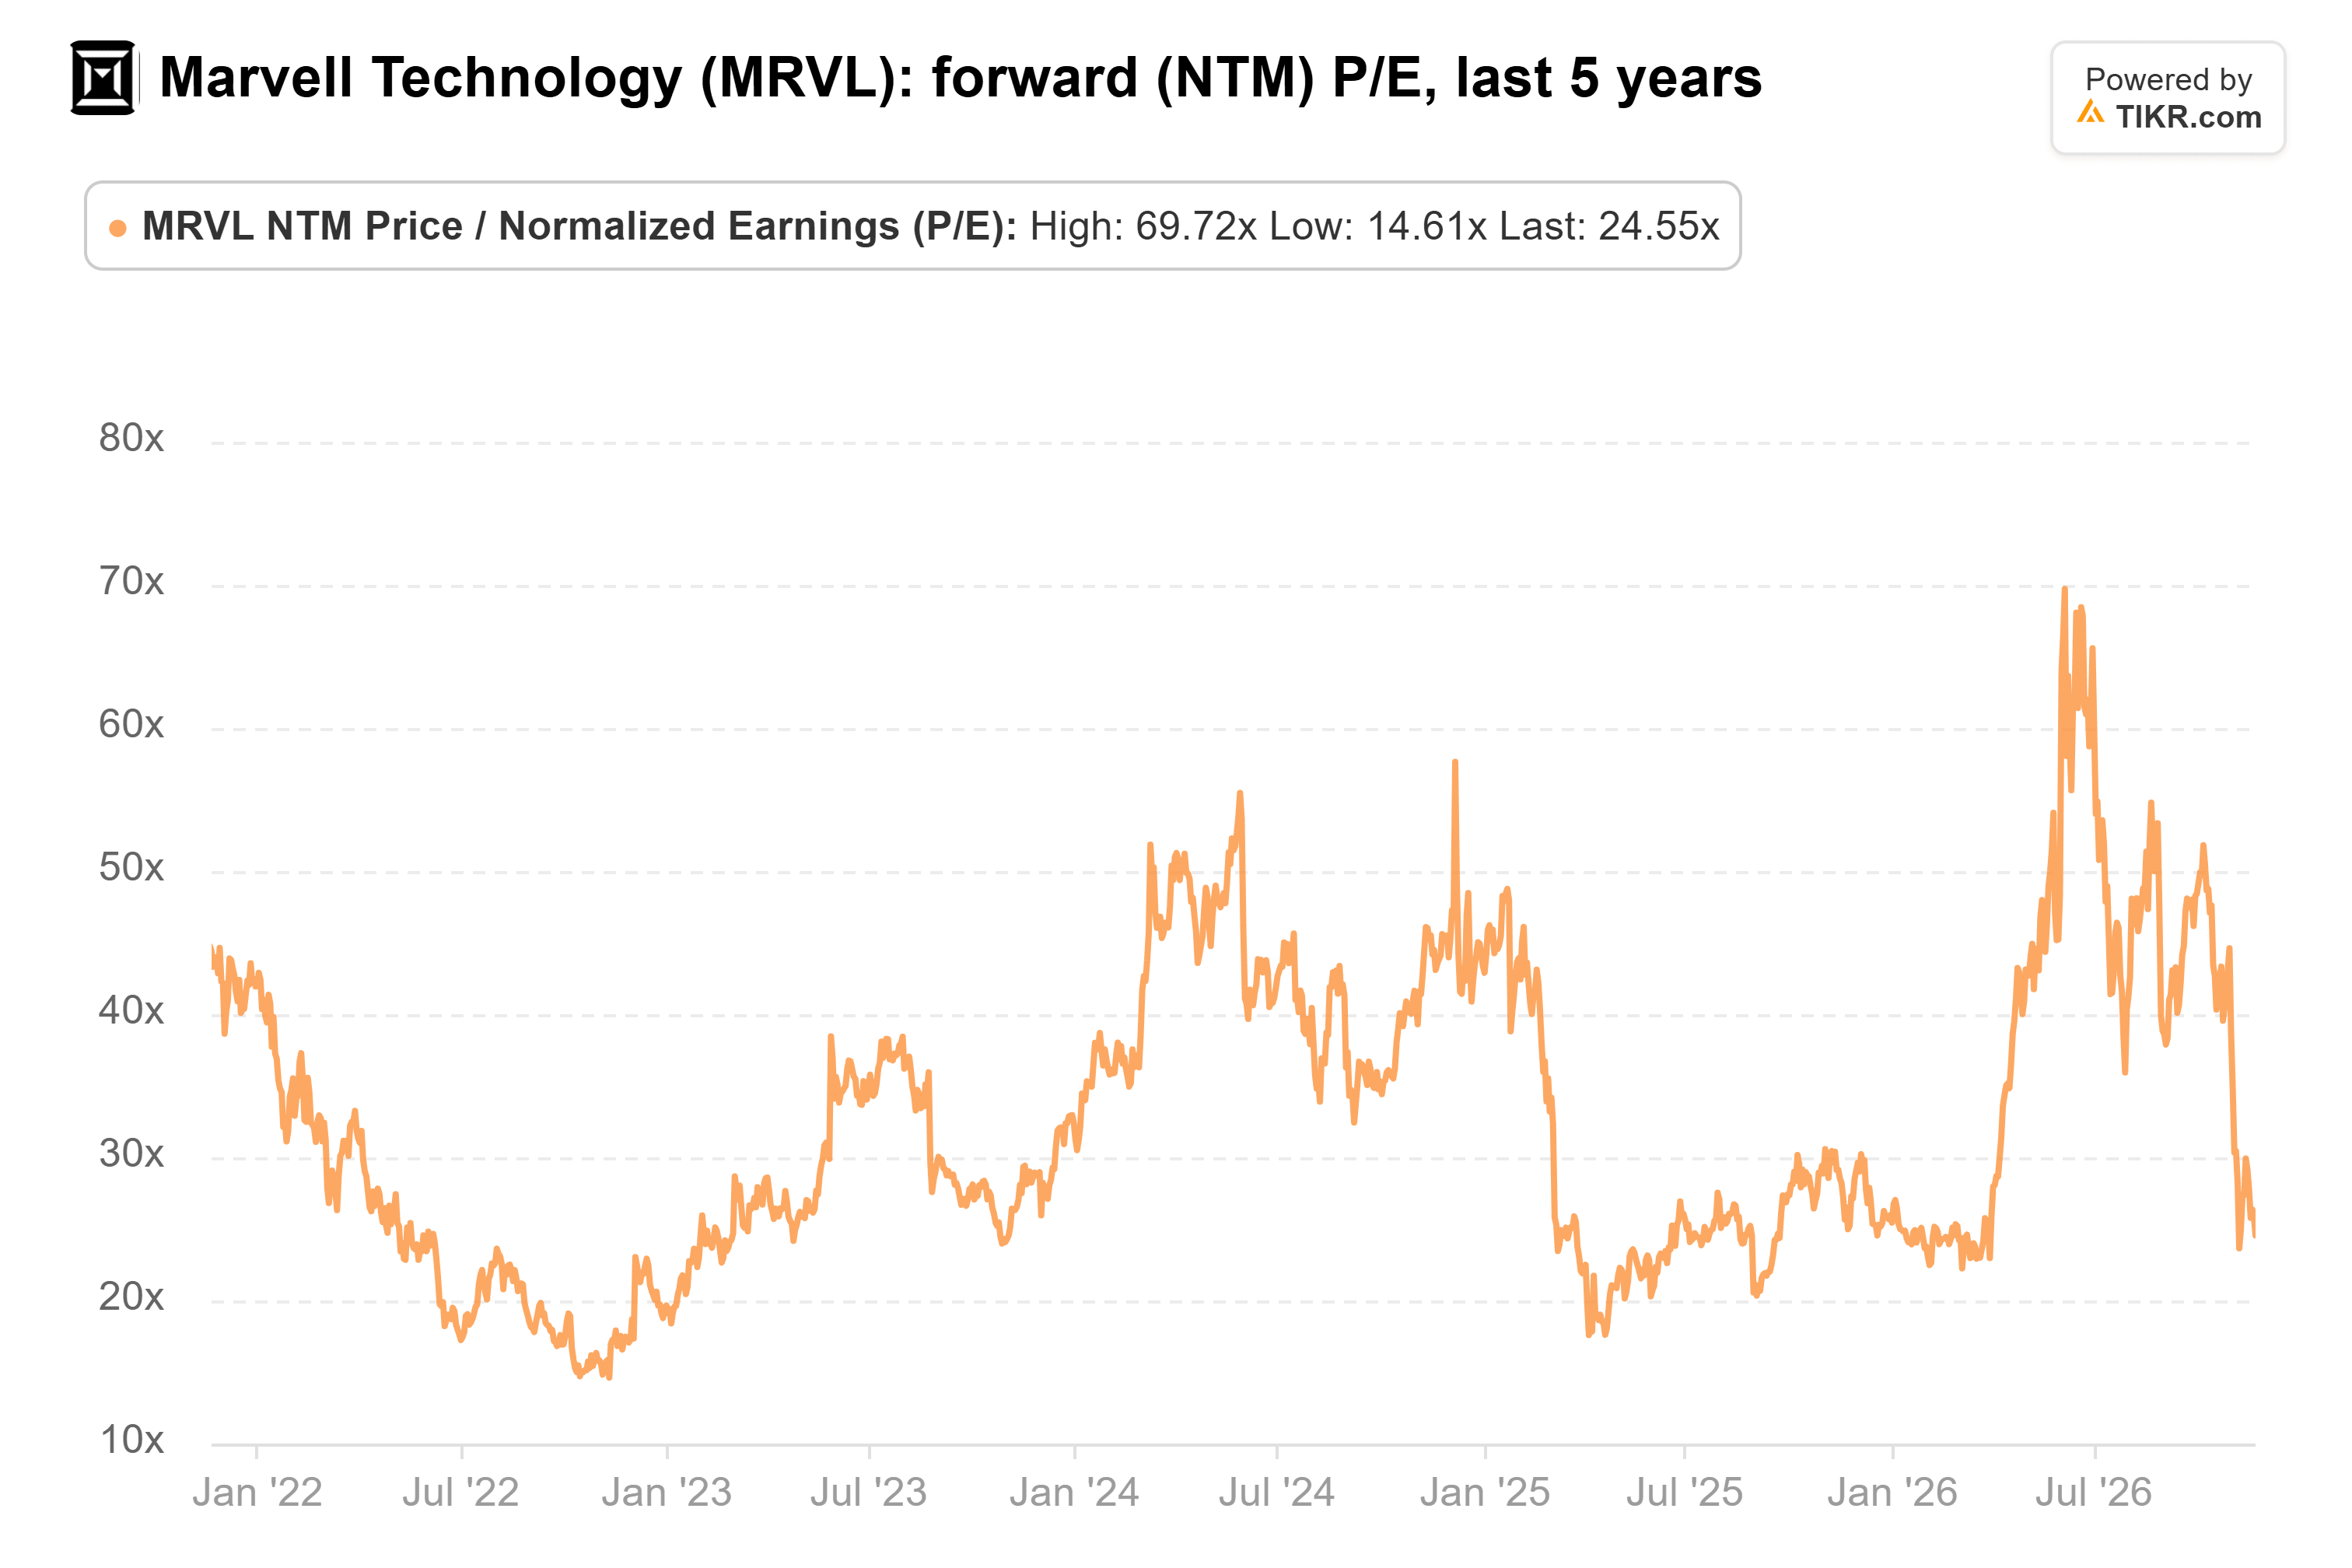
A year from now, investors will be pricing fiscal 2029, and $425 is about 33x that $12.76. Today, Marvell trades at about 17x fiscal 2028’s $7.37. So the target needs the multiple to roughly double and earnings to jump 73% in fiscal 2029. For context, Marvell’s forward P/E was about 25x before Friday’s drop, against a five-year average of 32x:
TIKR Tracks 43 Analysts on Marvell. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Marvell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Marvell’s Analyst Ratings
What Has to Go Right for Marvell
Four customers made up 72% of Marvell’s gross receivables at Aug. 1. It’s also unclear whether the fiscal 2029 estimates include Lumentum, which would add about half again to Marvell’s share count. And Marvell would owe Lumentum $3.2 billion if a final, non-appealable regulatory ruling kills a deal that could otherwise close.
Still, I think Oppenheimer has the better side of this one. The stock has gotten cheaper while the estimates have gone up, even if $425 needs both a higher multiple and those estimates to land.
Marvell reports third-quarter results on Dec. 1. With revenue all but set, watch whether non-GAAP gross margin lands inside the 57.5% to 58.5% guide, and whether management sticks with its roughly $20 billion revenue outlook for fiscal 2028.
So What Is Marvell Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Marvell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!