Key Takeaways
- Bloom Energy fell 26% in the past week as Nvidia’s turmoil hit AI power stocks, Vertiv and Oracle included.
- Bloom had no news of its own, and its raised guidance and big orders still stand.
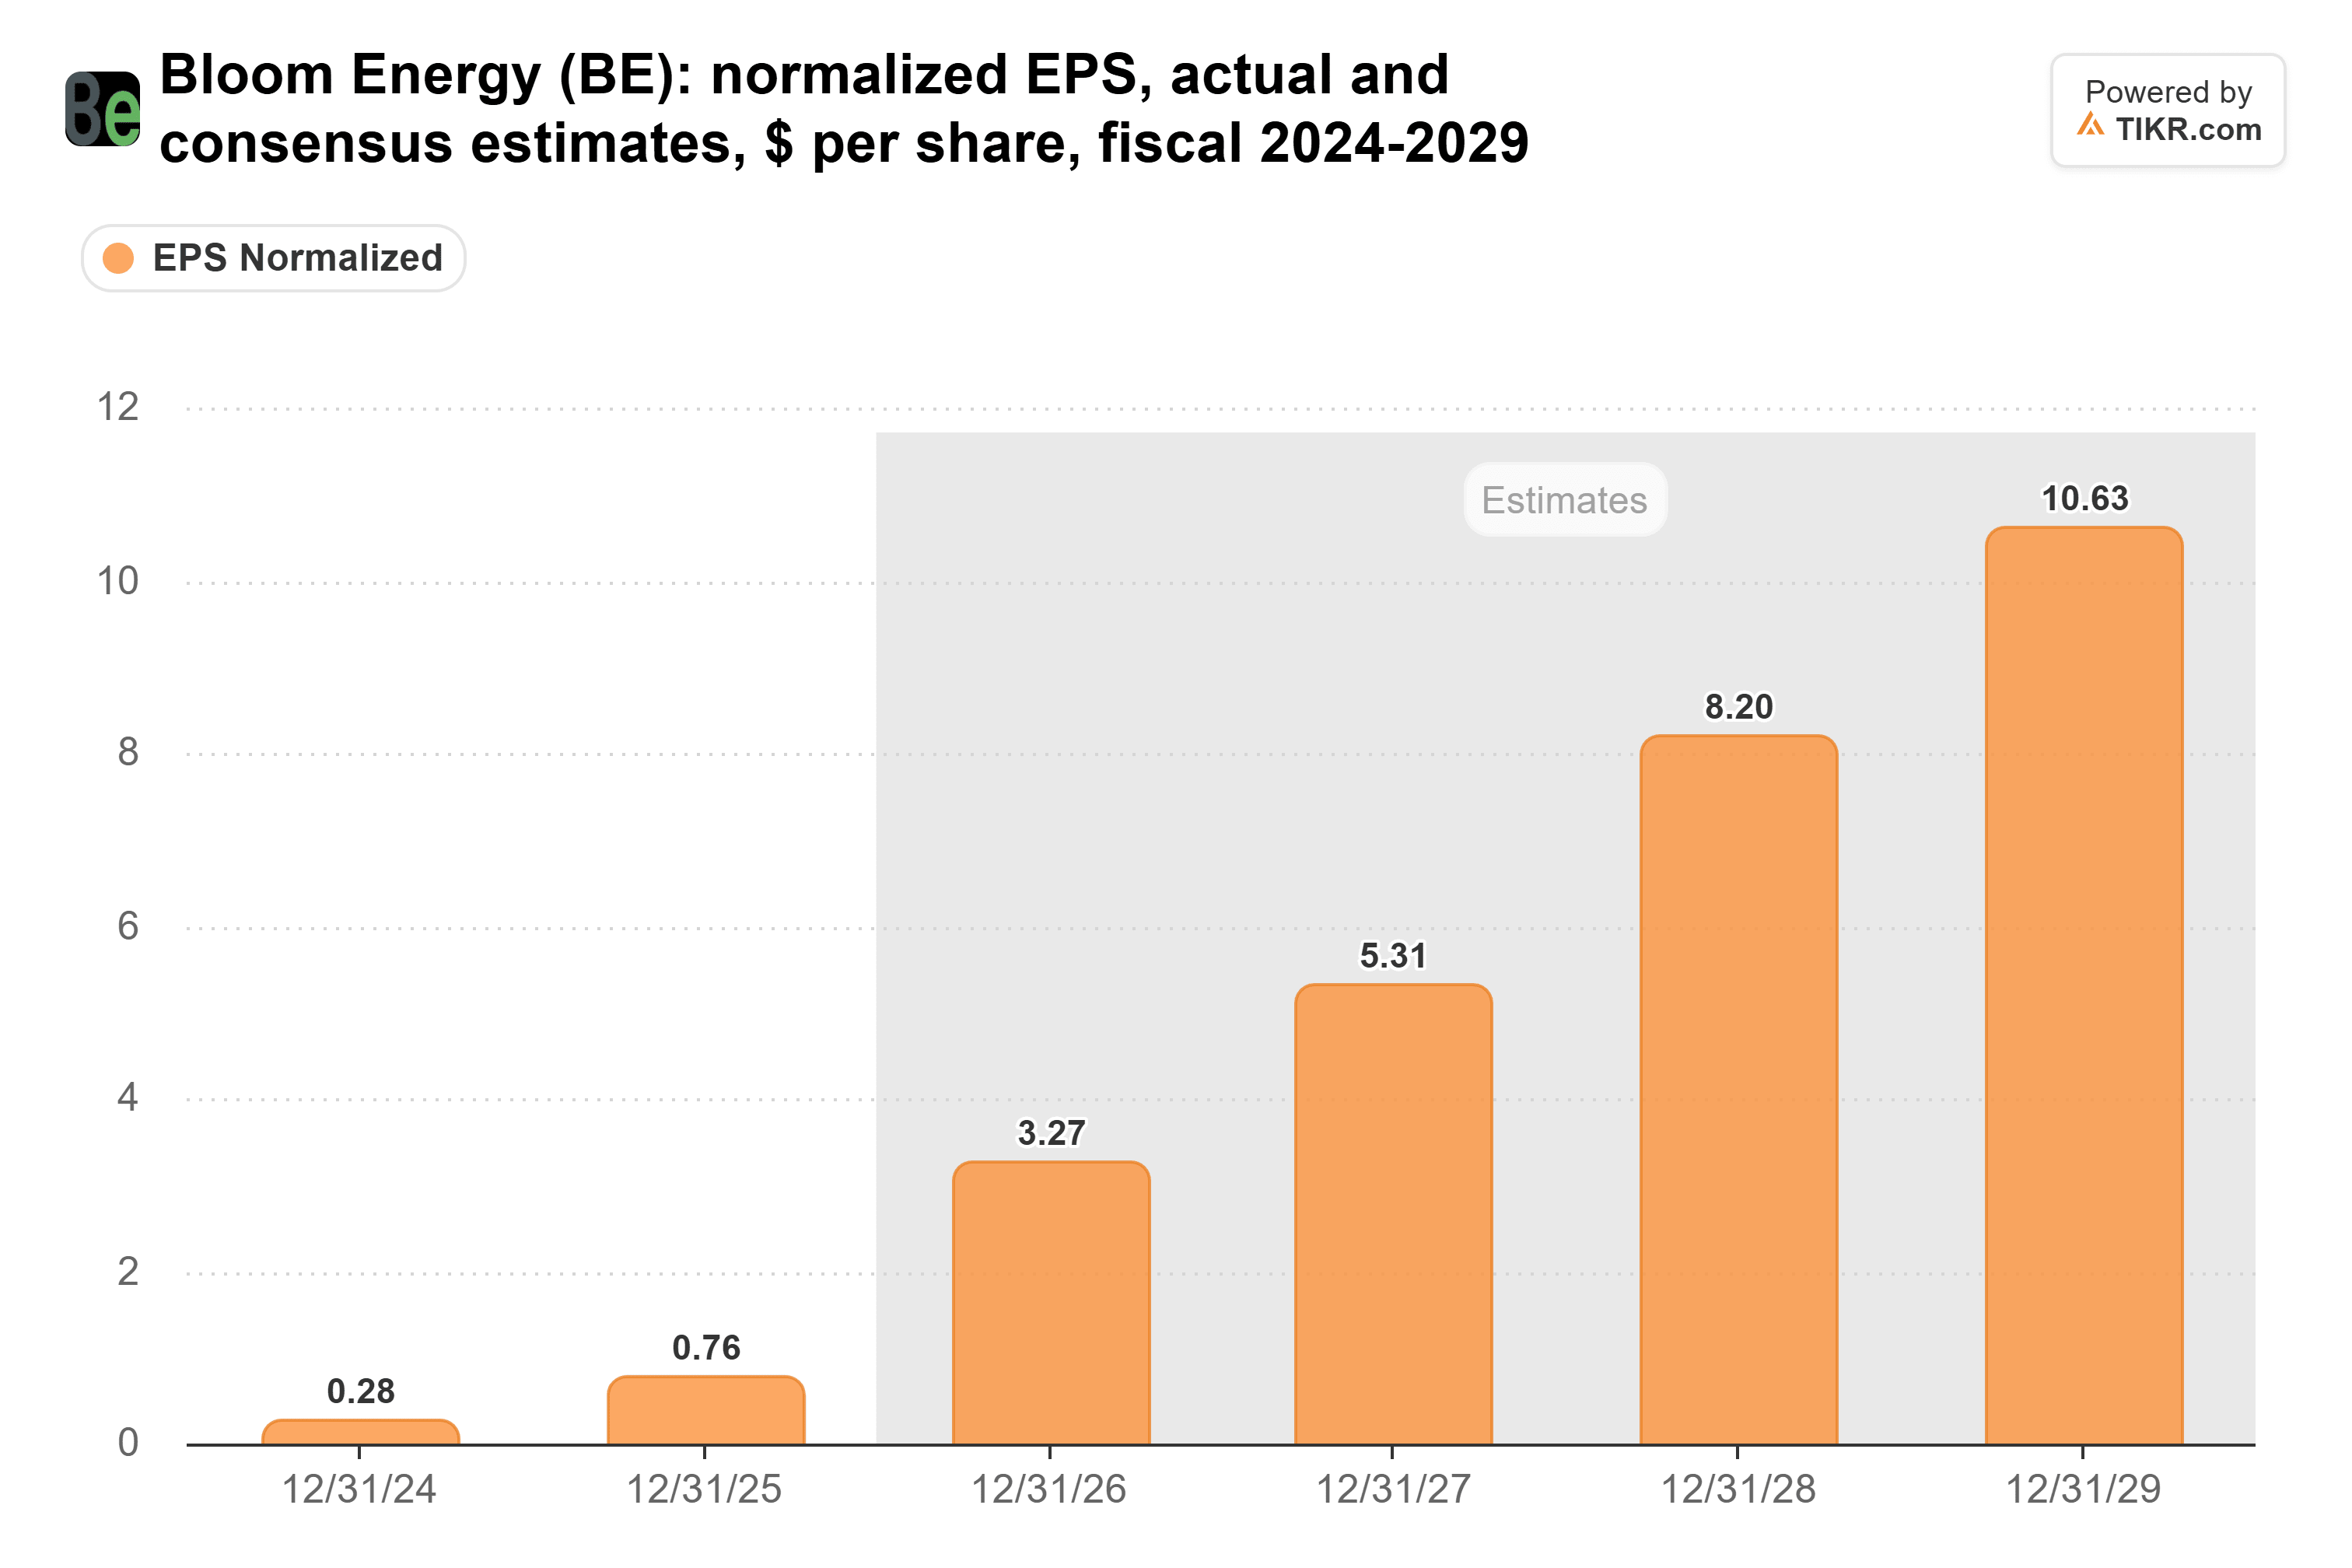
- Analysts still expect normalized EPS of $8.20 in 2028, up from $0.76 in 2025.
- The stock looks like a buy near the low end of its forward P/E range, and Bloom’s fourth-quarter cash flow is the test.
Bloom Energy (BE) is down 26% in the past week with no news of its own. The selling started at Nvidia (NVDA) and spread to Vertiv (VRT) and Oracle (ORCL), the customer behind Bloom’s biggest order.
Two Nvidia headlines did the damage
considering bringing him back. After the close on Nov. 19, reports said California’s attorney general had served Nvidia with an investigative subpoena, and the next day’s selling hit chip and data-center stocks alike. The S&P 500 ended the week down 9% and the Nasdaq 100 down 10%.
Bloom’s orders are all still there
In its record October quarter, revenue rose 138% to $1.24 billion, and management raised its 2026 revenue guidance for the third time, to $4.4 billion-$4.6 billion. Bloom has also kept signing customers, with NTT DATA’s 900 megawatts on top of Oracle’s 2.8 gigawatts. But 97% of third-quarter revenue came from the US, so every scare over American data-center spending lands on Bloom.
Analysts still expect normalized EPS to grow more than tenfold by 2028:
Vertiv, down 18%, shows the spending hasn’t stopped: Vertiv’s orders more than doubled organically in the third quarter, and net sales rose 61% to $4.31 billion. Oracle, down 19%, is the customer Bloom needs most. Oracle’s free cash flow was negative $5 billion in the quarter ended Aug. 31 as it built data centers. If its mid-December report shows it pulling back, Bloom’s largest order is where I’d look for trouble.
TIKR tracks 29 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
Cheap, as long as the cash comes in
Even before the Nov. 20 drop, Bloom traded at 35x forward earnings. That’s near the bottom of its range since late 2023, which runs from 29x to 145x and averages 76x.
Cash is Bloom’s weak spot. It only turned free-cash-flow positive in 2024:
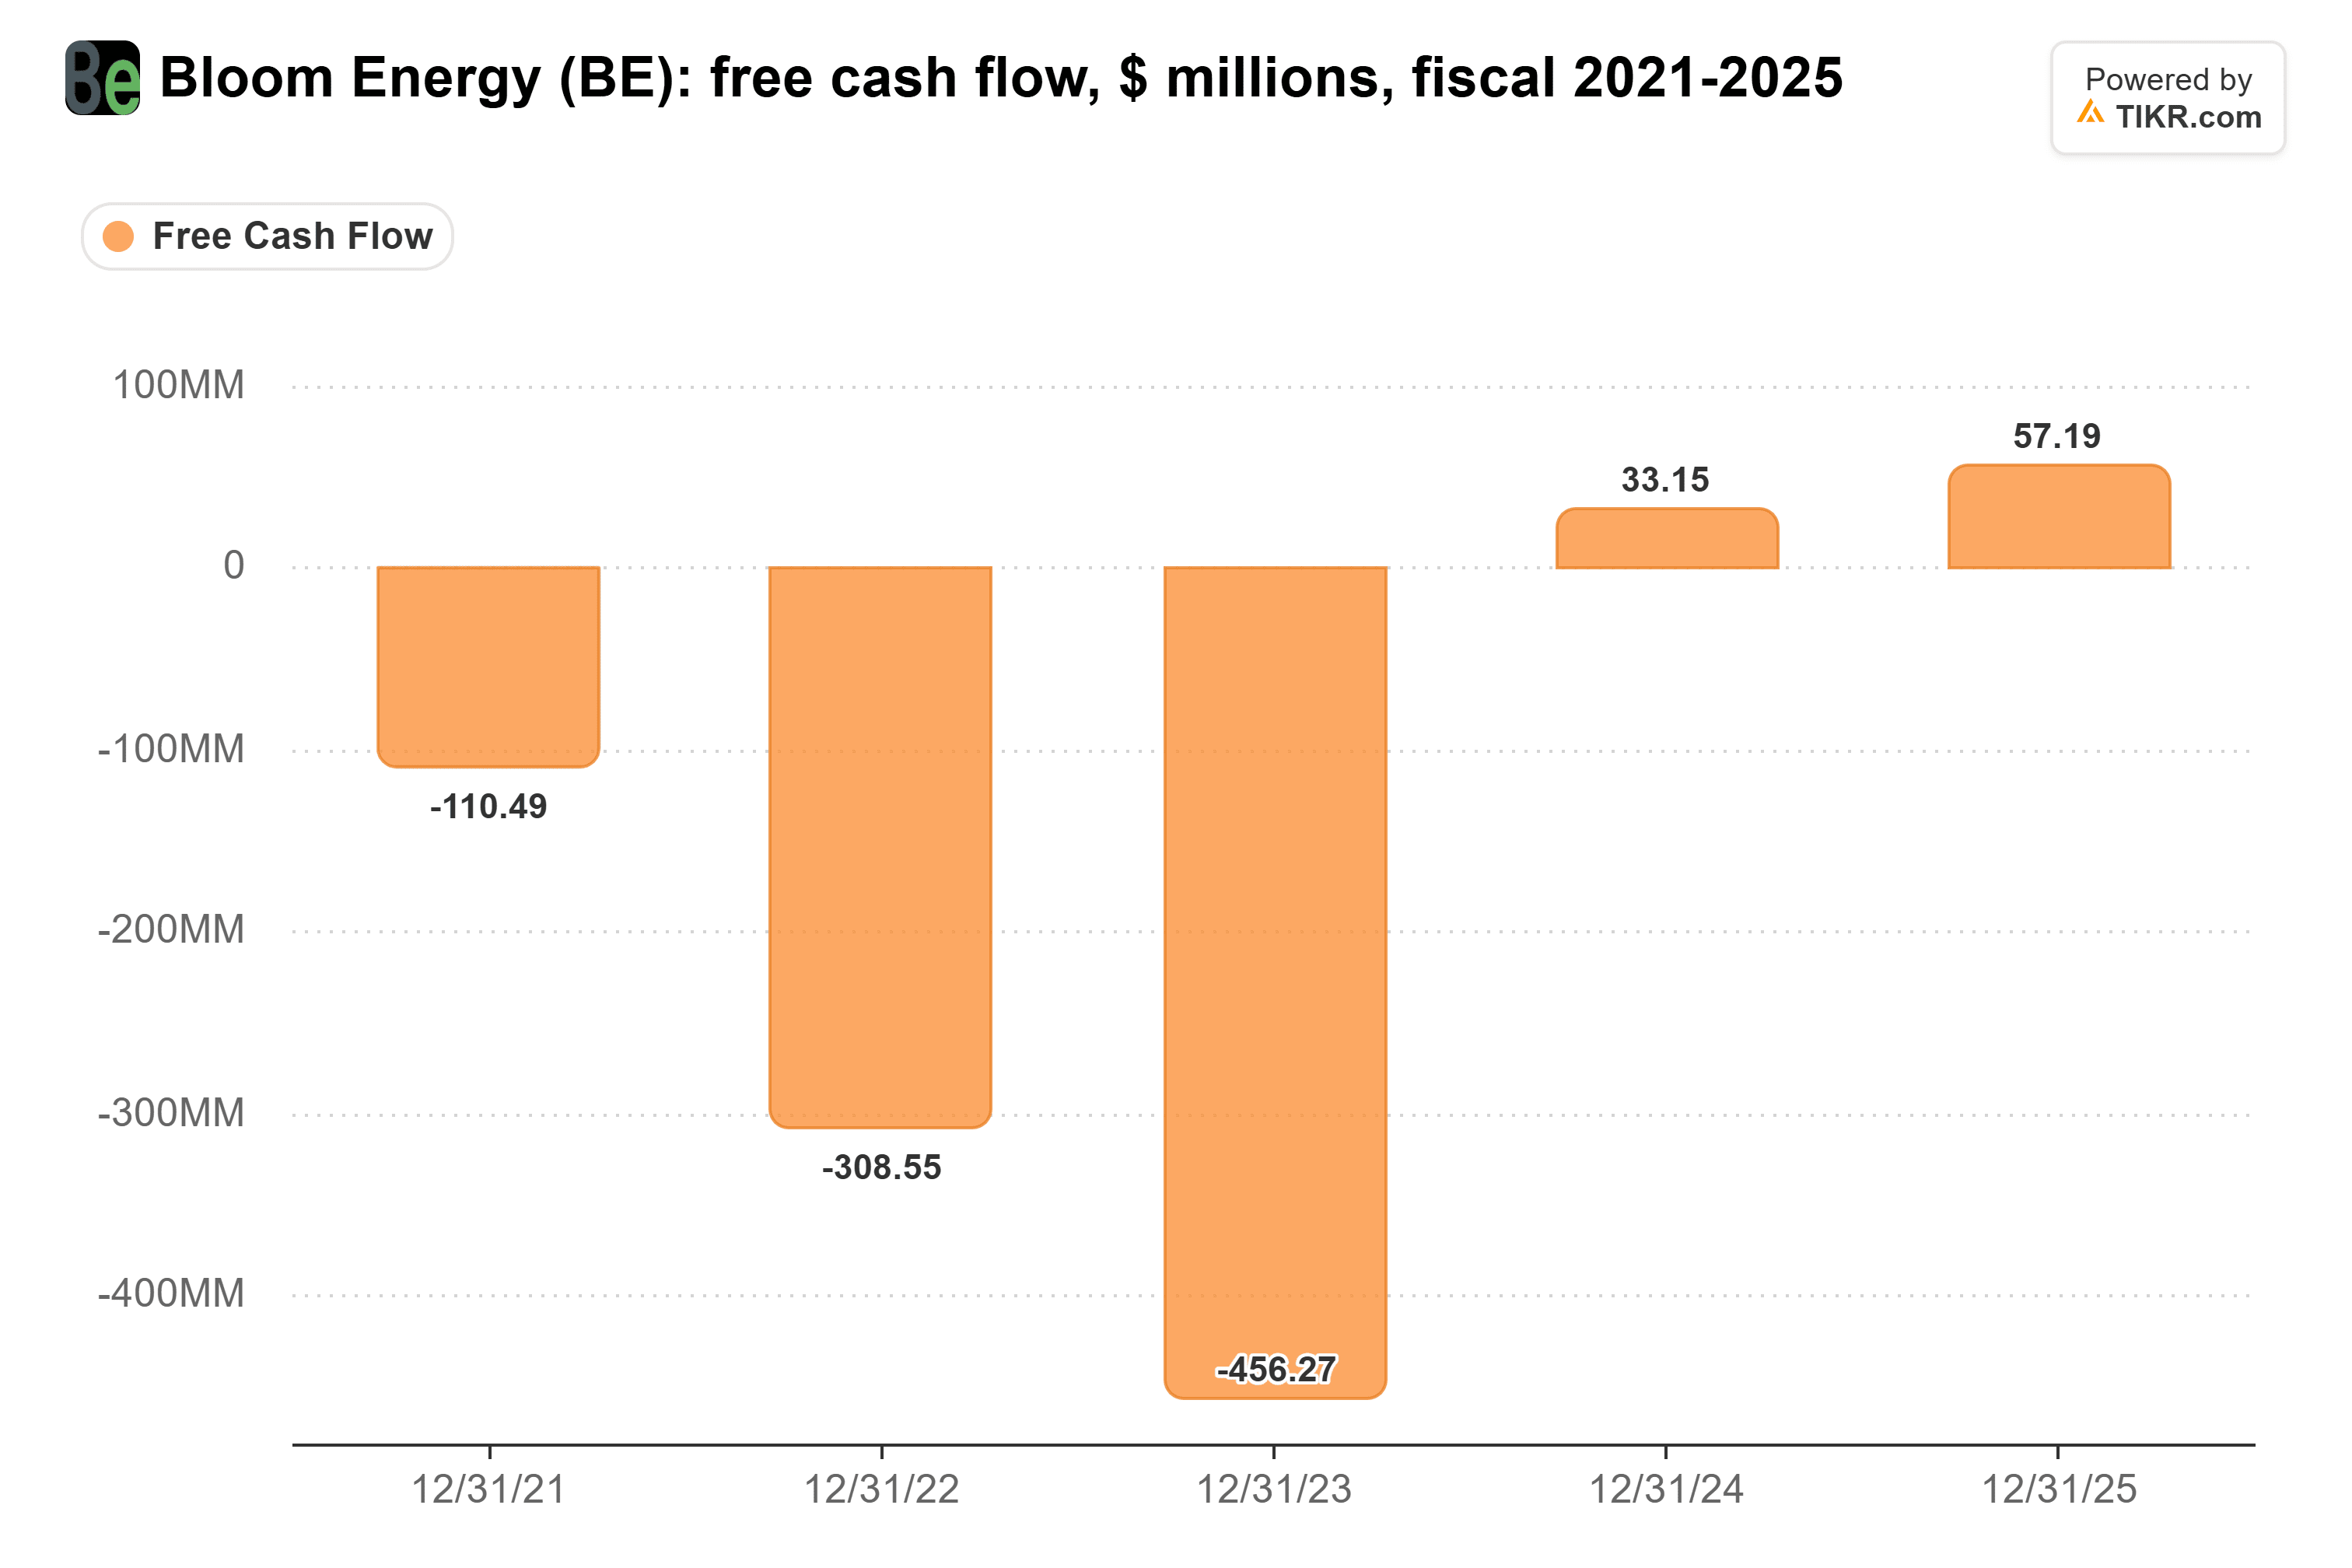
Third-quarter free cash flow was negative $181 million as unbilled revenue climbed to $858.6 million.
Still, I’d buy here, near the low end of Bloom’s usual multiple, with estimates that have barely moved. The test is Bloom’s fourth-quarter report in early 2027: positive free cash flow and unbilled revenue below $858.6 million would back the case.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!