Key Takeaways
- Tremblant Capital Group, a $3.24 billion fund, had sold all of its Howmet Aerospace and Starbucks shares by Sept. 30, its latest 13F shows.
- Since the quarter ended, Howmet is down 8% and Starbucks is up 10%.
- Starbucks trades at about 32x forward earnings, above its long-run average of about 29x, and analysts’ average target is just 8% above the stock.
- Howmet just beat estimates and raised guidance, and analysts’ average target is 42% above the stock, which makes it the one worth buying back.
A $3.24 billion fund just walked away from two of the market’s best-known stocks. Tremblant Capital Group’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows it no longer owns any Howmet Aerospace (HWM) or Starbucks (SBUX).
That $3.24 billion is what Tremblant’s 13F holds in US stocks, spread across 62 positions.
The early scorecard is split
Howmet was the bigger bet. At June 30, Tremblant held 324,954 shares worth $87 million, 2.5% of the fund. Its Starbucks stake was smaller, at 379,456 shares worth $39 million, or 1.1% of the fund.
By Sept. 30, both were gone. A 13F doesn’t say when in the quarter a fund sold, or at what price, so the fairest way to keep score is from each stock’s quarter-end price. On that basis, Howmet has fallen 8% since Sept. 30, and Starbucks has climbed 10%.
TIKR tracks 22 analysts on Howmet Aerospace. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Howmet Aerospace, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Howmet Aerospace’s Analyst Ratings
Howmet’s business hasn’t slowed down
Howmet is 33% below its 52-week high, but it keeps beating estimates. On Oct. 29, it reported third-quarter revenue up 29% to $2.70 billion and adjusted EPS up 54% to $1.46, both ahead of estimates. Management raised its 2026 outlook to about $10.3 billion of revenue and $5.49 to $5.51 of adjusted EPS, and the board added $5 billion to the buyback.
The one soft spot was 2027. Howmet’s first guide calls for revenue of about $11.5 billion, up about 12%, well below the 29% it just posted. Management also expects capital spending to stay high into 2028.
Analysts’ average target rose from about $224 a year ago to a peak near $338 in mid-September, and it has drifted down since:
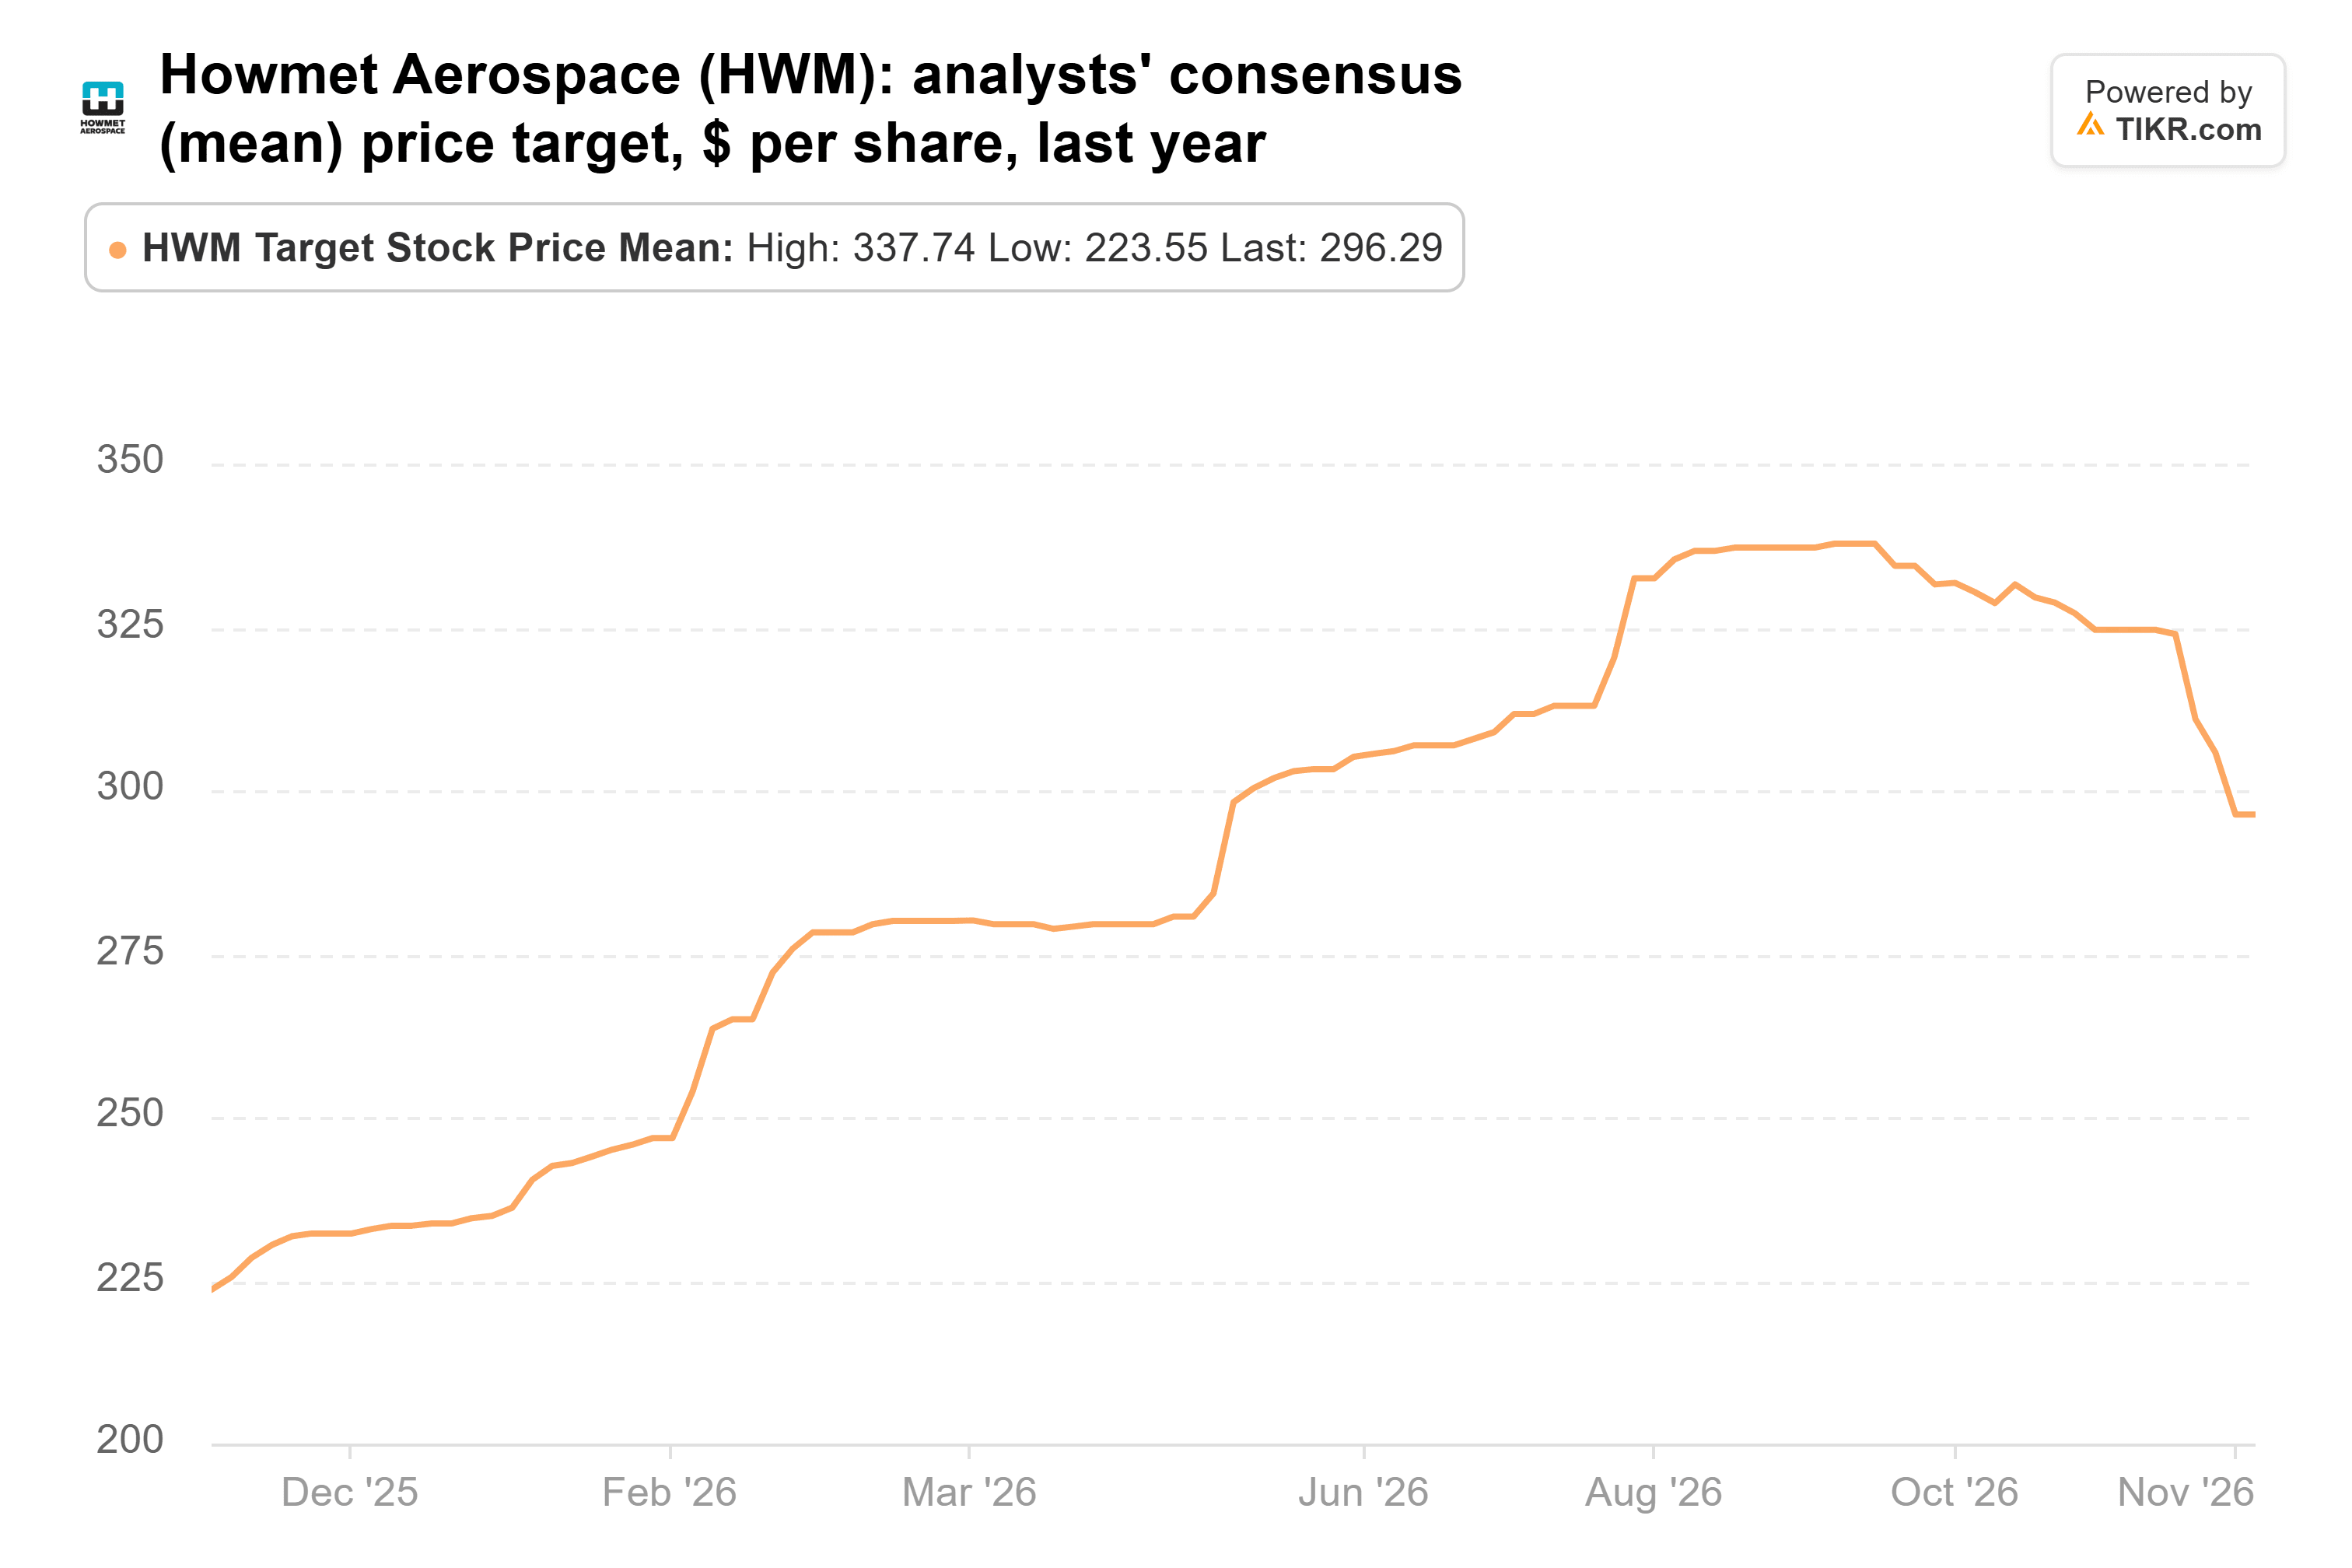
BTIG, for one, cut its target to $280 from $340 on Nov. 3 while keeping a Buy rating. Even so, the $296 average is 42% above the stock. At about 33x forward earnings, Howmet isn’t cheap, and investors are paying that for a company guiding to 12% growth next year.
Starbucks has run ahead of its earnings
Starbucks’ turnaround is real. In its fourth quarter, its adjusted operating margin rose 4.6 points to 14.0%. Management guided fiscal 2027 to an adjusted operating margin of 13.5% to 14.0% and EPS of $3.15 to $3.25, a range that includes slightly more than $0.10 from a 53rd week. But U.S. transactions grew just 2.4%, down from 4.2% the quarter before, so higher tickets did more of the work.
The cash is tighter too. Fiscal 2027’s dividends, restarted buybacks and capital spending add up to about $5.8 billion, against $5.0 billion of operating cash flow in fiscal 2026.
Analysts have been chasing the stock higher, lifting their average target from about $94 a year ago to $111:
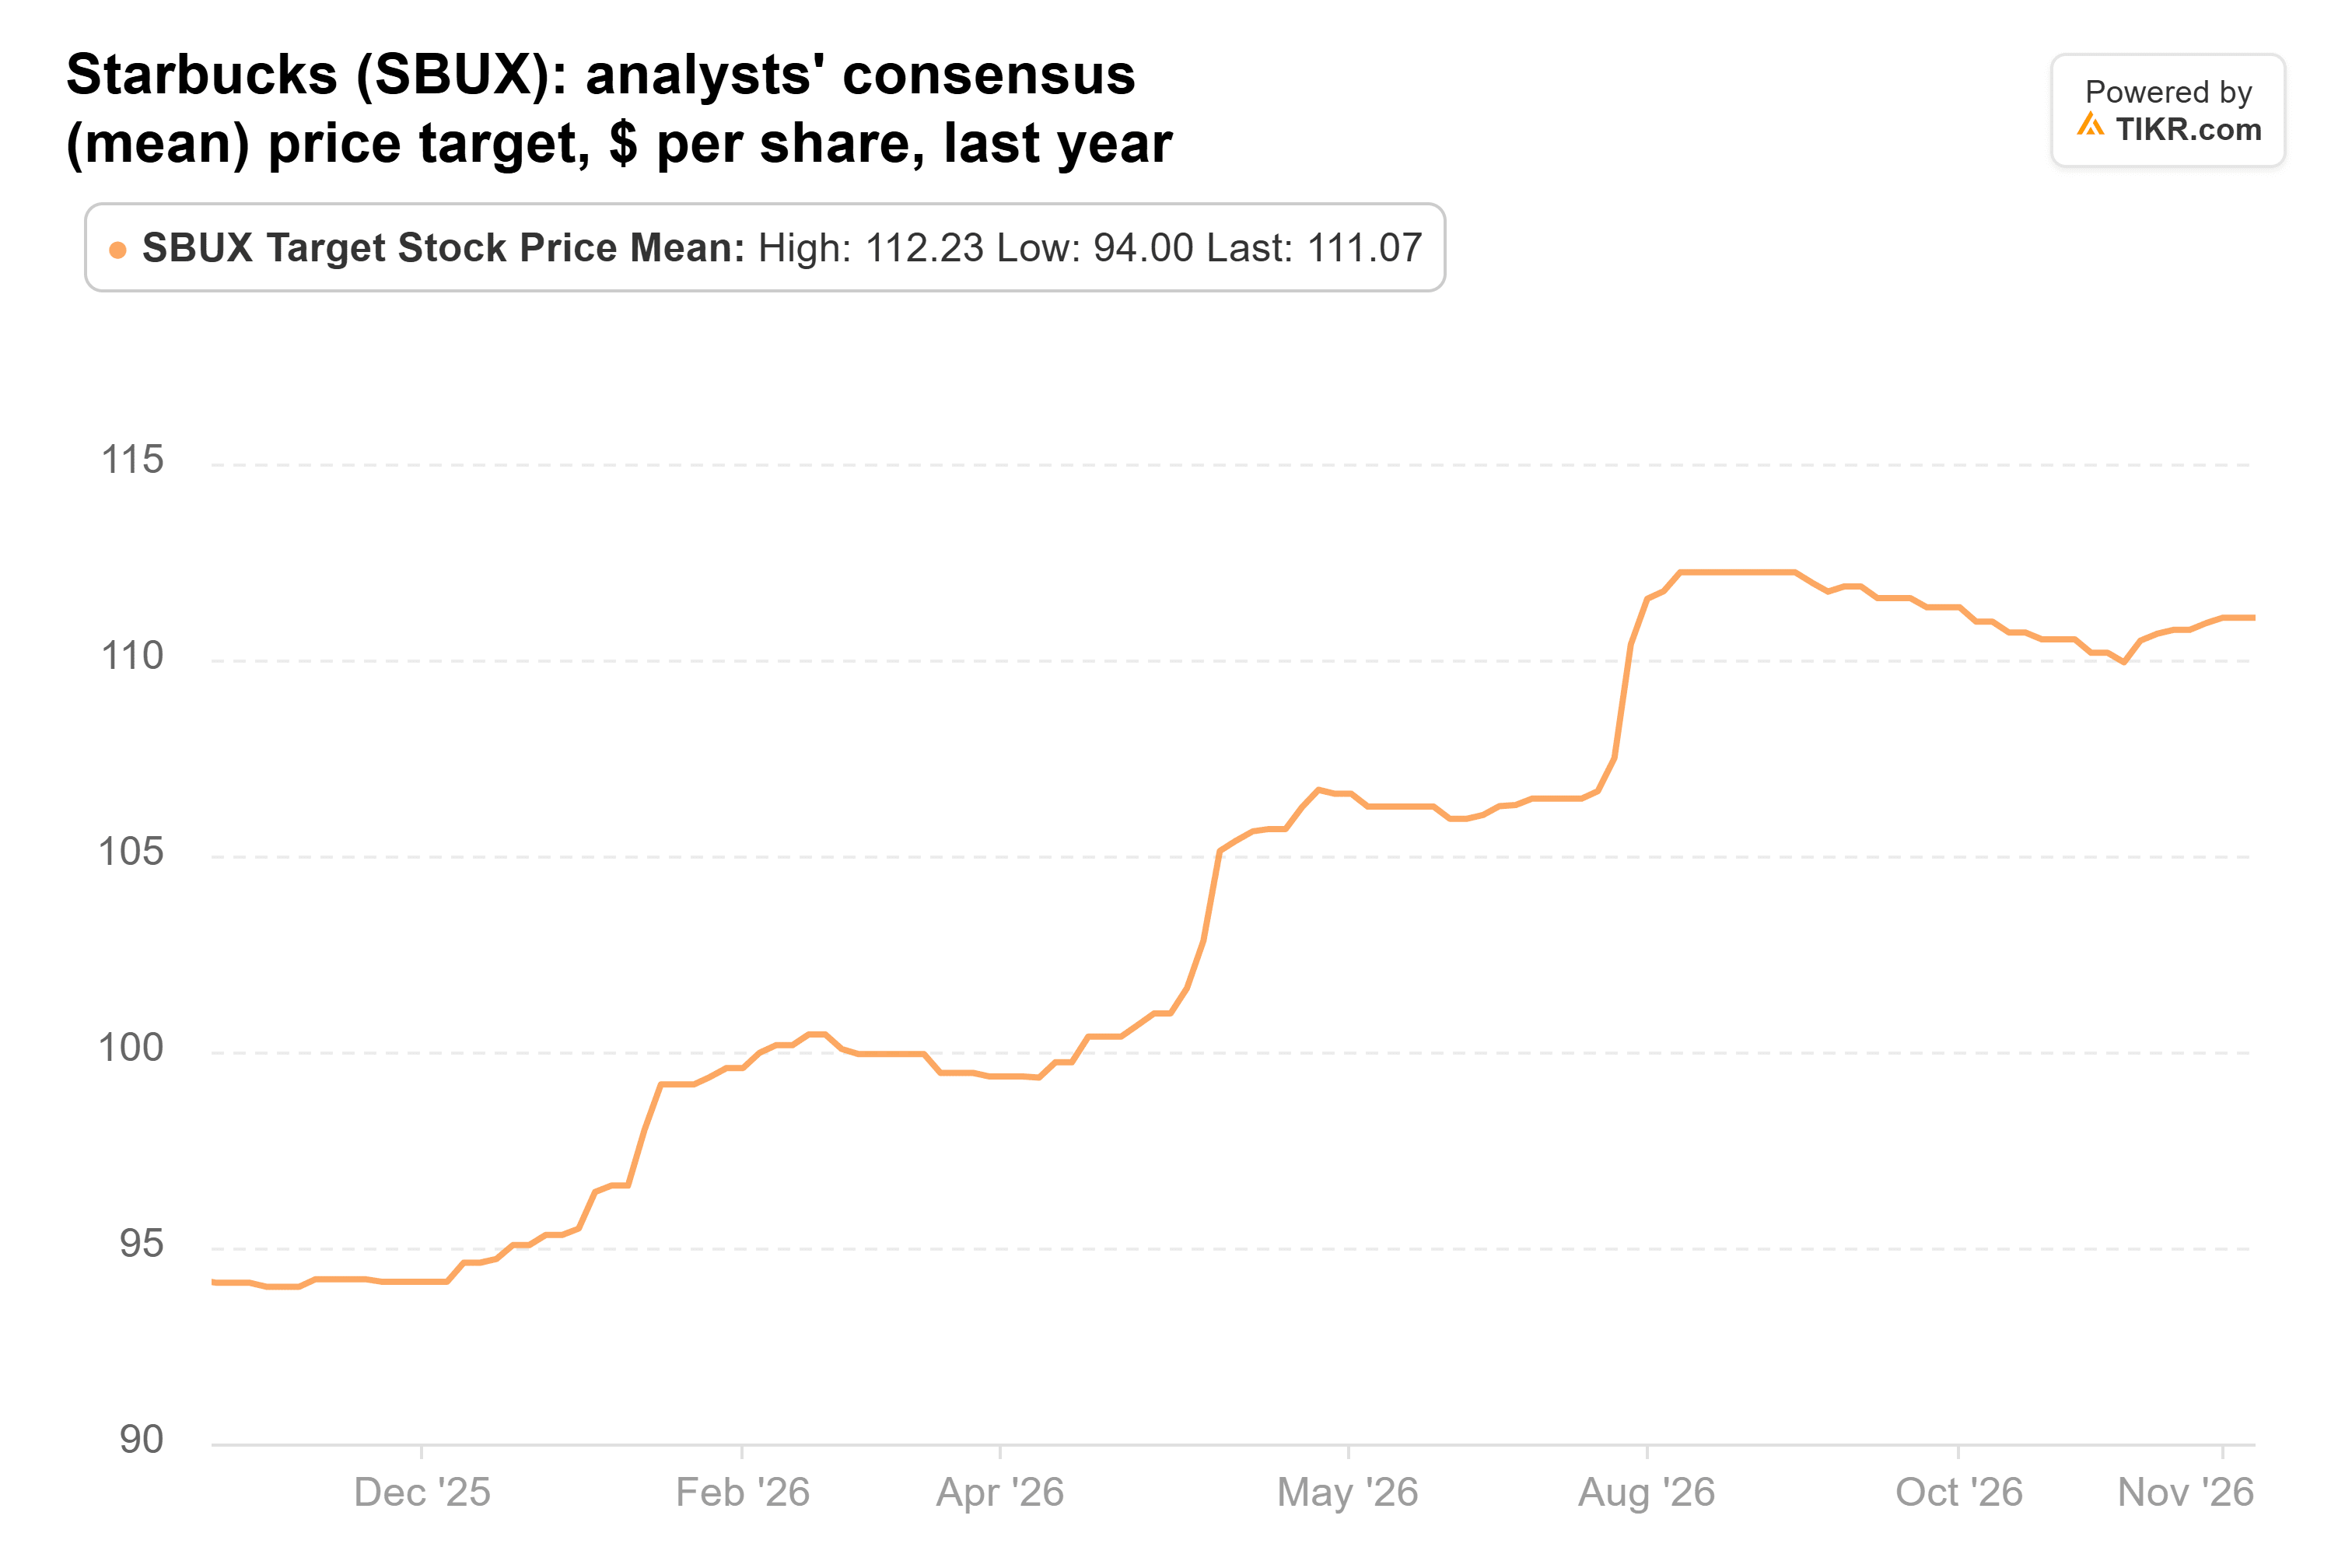
That leaves only 8% of upside. Starbucks trades at about 32x forward earnings, above its average of about 29x since 2014. Put fiscal 2028’s $3.73 consensus EPS on that average multiple, and you get about $109, a few dollars above today’s price. So the Street’s target doesn’t need a higher multiple, but there’s little room if the margin plan slips.
Howmet is the one I’d buy back
So far, the Howmet sale looks like the better call. From here, I’d judge the two differently.
At 32x, Starbucks’ price already reflects much of its margin recovery. With the Street’s own target only 8% higher, Tremblant’s exit looks reasonable. Howmet is harder to let go of: revenue is up 29%, guidance went up, and analysts still see 42% upside. The risk is that growth roughly halves next year while the stock trades at about 33x forward earnings.
If I had to buy one of these back today, it’d be Howmet, since it keeps beating estimates while its stock falls.
Howmet reports its fourth quarter in February, against guidance of about $2.75 billion of revenue. Starbucks reports in late January, and U.S. transactions need to grow faster than 2.4% to back up its rally. Tremblant’s next 13F, due by mid-February, will show whether it went back to either one.
So what is Howmet Aerospace stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Howmet Aerospace could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Howmet Aerospace for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!