Key Takeaways
- Bank of America cut its MercadoLibre price target to $2,000 from $2,400 on Nov. 19 and kept its Buy rating, 48% above the Nov. 20 close.
- MercadoLibre is giving up margin to stay ahead of rivals, including Sea Limited’s Shopee in Brazil and Nu Holdings in credit.
- On 2028 earnings estimates, $2,000 is 27x, below any forward multiple the stock has traded at in five years.
- The valuation looks fair, but estimates keep falling, so $2,000 will likely take more than 12 months to reach.
MercadoLibre (MELI) stock has lost 29% in a year, closing at $1,355.00 on Nov. 20. On Nov. 19, Bank of America cut its price target to $2,000 from $2,400 and kept its Buy rating, 48% above that close. The bank also lowered its 2026 to 2028 EPS estimates, saying the company is putting off monetization to reinvest in its lead.
MercadoLibre is spending heavily against two well-funded rivals: Sea Limited (SE)‘s Shopee in Brazil, and Nu Holdings (NU) in credit.
A margin MercadoLibre chose to give up
Sea can afford the fight. Shopee’s adjusted EBITDA rose 44.7% to $269.2 million in the third quarter, its most profitable quarter ever. Sea CEO Forrest Li said Brazil remained Shopee’s fastest-growing market, and its new instant delivery service there already delivers in under four hours from more than 7,000 partner stores.
MercadoLibre’s Nov. 4 report showed the cost of keeping up. Revenue rose 45% to $10.75 billion, but GAAP operating income fell 6.6% to $676 million. That’s a 6.3% margin, against 9.8% a year earlier. Management tied the drop to more free shipping, nearly 20% more fulfillment space added from the prior quarter ahead of peak season, and heavier affiliate marketing in Brazil.
Bank of America is betting on the card
Analyst Robert Ford Aguilar has made Mercado Pago’s credit card a big part of his case. In a June note, he forecast a $443 million EBIT loss on the card in 2026, breakeven in 2028 and $1.5 billion of EBIT by 2030. He put MercadoLibre’s share of Brazil’s card balances at 3.4% in March. Nu’s credit portfolio rose 33% in a year, FX-neutral, while MercadoLibre’s rose 62%, to almost $18 billion.
TIKR tracks 25 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
$2,000 doesn’t need a higher multiple
The Street’s average target has fallen over the past year, to $2,168 from $2,862.
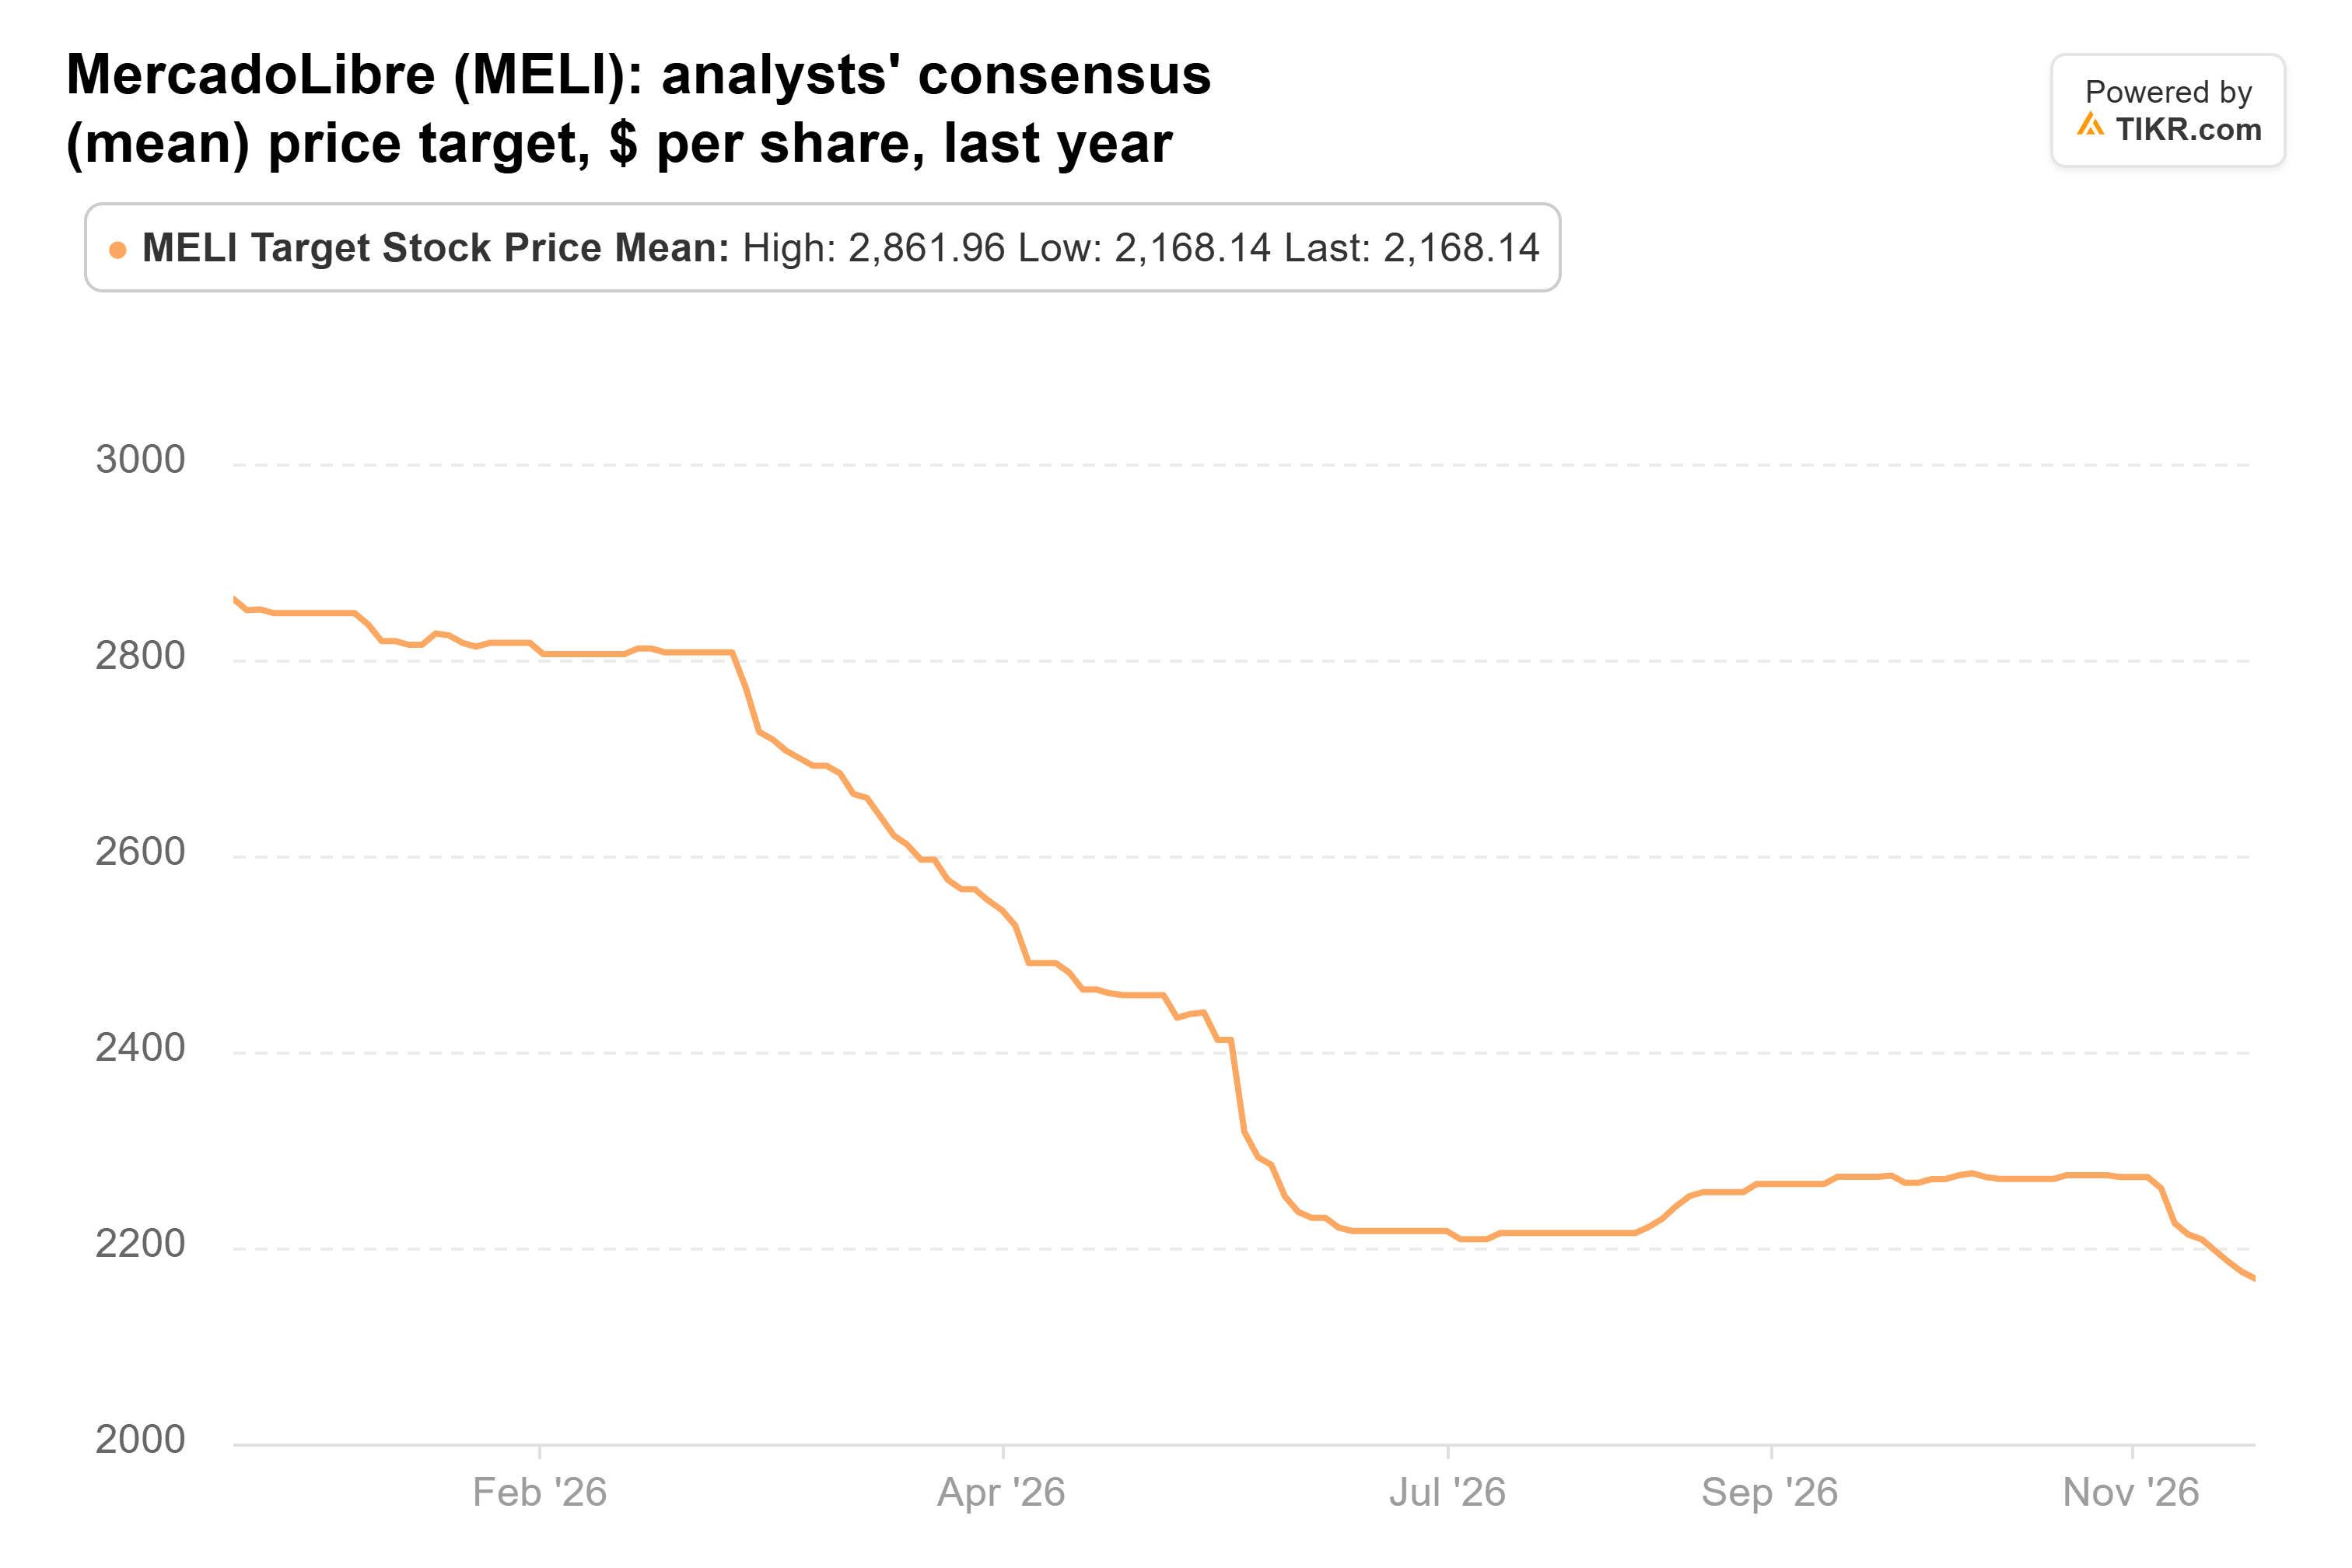
That’s 60% above the Nov. 20 close, and Bank of America’s $2,000 sits 8% below it.
Analysts expect normalized EPS to dip to $36.66 this year, then reach $73.57 by 2028.
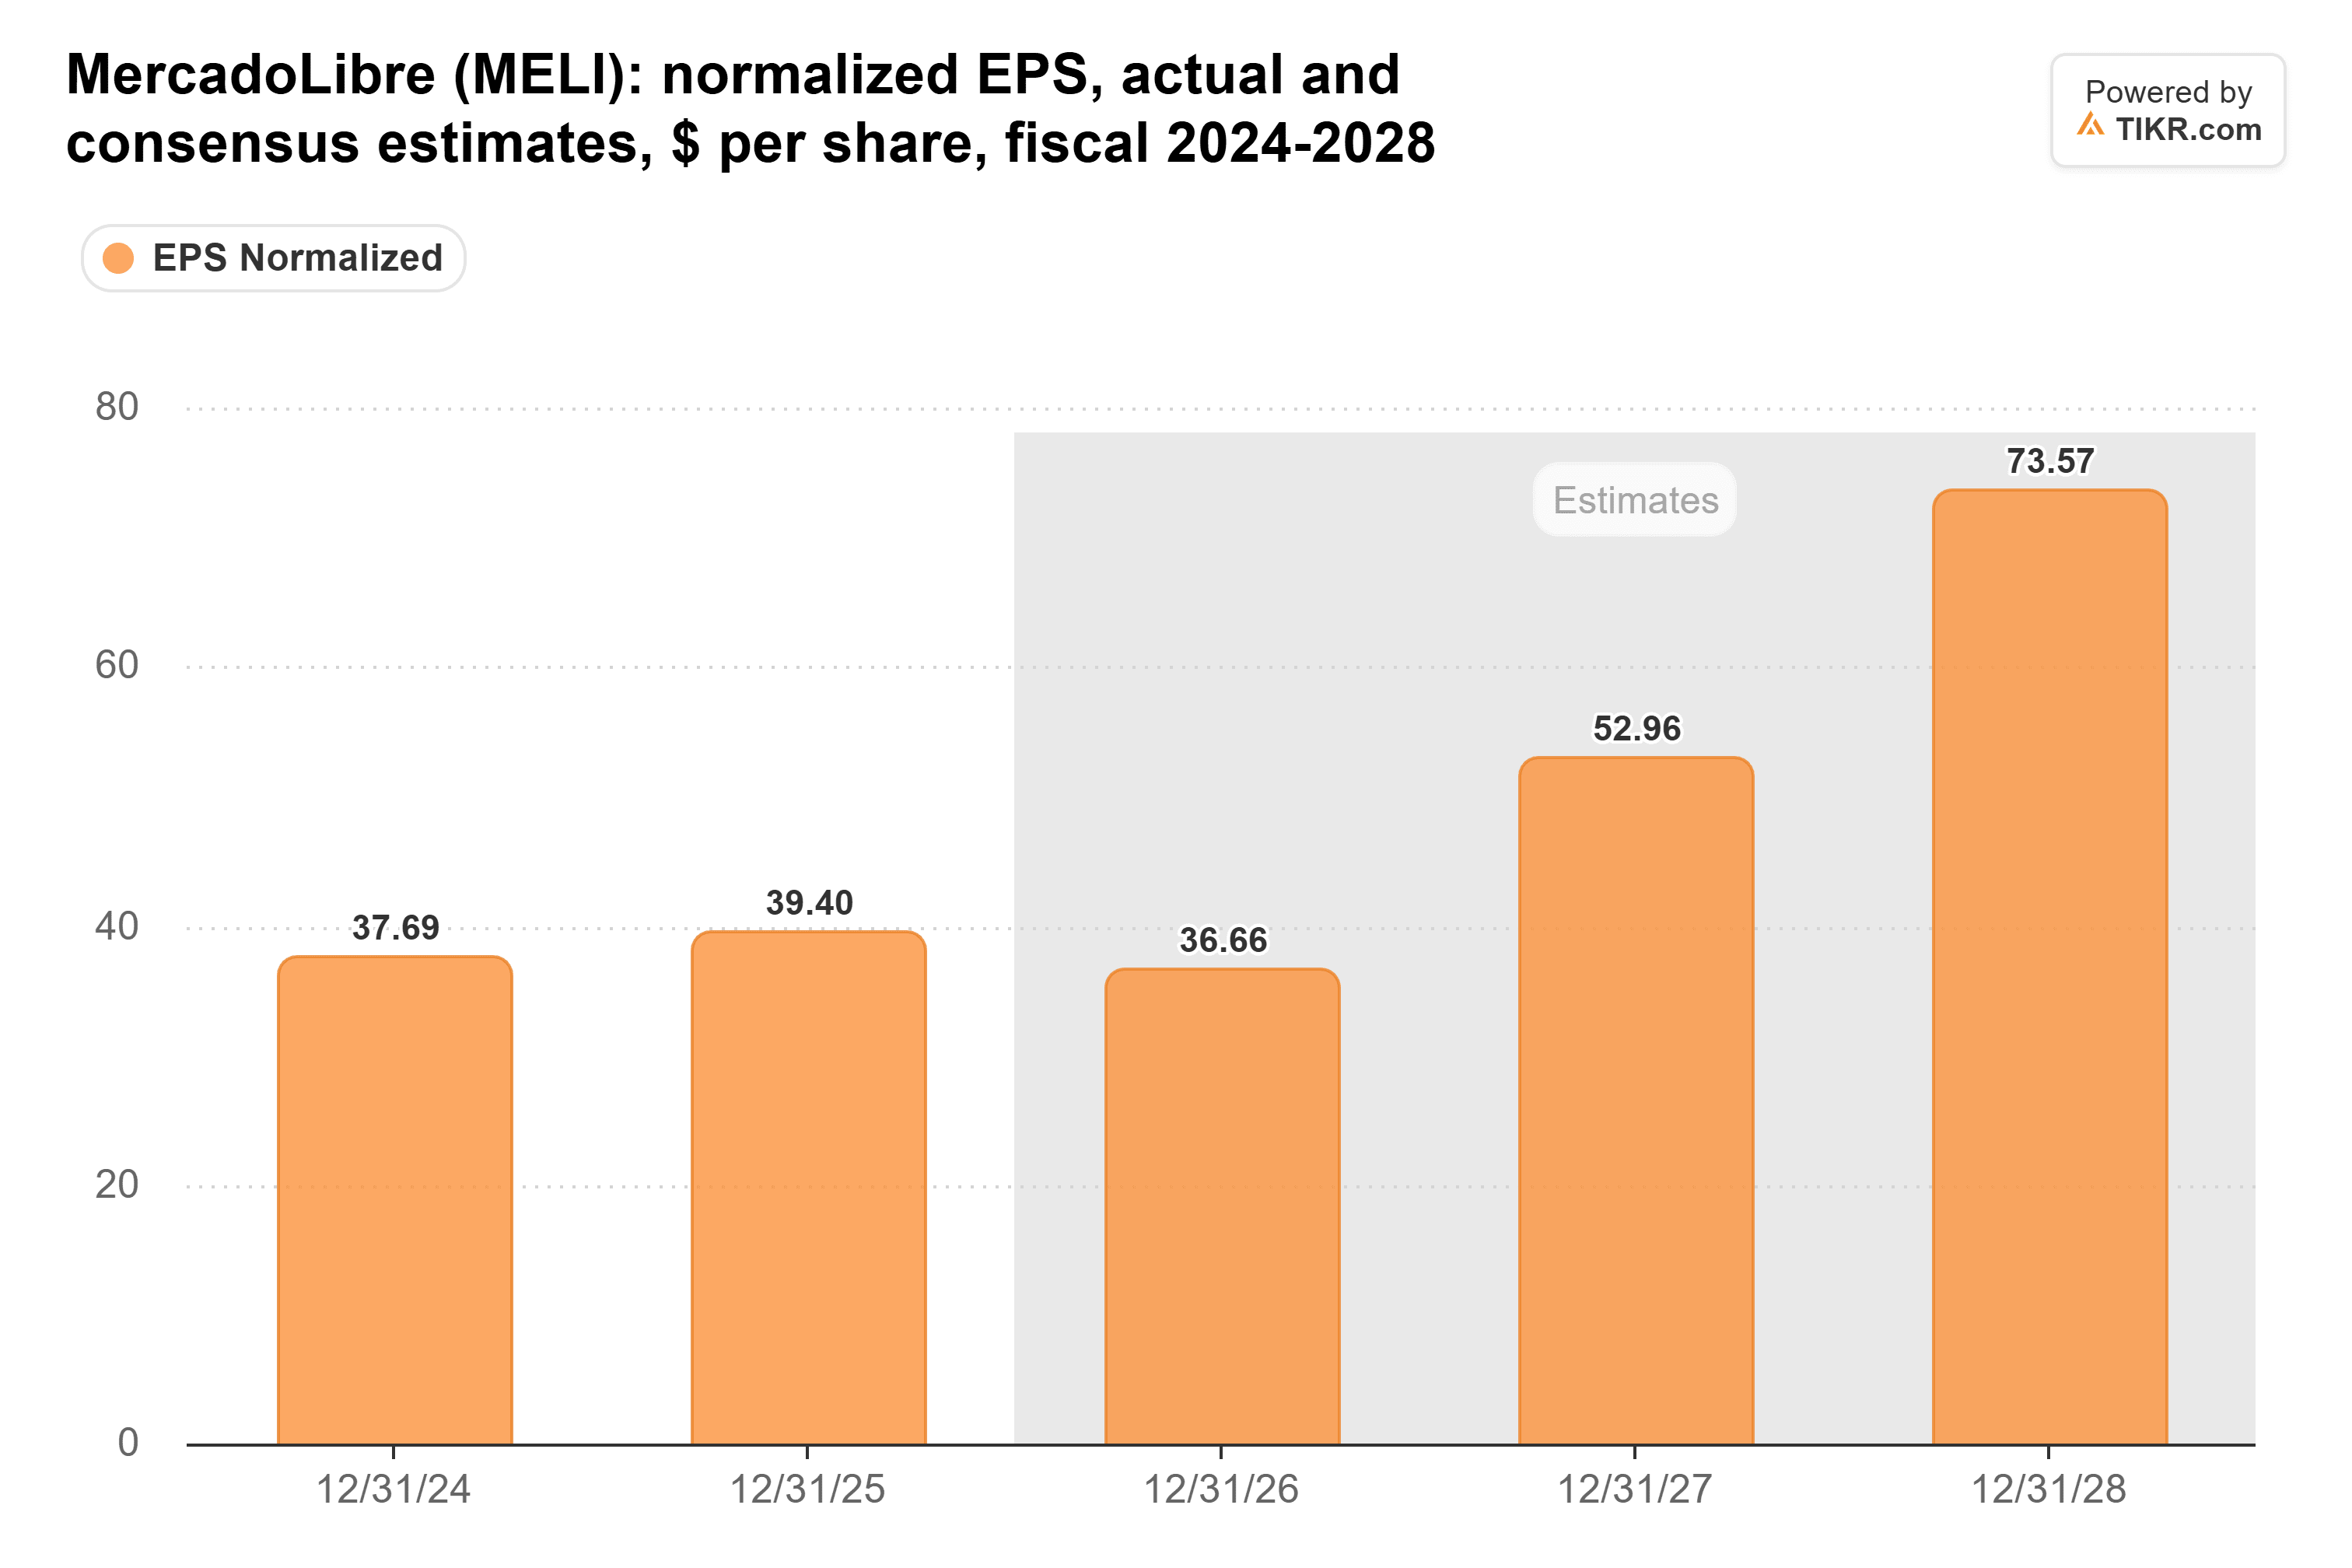
Those estimates are still falling: the Street’s 2027 EPS estimate is about 6% lower than a month ago.
The stock trades at about 31x forward earnings, about half its five-year average of 61x.
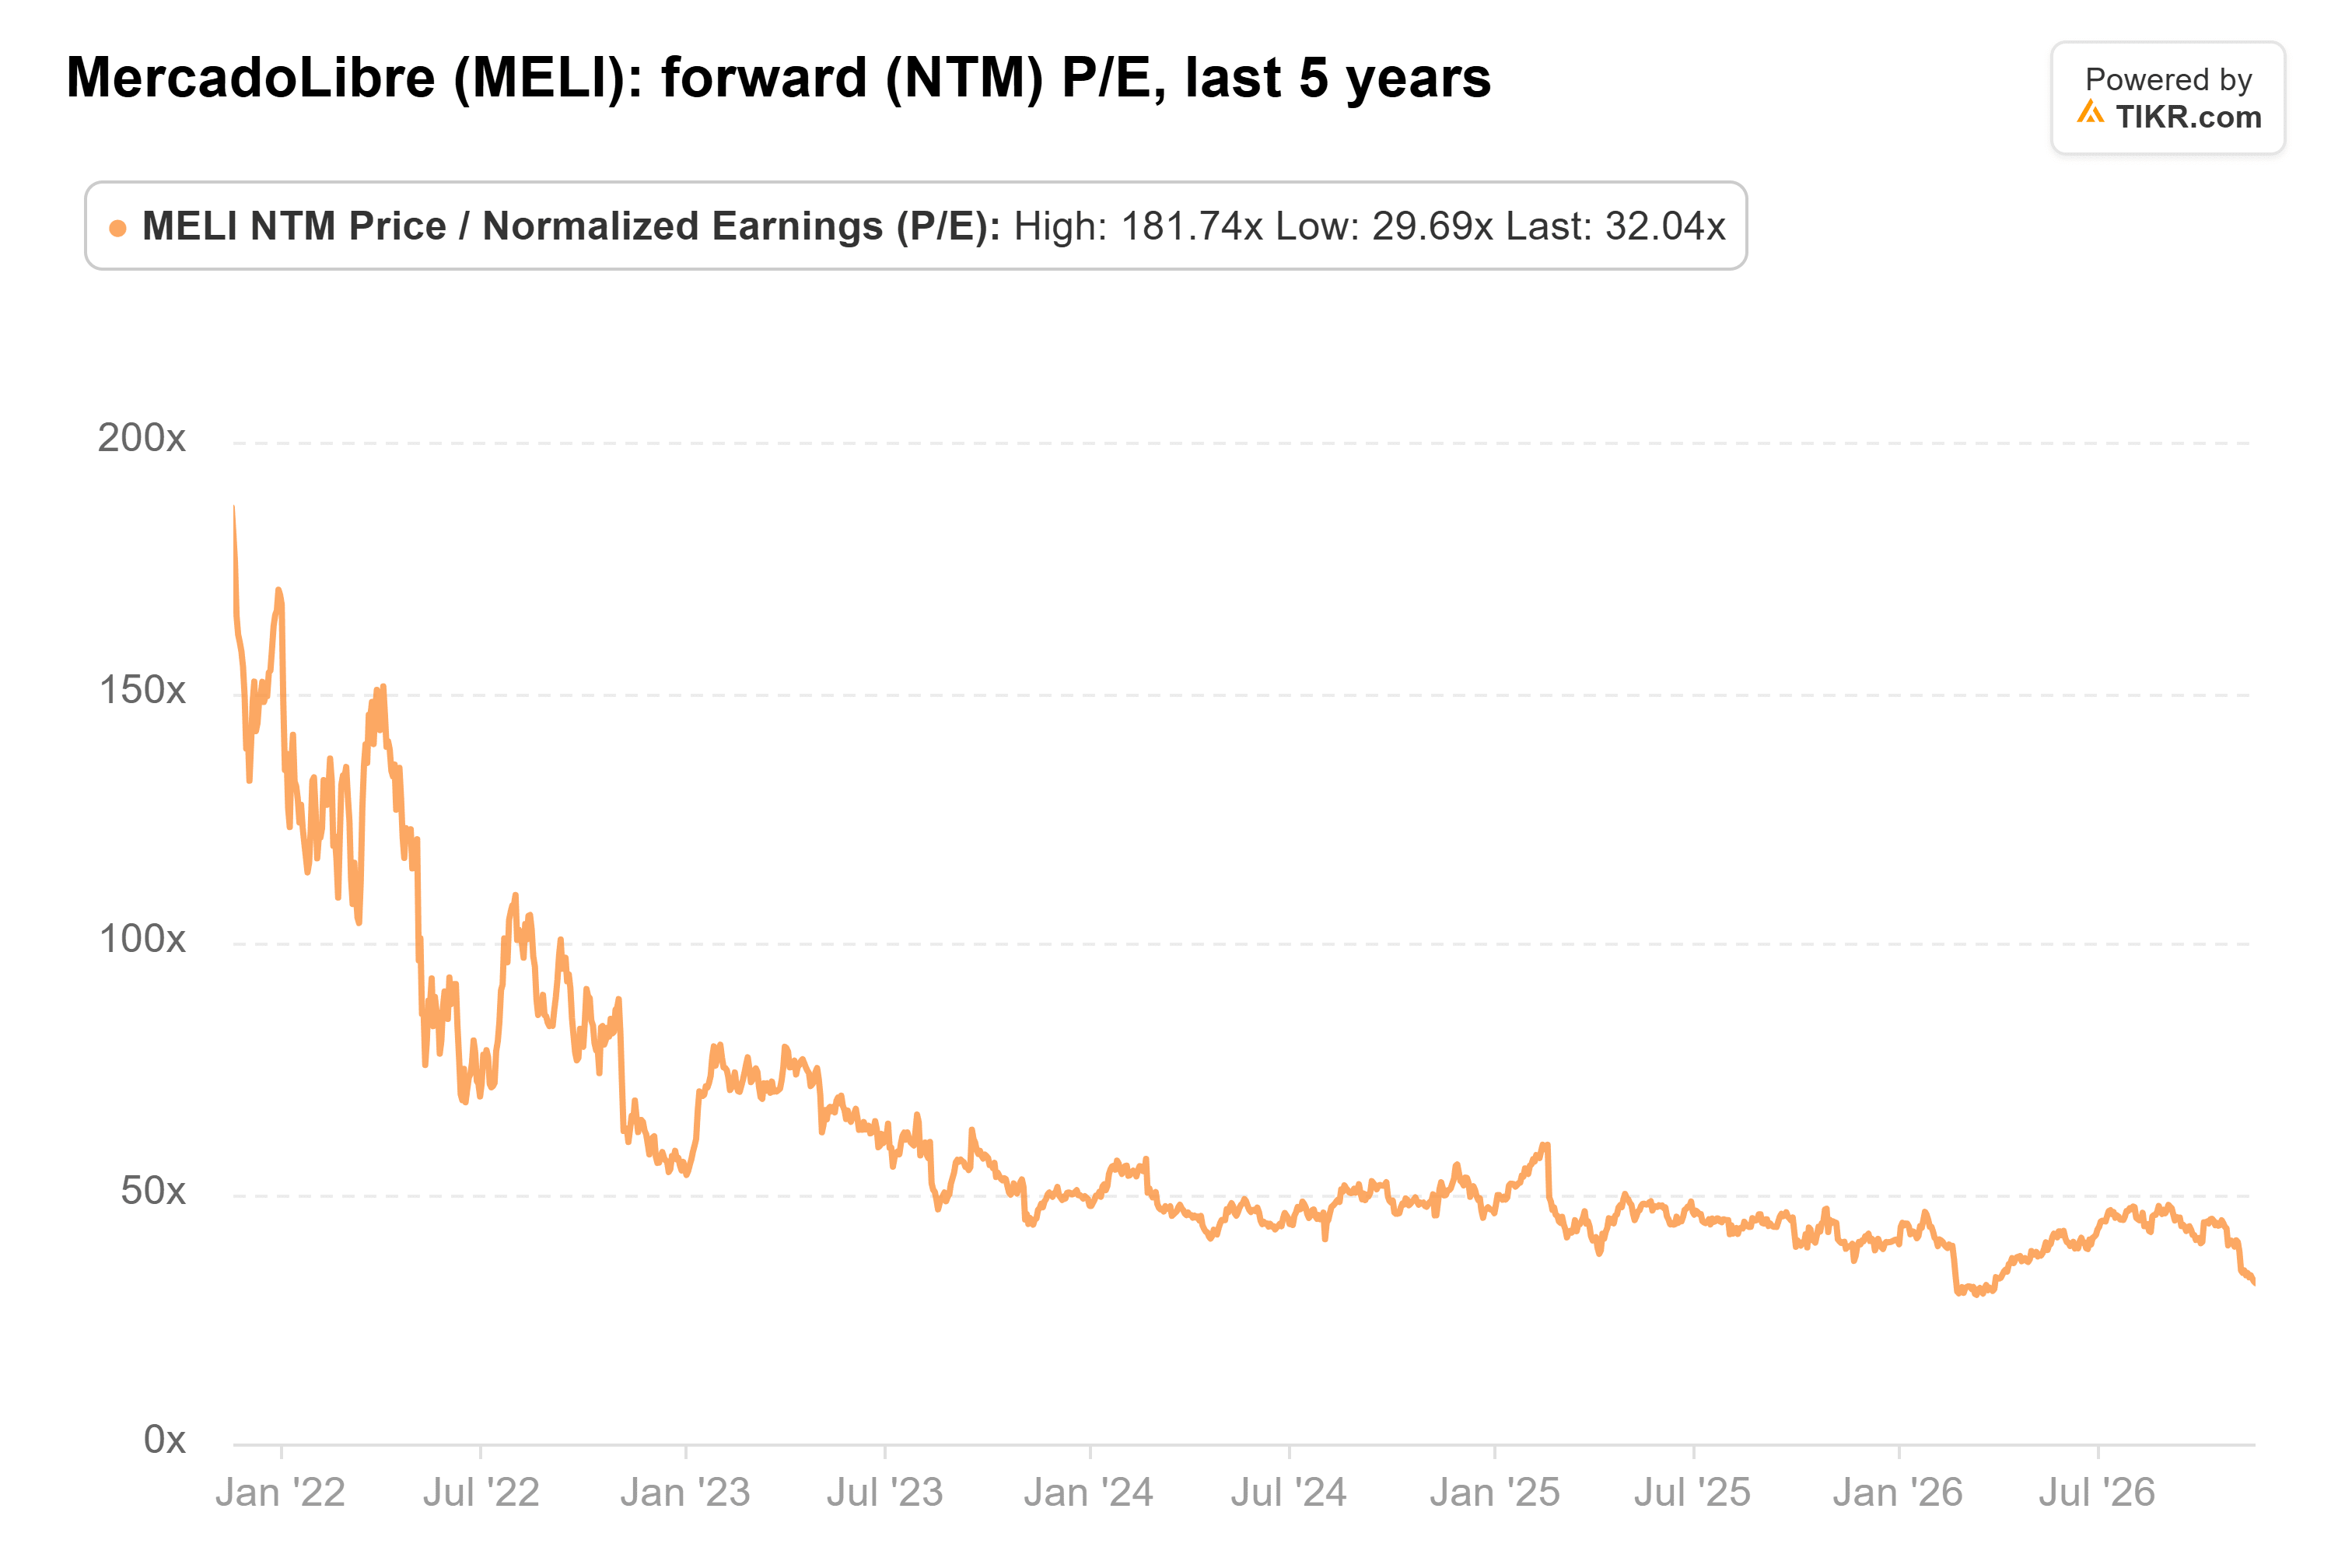
On 2028 estimates, $2,000 works out to 27x, below any forward multiple the stock has traded at in five years. Earnings growth of 66% from the next 12 months’ estimate would more than make up for an 11% lower multiple.
The earnings have to show up
CFO Martin de los Santos framed the margin drop as a choice on the Nov. 4 call: “These are deliberate investments.”
Bank of America looks right on valuation but early on timing. Investors have to trust a 2028 estimate that keeps shrinking, so $2,000 will likely take more than 12 months.
In the fourth-quarter report early next year, an operating margin back above 6.3%, with no big new spending planned for 2027, would give analysts a reason to stop cutting.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!