Key Takeaways
- Oklo fell 10% on Thursday morning to another 52-week low, a day after a 6% drop when Democrats were projected to win Congress. That’s about 15% in two sessions.
- At about $20 a share, Oklo’s market value is at least $3.8 billion, not far above the $3.0 billion of cash and securities it held at June 30.
- Oklo sold about $320 million of stock in the third quarter through Sept. 10, at around $44 a share, more than twice today’s price. That makes Friday’s share count the number to watch.
- NuScale Power reports after Thursday’s close, and GE Vernova’s quarter shows what Oklo still lacks: buyers with signed orders.
Oklo (OKLO) shares are down 10% this morning, trading at about $20 on Thursday, Nov. 5, the day before the company reports its third quarter. That’s another 52-week low. It follows a 6% drop on Nov. 4, when Democrats were projected to take the House and the Senate and investors sold AI power stocks. Over the two sessions, the stock has lost about 15%, and Oklo hasn’t put out any news to explain it.
Oklo reports before the open on Friday, Nov. 6, and revenue won’t say much: analysts expect $3.04 million for all of 2026. Cash is the number to watch. NuScale Power (SMR), which ended June with $1.9 billion of cash and investments, reports after today’s close. And GE Vernova (GEV) showed on Oct. 28 what Oklo still lacks: buyers with signed orders.
Oklo Is Trading Close to Its Cash
At about $20 a share, Oklo’s market value is at least $3.8 billion, counting the stock it sold through Sept. 10. At June 30, it held $3.0 billion of cash and marketable securities, nearly all of it raised by selling stock. The market is putting little value on the business beyond that cash, and the cash is shrinking.
Wall Street expects Oklo to lose money every year through 2028, with a bigger loss per share each year:
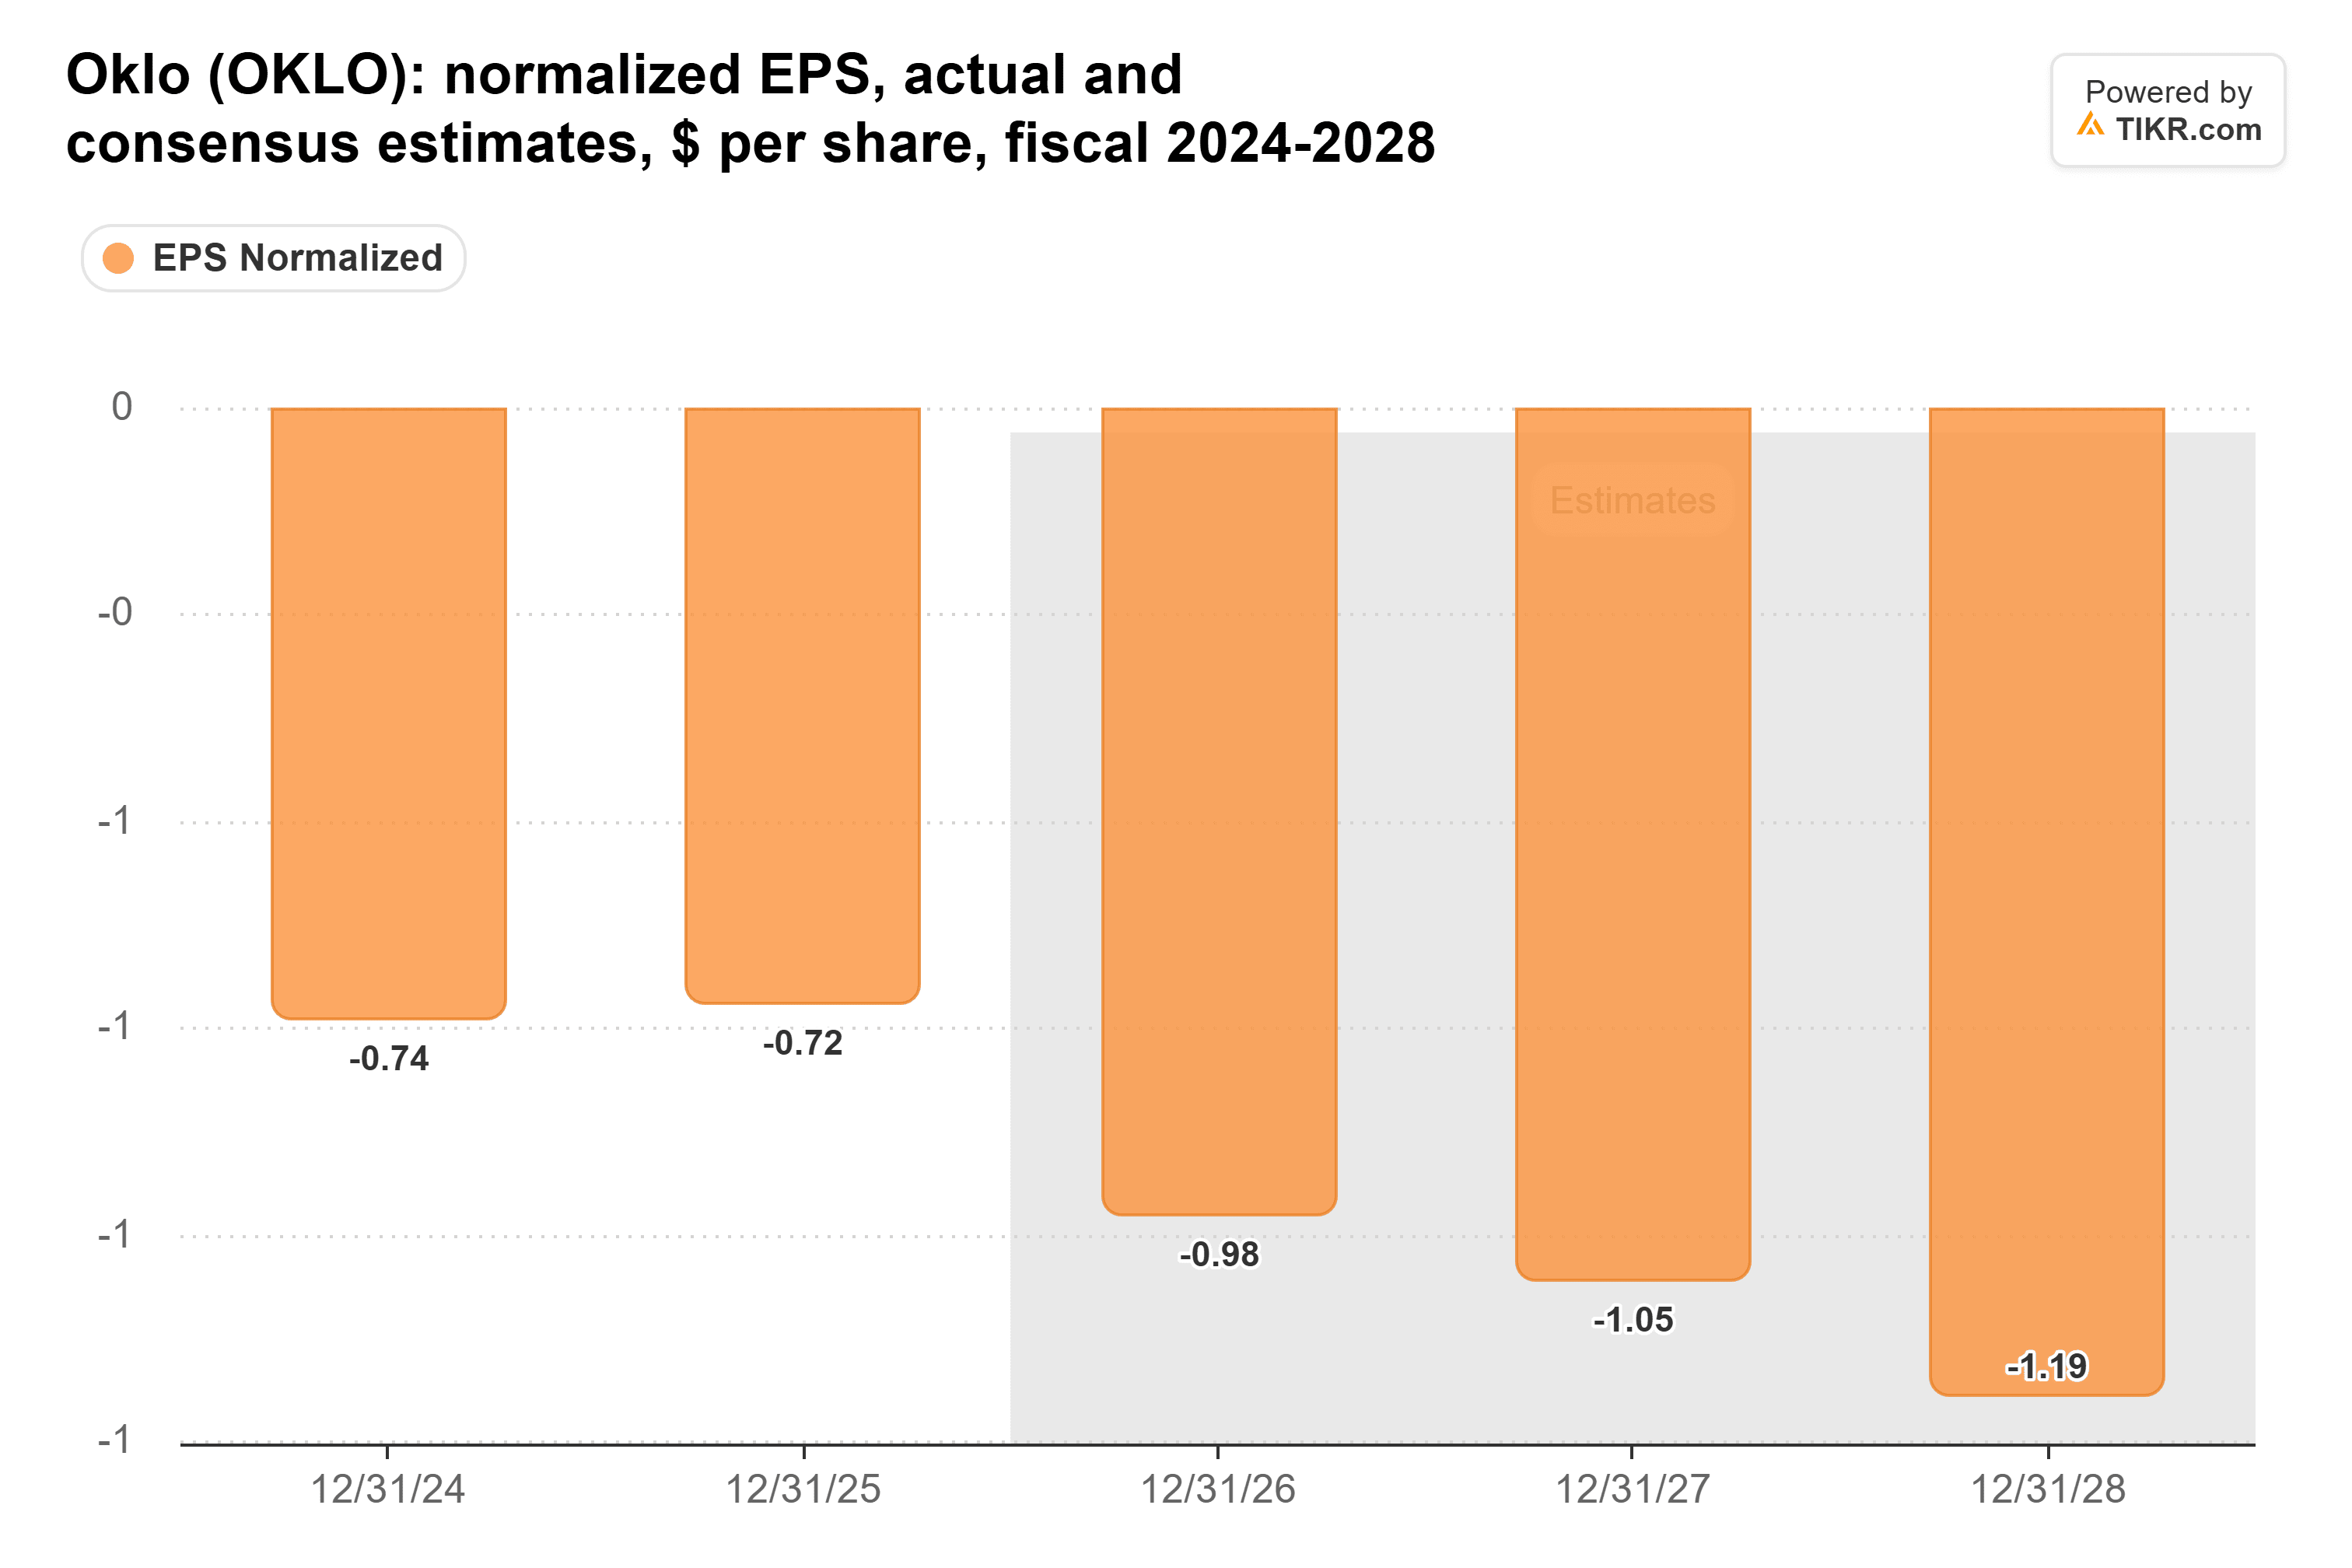
Analysts expect it to burn $6.3 billion of free cash flow from 2026 through 2030, 63% of it in 2029 and 2030. On their numbers, the June cash covers the burn through 2028 and runs short in 2029.
That should be enough to build Aurora-INL, its first power plant, in Idaho. The catch is that management still hasn’t said what Aurora-INL will cost. In October, Piper Sandler raised its estimate of what an Oklo plant costs to build to $7,000 per kilowatt from $4,000.
TIKR Tracks 25 Analysts on Oklo. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Oklo, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Oklo’s Analyst Ratings
Oklo’s Spending Has to Speed Up Again
Capital spending went from under $1 million a quarter in the first half of 2025 to $94.1 million in the second quarter of 2026. Cash used in operations rose to $47.6 million from $18.5 million a year earlier:
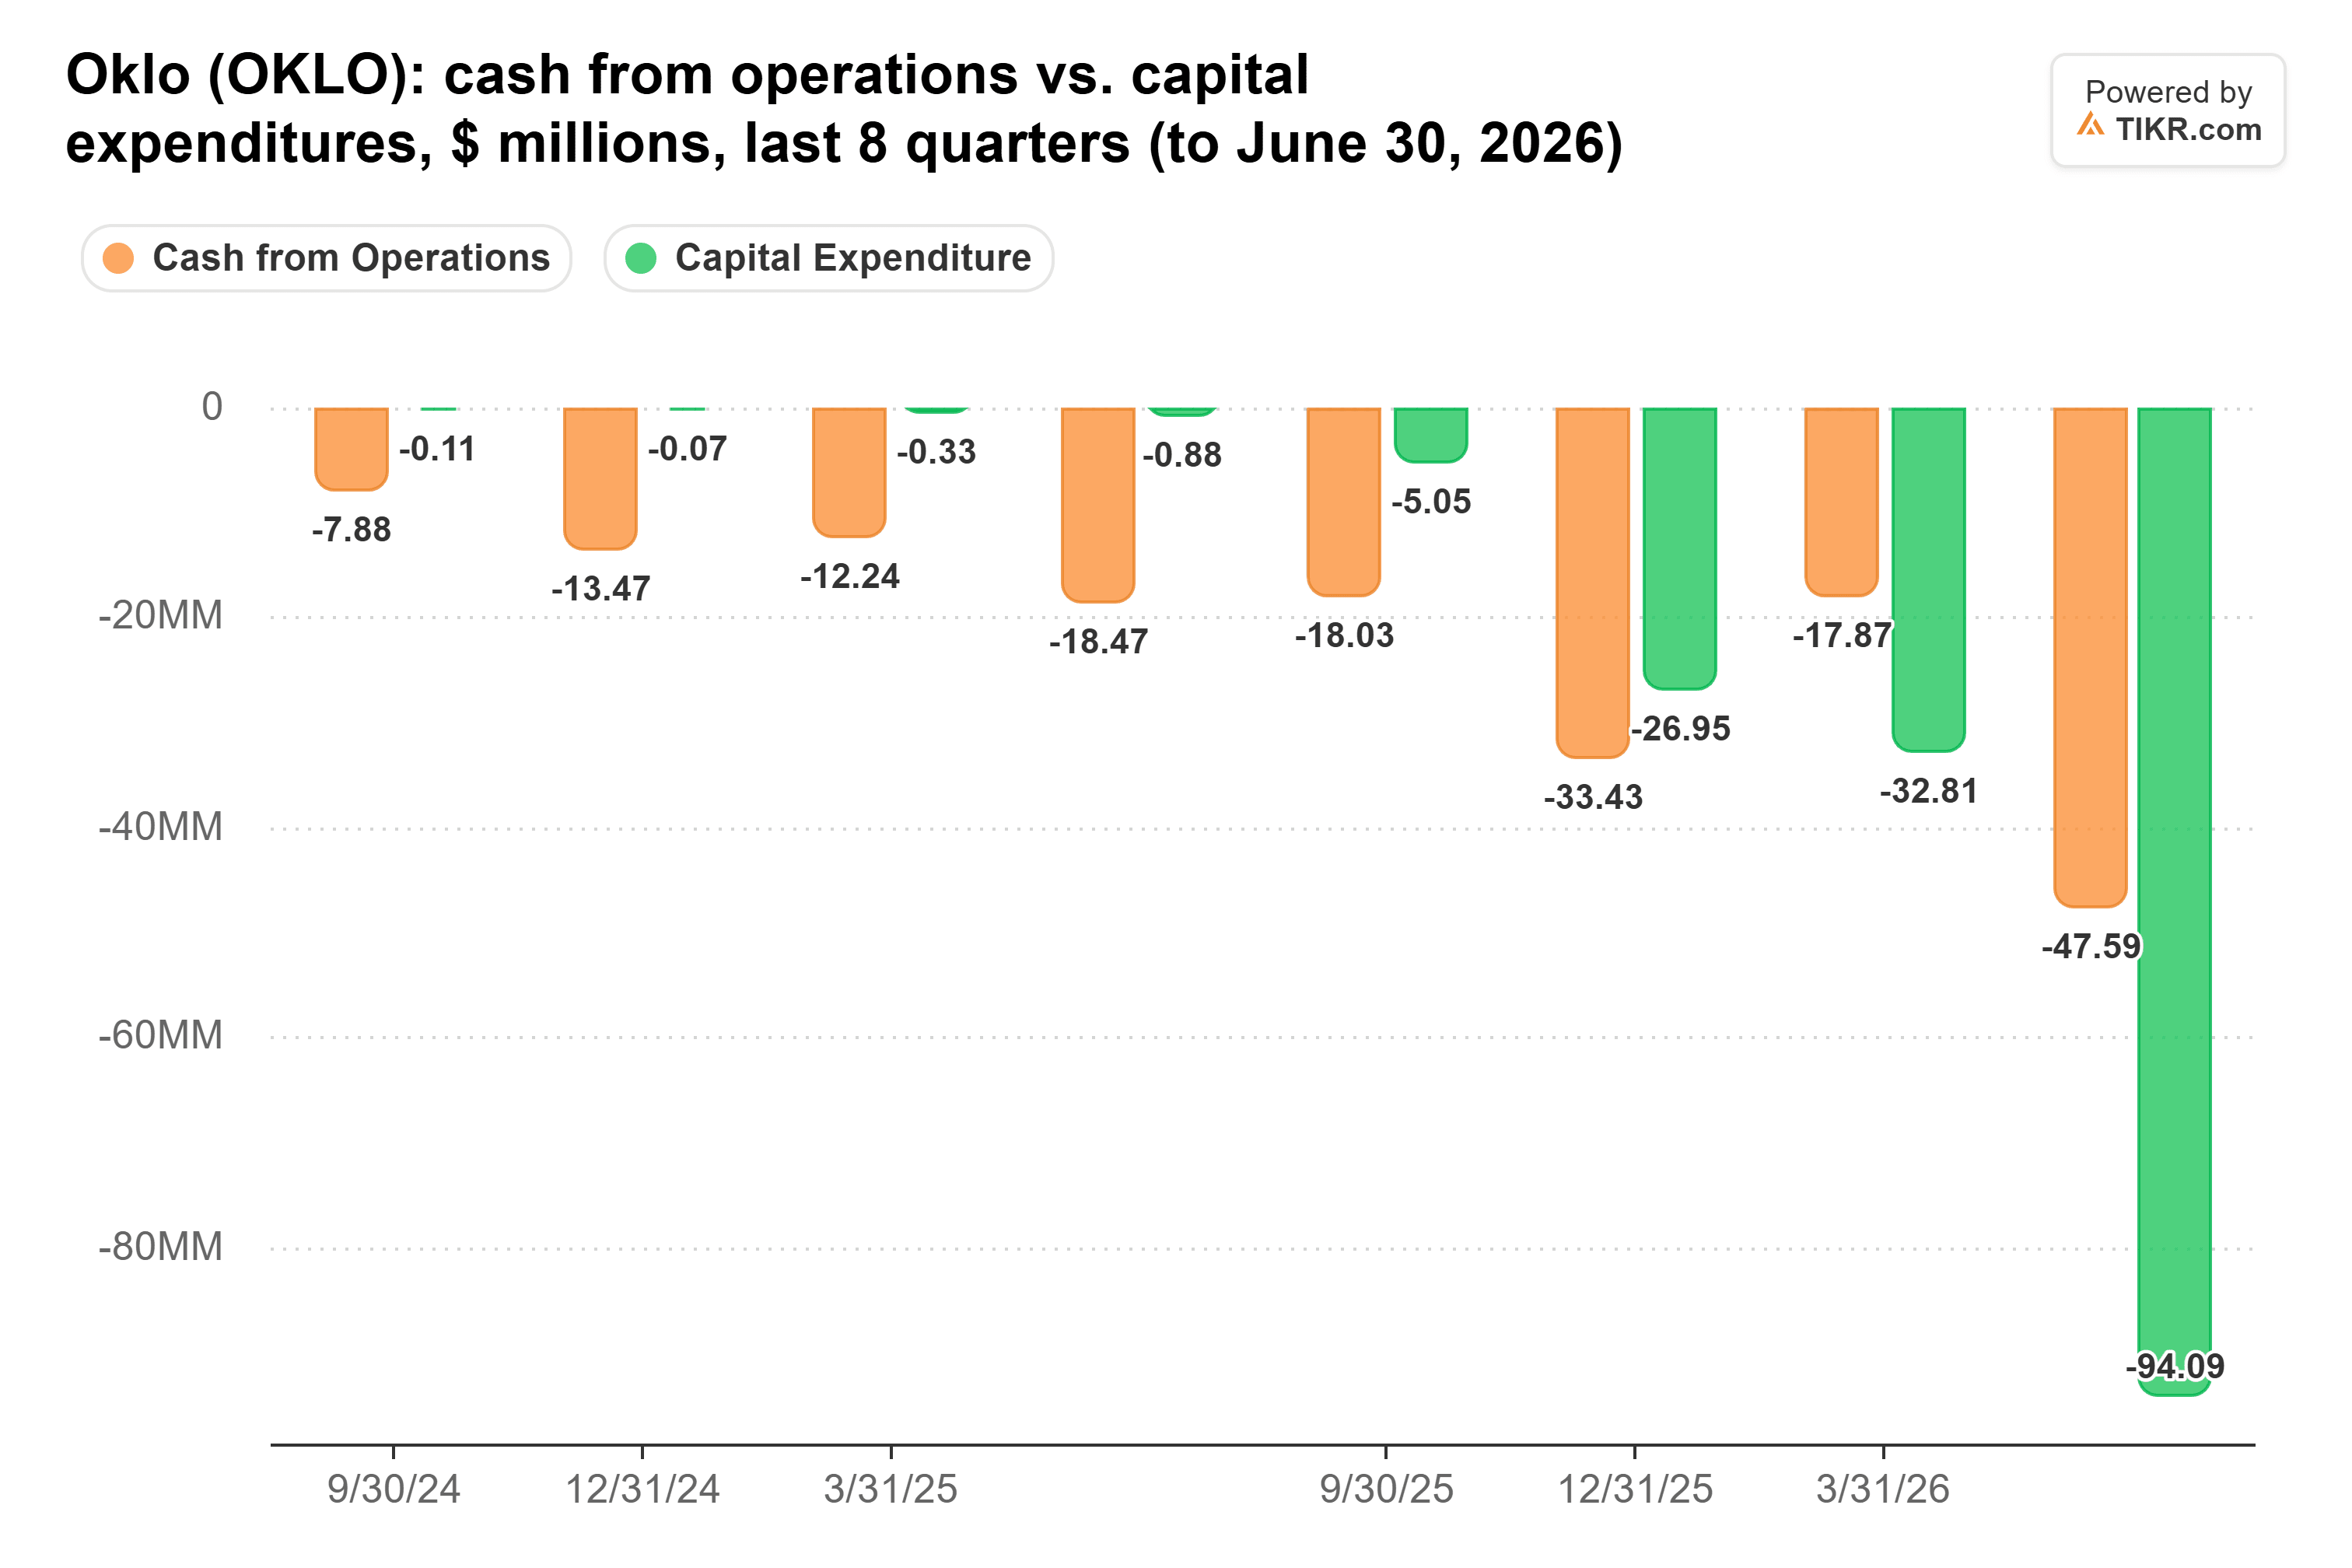
And it has to climb again. In August, management raised its 2026 guidance to $120 million to $150 million of cash used in operations and $400 million to $500 million of capital spending. With $126.9 million of capex in the first half, Oklo needs $273 million to $373 million in the second, or at least $137 million a quarter.
A third quarter near that pace says the build is on track. A big shortfall would point to delays, and another guidance raise would suggest the build is costing more than planned.
Watch the Share Count
Oklo’s share count rose 34% in 18 months, to 185.09 million at June 30, and the price it got kept falling: its stock sales averaged about $97 a share in the first quarter and about $64 in the second.
The third quarter was cheaper still. When Oklo ended its May program on Sept. 10, it had sold about 18.0 million shares under it for roughly $1.0 billion. About 10.7 million of those went in the second quarter. That leaves roughly 7.3 million sold in the third, for about $320 million, or around $44 a share, more than twice today’s price. A new $1.0 billion program started the next day.
The Street has followed the stock down. Wedbush assumed coverage on Nov. 2 with an Outperform rating and a $36 target, down from the firm’s earlier $110. That target now sits about 80% above the stock.
On consensus numbers, Oklo’s cash already pays for Aurora-INL. Heavy sales after Sept. 11 would mean Oklo is funding the plants after it at a fraction of what it got earlier in the year.
Oklo’s stock may not trade on its cash at all, though: it has dropped 15% in two days without any news. NuScale still has no binding reactor order, and its partner ENTRA1 is still working toward a definitive power deal with the Tennessee Valley Authority. If NuScale’s stock trades on that TVA update tonight and shrugs off its cash, I’d expect Oklo’s to do the same with any news on Meta.
Oklo’s Customers Are Only Starting to Pay
GE Vernova took $29.3 billion of orders in the third quarter, signed 11 gigawatts of new gas equipment contracts and brought in $5.4 billion of free cash flow. It also bought back $1.6 billion of its own stock, while Oklo sells its own to keep building.
Oklo’s closest equivalent is its January deal with Meta, which lets Meta prepay for power from a planned 1.2-gigawatt campus in Pike County, Ohio. Oklo hasn’t said how much Meta has paid, and the agreement directs that money to securing fuel for the first phase, not to the build. Any sign on Friday that customers will share the construction bill would take pressure off the share count.
Funded, for Now
On Wall Street’s own numbers, Oklo can pay for its first plant with the cash it already has. Friday has to show three things: capex on pace, guidance holding, and light stock sales after Sept. 11. If it gets all three, I think a stock trading this close to its cash has run ahead of the risk. Heavy sales at today’s prices would say the dilution has further to go.
Piper Sandler expects fuller cost guidance at Oklo’s capital markets day in spring 2027. Until Oklo puts a price on Aurora-INL, every share it sells pays toward a cost it hasn’t disclosed.
So what is Oklo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Oklo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!