

Key Takeaways
- SpaceX stock is down 43% from its June peak. China Renaissance initiated coverage with a Buy rating and a $194.20 target, 52% above today’s price.
- China Renaissance’s target is about 25% below the Street’s $257 average target, which has more than doubled since June as analysts raised their estimates.
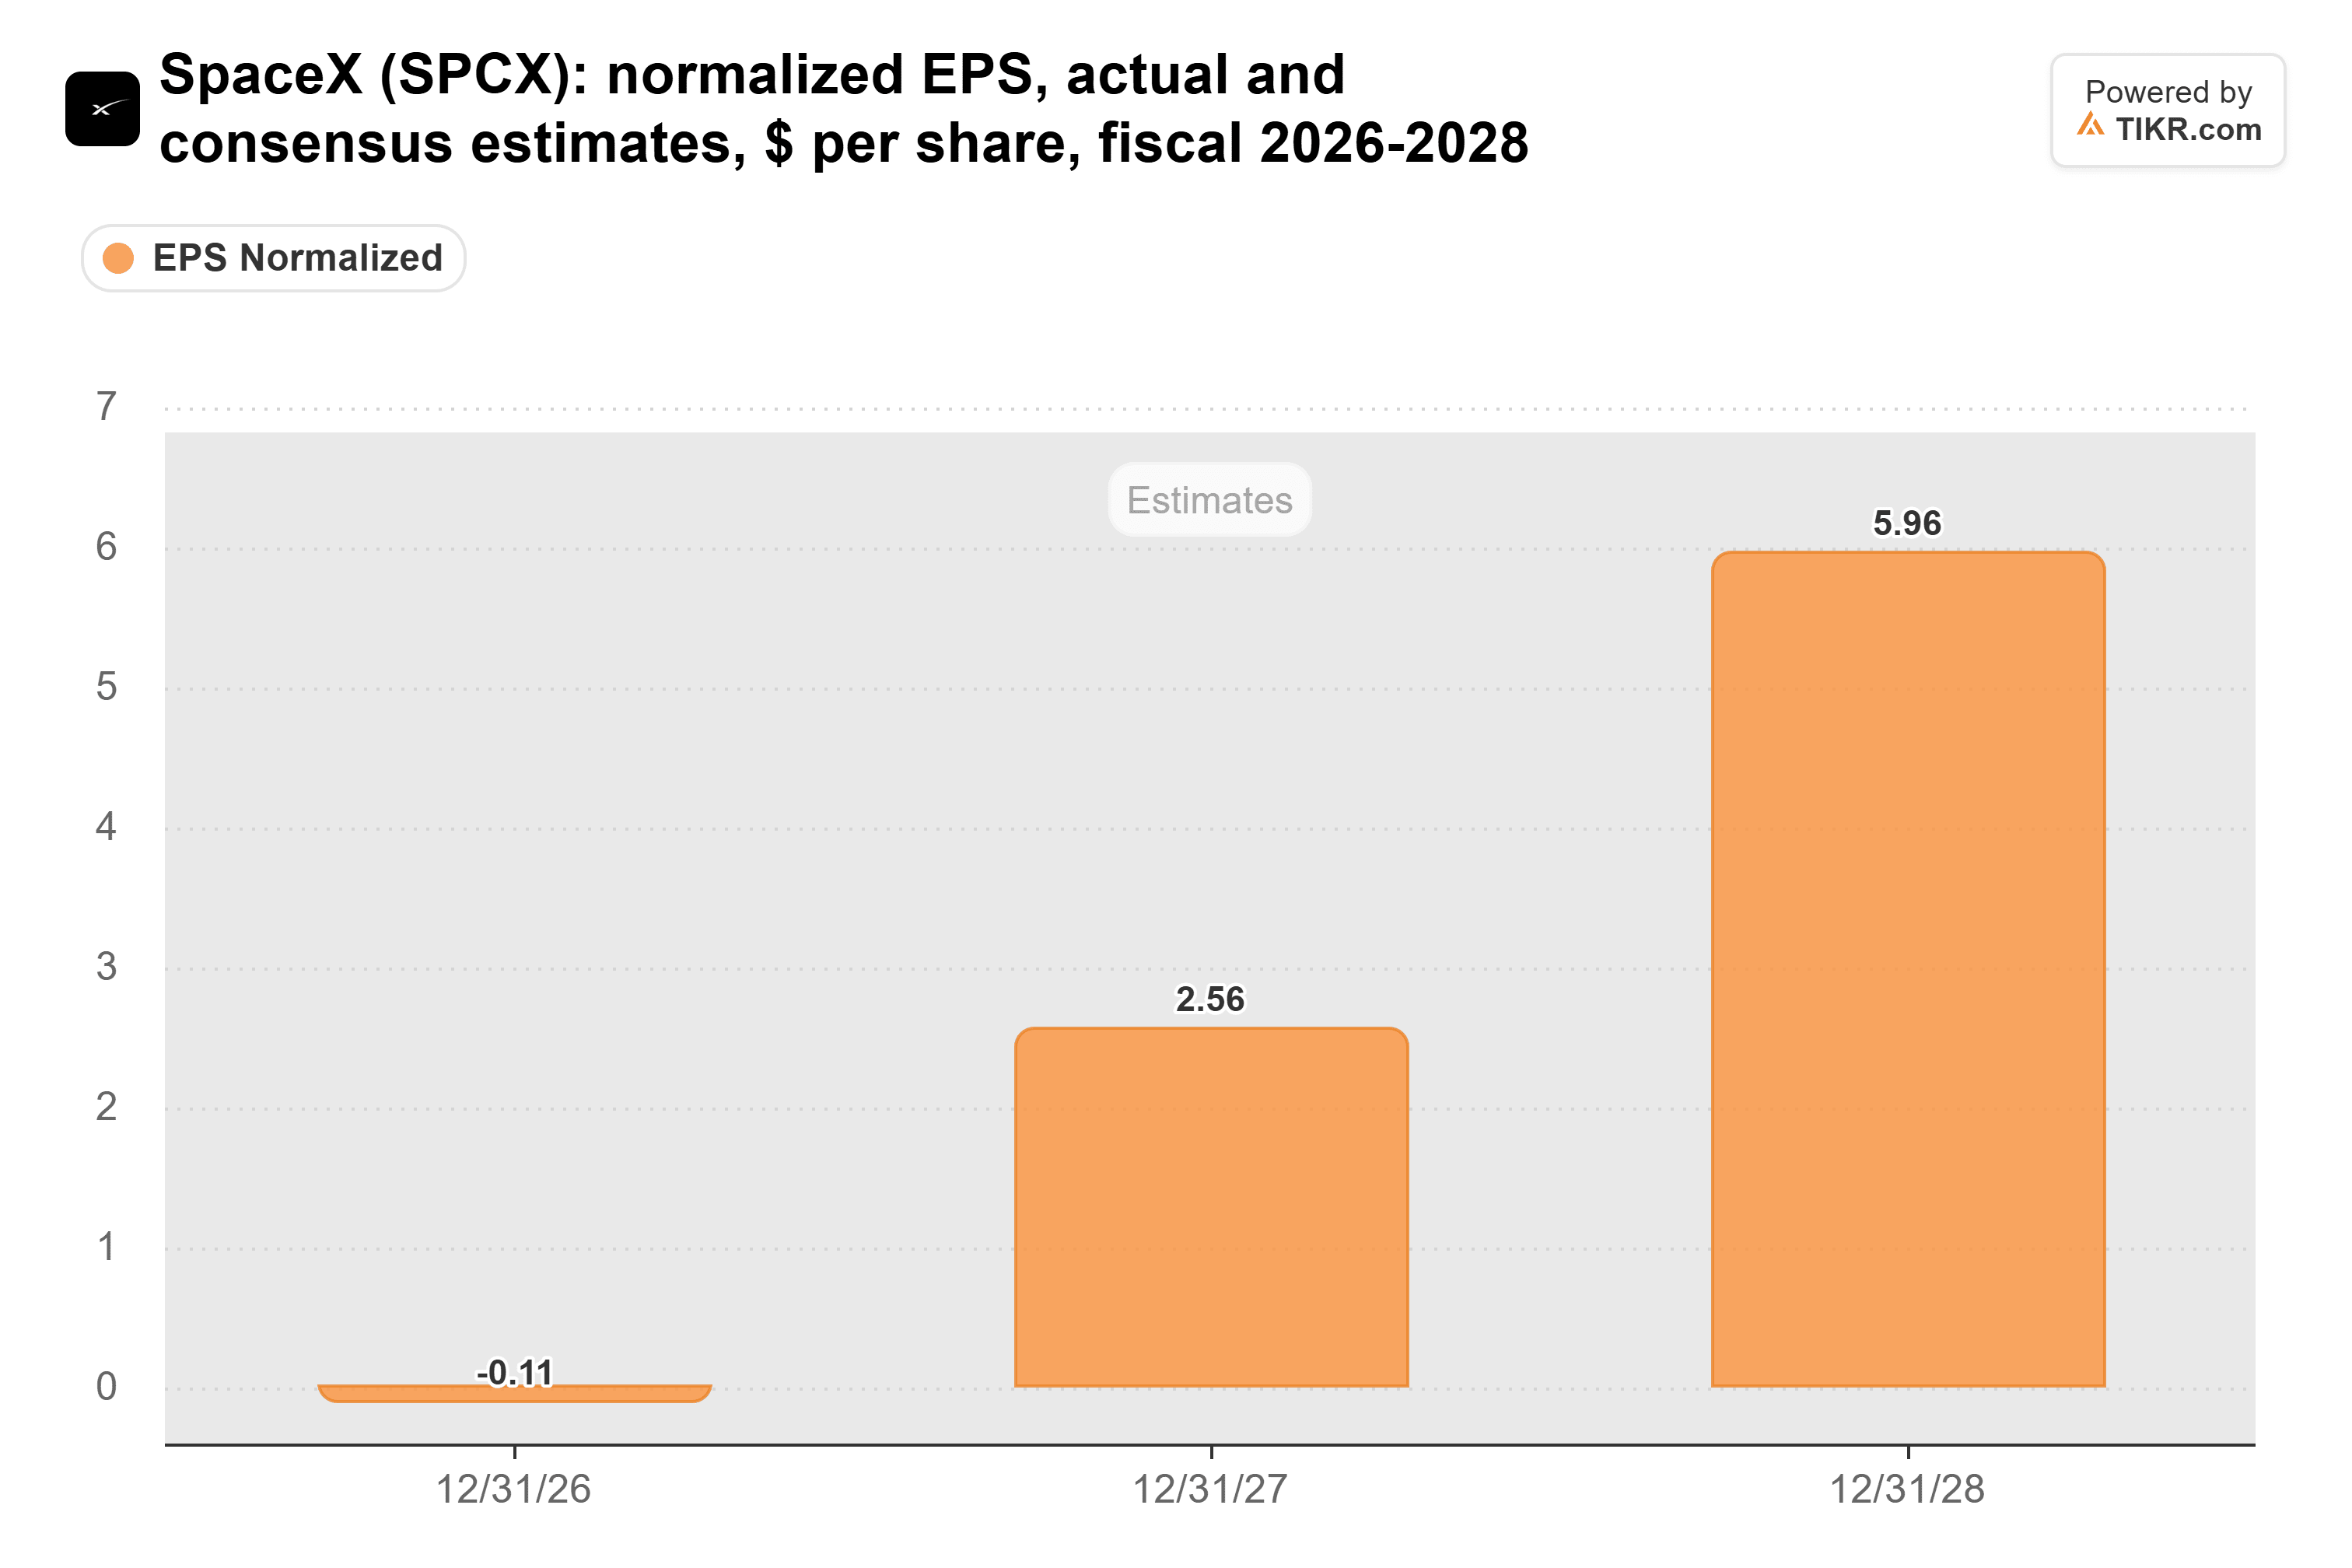
- Analysts expect normalized earnings of $5.96 a share in 2028. $194 is a lower multiple of that figure than SpaceX trades at today on the next 12 months’ earnings.
- China Renaissance has the earnings about right. But analysts expect $140.7 billion of negative free cash flow in 2027, so the stock isn’t a buy until SpaceX shows how it will pay for its build.
SpaceX (SPCX) is down 43% from its June 16 peak, and at $127.72, it’s back below its $135 IPO price. This week, China Renaissance initiated coverage with a Buy rating and a $194.20 price target, 52% above today’s price.
Supply, spending and a blue wave
Part of the slide came from supply: SpaceX’s staggered IPO lockup has freed waves of insiders’ and early investors’ shares to sell since August.
Then the spending grew. On the Oct. 20 third-quarter call, management guided fourth-quarter capex to $35 billion to $40 billion, up from $19.6 billion in the third quarter. This week, Bloomberg reported that SpaceX’s banks are shopping pieces of a roughly $40 billion chip financing deal.
On Wednesday, Democrats won both the House and the Senate, and Texas’s governor-elect, Gina Hinojosa, campaigned on an immediate moratorium on data centers. Elon Musk’s reply on X: “Data centers in space looking pretty appealing right now.”
A Buy at the low end
China Renaissance’s $194.20 is about 25% below the $257 consensus target. It’s also below the Buy targets that Goldman Sachs ($245), Needham ($250), Deutsche Bank ($250), Bernstein ($268) and Morgan Stanley ($300) put out after the third-quarter report.
TIKR tracks 39 analysts on SpaceX. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SpaceX, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SpaceX’s Analyst Ratings
Does $194 add up?
The Street’s average target has more than doubled since June, to $257 from $114:
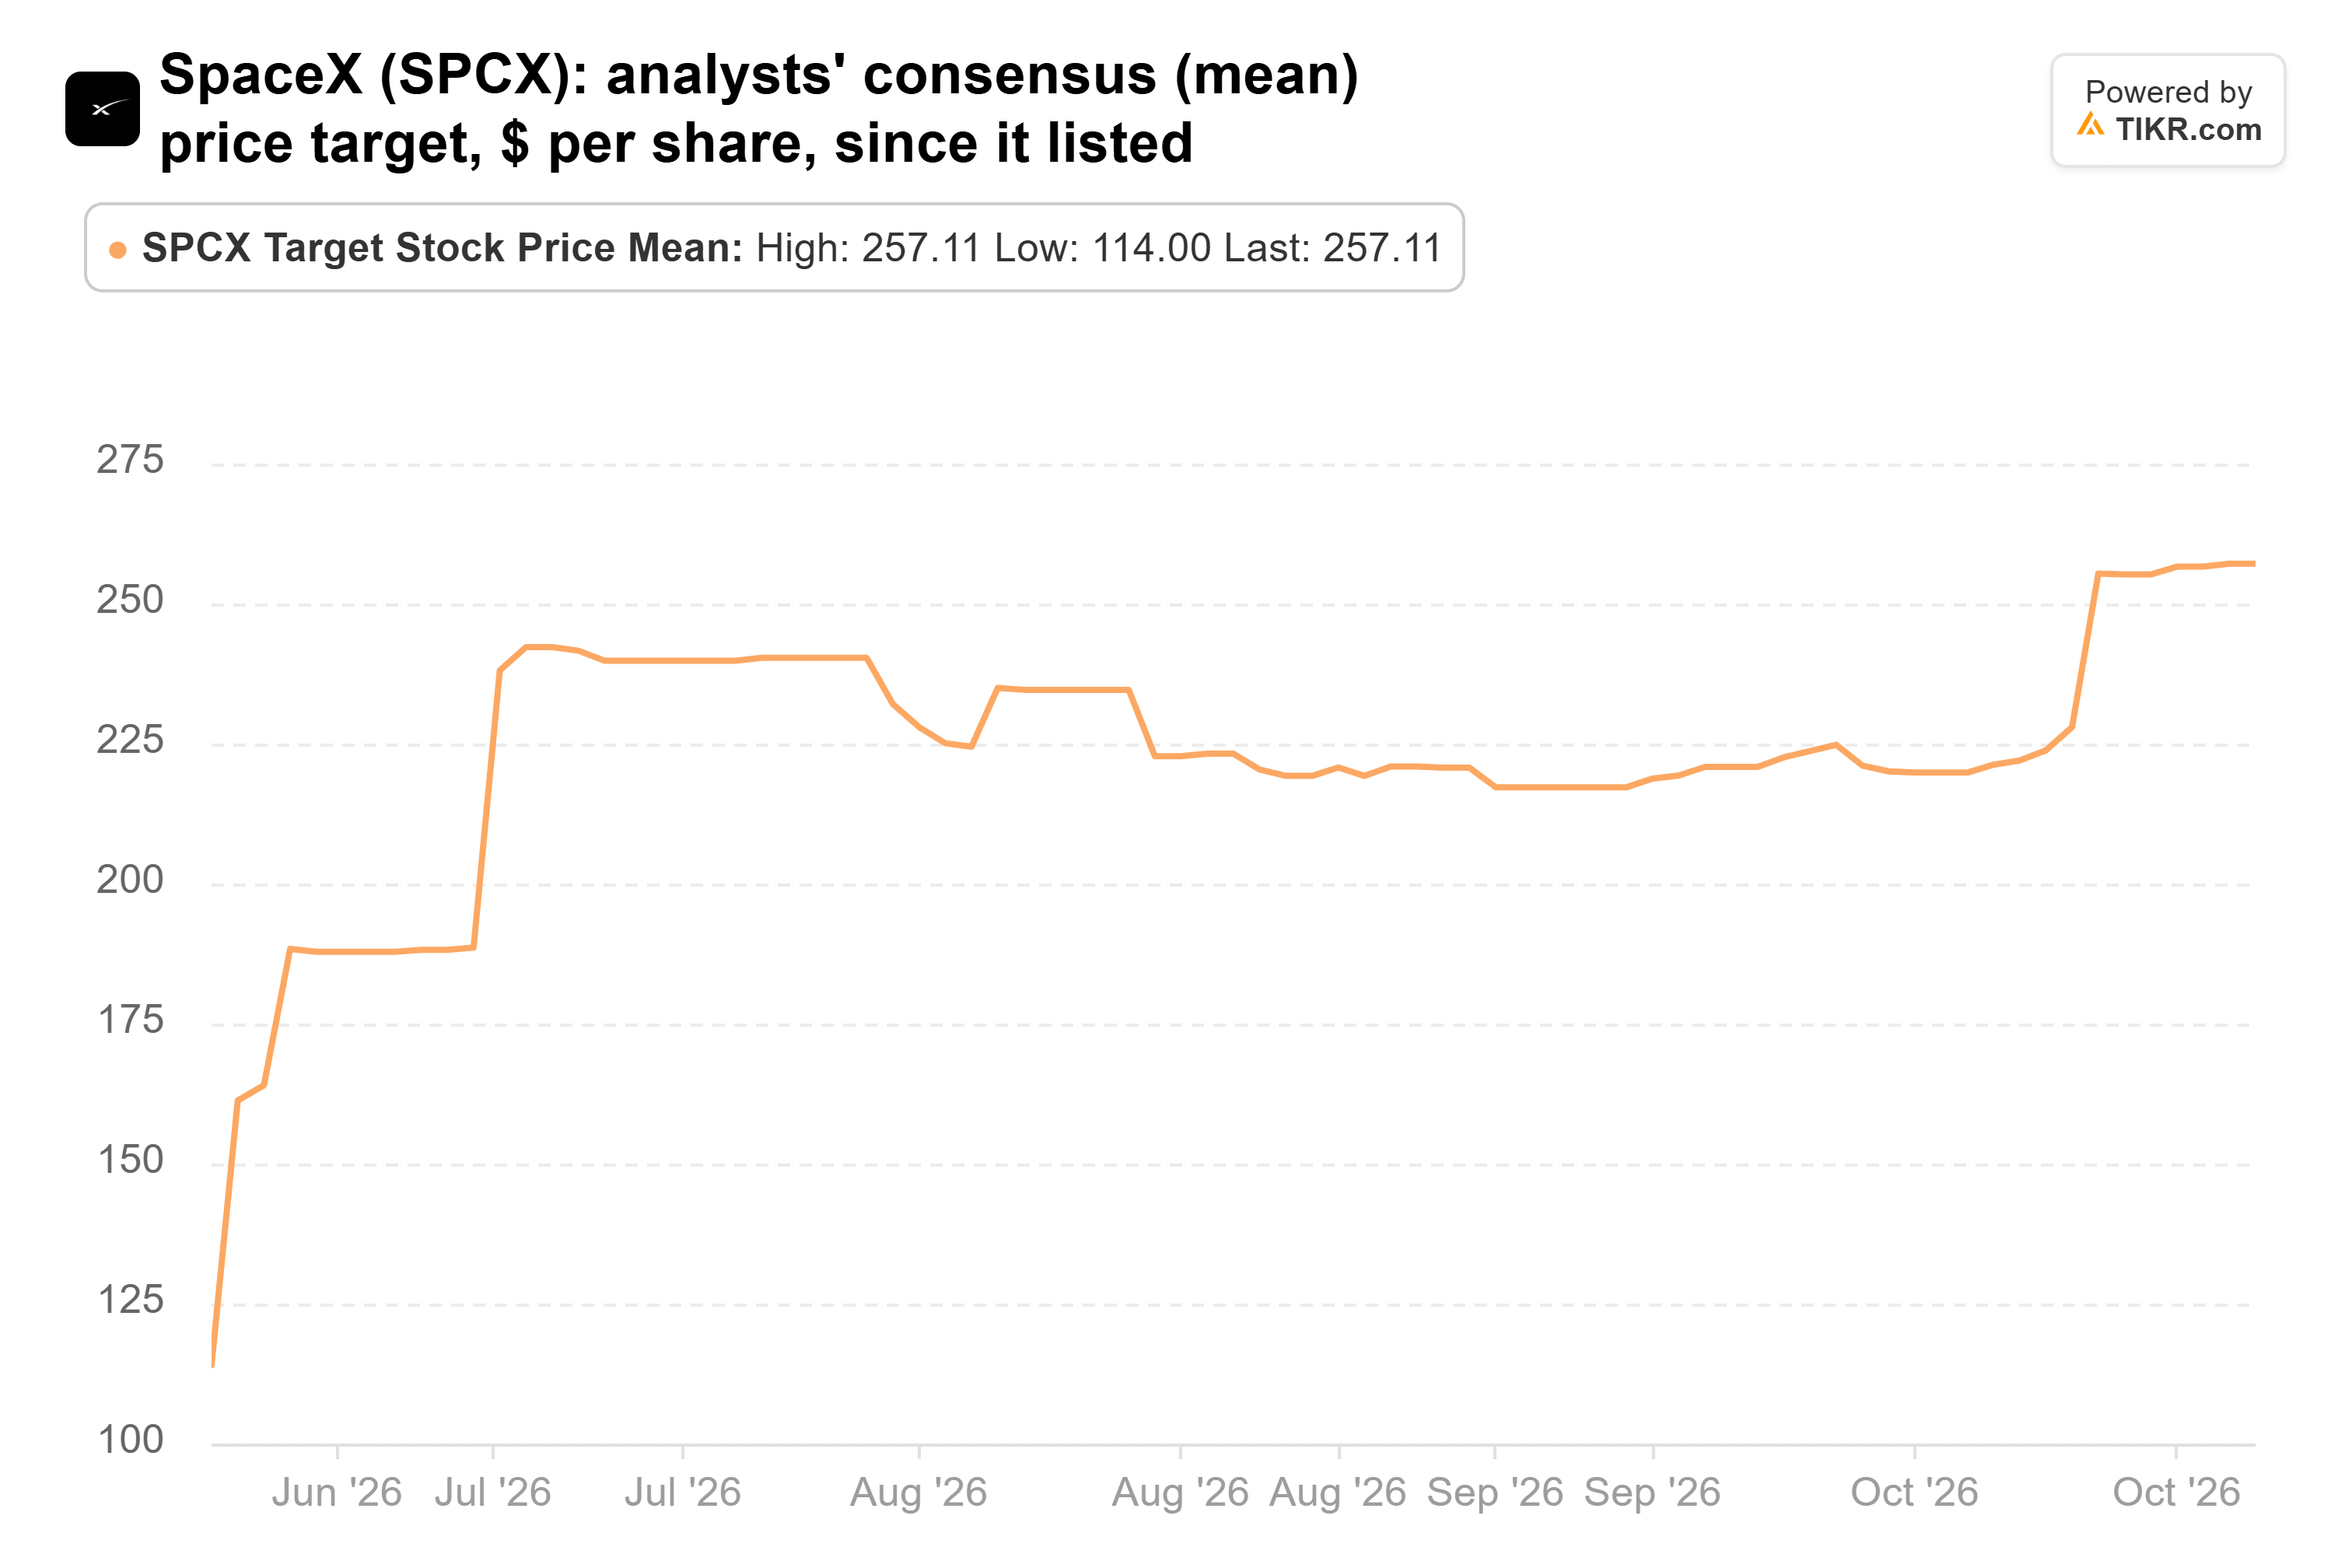
The 39 analysts covering it have targets from $70 to $800.
The estimates rose with it. Third-quarter revenue jumped 161% to $14.6 billion, led by the Super Intelligence segment’s cloud contracts, and analysts have raised their 2027 revenue estimate 146% since the end of June. On a normalized basis, they expect SpaceX to go from a small loss this year to $2.56 a share in 2027 and $5.96 in 2028:
That ramp depends on what compute rents for. “At current pricing, new compute deployments are generating a payback of less than a year,” CFO Bret Johnsen said on the call.
At Monday’s close, SpaceX traded at 45x the next 12 months’ expected earnings, and China Renaissance’s target works out to about 64x. A year from now, though, the next 12 months will be mostly 2028. $194 is a lower multiple of 2028’s expected $5.96 than SpaceX trades at today. If those estimates hold, investors wouldn’t have to pay up to get there.
The bill is the problem
Those estimates assume the build keeps going, and analysts expect it to burn cash. They see negative free cash flow of $57.7 billion this year and $140.7 billion in 2027, against $89.9 billion of cash and marketable securities at Sept. 30. Debt or new stock has to fill that gap, and new shares would dilute those earnings.
The way I see it, China Renaissance has the earnings about right, and $194 asks less of SpaceX than most of Wall Street does. But I’d wait to buy until SpaceX shows how it’ll pay for 2027’s build.
Fourth-quarter results early next year will show how much cash that record capex quarter burned, and the chip financing’s terms could come sooner.
So what is SpaceX stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SpaceX could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


