


Key Takeaways
- Mastercard (MA) stock is up 19% in the past month and is at a 52-week high after a Q3 report that beat on revenue.
- Most of the gain came from a higher multiple, because Wall Street’s earnings estimates barely moved after the report.
- Even after the run, Mastercard’s forward P/E is below its 10-year average, so buyers are paying for analysts’ forecast of about 16% yearly EPS growth and not much more.
- Free cash flow growth is expected to slow in 2026, and Q4 results in late January are next.
Mastercard stock is up 19% in the past month, including 8% in the past week, and is at a 52-week high. It’s up 17% in 2026, so it was still down for the year when the run began.
So how much of that move did the business earn?
A beat, with a catch
On Oct. 29, Mastercard reported Q3 net revenue of $9.81 billion, up 14% and ahead of the $9.66 billion analysts expected. Services grew 19% on a currency-neutral basis, and the payment network grew 11%.
But new CFO Ling Hai said part of that beat came from services projects and network deals pulled forward from Q4, adding: “You will see a similar offset in Q4.”
Wall Street’s normalized EPS estimates barely moved after the report. The 2026 estimate went from $19.95 the week before to $20.04, and 2027’s went from $23.07 to $23.13.
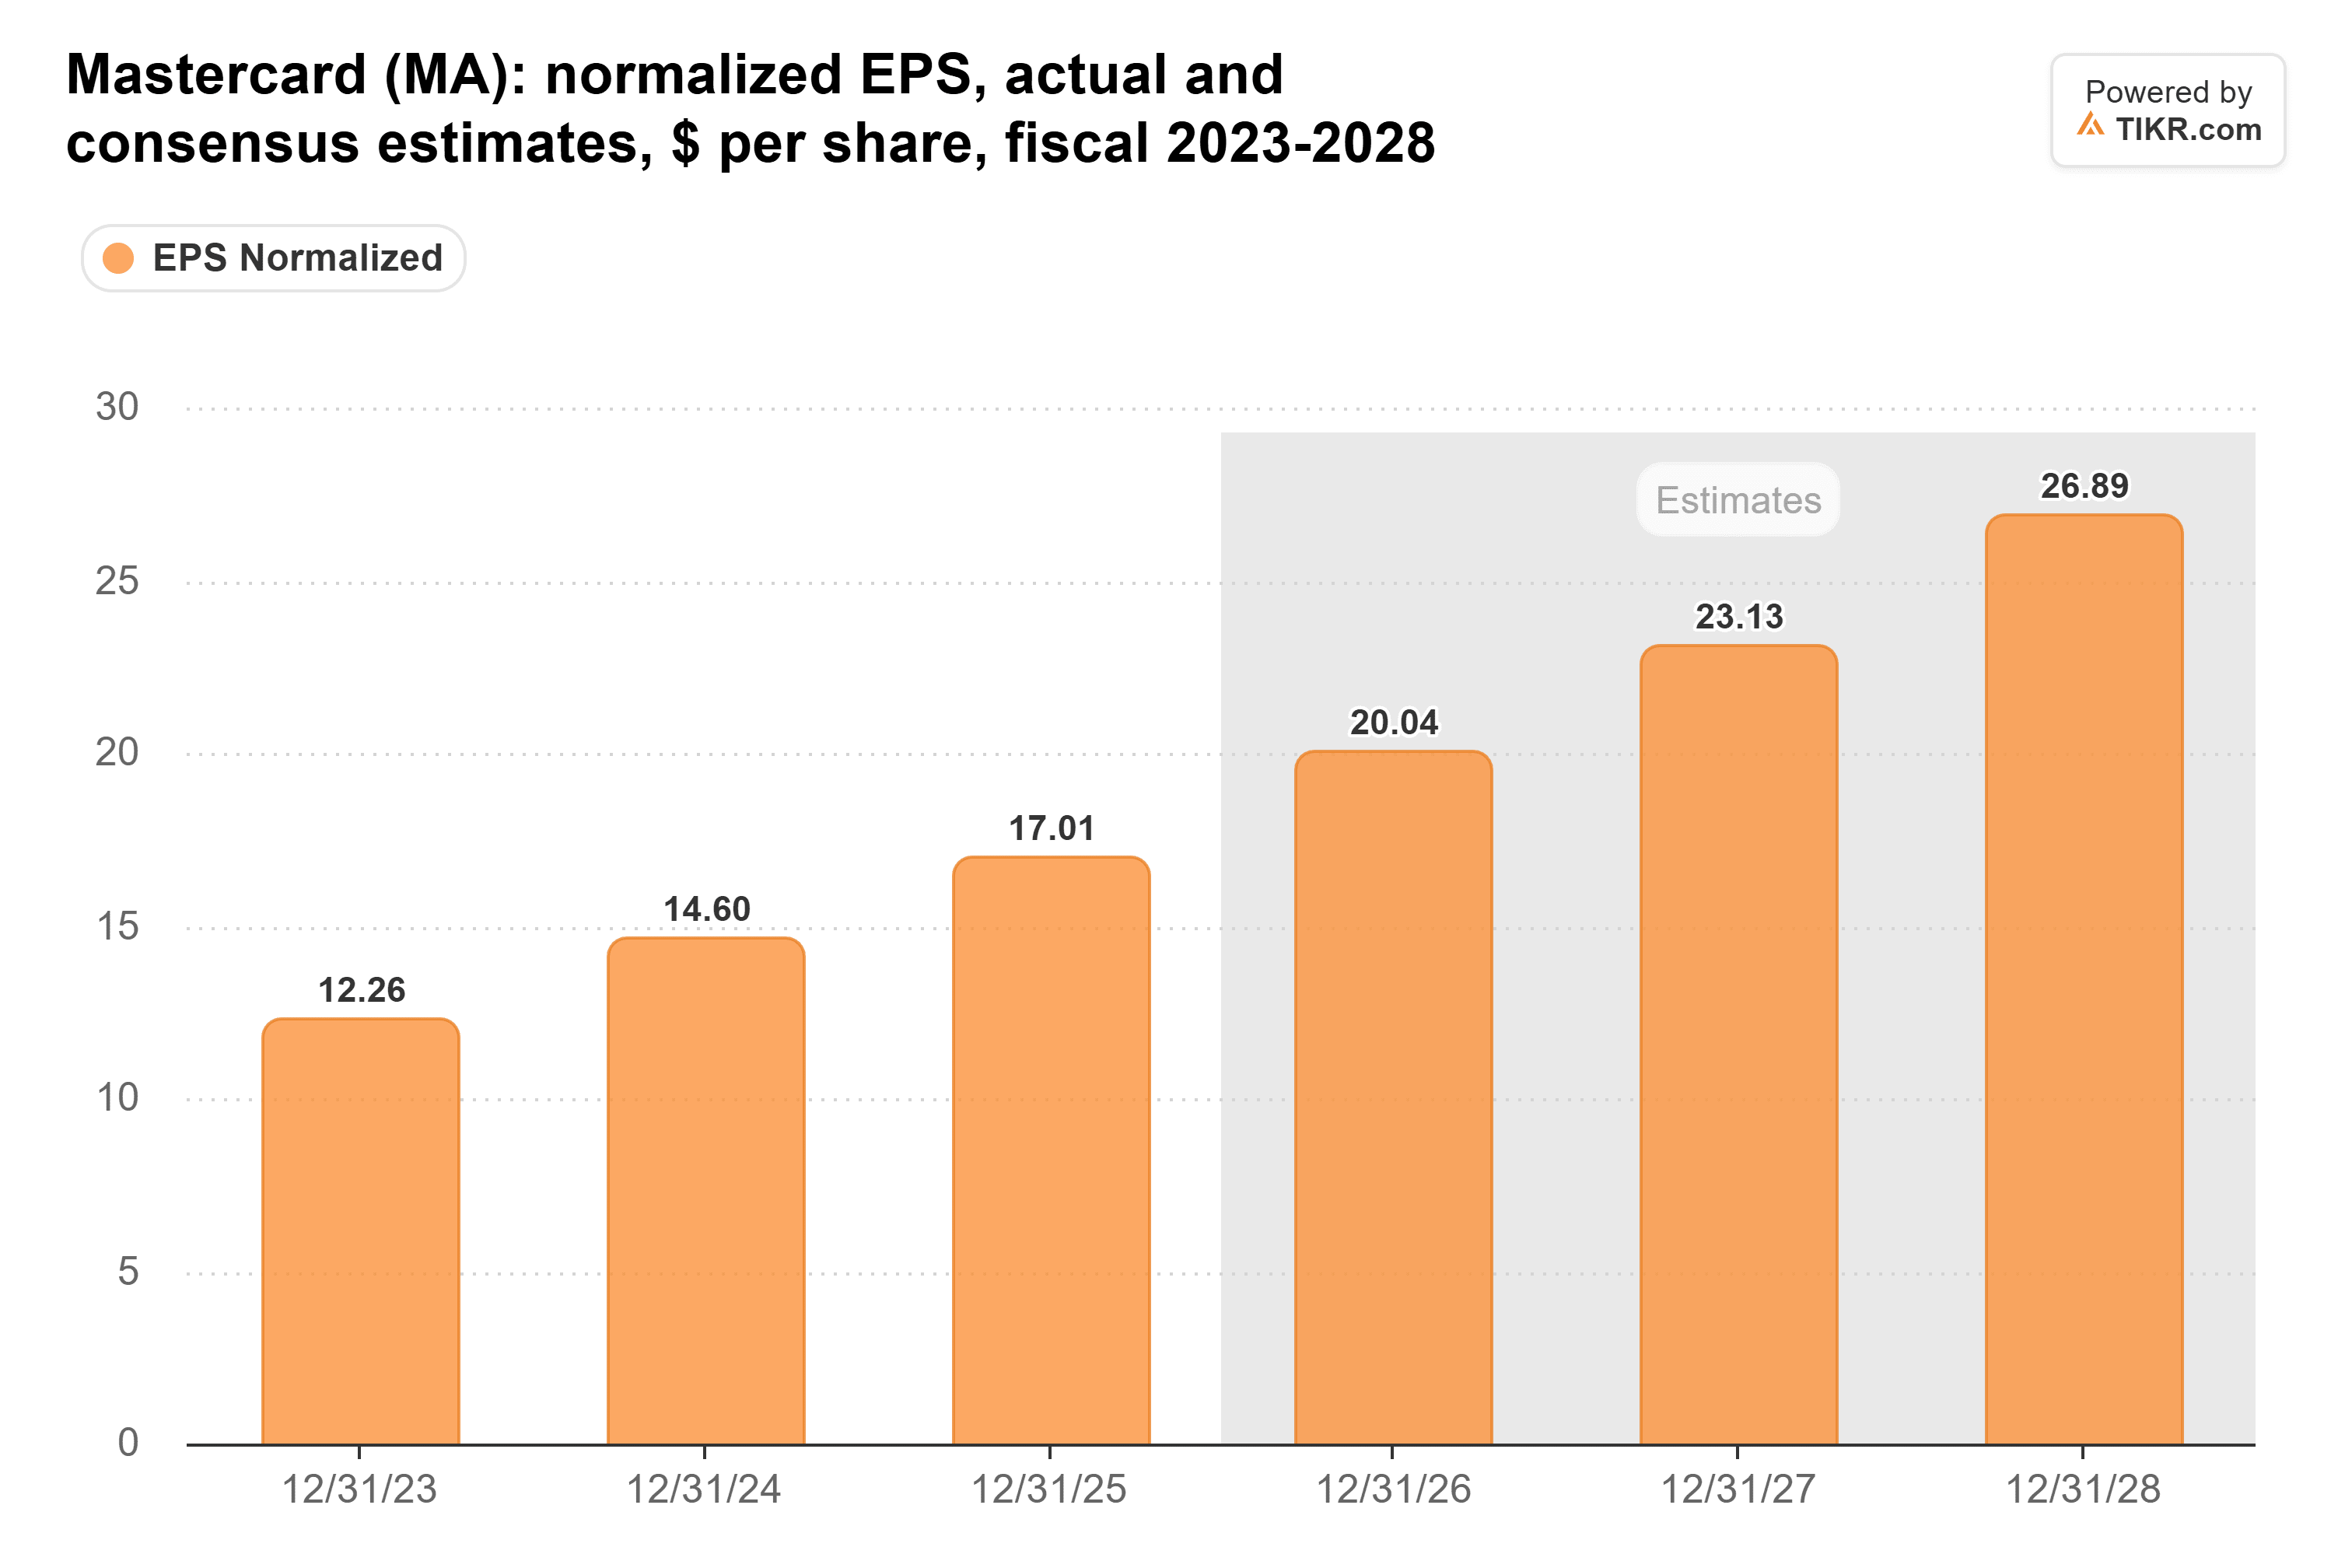
That works out to 18% growth this year and 15% in 2027. With part of the Q3 borrowed from Q4, I don’t see much reason for those estimates to jump.
Most of the gain is a higher multiple
Mastercard’s forward P/E rose from 25.9x at the end of September to 29.6x as of Nov. 2. That’s still below its 10-year average of 32.5x, a stretch that ran from a low of 23.2x in March 2020 to a high of 49.2x in April 2021.

So the run took Mastercard from the cheap end of its range back to a bit under its usual premium.
TIKR tracks 41 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Mastercard needs about 16% a year
At 29.6x, buyers are paying for roughly what analysts already expect. That forecast takes normalized EPS from $17.01 in 2025 to $26.89 in 2028, or about 16% a year.
If Mastercard gets there and the multiple holds, the stock should roughly keep pace.
The multiple matters too. If it dropped back to the 25x-26x it traded at the end of each of 2026’s first three quarters, the same earnings would be worth about 13%-14% less. A return to the 10-year average would make them worth about 10% more.
Mastercard has grown about that fast for a decade. Its free cash flow rose from $4.42 billion in fiscal 2016 to $17.2 billion in fiscal 2025, about 16% a year, and fell only in 2020.
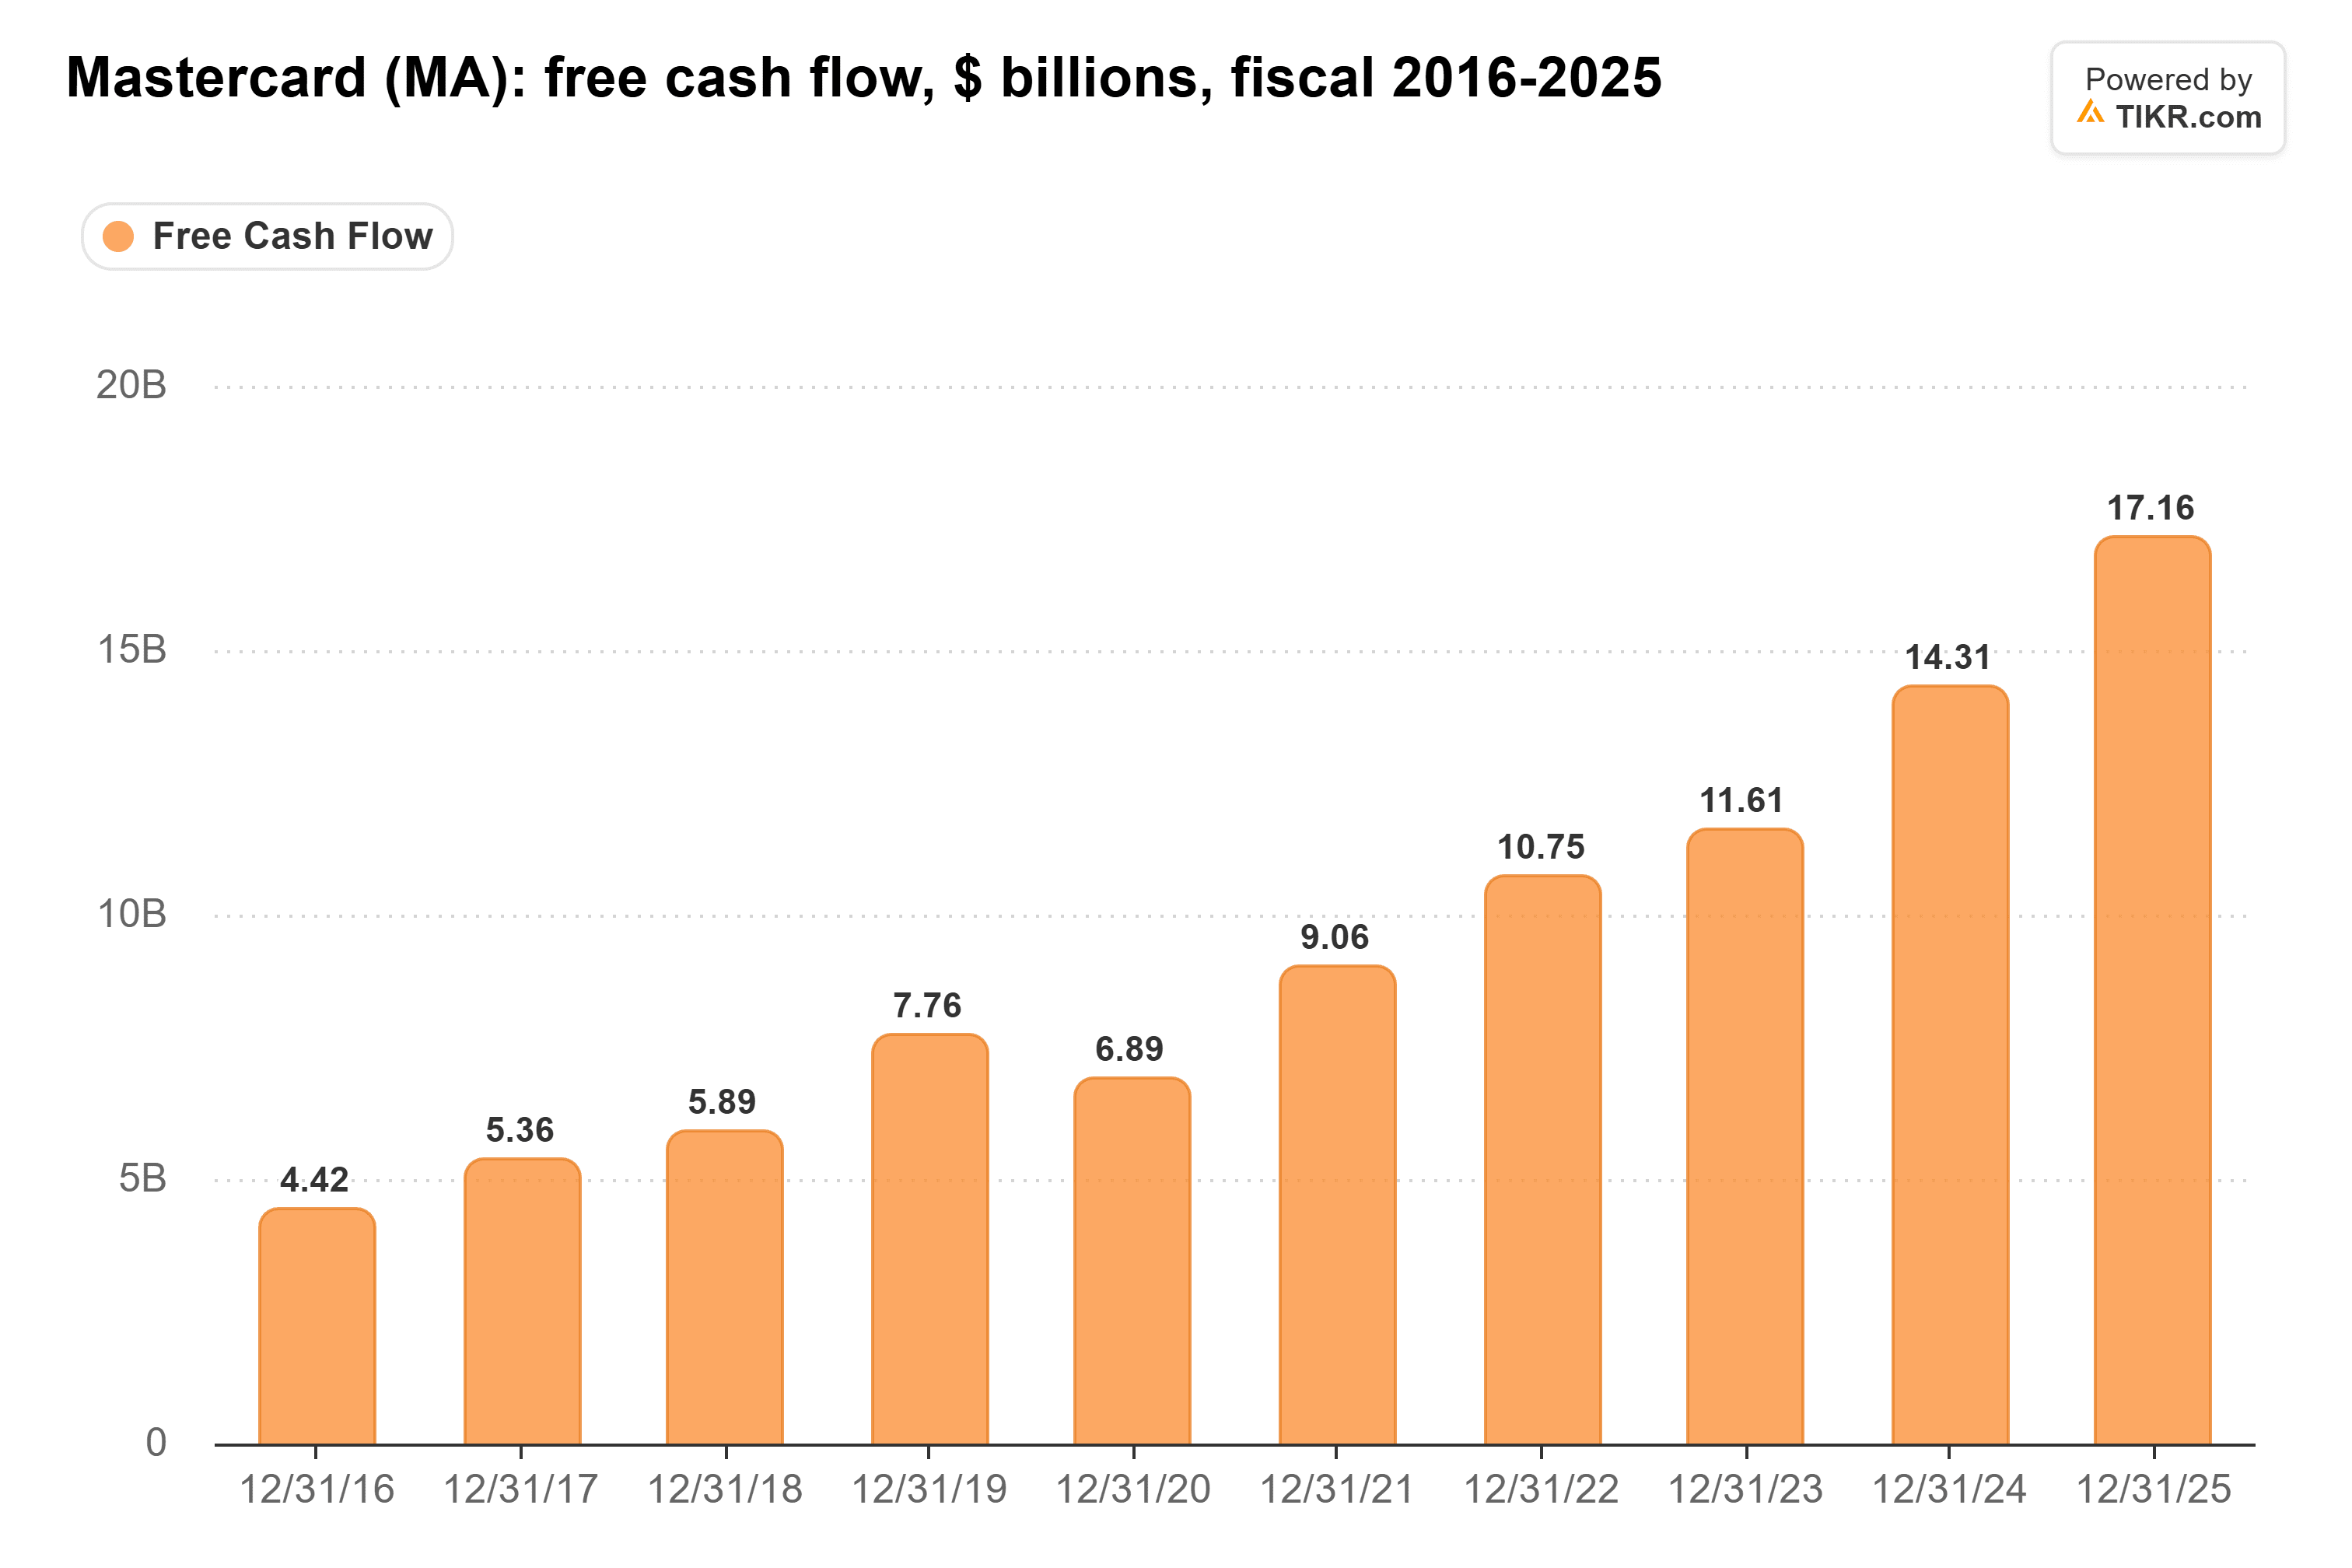
The risk is 2026. Analysts expect free cash flow to grow only about 3% this year. Meanwhile, rebates and incentives to banks took 52.4% of Mastercard’s gross network fees in Q2, up from 49.9% a year earlier.
Firms raised their targets after the report. Cantor Fitzgerald’s $765 is about 14% above the last close, while Monness kept its Hold rating with a $535 target.
A fair price for a great business
The way I see it, Mastercard is fairly priced here.
Buyers today pay a normal multiple for the earnings analysts expect. From here, they’ll earn roughly what that earnings growth delivers, without another boost from a rising multiple like the one behind the past month.
Q4 results in late January come next. Hai will give his first full-year guidance, and the revenue pulled into Q3 will come out of Q4.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


