Key Takeaways
- Blue Grotto Capital, a firm that manages $2.1 billion, sold all of its CDW, Celsius and Progressive shares in the third quarter, three positions that each made up more than 3% of its 13F stocks at June 30.
- Over the same quarter, it more than doubled its Microsoft stake, now its largest, and added 388% to its GE HealthCare shares.
- Celsius is the only one of the three that analysts see upside in, and its average target has fallen from $69 to $41 in a year.
- CDW is the one I’d still want to own, with sales up 18% last quarter, a raised outlook and a price of about 14x forward earnings.
A $2.1 billion firm just walked away from CDW (CDW), Celsius (CELH) and Progressive (PGR) entirely.
Blue Grotto Capital’s 13F for the quarter ended Sept. 30, filed Nov. 4, shows none of their shares. At June 30, they made up 3.7%, 3.6% and 3.2% of its 13F stocks, worth $44 million, $44 million and $39 million. A 13F shows only what a fund held on the quarter’s last day, so there’s no telling when in the quarter it sold or at what price.
CDW just raised its outlook
CDW is up 20% from its Sept. 30 price, and its third-quarter report on Nov. 4 gave investors plenty to like. Net sales rose 18% from a year earlier to $6.76 billion, non-GAAP earnings per share rose 20% to $3.26, and management raised its full-year outlook. The one soft spot: gross margin slipped to 20.5% from 21.9%.
Analysts have grown far more cautious over the past year, cutting their average target from $203 to $159:
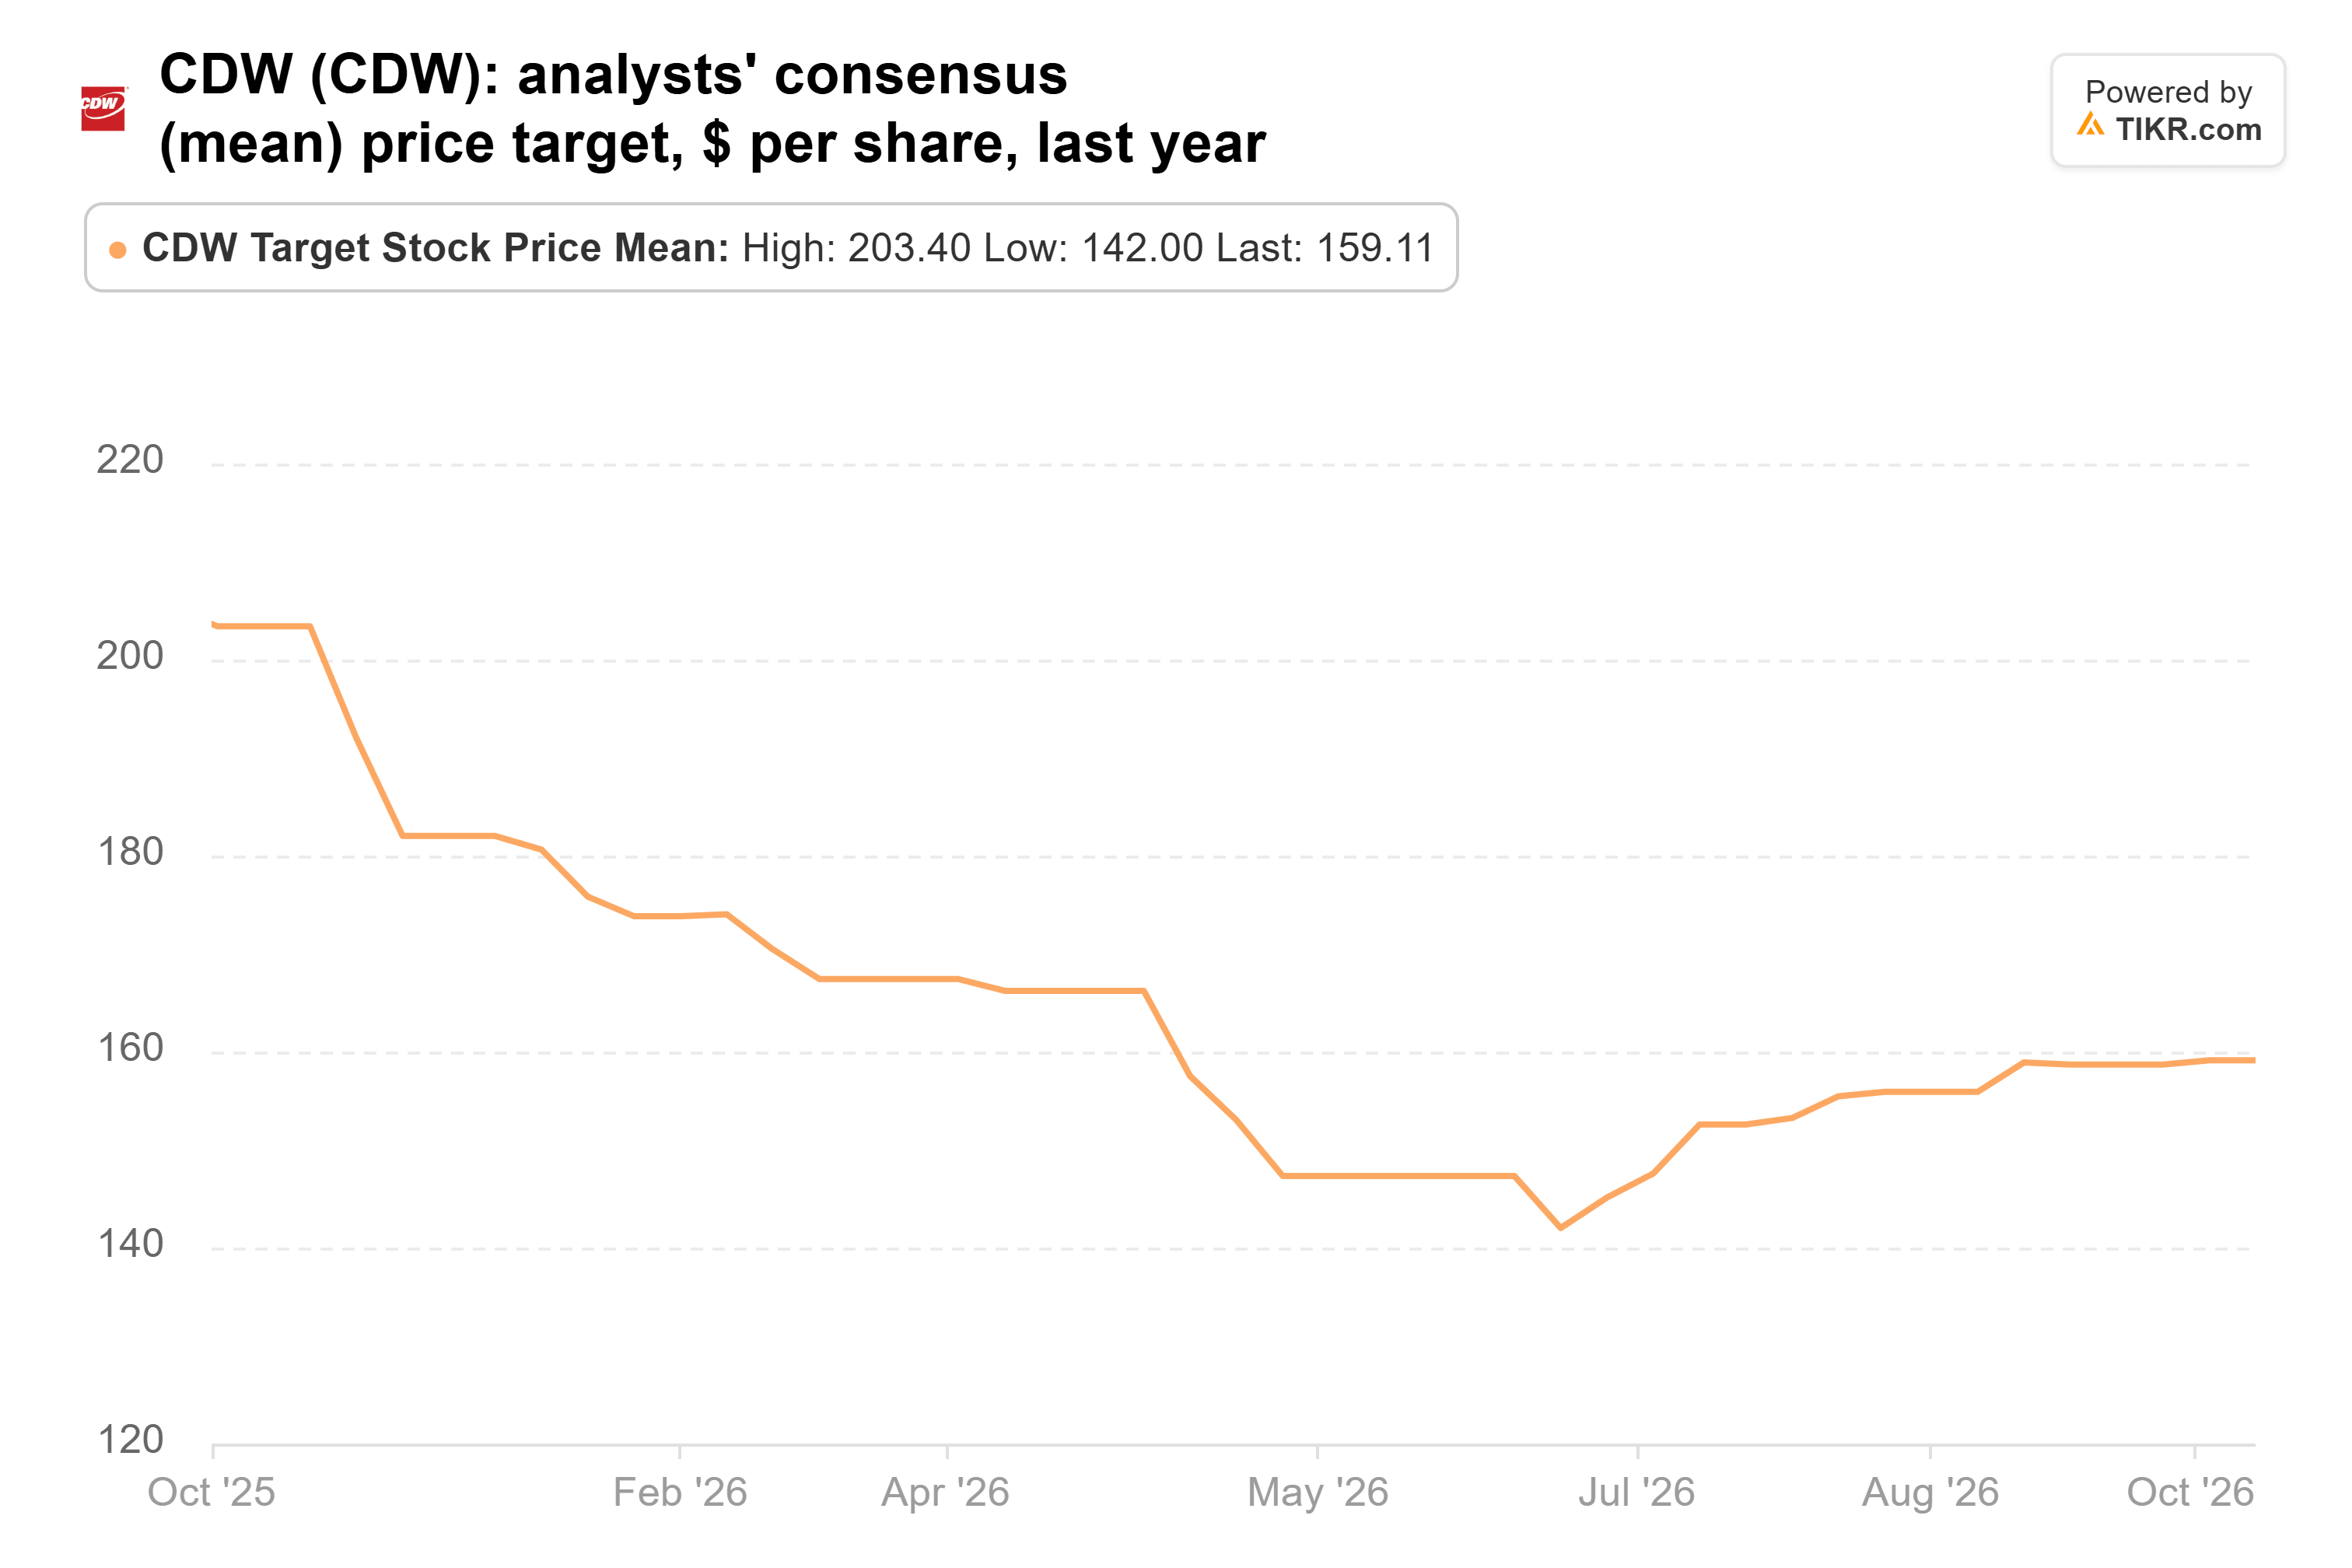
That leaves the stock 6% above the average target of its 10 analysts at Wednesday’s close of $168.75. Even so, CDW trades at about 14x forward earnings.
TIKR tracks 10 analysts on CDW. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CDW, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CDW’s Analyst Ratings
The Street still sees upside in Celsius, just less of it
Celsius is the only one of the three that analysts think has room to run. Its 24 analysts’ average target of $41.10 sits 34% above Wednesday’s close of $30.75.
But that target has been cut hard over the past year:
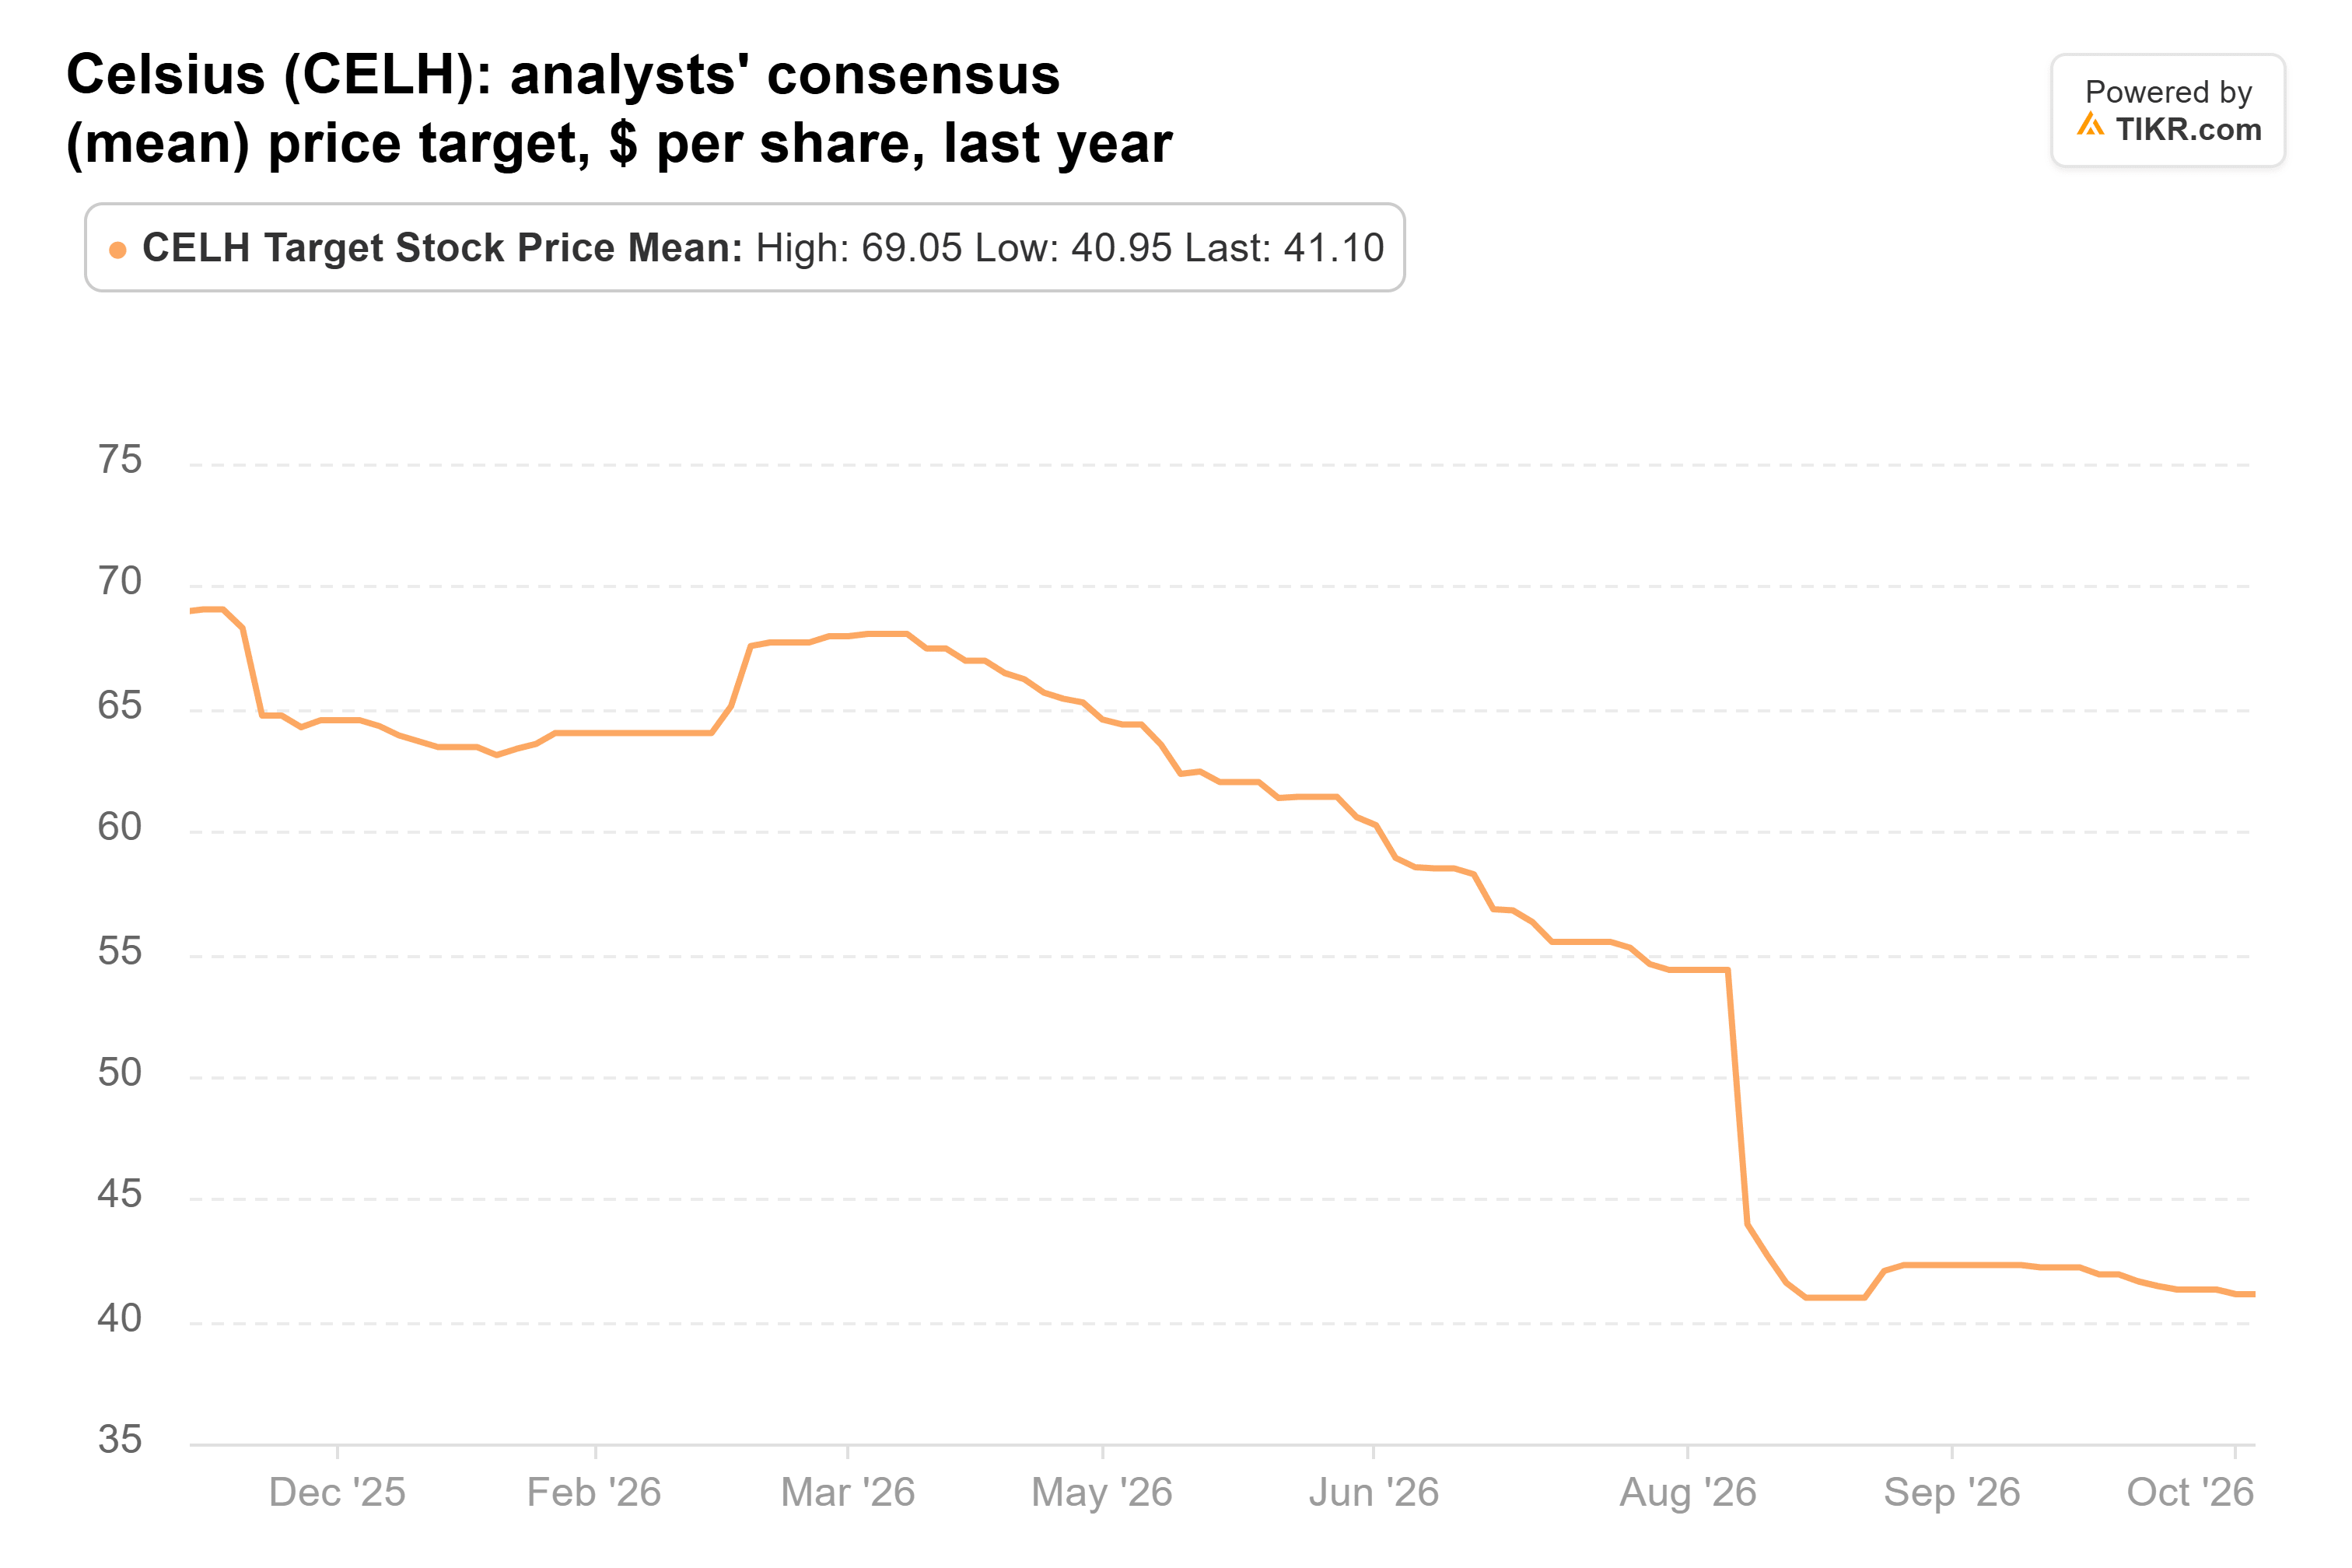
The target started the year at $69.05, and the stock fell even further, from $59.25 to $30.75. It’s now 50% below its 52-week high, though up 5% from its Sept. 30 price.
Celsius’ second-quarter revenue rose 11% to $817.9 million, and $66.5 million of that came from Rockstar Energy, a brand it bought. The Celsius brand’s own revenue fell about 11.7%. Management put that down to heavier promotions, shipment timing and a soft club channel, among other things.
At about 23x forward earnings, Celsius isn’t cheap for a company whose namesake brand is shrinking.
Progressive’s numbers back the sale
Progressive is the opposite case. It’s up 7% from its Sept. 30 price, and it already trades 1% above the $232 average target of its 25 analysts. That target has slid from $261 a year ago:
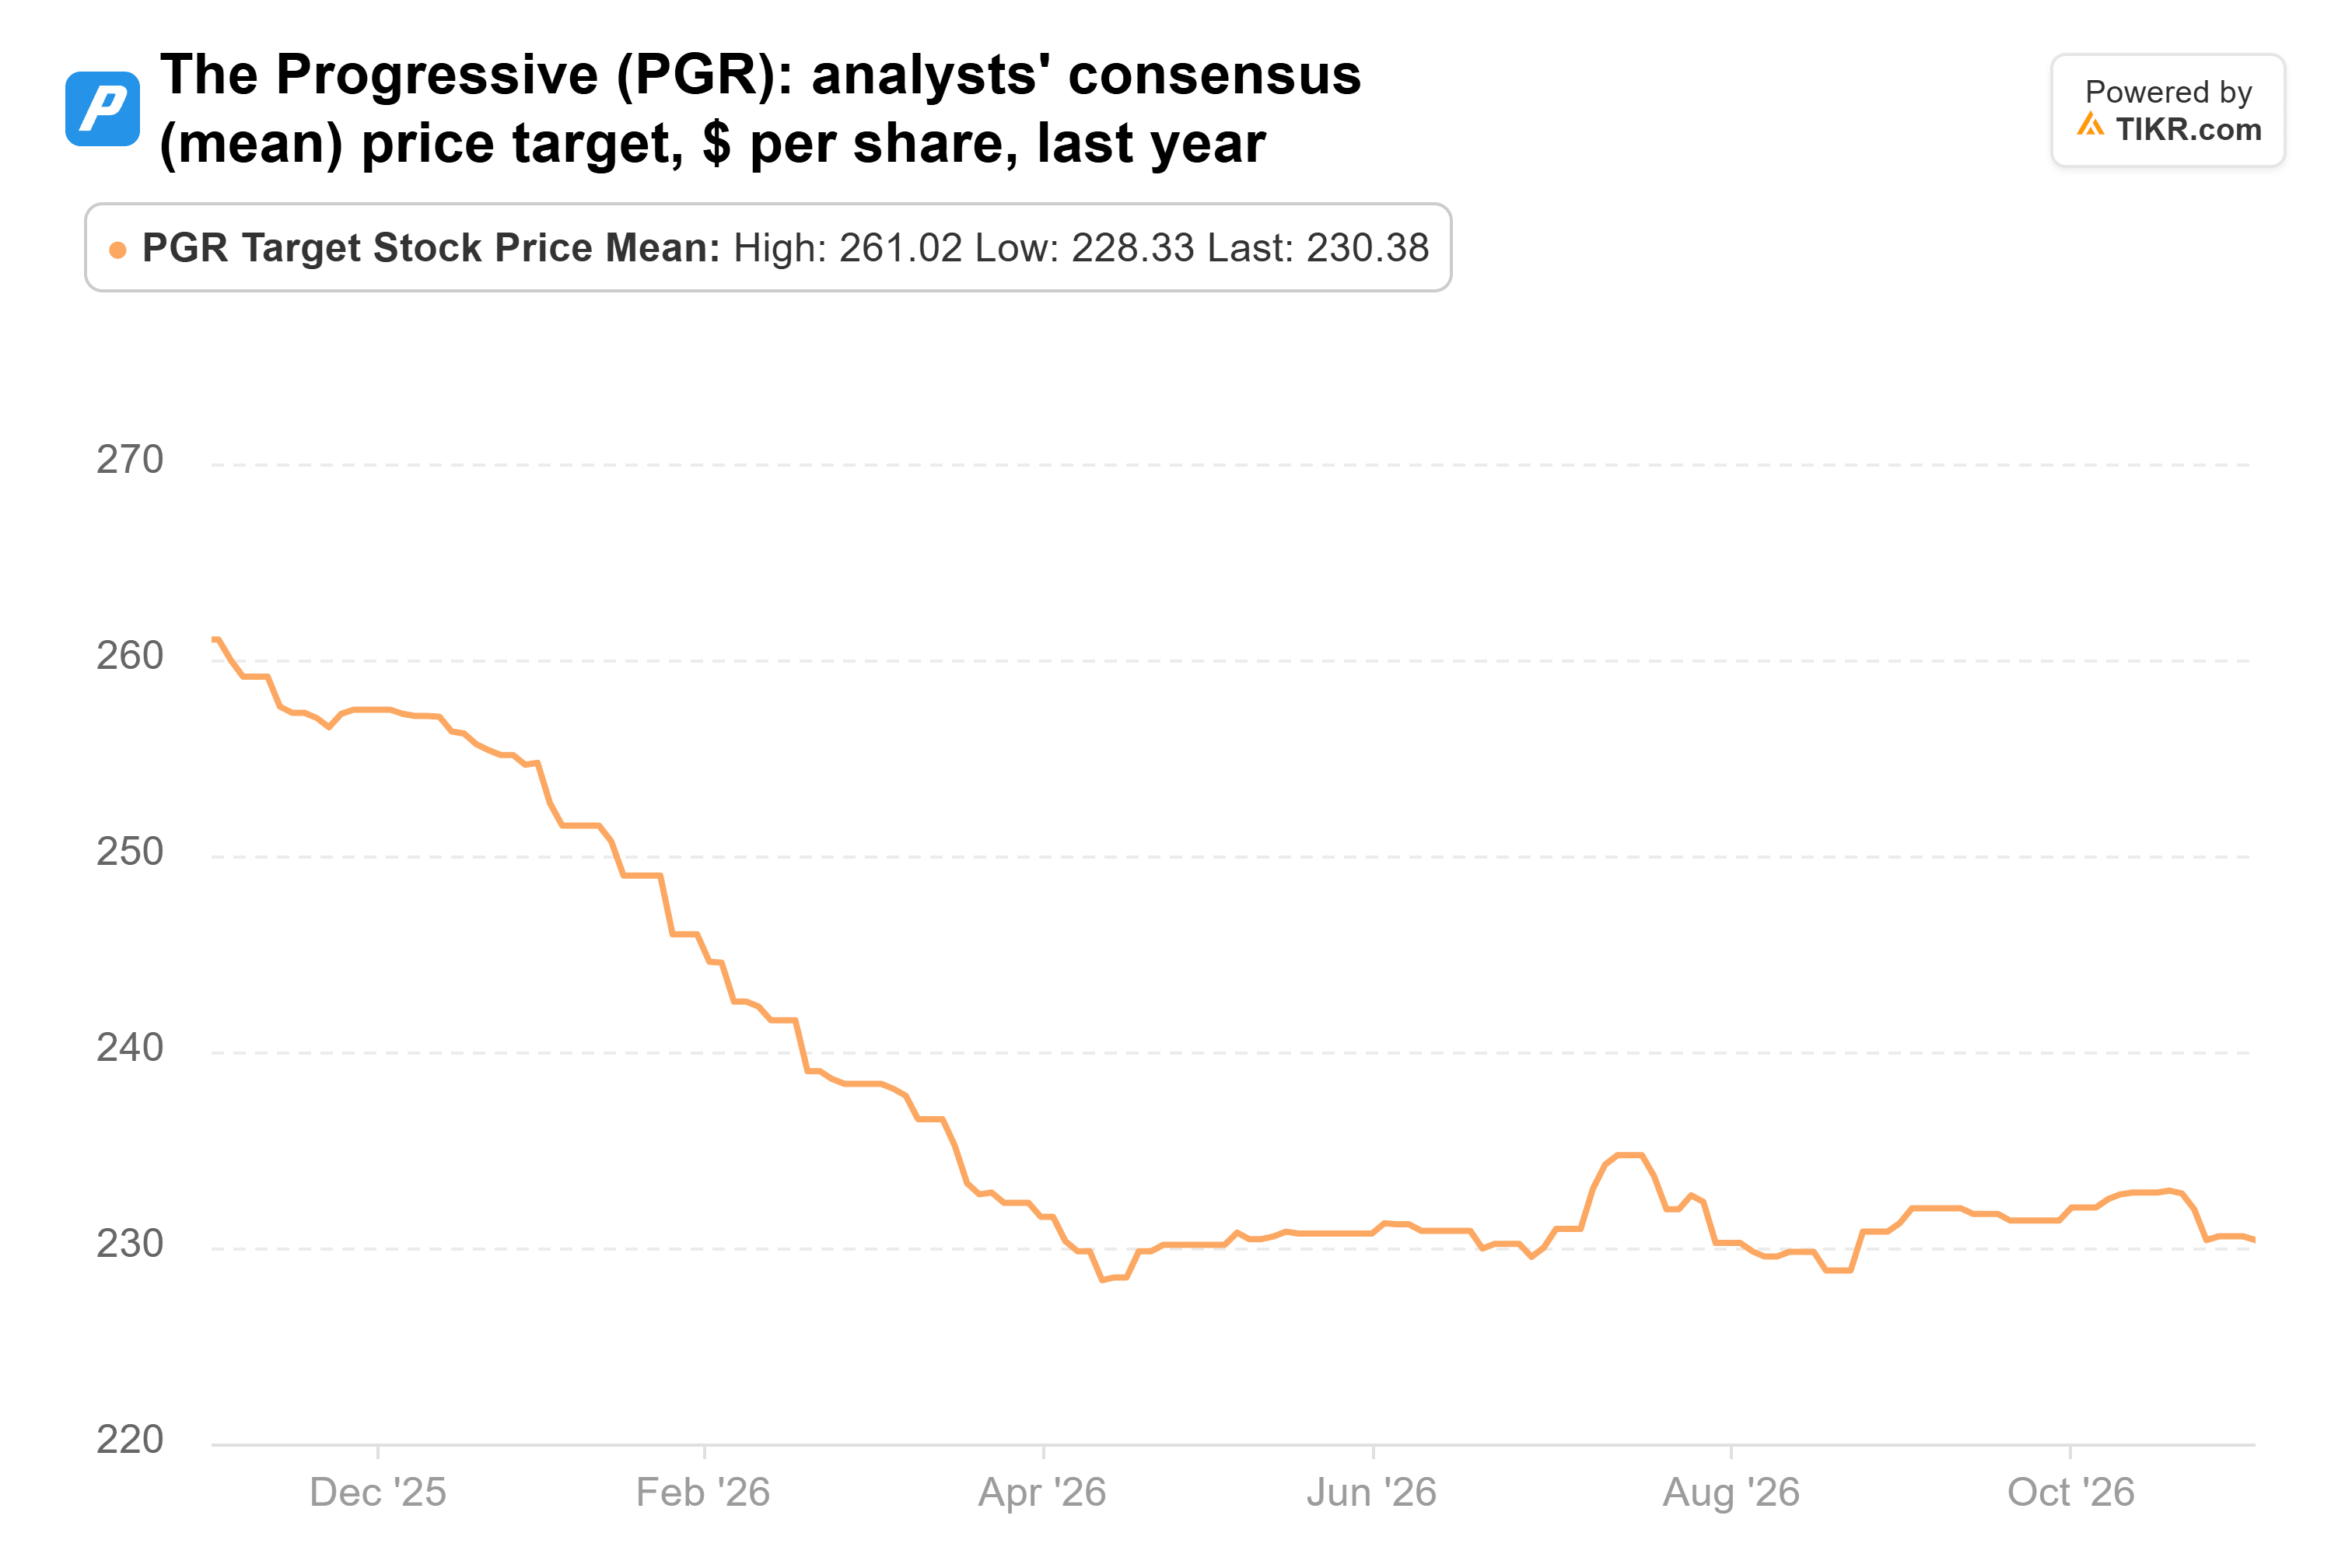
Progressive is still very profitable. Its combined ratio improved to 88.7 in the third quarter from 89.5 a year earlier, far better than the 96 it has long targeted. But net premiums written grew just 4%, to $22.3 billion, and its personal auto rates were flat in the quarter. Net income fell 3% to $2.54 billion on realized investment losses.
With margins that fat and rates flat, I’d expect rivals to keep chasing the same drivers, and premium growth to stay slow. At about 15x forward earnings, I don’t see much reason to rush back in.
Microsoft is now its biggest bet
Blue Grotto was busy on the buying side, too. Over the same quarter, it raised its Microsoft (MSFT) stake 120%, to 220,248 shares worth $113 million at Sept. 30. That’s 7.8% of its 13F stocks and its largest position. It also added 388% to its GE HealthCare (GEHC) shares, bringing it to 1.20 million shares worth $78 million, its fourth-largest at 5.4%.
Both have done well since. Microsoft is up 8% from its Sept. 30 price, and its $633 average target is still 14% above the stock. GE HealthCare is up 31%, and its $88 average target is just 2% above the stock.
CDW is the one I’d keep
The risk with CDW is its margin: gross profit grew 10% last quarter, well behind sales.
Still, if I could only own one of these three today, it’d be CDW. That’s a lot of growth for about 14x forward earnings. Progressive’s exit looks the easiest to defend, and Celsius’ 34% upside depends on a brand that has to start growing again.
Of course, Celsius reports its third quarter any day now, and a quarter of growth from its namesake brand would change that call. Blue Grotto’s next 13F, for the quarter ending Dec. 31, is due in mid-February.
So what is CDW stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CDW could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!