Key Takeaways
- MercadoLibre shares fell 9% after third-quarter EPS of $8.83 missed the $9.27 consensus.
- Management blamed the 6.3% operating margin on free shipping, fulfillment centers and Brazil marketing.
- Brazil’s falling cost per shipment suggests MercadoLibre can work the squeeze down.
- Sea Limited and Nu Holdings report next week, testing its share gains and credit.
MercadoLibre (MELI) stock is down 9% today after its third-quarter profit missed estimates. Management’s explanation for the shrinking shipping margin? It’s “the price of the habit.”
That habit is being built on Brazil’s low-priced orders, the ones Sea Limited (SE) chases with Shopee. And the quarter’s steady credit sets a bar for Nu Holdings (NU).
Where the profit went
Revenue rose 45% to $10.75 billion, ahead of estimates. But EPS missed as operating income fell 6% to $676 million on more free shipping, almost 20% more fulfillment space ahead of the holidays, and extra affiliate marketing in Brazil.
Analysts expected margins to drive a rebound:
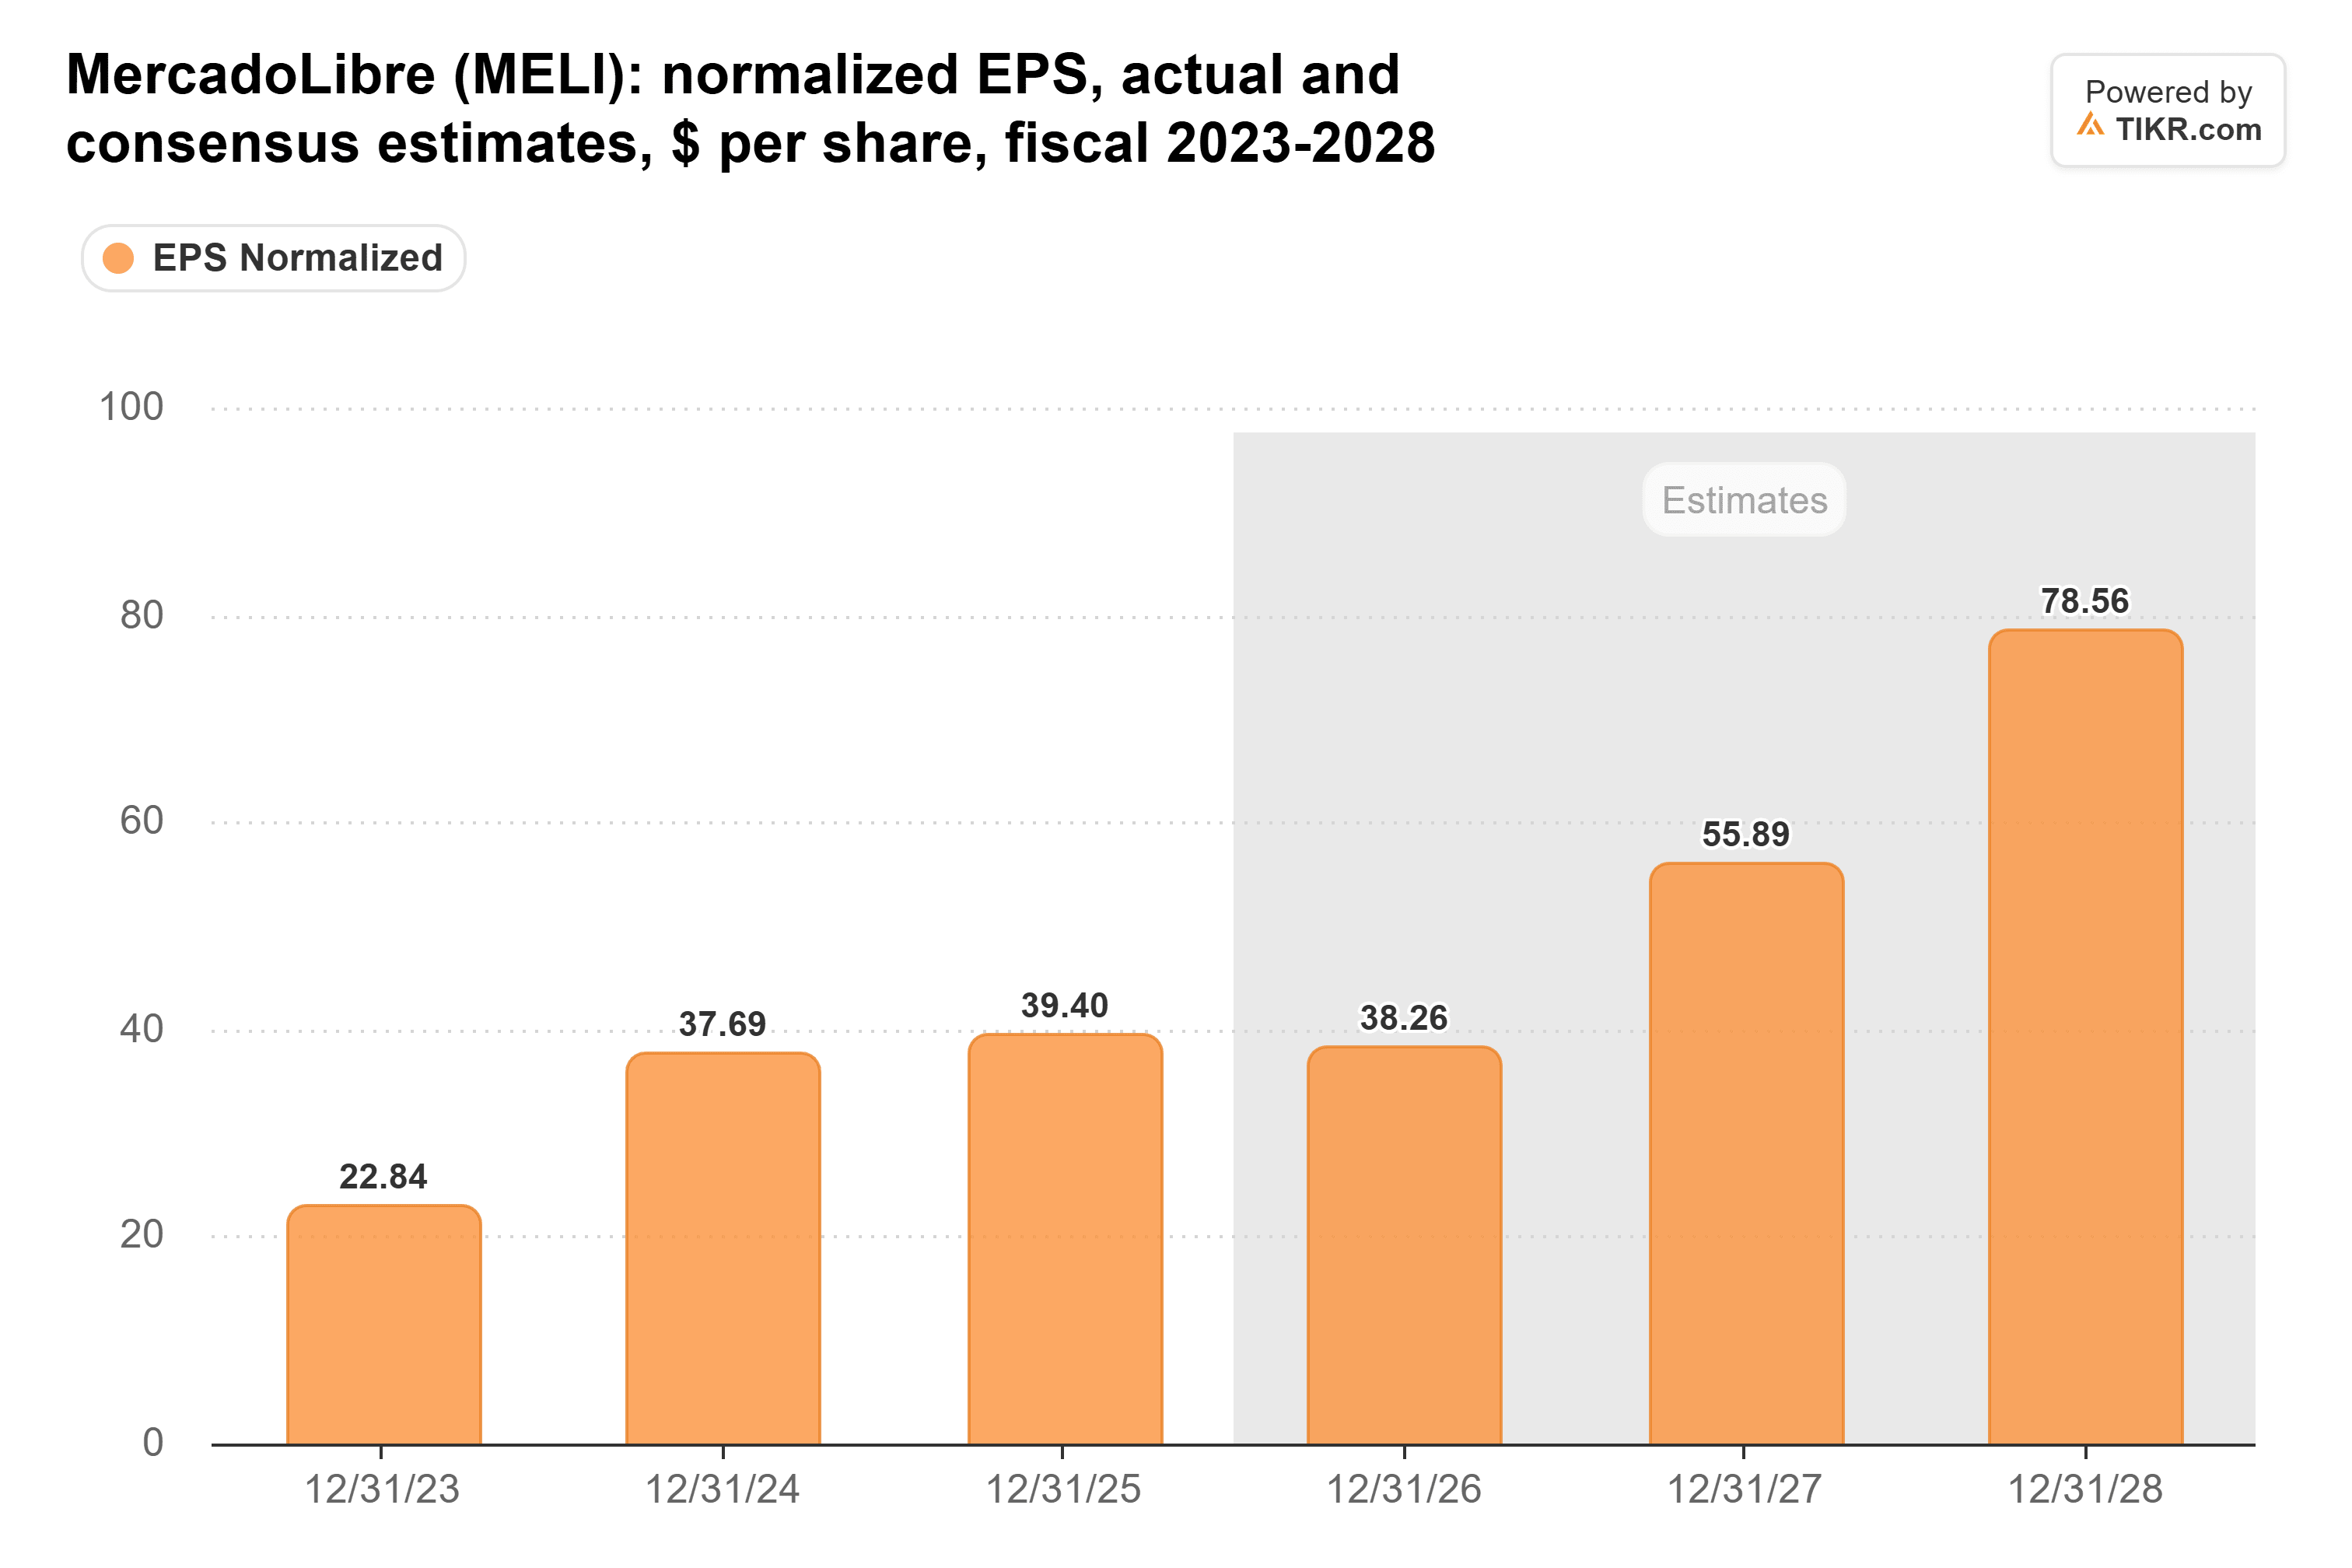
Their 2026 numbers implied a second-half operating margin of about 7.1%, so after a 6.3% quarter, this year’s and 2027’s estimates both look high.
TIKR tracks 26 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
Paying for the habit
MercadoLibre cut Brazil’s free shipping threshold to R$19 from R$79 in June 2025, and items sold there have grown more than 40% for five straight quarters since.
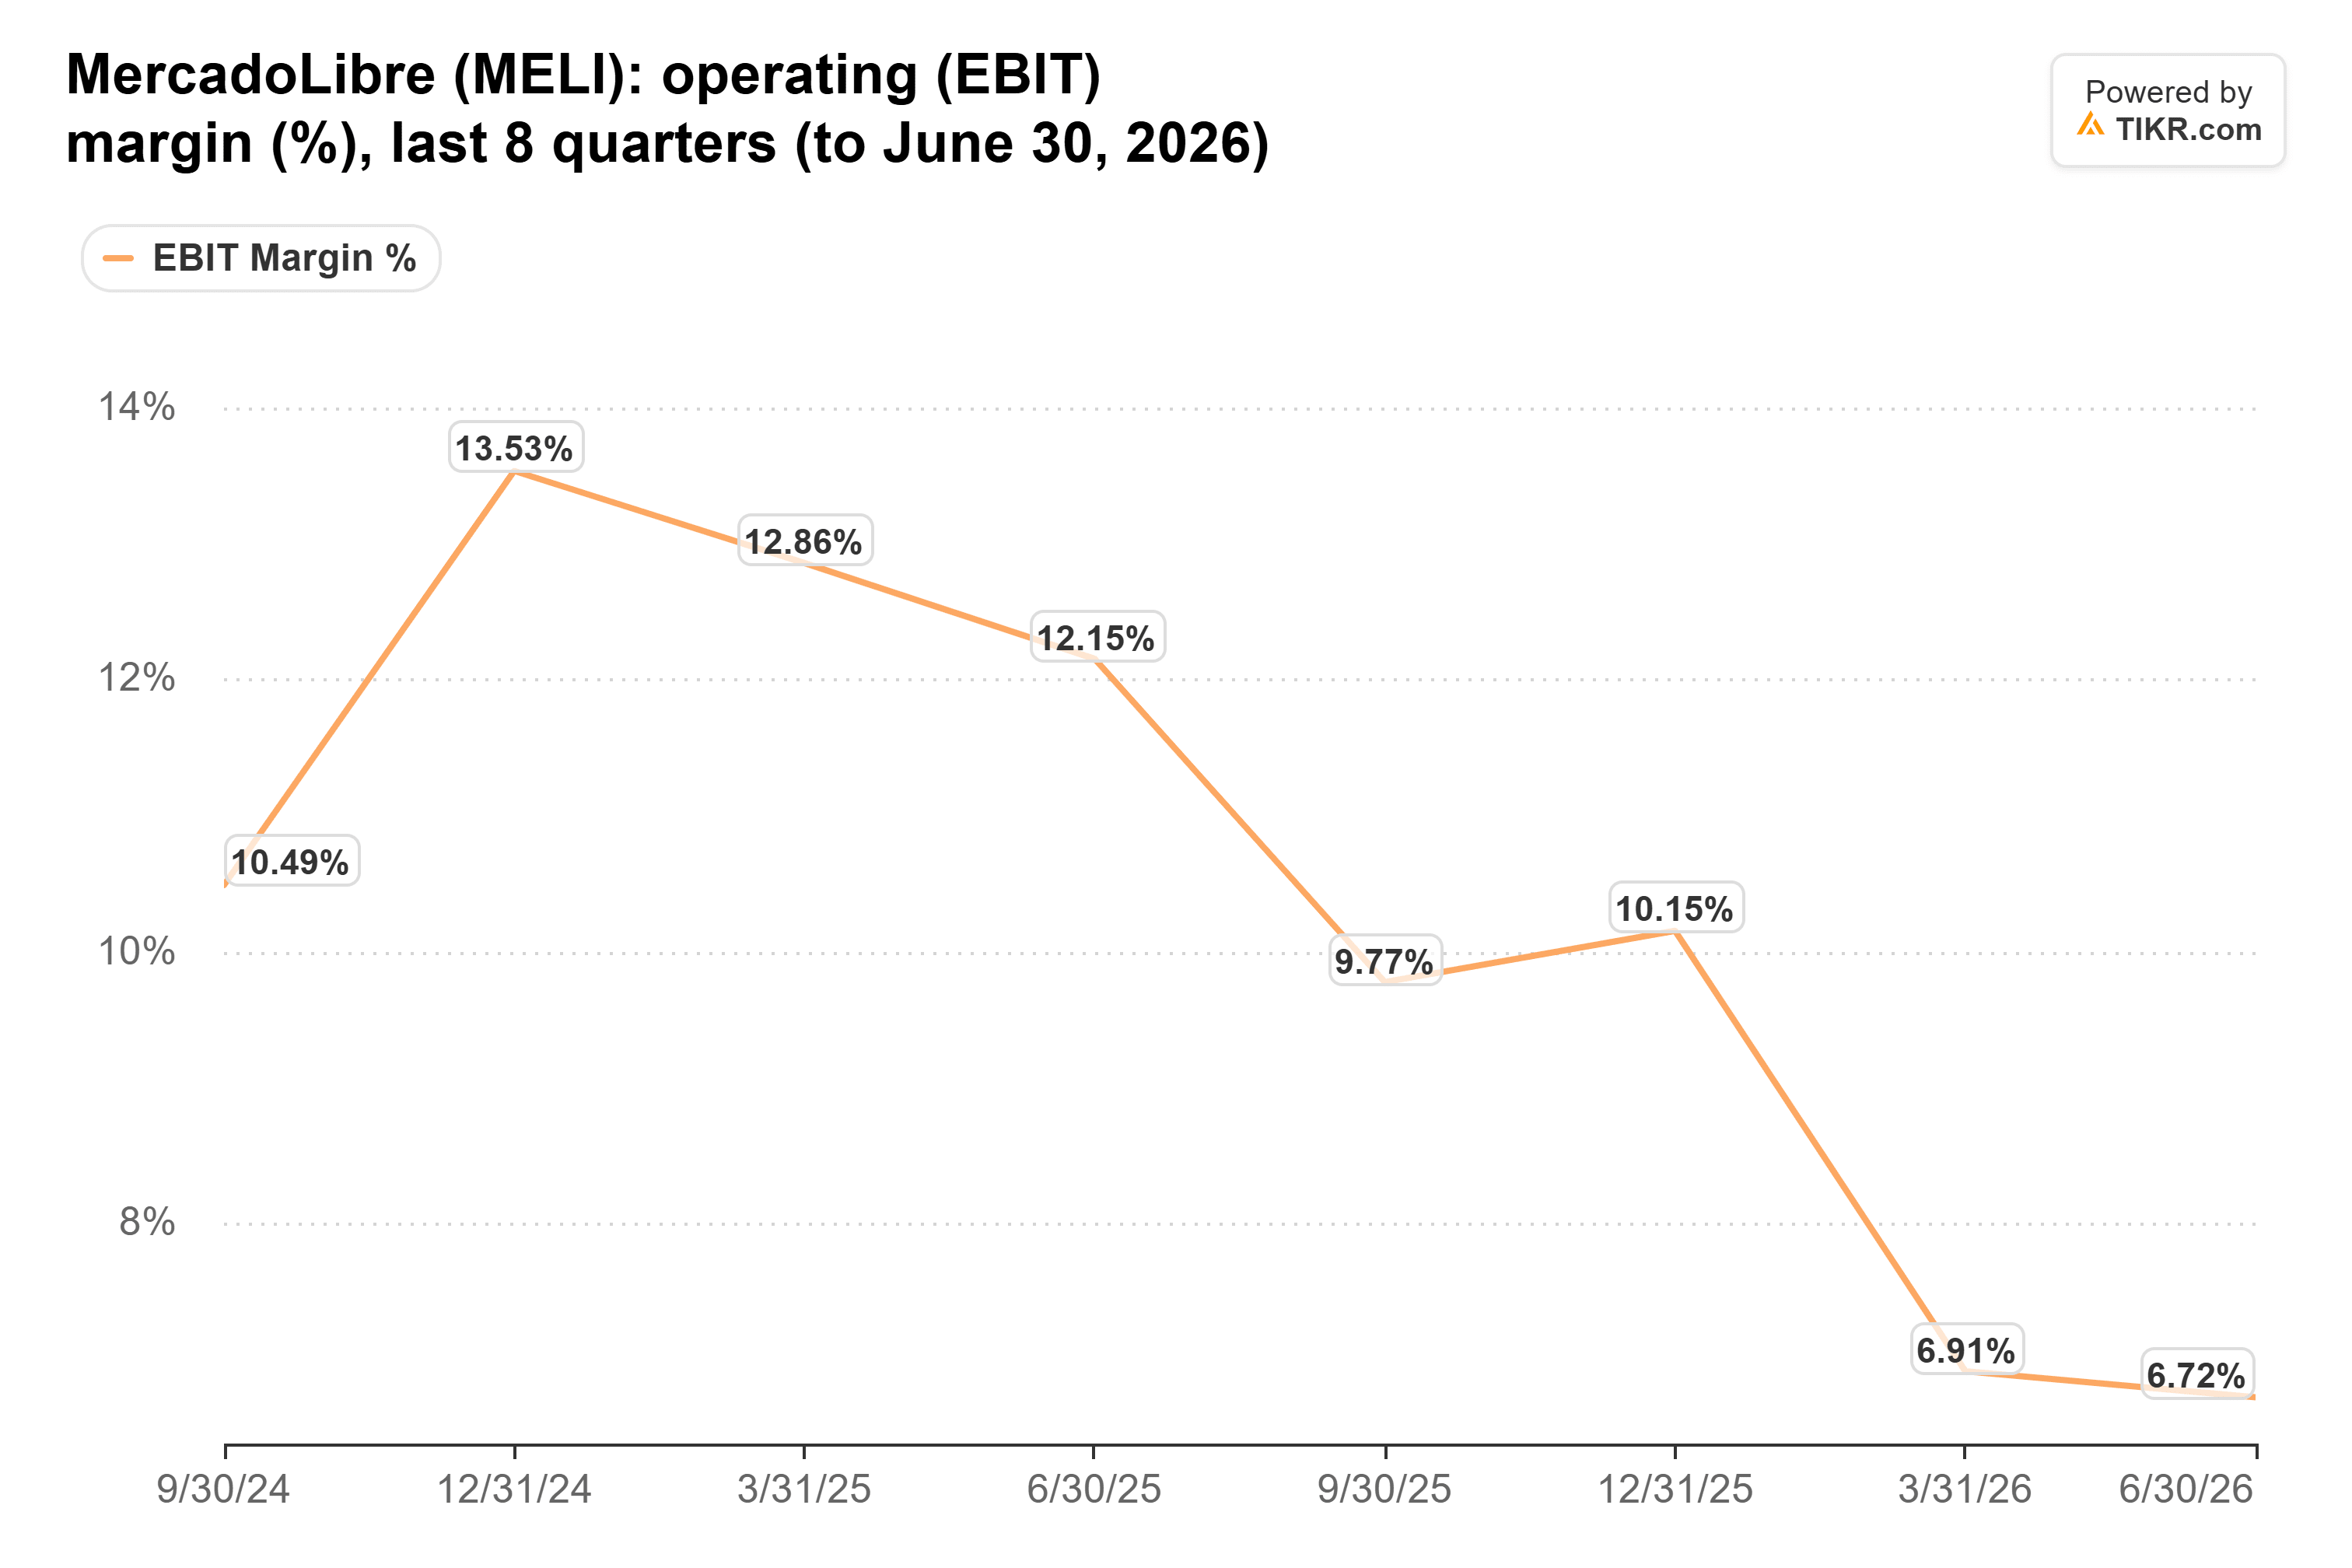
But cheaper items earn less each, so net shipping margin has lost about 200 basis points of gross merchandise volume since early 2025.
The margin was sliding well before the third quarter, when it fell to 6.3% from 9.8%:
The bill is starting to shrink
Brazil’s cost per shipment fell 5% from a year earlier in local currency. And in September, free, slow shipments priced from R$19 to R$79 covered their variable costs as a group for the first time.
That push lands on Shopee, whose Brazil capacity Sea grew 60% in a year. If Shopee’s Brazil growth slows next week, MercadoLibre’s shipping spend is buying share.
Credit held up, too: MercadoLibre’s 15-90 day NPL stayed around 7.0%. Nu’s improved to 4.8% in the second quarter, and its report next week will show whether its Brazil book is as steady.
Cheaper than usual
MercadoLibre traded at 41x forward earnings at Wednesday’s close, far below its five-year average of 63x:

At today’s price, it’s even lower, about 37x.
The way I see it, MercadoLibre is buying a habit with margin, and at this price, the squeeze is worth sitting through.
Of course, the holidays will show whether all that new fulfillment space fills up.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!