Key Takeaways
- MercadoLibre fell 14% over three months to $1,625, with the steepest drop coming after Lula’s surprise runoff win sent Brazilian assets lower on October 26.
- Brazil supplied 52.6% of 2025 revenue, so a weaker real and consumer credit now matter more than the 50% sales growth the company posted in the second quarter.
- Second-quarter operating margin fell to 6.7% from 12.2% as MercadoLibre cut fees and expanded credit, while Shopee keeps adding capacity in Brazil.
- The November 4 report covers a quarter that ended before the election, so management’s Brazil commentary matters as much as the numbers.
Brazil voted, and MercadoLibre shareholders paid for it.
MercadoLibre (MELI) closed Friday at $1,625, down 14% over three months and 32% below its 52-week high of $2,388. The sharpest hit came on October 26, the first trading day after President Lula’s surprise runoff win. Shares fell more than 11% early that session as investors dumped Brazilian assets.
Competition isn’t easing either. Sea Limited (SE) increased capacity for its Shopee marketplace in Brazil by 60% in one year, and it is waiting on regulation to start selling medicine there. That lands right where MercadoLibre is expanding.
MercadoLibre reports third-quarter results on November 4, after the close.
Election night, then the selloff
Three weeks earlier, the mood was very different. Flávio Bolsonaro took 47% of the first-round vote on October 4 against Lula’s 45%, and MercadoLibre rallied with Brazilian banks.
The runoff erased that trade. Investors now worry about Brazil’s fiscal path, a weaker currency and what both mean for consumer borrowers.
The exposure is hard to overstate:
- Brazil generated $15.2 billion of MercadoLibre’s $28.9 billion in 2025 revenue.
- The company planned to invest about 57 billion reais, roughly $10.9 billion, in Brazil this year, 50% more than in 2025.
- It launched one-hour deliveries and expanded its pharmacy business there in September.
The round trip shows up clearly in the share price.
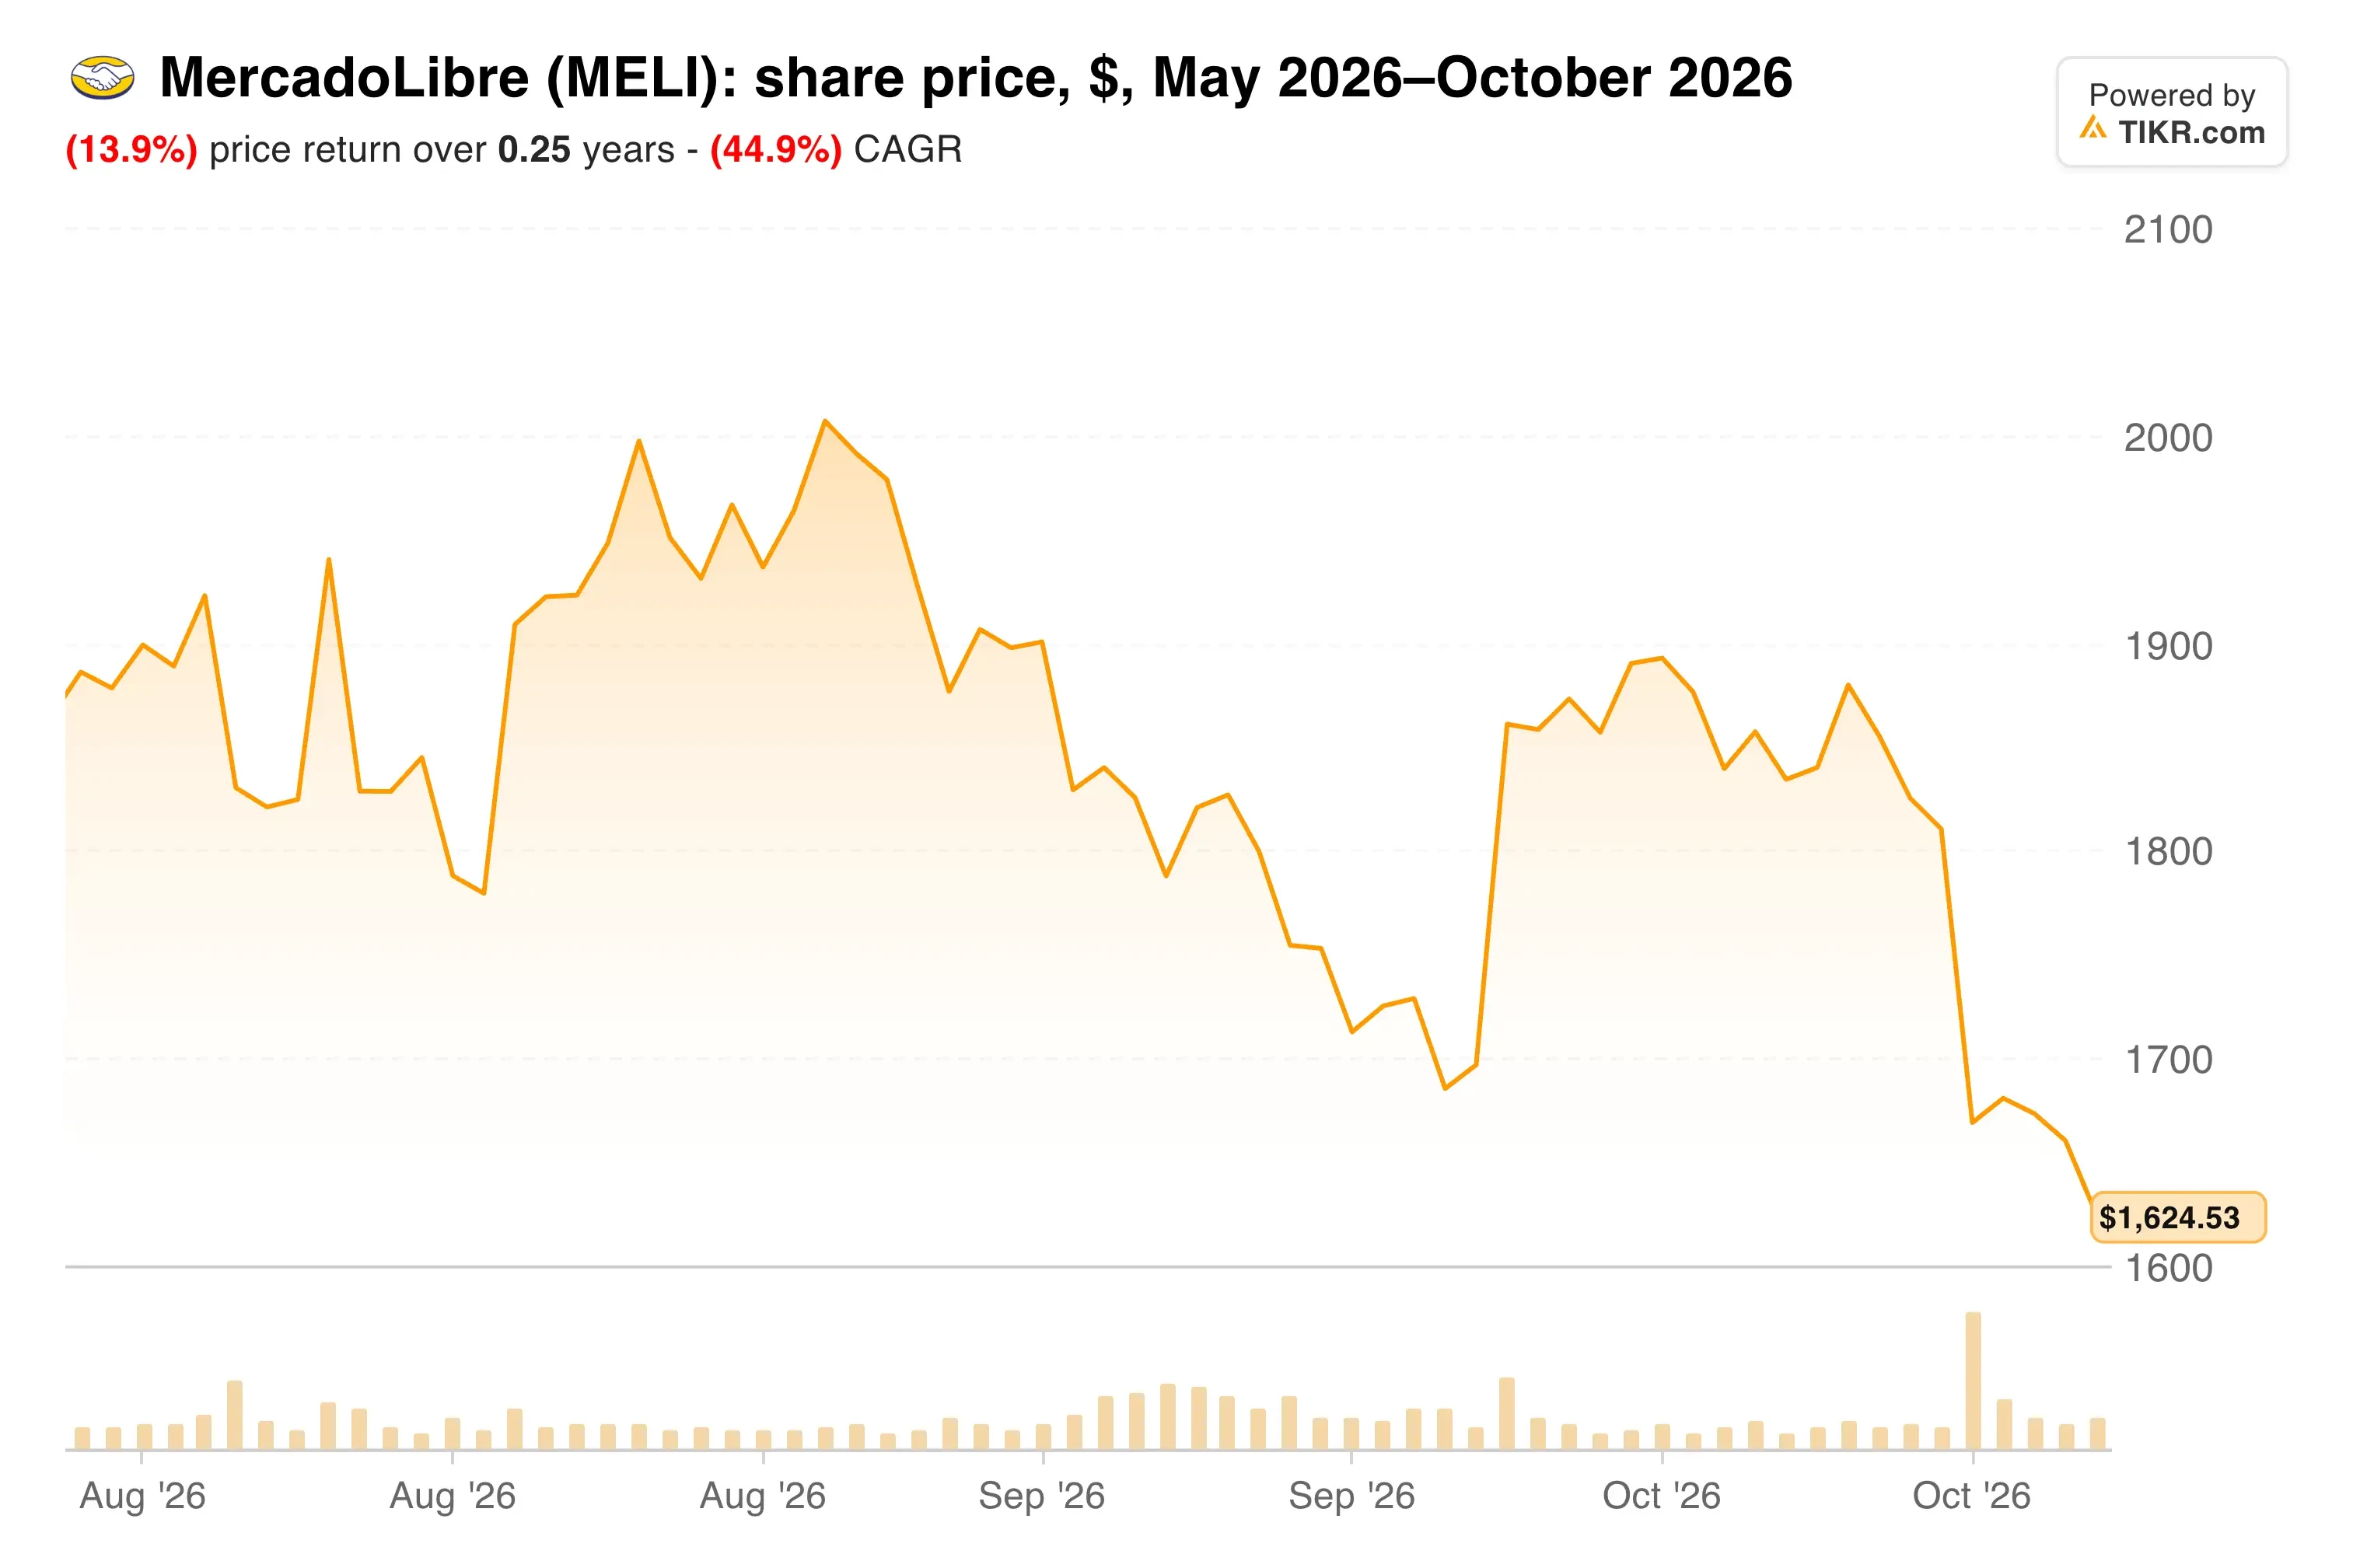
The stock now trades just 9% above its 52-week low of $1,495.
Growth bought with margin
MercadoLibre’s second quarter showed the trade-off it is making. Revenue grew about 50% to more than $10 billion, and GMV rose 36% on an FX-neutral basis. But operating margin fell to 6.7% from 12.2% a year earlier.
That compression is deliberate. The company lowered free-shipping thresholds and seller fees in Brazil, and it kept growing credit fast. Its loan book reached $16.4 billion, up 75%.
Credit quality has held so far. Loans 15 to 90 days past due sat at 7.0%, and credit card NPLs at 4.6%, both near historical lows. “So far, we are not seeing any deceleration or deterioration of credit book in Brazil,” fintech president Osvaldo Giménez said on the second-quarter call.
How far has the margin actually fallen?
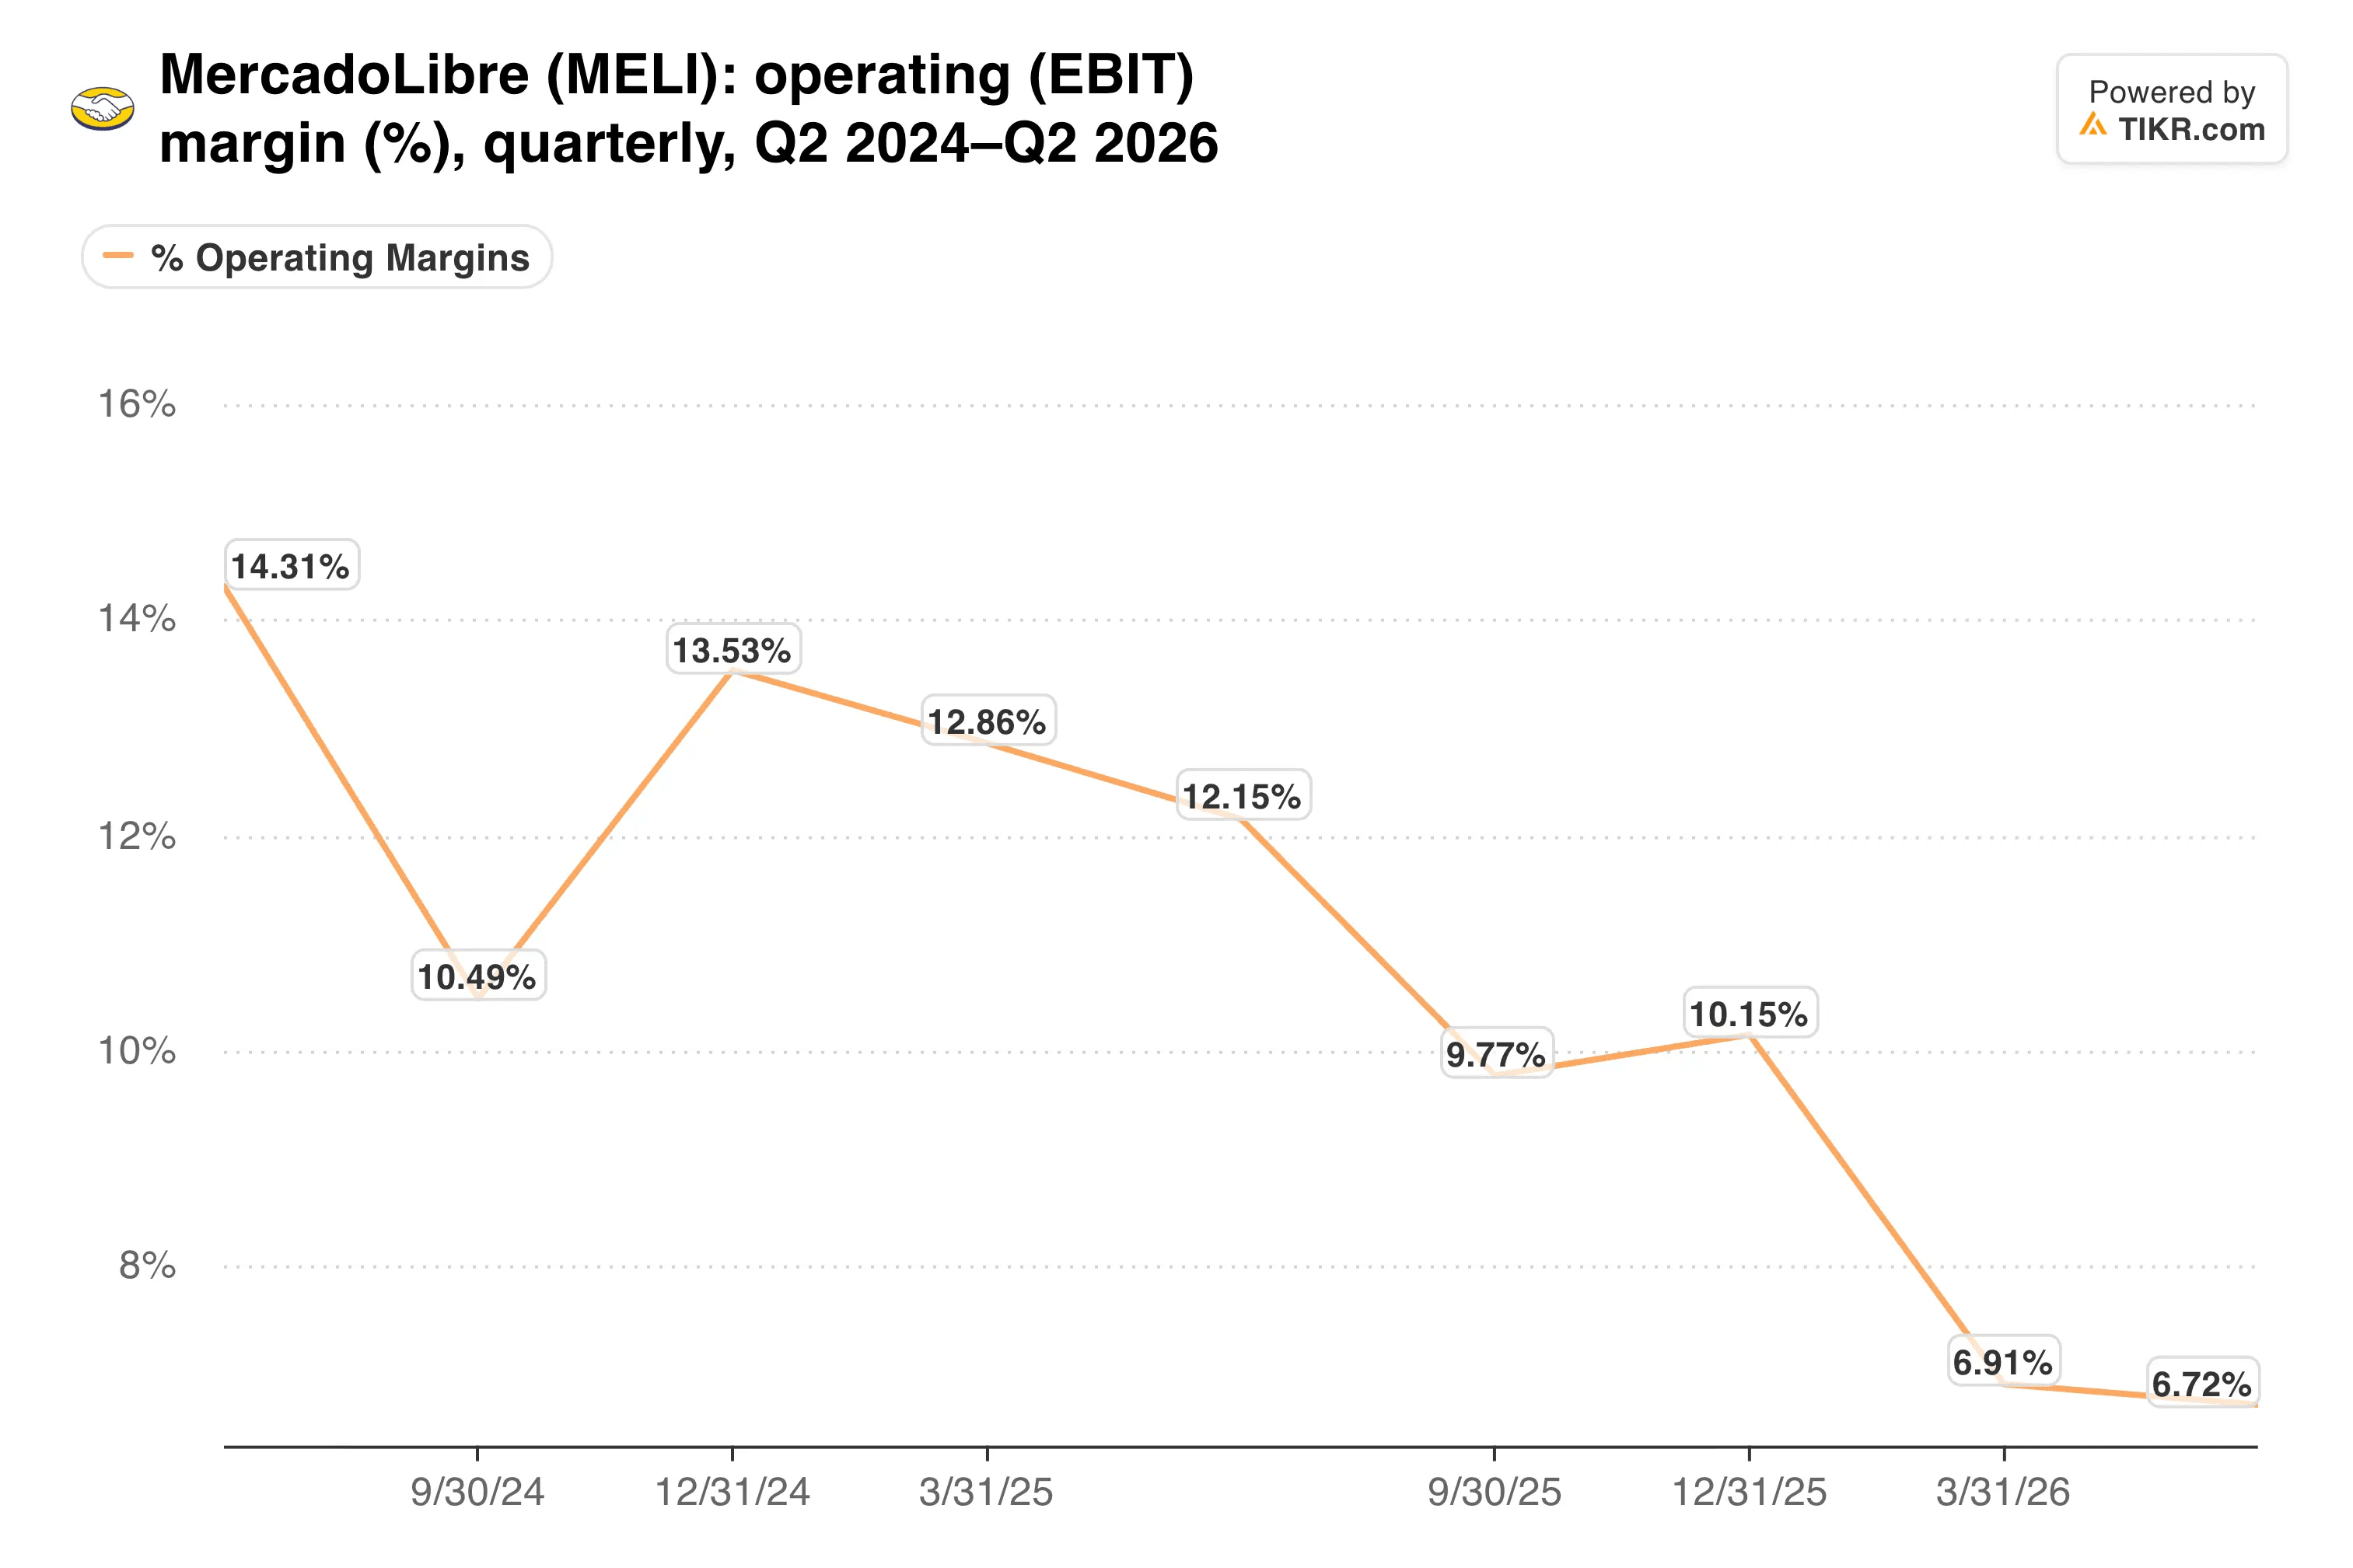
It roughly halved in a year, so the third quarter needs to show a floor.
TIKR tracks 26 analysts on MercadoLibre. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on MercadoLibre, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See MercadoLibre’s Analyst Ratings
Cheap only if credit holds
Consensus expects third-quarter revenue of about $10.7 billion and EPS of $9.41. The quarter ended September 30, before the runoff, so the reported numbers won’t capture the election shock. Fourth-quarter commentary will.
Valuation has already reset. MercadoLibre trades at 39.3x forward earnings, well below its five-year average near 63x…
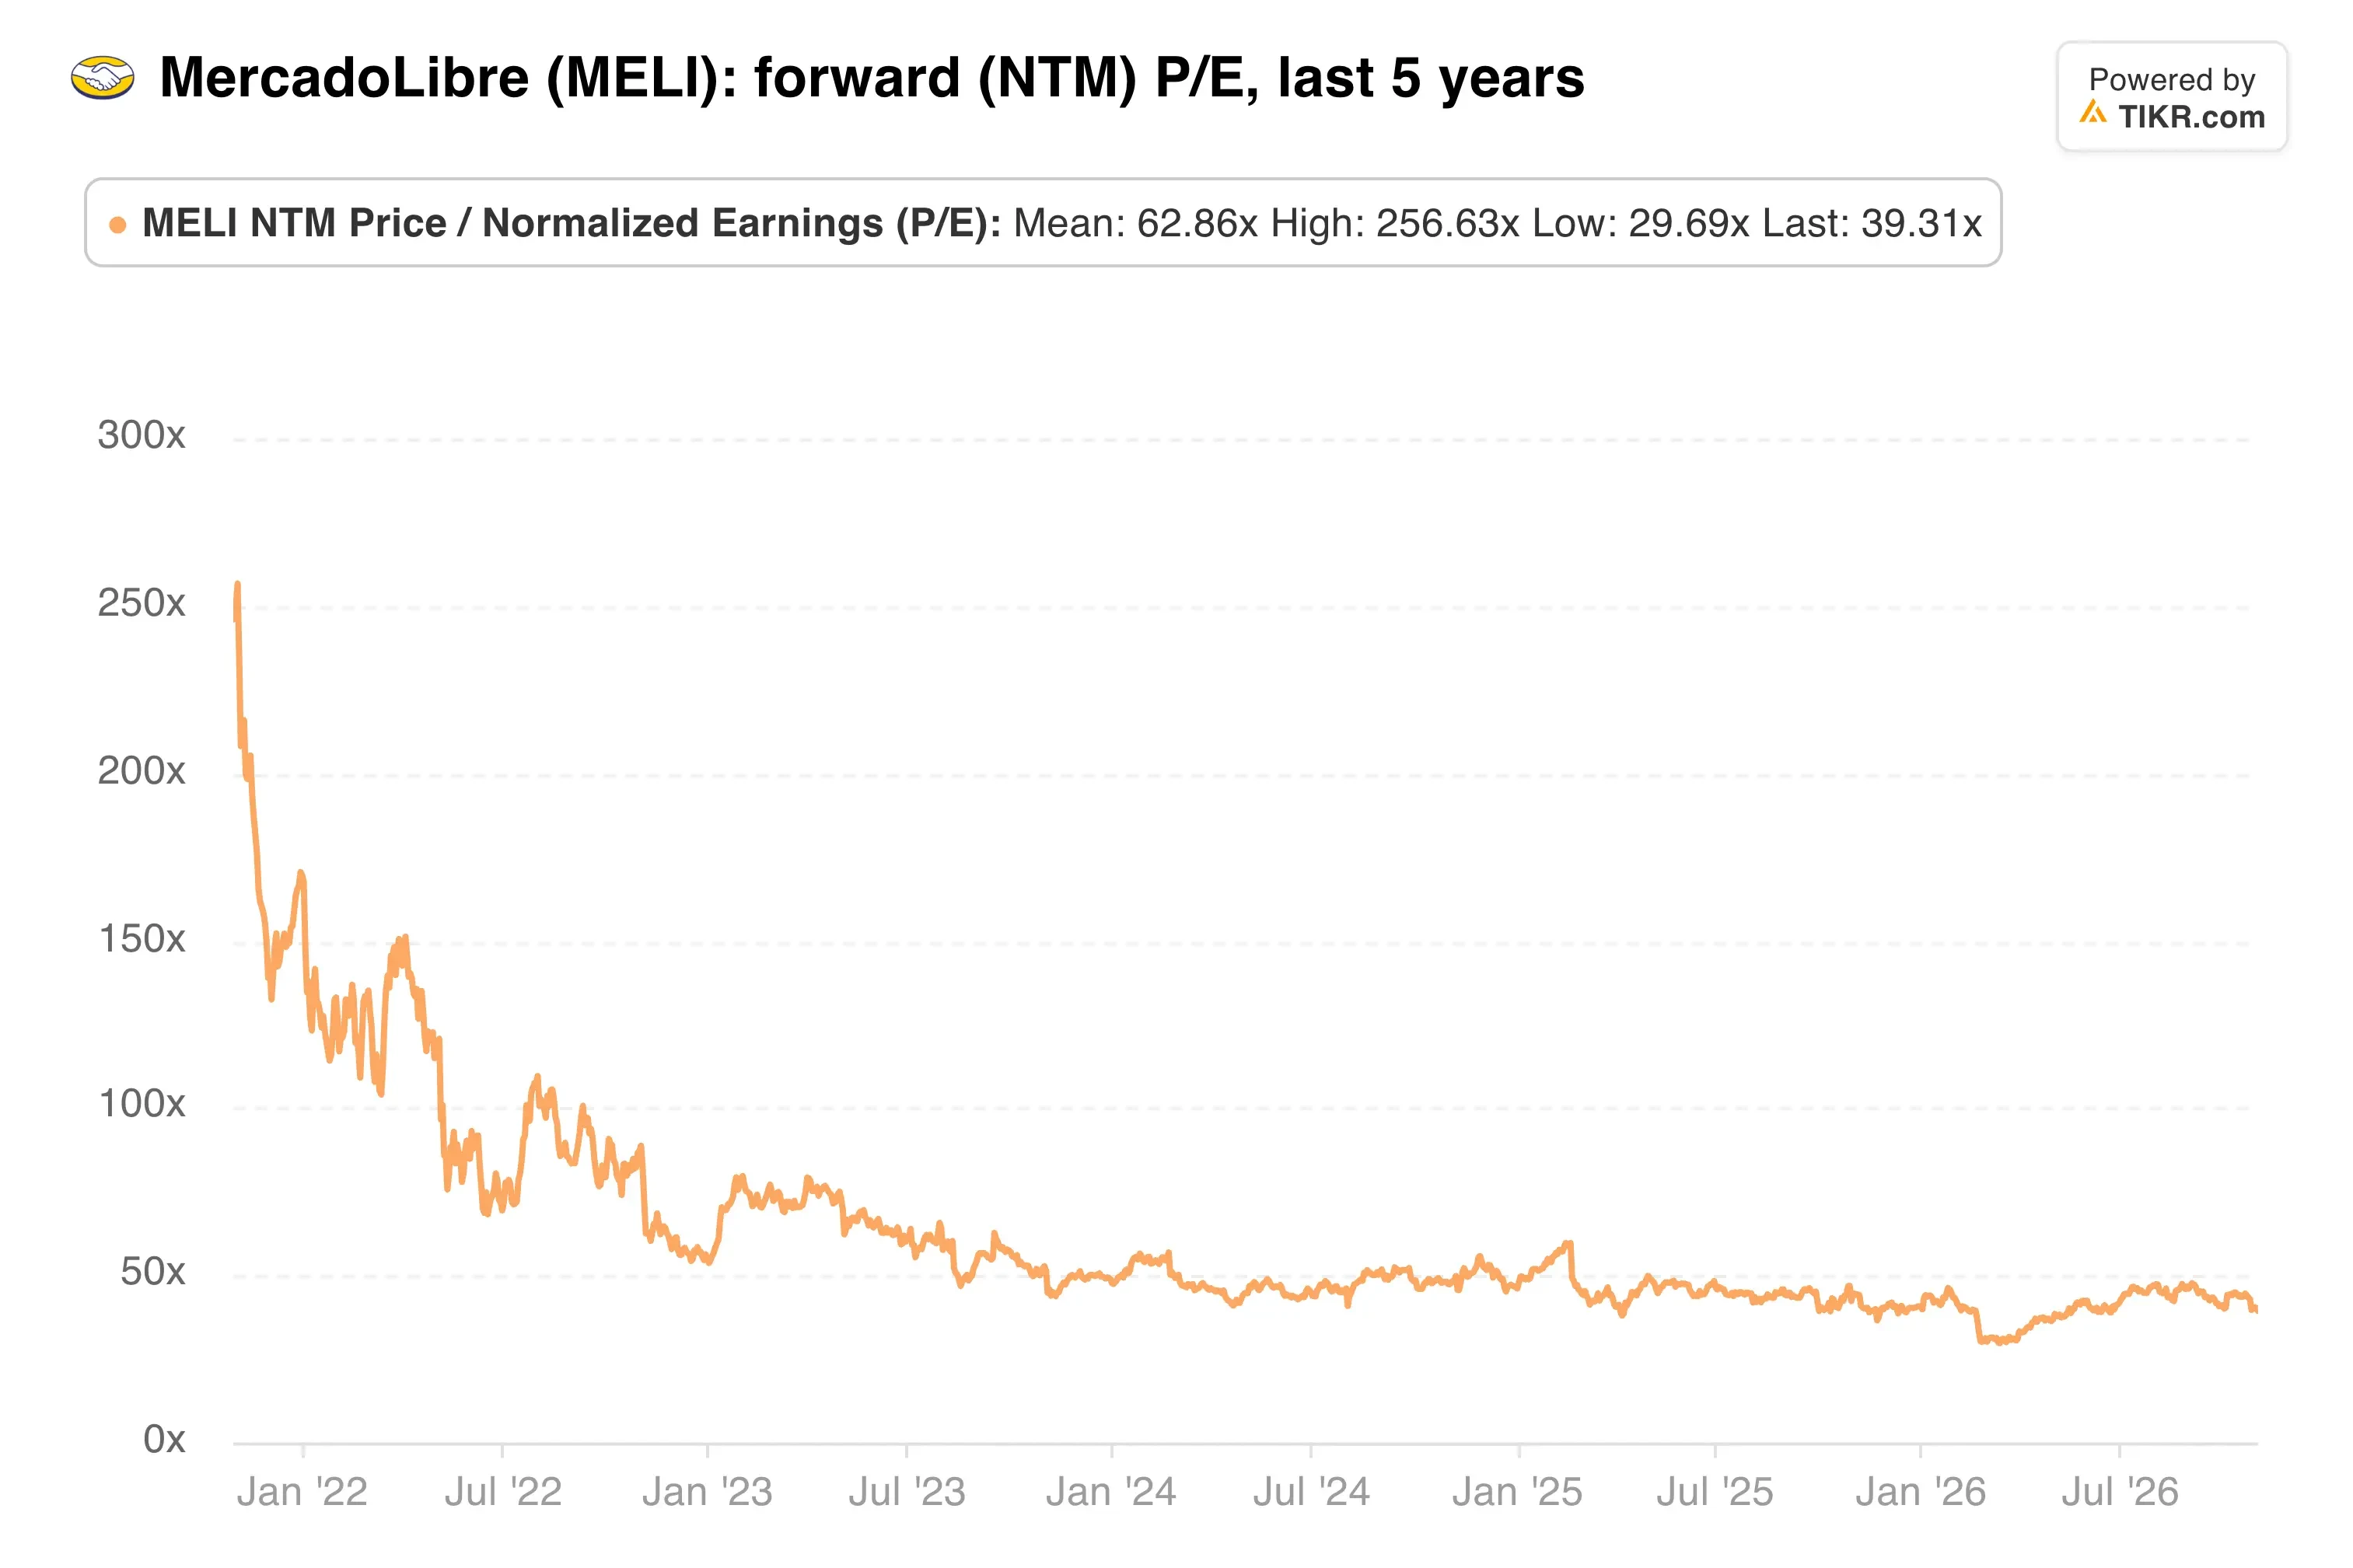
The Street’s $2,272 average target implies 40% upside. Citi upgraded the stock to Buy after the selloff, though it trimmed its target to $2,050, about 26% above Friday’s close.
The risks are concrete. A weaker real shrinks Brazil revenue in dollar terms. And if borrowers strain, a loan book that grew 75% in a year could turn from growth engine to drag.
My take: The multiple looks reasonable for a company still growing sales above 40%, and I think the selloff has run ahead of the fundamentals so far. But credit is the swing factor, and the election’s impact won’t show in the numbers until February. I’d want the November 4 call to sound as calm about Brazil credit as the last one did.
On Wednesday, watch three things: operating margin, the 15 to 90 day NPL ratio, and what management says about Brazil since October 25.
So what is MercadoLibre stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what MercadoLibre could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!