Key Takeaways
- Napco shares fell 17% today after equipment revenue dropped 7.3% as two locking distributors bought less.
- Recurring service revenue hit a record and is now over half of sales, so the drop looks overdone.
- Allegion’s strong lock sales suggest the problem sits with Napco’s two distributors, and Alarm.com reports later this week.
- Free cash flow fell 80% and needs to recover.
Napco Security Technologies (NSSC) sank 17% today after fiscal first-quarter revenue rose just 1.7% to $50.0 million, short of Wall Street’s estimates.
CEO Kevin Buchel blamed “two locking distributors.” But Allegion (ALLE), which sells commercial locks through similar distributors, just had a strong quarter, and Alarm.com (ALRM), which also sells hardware alongside its subscriptions, reports later this week.
What exactly happened
Napco reported before the open:
- Recurring service revenue rose 11.5% to a record $26.1 million, at gross margins above 90%
- Equipment revenue fell 7.3% to $23.9 million
Buchel added in the release that “sell-through at both distributors grew year-over-year and strengthened meaningfully on a sequential basis.”
I suspect they’re working down inventory, and with sell-through growing, they’ll have to restock.
Locks are selling just fine elsewhere
In the same three months, to Sept. 30, Allegion’s Americas non-residential business grew by low double digits organically, and it raised its full-year organic growth outlook to 5% to 6%. That’s no slowdown in commercial locks.
In the second quarter, Alarm.com’s SaaS and license revenue grew 11.1%, and its hardware and other revenue rose about 5%. If its hardware holds up again, that’s one more sign Napco’s problem sits on two customers’ shelves.
TIKR tracks 6 analysts on Napco Security Technologies. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Napco Security Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Napco Security Technologies’ Analyst Ratings
Most of Napco is a subscription business now
Recurring service revenue made up 52% of sales, and Napco puts its run rate at about $106 million. Analysts expected $1.64 a share this fiscal year, barely above last year’s $1.60:
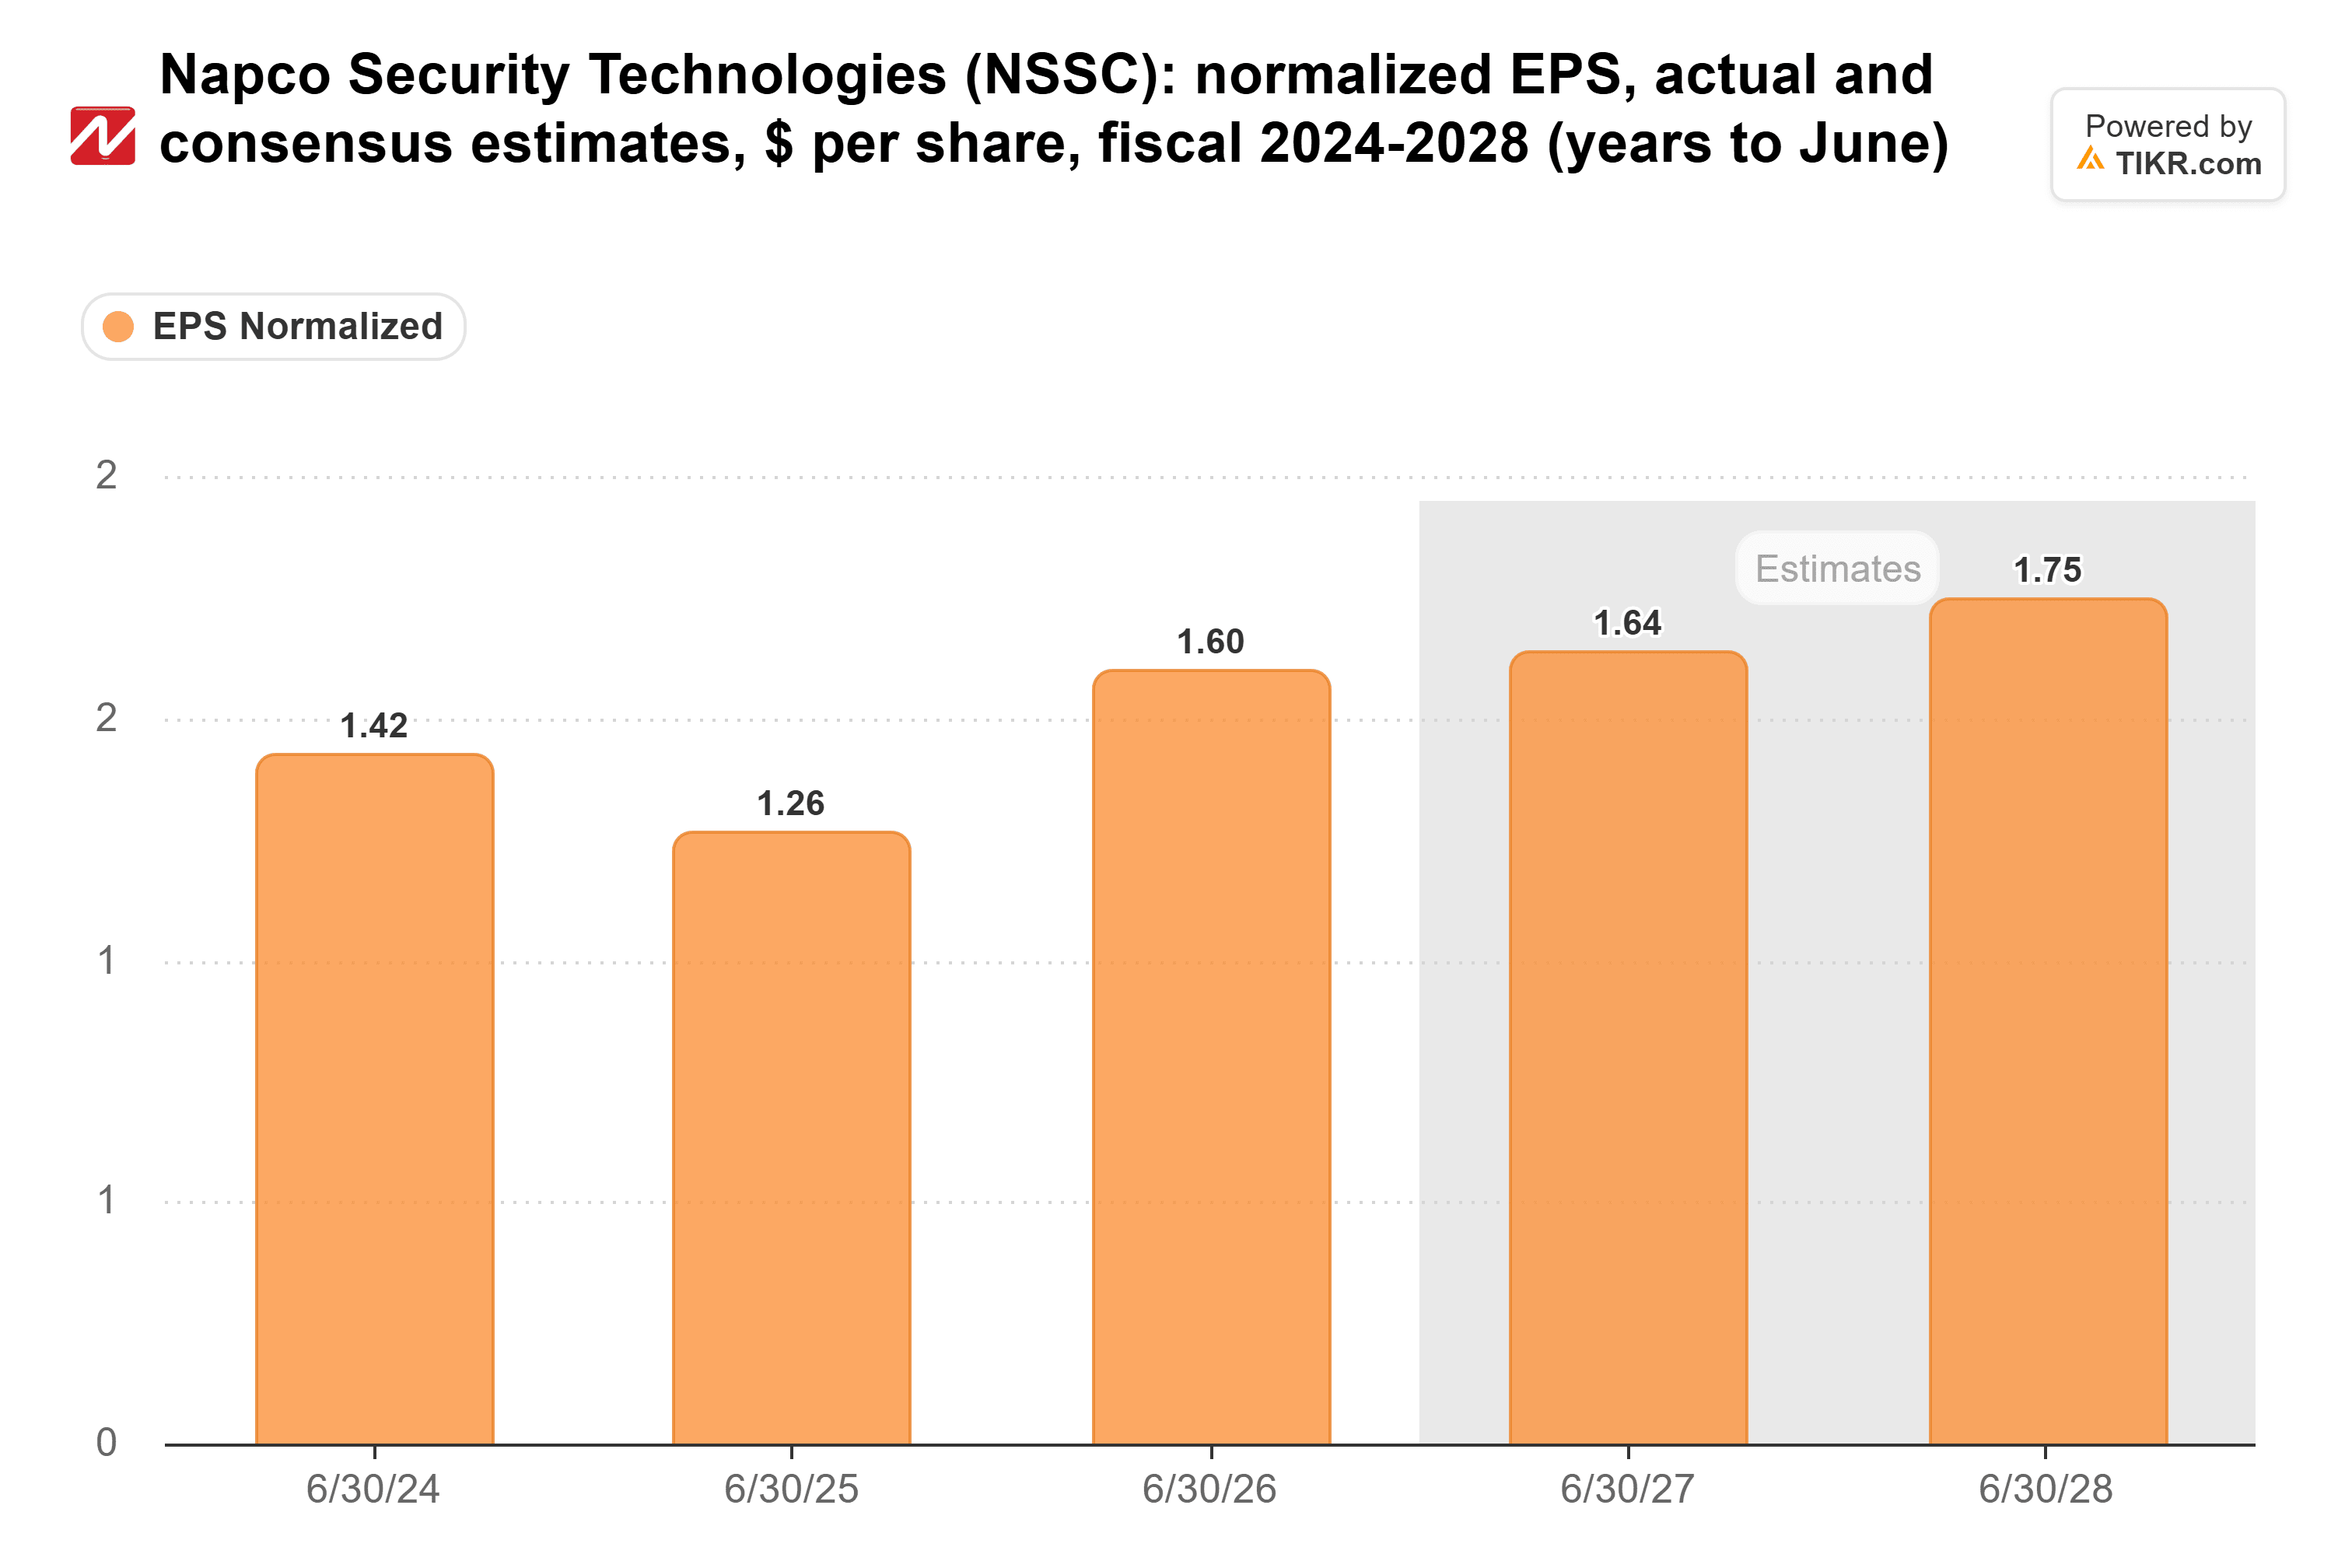
I don’t expect much of a cut to that $1.64 after this quarter.
At the last close, Napco’s forward P/E was already well below its five-year average of 31x:
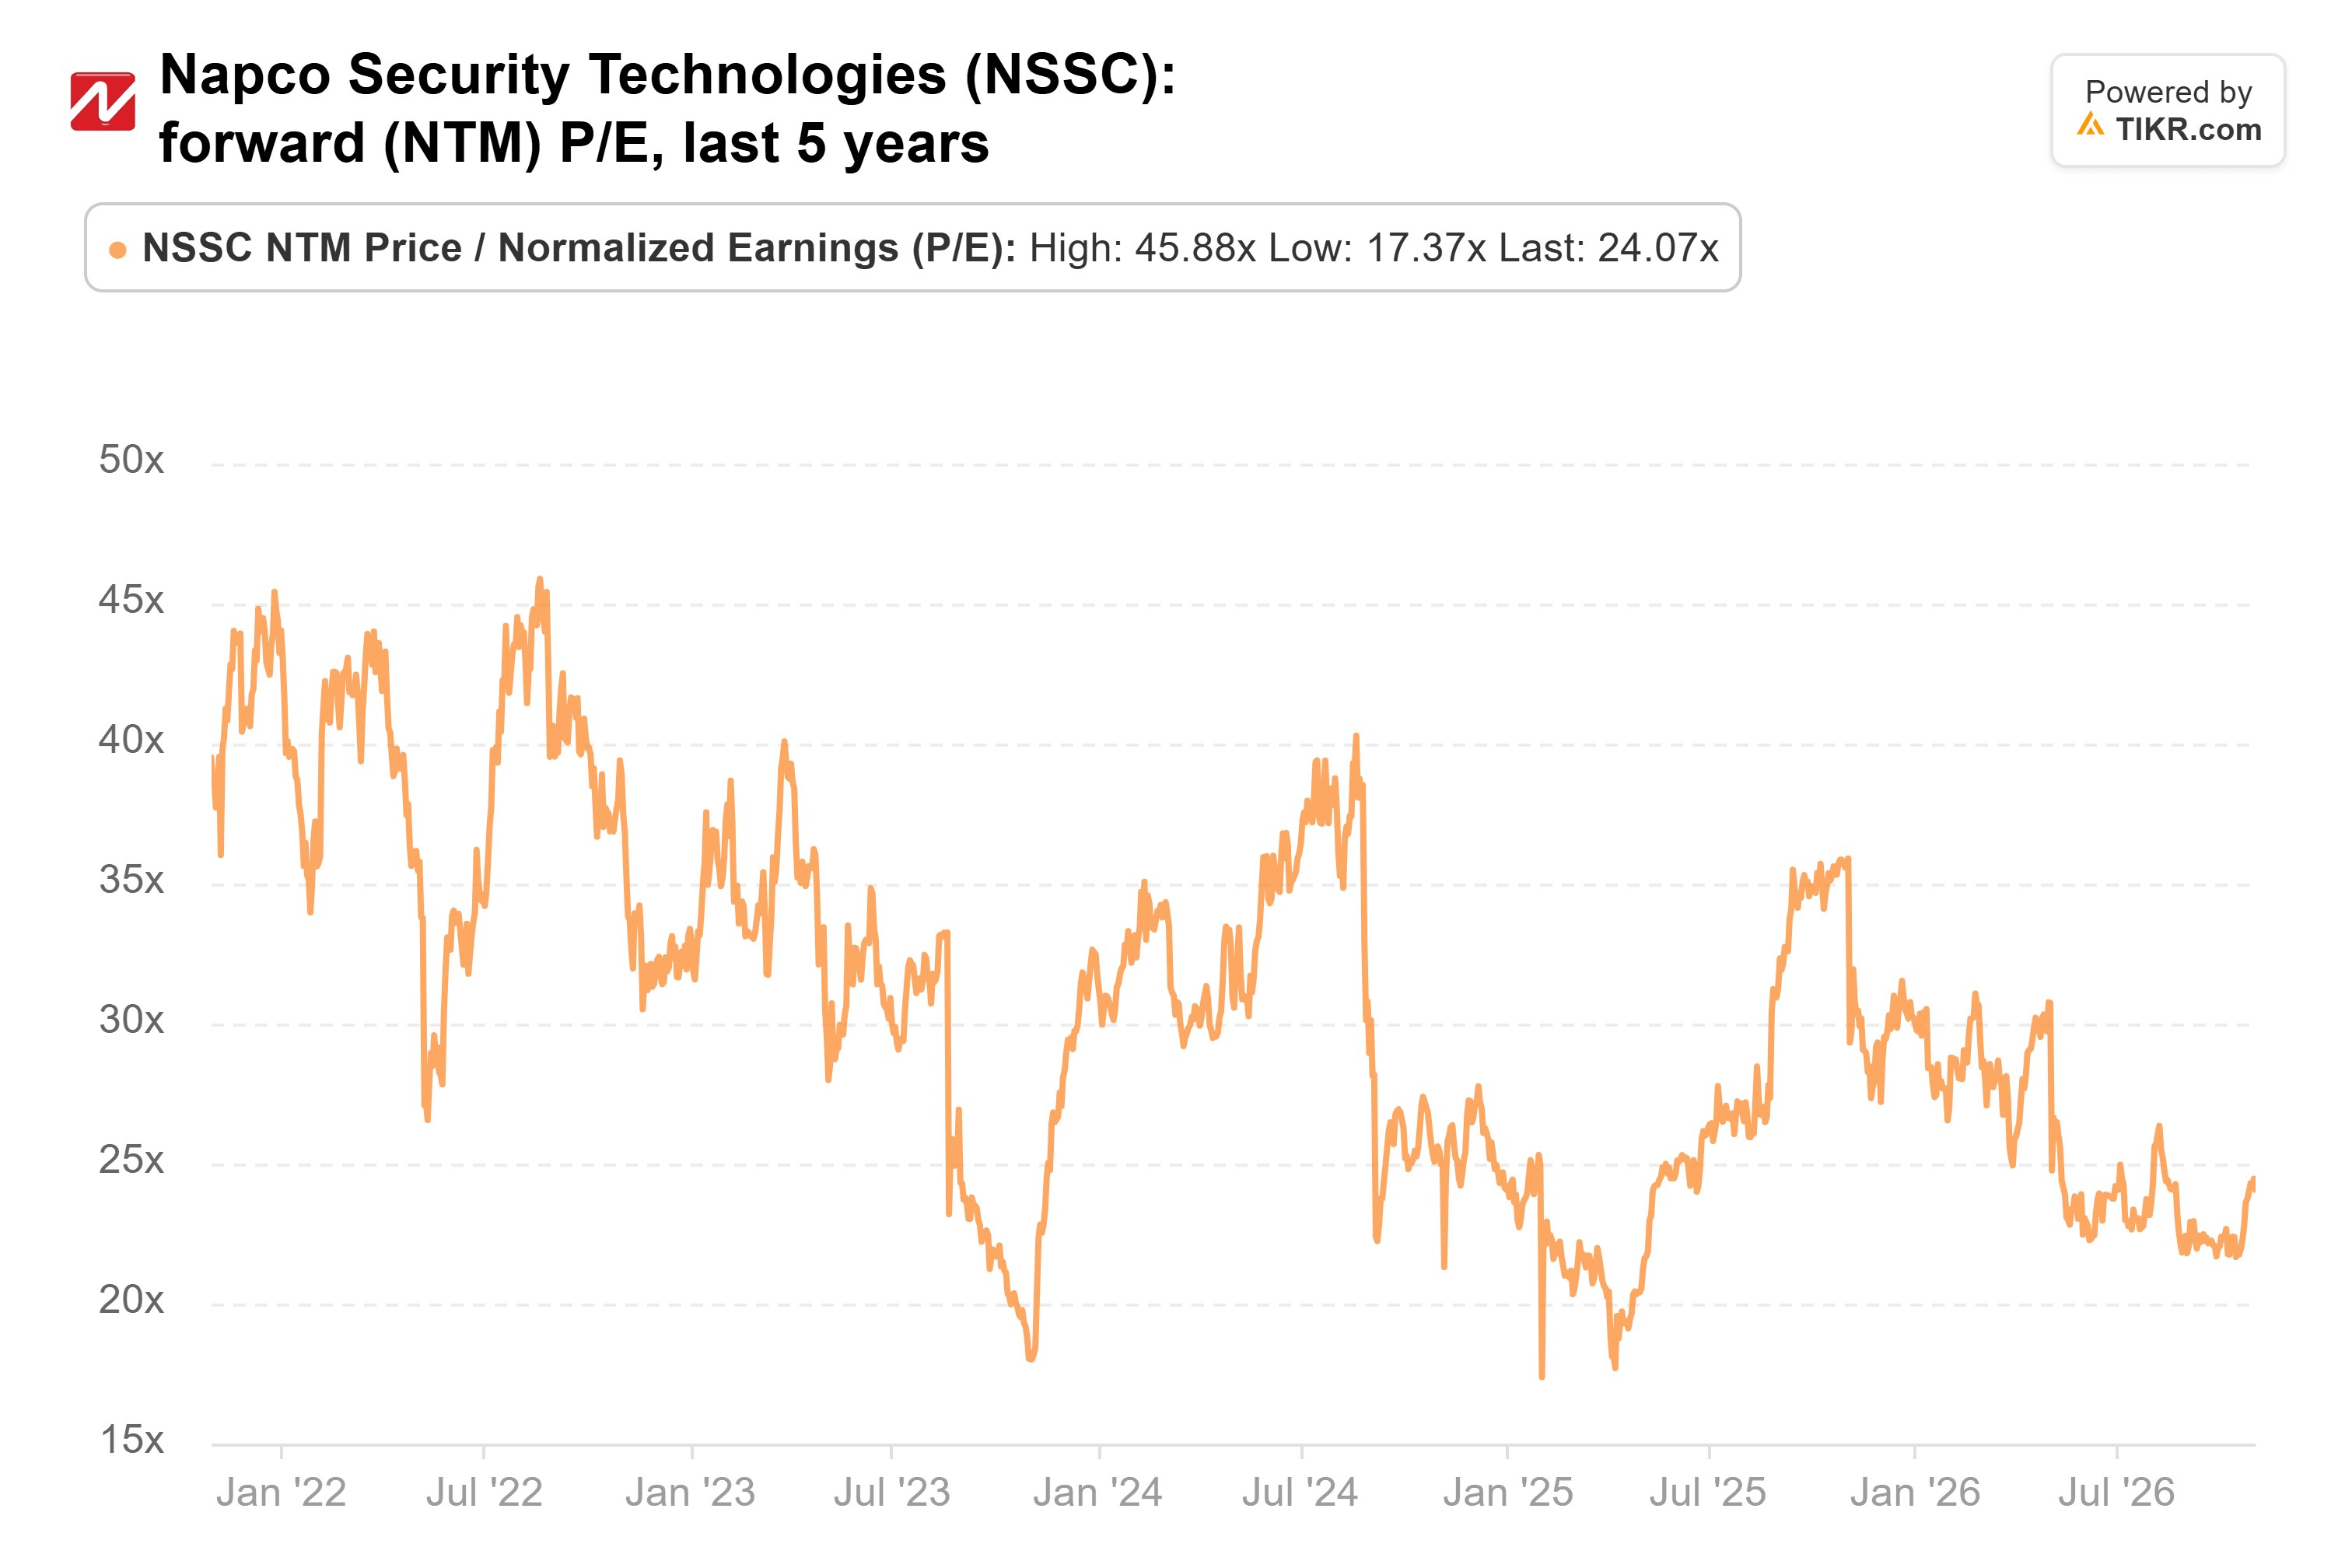
At today’s price, it’s about 20x, not far above its five-year low of 17x.
Cash is the catch
For two years, free cash flow ran between $11 million and $17 million a quarter:
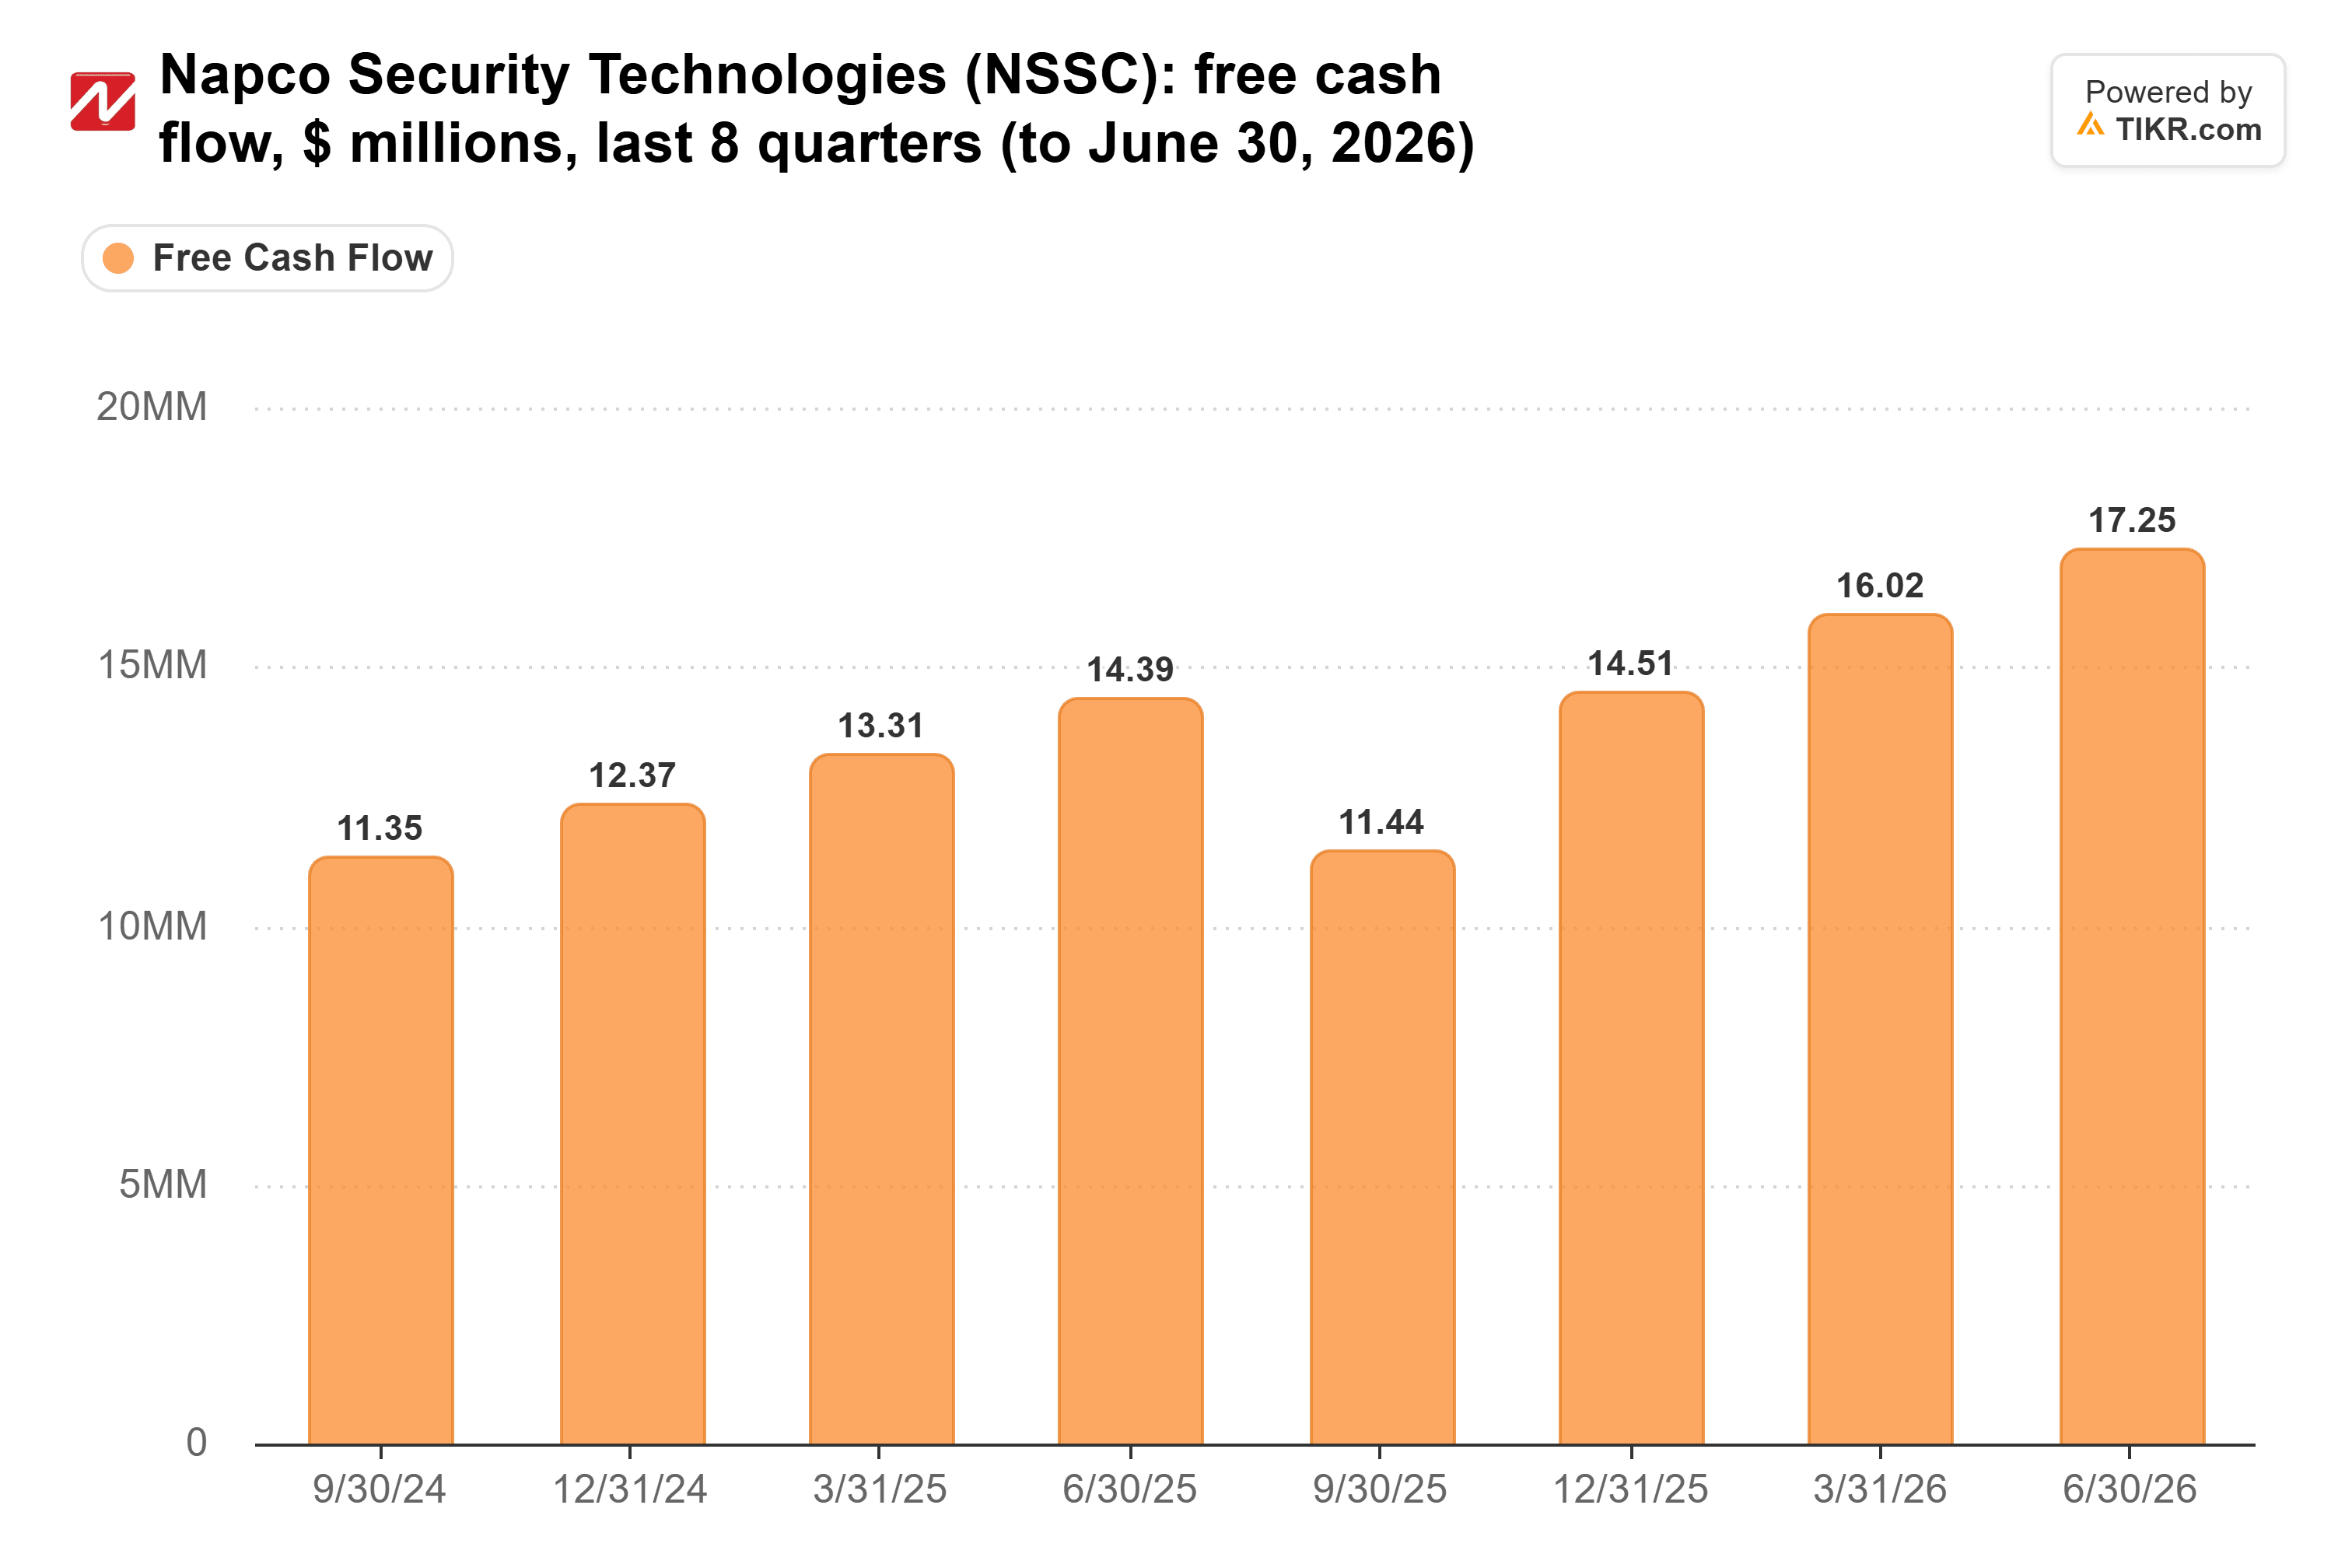
In the quarter just reported, it fell to $2.3 million.
The selloff looks overdone
The market is treating two distributors’ cutbacks like a demand problem. At about 20x earnings, I think that’s an opportunity.
Of course, equipment revenue needs to recover next quarter, and cash flow has to come back with it.
So what is Napco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Napco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!